Archive for Dairy Markets – Page 13

Cheese Exports Skyrocket: U.S. Dairy Industry Embraces Global Demand Despite Challenges

Why are U.S. cheese exports booming amidst global challenges? How is the dairy industry adapting to meet rising international demand? Learn more. 

Summary:

The U.S. cheese export market is sizzling, continuing its upward trajectory even as other dairy sectors face challenges. October 2024 figures reveal a 12.4% increase in cheese exports compared to last year, with Mexico’s unquenchable demand as the top consumer of American cheese, making it a pivotal export destination. This growth has kept cumulative numbers 1.6% ahead of 2023 figures, contrasting with declines in dairy categories like milk powder and whey, which have faced constraints from decreased demand in key Asian markets. The industry showcases strategic agility, offsetting challenges by focusing on high-demand categories like cheese. Mexico’s escalating importation and the robust appetite for U.S. cheese globally affirm a positive outlook for future growth, underpinned by cultural preferences and strengthened trade agreements.

Key Takeaways:

  • Despite a 1.9% decline in overall dairy exports from the United States in October, cheese exports showed robust growth with a significant 12.4% year-over-year increase.
  • Mexico plays a crucial role in the U.S. cheese export market, accounting for over 40% of exports and showing a remarkable 27.2% increase despite economic challenges.
  • Milk powder exports witnessed a downturn, primarily due to reduced shipments to Southeast Asia, although exports to Mexico increased to help offset domestic production challenges.
  • While whey exports declined, butter exports experienced a notable rise of 21.8% compared to the previous year.
  • Future risks for dairy export growth include potential climate changes and geopolitical tensions that could impact trade dynamics.
U.S. cheese exports, Mexico cheese demand, dairy export growth, U.S. dairy industry, cheese export strategies, international dairy markets, trade agreements Mexico, milk powder decline, whey market challenges, dairy market diversification

In a global market where economic turbulence often wreaks havoc on trade sectors, the United States seemingly spins its fortune on the wheel of cheese exports. Despite a waning global economy, U.S. cheese exports have defied expectations to rise to impressive levels. Notably, October experienced a 12.4% increase from the same month the previous year. This success poses an intriguing question: What strategies enable the U.S. dairy industry to flourish amid fierce international competition? The answer lies in the U.S. cheese industry’s strategic market positioning, with Mexico’s seemingly unquenchable demand accounting for over 40% of U.S. cheese exports.

MonthCheese Exports (Million Pounds)Year-Over-Year Change (%)
January72.4+4.8%
February75.0+6.5%
March78.9+8.2%
April82.3+10.1%
May85.6+11.9%
June86.0+12.3%
July87.5+13.0%
August89.1+13.5%
September88.4+12.9%
October88.8+12.4%

Cheese Powerhouse: U.S. Exports Surge as Other Dairy Sectors Stumble

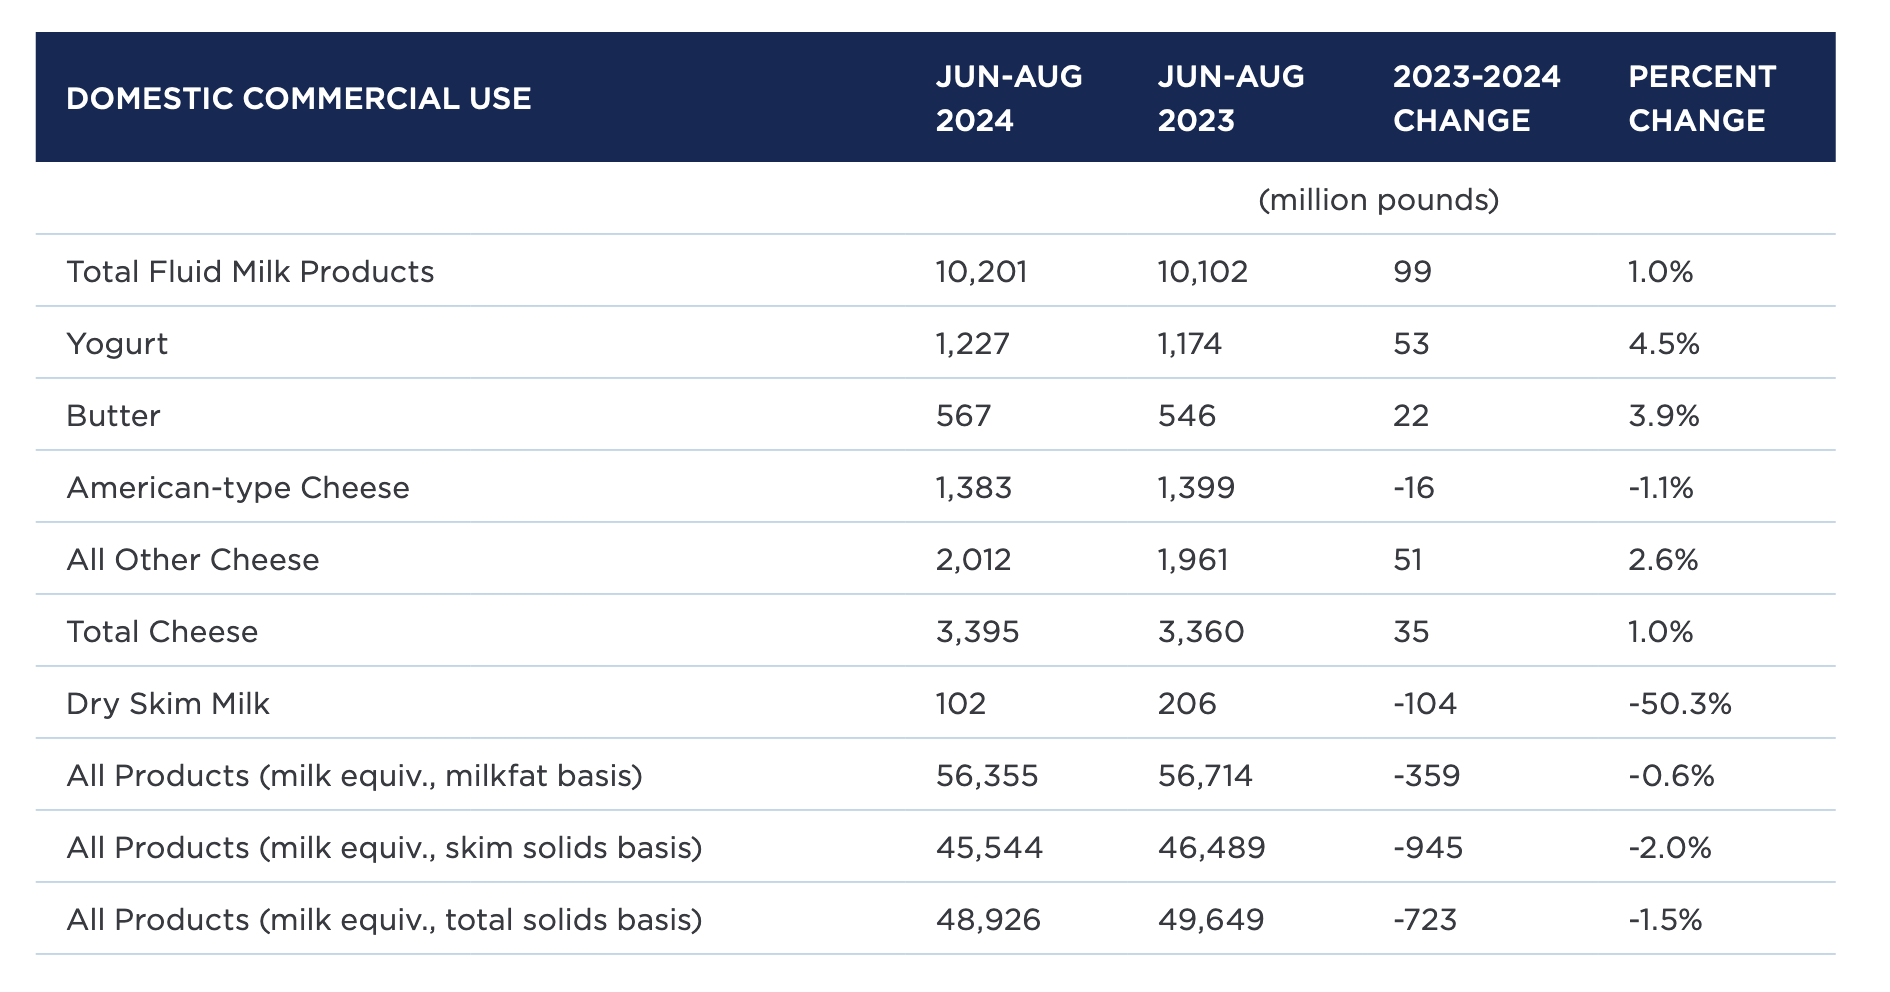
The latest data on U.S. dairy exports presents a compelling narrative of resilience and growth, particularly in the cheese sector, which has continually outpaced previous benchmarks. October 2024’s cheese export figures, reaching 88.8 million pounds, underscore a robust upswing of 12.4% compared to last year. This surge indicates a broader trend throughout 2024 despite the overall dip in October’s total dairy exports. This resilience and growth in the U.S. dairy industry should instill optimism about its future. 

Contextually, the year has set new precedents for dairy exports, with cumulative numbers standing 1.6% ahead of the 2023 figures. The early months of 2024 painted a particularly rosy picture with significantly higher performance metrics, partly driven by the global market’s insatiable demand for U.S. cheese. This trend is amplified by Mexico’s escalating importation, marking it a pivotal export destination. Together with robust demand from other international markets, this propels the cheese export sector to new heights. 

In contrast to the buoyant cheese sector, other segments like milk powder and whey have faced constraints and declines. However, the dairy industry’s ability to offset these challenges through a strategic focus on high-demand export categories such as cheese and solid supply chain logistics affirms a positive outlook for U.S. dairy exports as the year closes and offers a platform for compelling future growth. This potential for future growth should inspire hope and confidence in the U.S. dairy industry.

A Cheesy Affair: Mexico’s Role in the U.S. Export Explosion

When we examine the cheese export phenomenon, we see that the U.S. cheese industry is experiencing an unprecedented surge, with Mexico emerging as a pivotal player in this expansion. The growth in cheese shipments to Mexico isn’t just a fluke; it’s a testament to a combination of favorable factors that have fueled this demand. 

First and foremost, cultural preferences play a significant role. Mexicans have a long-standing affinity for cheese, weaving it into the fabric of their culinary landscape. Cheese’s versatility makes it a staple in Mexican cuisine, from traditional delicacies like quesadillas to modern twists. This inherent cultural demand forms a solid foundation for U.S. cheese exports. 

However, cultural preferences are just one piece of the puzzle. Strengthening trade agreements between the U.S. and Mexico have further greased the wheels. These agreements have facilitated more straightforward access to the market and encouraged trade through reduced tariffs and favorable exchange rates despite the recent dip in economic activity. The U.S.-Mexico-Canada Agreement (USMCA) exemplifies a framework supporting sustained export growth. 

Another critical factor is the high-quality reputation that U.S. cheese enjoys. As Mexican consumers develop a taste for diverse cheese varieties, American cheese stands out due to its quality and range. Prominent brands have established a firm foothold across the border, contributing to the steady increase in demand. 

With over 40% of U.S. cheese exports going to Mexico, it’s clear that this attractive market shows little sign of waning. This demand paints a promising picture for U.S. cheese producers. However, they must understand and adapt to evolving Mexican preferences to maintain robust trade relationships. As we ponder this growth, the question remains: How can the U.S. further capitalize on this lucrative market? As industry professionals, it’s time to brainstorm and unlock the answers.

Dairy Dichotomy: Navigating the Rise and Fall of U.S. Trade 

The challenges faced in other dairy categories, particularly milk powder and whey exports, starkly contrast with the triumphant rise of cheese exports. Milk powder exports experienced a decline of 4.3% year over year, hitting their lowest October volume since 2018. This downturn is primarily due to limited supplies, as nonfat dry and skim milk powder production has dramatically slowed this year. Moreover, the Southeast Asian market, once a robust consumer, has considerably reduced its demand. Exports to the Philippines, Indonesia, and Vietnam have plummeted by 33.3%, 41.9%, and 48.2%, respectively. 

Similarly, whey exports have declined by 11.7% compared to last year. This decline is primarily attributed to shipments of whey protein concentrate, which fell by 13.7%. Although dry whey exports declined by a less dramatic 1.6%, the tight supply chain is anticipated to constrain future exports further. 

In stark contrast, cheese exports have soared, prominently driven by Mexico’s insatiable demand, showcasing the U.S. cheese sector’s robust performance. This divergence highlights the resilient demand and strategic market positioning that have enabled cheese to outpace other dairy categories struggling with supply and demand challenges. As experts, it’s crucial to question what adaptive strategies could be implemented to revitalize these waning segments of the dairy market.

Strategic Agility: How U.S. Dairy Masters Global Market Winds

As U.S. dairy producers and exporters navigate the ebb and flow of global market conditions, adaptation has become the industry’s mantra. To successfully navigate the global dairy trade, these stakeholders employ strategies to ensure sustained growth and competitiveness in an increasingly challenging landscape. 

One of the foremost strategies is market diversification. By expanding beyond traditional trading partners, U.S. dairy producers mitigate risks posed by fluctuating demand or economic instability in any single market. “Diversifying our export destinations has allowed us to distribute risk and stabilize revenue streams,” explains a senior U.S. Dairy Export Council executive. This shift is apparent in heightened cheese exports to dynamic markets such as Southeast Asia and the Middle East and in exploring untapped opportunities in regions like Africa. 

Quality also plays a critical role in maintaining a competitive edge. U.S. producers have invested heavily in improving product quality to meet the stringent standards of international customers. “Quality isn’t just a selling point; it’s a necessity,” says Dr. Michael Hennessey, an industry analyst and consultant. “Our ability to deliver premium products tailored to specific market requirements has been pivotal in expanding our global footprint.” This quality focus spans everything from enhanced production techniques to rigorous food safety protocols. 

Furthermore, leveraging trade relationships has been instrumental in opening doors and fostering growth. The U.S. dairy industry has capitalized on trade agreements and partnerships that facilitate market access by building and sustaining positive trade relations with foreign counterparts. Experiences shared by industry veterans at international expos underline the importance of these relationships: “Our strategic alliances have been crucial in navigating trade barriers and enhancing competitive positioning,” remarks Linda McGregor, a trade liaison officer with extensive experience in international dairy markets. 

Through these multifaceted strategies, U.S. dairy producers and exporters are not just adapting to global market fluctuations—they are proactively shaping the industry’s future. As the world continues to change, their commitment to innovation and excellence remains a constant driving force behind the sector’s success. 

The Bottom Line

Despite a slight decrease in U.S. dairy exports, cheese continues to shine as a dominant export, with significant growth driven by demand from Mexico. Other dairy products like milk powder and whey have faced setbacks, highlighting a complex landscape where strategic adaptation is crucial. This raises a vital question: As the global economic terrain shifts, how will U.S. dairy exports leverage this momentum in cheese to counterbalance the fluctuations seen in other sectors? Maintaining resilience will require innovation, market diversification, and an acute focus on consumer demands. Are we ready for the challenge ahead?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Unraveling Dairy Market Trends: Profit Insights for Dairy Farmers on December 5, 2024

Explore December 2024 dairy trends. Learn how farmers can profit amid export and production changes. Discover strategies now.

Summary:

The dairy industry is navigating a volatile phase, balancing opportunities and challenges. October metrics reveal a 1.6% decline in U.S. exports on a milk equivalent basis amidst increased cheese and butter production. While domestic cheese consumption rose by a modest 0.1%, export demand sustainability remains questioned. U.S. cheese production increased by 1.0%, with exports up 12.9%, and butter production surged by 3.1%, alongside record-high imports from New Zealand. NFDM/SMP exports to Southeast Asia underperformed, triggering downward price adjustments. These shifts demand rapid adaptation and strategic maneuvers to maintain profitability. The pressure from global and domestic markets is mounting, emphasizing the need for dairy farmers to stay informed. Cheese markets require strategic positioning, while the butter market undergoes significant transformations fueled by U.S. production and New Zealand imports. Meanwhile, the dry whey market sees a robust uptick, highlighting a complex economic landscape. The pricing environment attempts adaptation in a dynamic market where strategic adjustments are essential for survival.

Key Takeaways:

  • U.S. milk exports show weakness, with a decrease of 1.6% on a milk equivalent basis, hinting at potential challenges in international demand.
  • Overall cheese production in the U.S. increased by 1.0% in October, balancing with a matching rise in total sales, suggesting a stable cheese market.
  • Butter production has risen by 3.1%, with U.S. imports reaching record levels, especially notable with significant arrivals from New Zealand.
  • NDFM/SMP exports to Southeast Asia underperformed expectations, leading to adjustments in price forecasts.
  • CME dry whey prices have risen significantly, indicating intense demand pressures, in contrast to relatively stable European market prices.
  • New Zealand’s Global Dairy Trade (GDT) auction indicates varied demand across regions, influencing WMP and butter prices differently.
  • Adaptation and strategic decision-making are crucial for dairy professionals navigating ongoing market fluctuations and volatility.
dairy market trends, milk price fluctuations, cheese production growth, butter market changes, dairy export demands, NFDM SMP performance, dairy farmer strategies, U.S. butter imports, competitive edge in dairy, pricing environment adaptation

In the volatile arena of dairy markets, understanding the latest trends is not just beneficial—it’s essential for survival. Dairy farmers face many challenges today, from fluctuating milk prices to unexpected shifts in export demands. With global pressures mounting and domestic competition heating up, staying informed is more crucial than ever. “In these unpredictable times, knowledge isn’t just power; it’s profitability.” This article delves into the intricacies of the current dairy market, aiming to equip farmers with the insights and strategies necessary to navigate uncertainty. By exploring hurdles and opportunities in today’s dairy industry, we provide the tools to maximize profits and secure a stable future.

Dairy Dynamics: Navigating a Sea of Constant Change 

In recent months, the dairy market has displayed a mix of trends across various commodities, reflecting opportunities and challenges for industry stakeholders. Milk production has seen modest growth, accompanied by notable changes in cheese and butter production and fluctuations in powder markets, such as NFDM and SMP. 

U.S. cheese production expanded by 1.0% in October, signaling a balanced relationship between production and sales. This was due to a 0.9% increase in total sales derived from export surges of 12.9% and a marginal 0.1% rise in domestic consumption. This suggests that, contrary to concerns of market oversupply, cheese production levels align well with current market demand, providing a stable platform for dairy farmers. 

Butter production, on the other hand, surged 3.1% as compared to the same month in the preceding year, closely aligning with forecast figures. This was complemented by record-breaking U.S. butter imports, totaling an impressive 2,000 metric tons primarily sourced from New Zealand. Despite this influx, CME spot butter found support at around $2.50, hinting at a stable marketplace. 

Regarding powders, particularly the NFDM and SMP categories, October’s U.S. exports indicated unexpectedly weaker performance, prompting a downward revision of future price forecasts. The weaker performance was due to a complex interplay of global market conditions, including weaker-than-expected exports to Southeast Asia. Current demands appear soft, and the pricing environment is attempting to adapt accordingly. In contrast, the dry whey markets experienced a robust uptick, with CME prices rising above 70 cents, reflecting tight supply and persistent demand. 

The U.S. dairy market navigates various dynamics as global interactions and regional variances influence production and export outcomes. Cheese and butter hold steady, while powders present more challenging conditions. These conditions require vigilant market strategies to capitalize on emerging opportunities and mitigate potential risks.

Cheese Dynamics: Balancing Production and Global Demand

The cheese market presents a complex scenario for dairy farmers, characterized by a nuanced balance between production and exports. In October, U.S. cheese production saw a modest increase of 1.0%, aligning closely with the total sales growth of 0.9%. This suggests a relatively balanced market devoid of the surplus that could drive prices downward significantly. The driving force behind sustaining this equilibrium is the substantial boost in exports, up by 12.9%, effectively absorbing excess production and preventing market saturation. 

However, the international markets play a pivotal role in determining the trajectory of U.S. cheese prices. With cheese prices in both the U.S. and the EU experiencing a downward trend, there appears to be a spillover effect influencing New Zealand’s market dynamics. This convergence hints at a potential drag on global cheese prices, mainly due to competitive pressures from international producers seeking market share. 

This interconnected global market presents both challenges and opportunities for U.S. dairy farmers. While robust export growth provides a lucrative outlet and mitigates domestic oversupply concerns, the pressure from declining international prices necessitates strategic positioning. Dairy farmers must enhance their competitive edge through quality, efficiency, and adaptability to navigate such fluctuating economic currents. Understanding the impact of global economic pressures on the dairy market is crucial for making informed decisions. 

As we look forward, the cheese market’s balance hinges on sustained export strength. Observing the global economic landscape and international trade policies will be crucial in anticipating future trends and preparing accordingly. Optimizing production processes and exploring new markets could allow U.S. dairy farmers to remain resilient in this evolving cheese market paradigm.

Butter Balancer: Navigating Supply Swells and Steady Demand

The butter market, a critical aspect of the dairy sector, is experiencing noteworthy dynamics. Production increases in the U.S., up 3.1% compared to last year, have significantly shaped current market conditions. Additionally, record-large imports of 2,000 metric tons from New Zealand in October further impacted the supply side. These twin factors have contributed to the observable price point of around $2.50 on the CME spot market. 

Several factors explain this price support. Firstly, while domestic and imported supplies have swelled, demand has demonstrated resilience, potentially absorbing the increased availability—though price elasticity will inevitably test the limits of this demand. This suggests a marketplace where buyers are willing, perhaps even eager, to capitalize on relatively stable pricing before anticipated volatility in the coming quarters, offering a potential for profitability. 

Understanding these trends requires acknowledging the robust nature of current consumer demand and the potential cooling effects of any future economic slowdowns worldwide. As butter finds support at $2.50, stakeholders might anticipate a gradual adjustment as market forces recalibrate. This could lead to price fluctuations influenced by global economic pressures and domestic storage capabilities. Discussing the potential impact of future economic slowdowns on the dairy market can help farmers prepare for potential challenges.

Powder Market Performance: Navigating Soft Demand and Strategic Opportunities

The powder market, encompassing NFDM (non-fat dry milk) and SMP (skim milk powder), is experiencing a steady to slightly lower pricing trend. The demand side remains soft, driven by a complex interplay of global market conditions. Factors include weaker-than-expected exports to Southeast Asia, contributing to this pricing environment. The U.S. market has not seen a surge in demand sufficient to offset these weaknesses, leading to adjustments in forecasts and highlighting vulnerabilities in export markets [source: current market analysis]. 

In contrast, the CME dry whey market has witnessed a noteworthy surge beyond 70 cents. This price increase is partly due to tight fundamentals where stocks of whey, WPC (whey protein concentrate), and WPI (whey protein isolate) remain minimal. The robust pricing reflects an ongoing effort to ration demand, which continues to show strength heading into the first quarter. However, such tight market conditions may only be sustained for a while, and the pricing will likely adjust as market dynamics evolve. 

For dairy farmers, these market conditions present a dual challenge. On the one hand, the stable to declining prices of NFDM/SMP pressure profit margins, while on the other, the higher whey prices offer a glimmer of profitability but require strategic positioning to capitalize on. Balancing these dynamics demands astute market awareness and nimble operations management. The ability to anticipate and respond to shifts in demand and pricing will be crucial for maintaining profitability amidst these turbulent market conditions [source: dairy industry reports].

Strategic Maneuvering: Thriving Amid Market Fluctuations

Amidst fluctuating market conditions, astute dairy farmers can leverage specific strategies to adapt and thrive. One actionable insight is to diversify the product portfolio. With cheese and butter showing varied trends, consider focusing on products with stable demand, such as domestic butter, which has significantly increased consumption. 

Staying informed is not just beneficial; it’s vital. Regularly updating oneself with the latest market reports, governmental policy changes, and technological advancements ensures preparedness against sudden shifts. Engaging with agricultural economists and market analysts can provide insights into upcoming trends and potential challenges. 

Moreover, it’s essential to recognize the significant role of international markets. The recent variations in exports, particularly to Southeast Asia, underscore farmers’ need to monitor global demand fluctuations closely. Understanding these export trends can help identify new opportunities for expanding and diversifying market strategies. 

Finally, maintaining a flexible operational structure can allow quick adjustments in operations based on the marketplace indicators. Whether modifying production volumes in response to demand or exploring alternative markets when traditional ones wane, adaptability remains a key success factor in navigating the complexities of dairy farming today.

The Bottom Line

The dairy industry continues to experience dynamic shifts, with fluctuations in production and market demands requiring vigilant observation. Cheese, butter, and powder markets display varied trends, each influenced by production outputs, export demands, and regional buying behaviors, especially with the notable activity in markets like New Zealand and the United States. Amidst these changes, dairy farmers must remain alert to market signals and proactively adjust their strategies to maintain profitability. By understanding these market dynamics and anticipating future shifts, their decision-making can pivot from reactive to strategic. 

As dairy farmers navigate the complexities of supply and demand, the path to sustained success lies in leveraging up-to-date market insights and fostering agile business models. In a world where dairy sectors are unpredictable, the question remains: are you equipped to adapt quickly and strategically to these ever-changing tides?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

CME Market Insights: Cheese and Butter Prices Rally as U.S. Production Climbs

Discover key trends as CME cheese and butter prices rise. Understand how U.S. production growth could affect your dairy strategies.

Summary:

The latest CME market report showcases a rally in Class III and cheese prices, driven by renewed buyer aggression and U.S. production gains, with the USDA’s October report detailing a 1% increase in cheese output and a 3.1% rise in butter production year-over-year. Market complexities like technical resistance levels and fluctuating whey prices prompt producers to reassess strategies, especially as U.S. cheese prices lag behind those in New Zealand and the EU. Dairy markets show bullish momentum, with block cheese at $1.70 per pound and butter prices increasing, paving the way for potential profit expansions. However, strategic hedging is necessary to balance pricing strategies and profit margins amid rising cheese prices, strong market dynamics, and holiday season-driven demand for butter now priced at $2.54.

Key Takeaways:

  • Class III cheese and block cheese markets experience steady gains, indicating bullish sentiment despite seasonal demand fluctuations.
  • The U.S. continues to produce more cheese and butter than previous years, driving domestic market prices up while still remaining competitive globally.
  • Butter futures have risen significantly, with current market conditions suggesting a sustained demand around the $2.50 per pound mark.
  • The USDA’s October Dairy Products report highlights an increase in overall cheese and butter output compared to last year, despite some sector-specific declines.
  • Whey prices impact Class III contracts significantly, necessitating careful monitoring by producers, especially as the first quarter of 2025 approaches.
  • The NFDM market faces challenges as global demand appears to stabilize, emphasizing the need for strategic positioning in the current pricing environment.
  • U.S. dairy pricing remains more favorable compared to New Zealand and EU counterparts, providing competitive leverage in international markets.
dairy markets, cheese prices, butter prices, dairy farmers, market dynamics, pricing strategies, supply chain decisions, USDA Dairy Products report, export opportunities, global pricing trends

Dairy markets are currently experiencing a bullish momentum, with cheese and butter prices on the rise. This unexpected pre-holiday market rally has certainly stirred things up. Block cheese has advanced to $1.70 per pound, and butter prices have also seen a significant increase. This rally presents both risks and opportunities, affecting pricing strategies, profit margins, supply chain decisions, and market forecasts. As these forces behind the numbers capture industry attention, it’s crucial to start strategizing for 2025, ensuring preparedness and proactivity in the face of these market dynamics.

ProductCurrent Price (per pound)Weekly ChangeComparison Index
Block Cheese$1.70+3 cents+7 cents week-to-date
Barrel Cheese$1.6675+1.75 cents+7 cents week-to-date
Spot Butter$2.5400+1.75 cents+5.5 cents from last week’s low
NDM$1.3700-0.50 centSideways price action

Riding the Wave: CME Cheese and Butter Prices Climb Amid U.S. Production Surge 

The recent pricing trends at CME exhibit a clear upward trajectory in cheese and butter, driven primarily by U.S. production dynamics and international market comparisons. Cheese markets are showing a continuous rally, with block cheese advancing to $1.70 per pound and barrel cheese climbing to $1.6675 per pound. Notably, both categories reflect a 7-cent increase this week, contributing to bullish sentiments in futures markets. This movement is juxtaposed against U.S. cheese prices, which are significantly lower than New Zealand and EU figures, priced at $2.13 and $2.28 per pound, respectively. 

Butter pricing follows a similar ascent, now reaching $2.54 per pound, influenced by a robust production backdrop. The USDA’s recent dairy report indicates a 3.1% annual increase in butter output, revealing a comparative advantage over European and New Zealand markets, where butter prices are notably higher. These variances highlight the U.S.’s relative positioning in global markets, as the domestic increase in production aligns strategically with international price disparities, offering competitive advantages that bolster market resilience.

The Cheese Surge: Navigating Gains and Strategic Opportunities 

The cheese market is currently undergoing significant shifts, particularly within the block and barrel cheese categories. Block cheese has climbed to $1.70 per pound, witnessing a 3-cent rise through multiple trades, while barrel cheese saw a 1.75-cent increase, settling at $1.6675. These seemingly modest increments have amplified the momentum in the futures market, particularly impacting Class III futures. Over recent sessions, January Class III futures have surged by $1.00/cwt, reflecting investor optimism fueled by these incremental gains. This surge in the cheese market presents a promising outlook, potentially leading to better returns for dairy producers. 

These market shifts bear significant implications for dairy producers. The rising price of cheese indicates stronger market dynamics and potentially better returns. However, these gains bring with them the need for strategic hedging as there’s a delicate balance to maintain. For producers under-covered for the first quarter of 2025, the current rise offers an opportunity to secure favorable pricing floors. It’s crucial, however, to remain vigilant about whey prices, as any decline in whey, which plays a critical role in Class III pricing, could erode these advantages. Each penny drop in whey could translate to a 6-cent impact on Class III prices, underscoring the importance of monitoring these interconnected market components. While the present trajectory offers positive signals, producers must navigate these waters with a keen eye on volatility and fundamentals.

Butter Bounces Back: Market Dynamics and Growth Deceleration 

The recent upswing in butter market prices reflects a nuanced amalgam of supply and demand dynamics. With spot butter rising 1.75 cents to close at $2.54, it is noteworthy that the butter futures have also shown appreciable gains, advancing 0.50 to 2.00 cents across contracts through July 2025. This upward movement suggests a robust reaction following some expected technical oversold conditions seen before Thanksgiving. 

The driving force behind this price increase is the persistent demand during the holiday season, combined with a steady supply of cream, facilitating ample butter production. What’s compelling is the notable deceleration in butter output growth, shifting from a staggering 15.1% increase in August to a more moderate rise of 3.1% compared to last year. Despite this slowdown, the current production levels are sufficient to meet prevailing demand while maintaining price stability. 

The second half of 2025 appears promising for a balanced trade, given the confidence in production capacity supported by available cream supplies. Yet, the market also benefits from targeted consumer interest around the $2.50 price point, adding a layer of demand elasticity that continues to underpin market strength.

USDA’s October Dairy Report: Navigating Production Shifts and Market Resilience

The USDA’s October Dairy Products report provides a comprehensive overview of the trends in cheese and butter production in the United States, revealing pivotal insights into market dynamics. Notably, total cheese production witnessed an incremental rise, reaching 1.226 billion pounds, marking a 1.0% increase compared to last year. This modest increase suggests a more robust output relative to the stagnation observed in September, signaling potential stabilization in demand despite underlying challenges. 

Conversely, the production of U.S. Cheddar remains tepid, showing a 3.1% decline against the figures recorded in October 2023. This downturn in Cheddar production underscores a potential shift in consumer preference or market demand, challenging producers to optimize production levels without incurring surplus. Such strategic restraint aligns with maintaining balanced inventories amidst fluctuating demand. 

In the butter sector, production expanded by 3.1%, totaling 167.5 million pounds. While this growth is a marked deceleration from the double-digit increases noted in August and September, it reflects the market’s ability to calibrate outputs effectively to avoid oversupply, thus supporting price levels. The deceleration suggests some caution among producers, yet the upward trend in butter production reinforces its consistent demand in the domestic market. 

These production insights, grounded in the October Dairy Products report, highlight shifts in year-over-year production patterns and underline dairy producers’ nuanced adjustments to navigate current market demands and price signals. As the industry maneuvers through these fluctuations, strategic production decisions will be crucial in shaping future market resilience and pricing stability.

Strategic Advantage: U.S. Dairy’s Path to Global Leadership through Competitive Pricing

The current price of cheese in the U.S. is $1.67 per pound, significantly lower than in international markets such as New Zealand and the EU, where cheese fetches $2.13 and $2.28 per pound, respectively. This disparity presents a strategic opportunity for U.S. producers to expand their export reach. The more competitive pricing could make U.S. cheese an attractive option for international buyers seeking cost-effective imports. 

Similarly, U.S. butter, priced at $2.52 per pound, is also competitively positioned in the global market compared to New Zealand’s $2.96 per pound and Europe’s far higher price of $3.80 per pound. Such pricing differentials present promising export prospects for U.S. butter producers, who can capitalize on these price advantages to penetrate foreign markets. 

Lower U.S. price levels relative to international markets are beneficial for exports and could also influence domestic market dynamics. This pricing competitive edge may stimulate increased production as domestic suppliers aim to meet potential heightened demand at home and abroad. It may also lead to adjusting domestic supply chains to better cater to the export-oriented production strategy. For U.S. dairy farmers, aligning production with global pricing trends is crucial for sustaining competitiveness and leveraging new markets.

Whey and NFDM: Essential Components in Dairy Market Dynamics 

The intricate web of the global dairy market is significantly influenced by the roles of whey and nonfat dry milk (NFDM). Recently, whey has shown resilience, maintaining its position above 70 cents despite a minor slip, a testament to its critical role in the Class III pricing structure. Given that every penny moves in whey correlates to a six-cent adjustment in Class III milk prices, its stability underpins the robustness seen in this sector despite broader market fluctuations. 

On the production front, the October Dairy Products report indicated a notable downturn in dry whey production—down 12.3% from the previous year. This significant reduction in output, paired with a 33.1% decline in stocks from 2023, has likely contributed to the observed stability in whey pricing, supporting its market relevance even as other products like cheese advance [USDA Dairy Products report]. 

Conversely, NFDM’s market performance appears more precarious. Despite weaker production figures and growing inventories, NFDM prices remain around $1.40. Recently, the spot market saw NFDM edge down half a cent as supply pockets permeated the CME market, testing this price ceiling. Analysts suggest that the lack of aggressive global demand, amplified by global price competitiveness, may prevent NFDM from capitalizing on current price points [source]. 

The implications of these trends are profound for the dairy market. The robust price amidst constrained production indicates strong demand fundamentals for whey, offering producers a buffer against volatility in other dairy categories. Meanwhile, NFDM’s plateau suggests potential opportunities or risks contingent upon global demand or supply dynamics shifts. Therefore, Market participants must navigate these evolving landscapes strategically, balancing production with emerging market cues to effectively leverage these critical commodities.

Technical Terrain: Navigating Peaks and Valleys in Cheese and Butter Markets 

The current landscape in the CME cheese and butter markets reveals key technical considerations that can significantly impact future price movements and trading strategies. Notably, the current market is facing resistance levels just above prevailing prices. This suggests that while a continued upward trajectory is possible, traders should exercise caution as price action could encounter difficulty sustaining momentum beyond these thresholds. 

Technical patterns indicate the potential for a weekly reversal in nearby contracts, a development usually perceived as bullish despite lackluster current demand narratives. Such a reversal suggests that underlying strength supports current price rebounds. It could attract more buying interest if confirmed, further fueling upward price momentum. 

Traders should watch these resistance points closely. Breaking through them could initiate a new price leg higher, indicating robust demand or supply dynamics that could alter market perceptions. On the other hand, failure to surpass these resistance levels could result in consolidation phases where prices stabilize, allowing for strategic reassessment. 

Regarding trading strategies, prudent market participants might consider short-term positions to capitalize on these potential reversals and longer-term hedges to mitigate risk should prices reverse again or encounter sustained pressure. This multifaceted approach allows for flexibility, ensuring traders can efficiently adapt to evolving market dynamics.

The Bottom Line

The current landscape of the CME market indicates the rebound of cheese and butter prices and the intricate web of production dynamics influencing these shifts. As the U.S. continues to ramp up cheese and butter production, the pivotal role of strategic pricing relative to international markets cannot be overstated. Navigating the complexities of whey and NFDM further underscores the need for dairy professionals to remain vigilant and proactive in their market strategies. 

Dairy farmers and industry stakeholders must monitor emerging market trends and assess how these could affect their operations. What strategies can you adopt to leverage this knowledge and navigate fluctuating market conditions? Can you implement innovative approaches to stay ahead of the competition despite shifting demand and production levels? 

Engage with these questions, adapt your business strategies, and harness the insights from ongoing market reports. Staying informed with reports like these will ensure you are well-equipped to make informed decisions, enhancing your resilience and competitive edge in this dynamic industry.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

US Dairy Production Trends: Unpacking October Surprises and Future Implications

Understand October’s US dairy trends. How might changes in cheese and butter affect your business? Review the data and future insights.

dairy industry trends, cheese production analysis, US Cheddar production decline, butter production increase, Nonfat Dry Milk production, dairy market dynamics, consumer preferences in dairy, dairy export opportunities, Skim Milk Powder challenges, economic resilience in dairy

Did anyone anticipate the glide upon cheese production or the stumble in butter output? The October Dairy Products Report unfurls unforeseen trends, prompting a reevaluation of market dynamics in the dairy industry. Cheese production, while inching upwards by 1.0% from last year, nonetheless reveals a downward bump that has tongues wagging among market analysts. US Cheddar production plunges by 3.1%, casting uncertainty on market predictions. Are we witnessing the onset of a more profound market shift? Such insights, crucial for dairy farmers and industry professionals, provide a deeper understanding of the industry’s current state and future direction, empowering stakeholders to make informed decisions. 

Shifting Sands: The US Dairy Production Landscape Evolves 

As the October Dairy Products report unfolds, a nuanced narrative of the US dairy production landscape emerges. Notably, there is a slight uptick in overall cheese production compared to the previous year, nudging upwards by 1.0% despite certain expectations suggesting otherwise. This indicates a modest recovery from the stagnant figures observed in September. However, within this broad category, Cheddar—a staple in the American cheese sector—continues to underscore the industry’s complexities, as its production notably dipped by 3.1% from October last year. This contraction indicates the challenges cheesemakers face in maintaining Cheddar’s demand momentum, potentially signaling shifts in consumer preferences or competition within the cheese category. 

Turning our gaze to butter, the situation presents a contrast. Here, production witnessed a 3.1% rise compared to last year. Although this is a deceleration from the double-digit growth rates of previous months, it remains a positive indicator of steady consumption patterns. The availability of ample cream supplies continues to support this production, reflecting a favorable supply chain status. 

Meanwhile, Nonfat Dry Milk (NFDM) sees developments of its own. While production estimates exceeded forecasts by 7 million lbs., it navigated a balancing act with Skimmed Milk Powder (SMP) production to present a combined output close to expectations, albeit showing a 9% year-over-year decline. This decline poses questions about domestic and international demand adjustments that stakeholders must address to avoid potential market imbalances. 

The implications of these trends are multifaceted. The cheese market, grappling with the challenge of a waning Cheddar demand, may see alterations in pricing strategies to stimulate consumer interest or explore export opportunities. Butter’s steady growth suggests relative market stability, offering some insulation from volatility. Still, it also underscores the need to monitor cream supply chains. In the case of NFDM, producers must remain agile, whether by pursuing emerging markets or refining production processes, to maintain economic viability.

Cheddar’s Challenge: Navigating a Competitive Cheese Landscape

The October Dairy Products report may have left stakeholders pondering the lackluster performance in the cheese production sector, particularly cheddar, which saw a notable 3.1% decline compared to the previous year. Such figures raise pertinent questions about the underlying causes. Various factors may have contributed to this decline, including shifts in consumer preferences and potential economic constraints influencing buying behavior. 

Cheddar, traditionally a staple in the American diet, is losing its edge amid new cheese varieties emerging. The proliferation of artisanal and specialty cheeses might redirect consumer interest, creating a competitive landscape that challenges cheddar’s dominance. Additionally, recent health trends emphasizing lower fat and salt intake could lead consumers away from processed and mature cheeses, further impacting cheddar’s popularity. This decline in Cheddar production could signal a shift in consumer preferences and competition within the cheese category, prompting stakeholders to consider diversifying their product range or adjusting their production volumes. 

Despite the downturn, cheesemakers are navigating these turbulent waters with strategic diligence. By tightly controlling production volumes, they deftly sidestep the risks associated with an oversupply, which could otherwise drive prices down and exacerbate market challenges. This careful balancing act suggests an acute awareness of market signals. It highlights tactical production adjustments tailored to current demand dynamics. These producers demonstrate agility and foresight by aligning output with actual market needs. 

Furthermore, cheesemakers’ ability to manage production efficiently in such a volatile environment reflects broader market trends. Their savvy approaches safeguard their operations and represent a bigger picture of an industry attuned to consumer demands and supply chain fluctuations. As we navigate these dynamic conditions, the emphasis will likely remain on adaptability and market responsiveness as key strategies for sustaining competitiveness across the cheese production landscape, underscoring the crucial role of each stakeholder in shaping the industry’s future.

Butter’s Balancing Act: Navigating Slower Growth Signals

While butter production was up 3.1% from last year, the pace has notably decelerated compared to previous months. In stark contrast to the impressive growth rates of +15.1% in August and +12.1% in September, October’s figures reveal a significant downshift. This slowdown in growth could be attributed to several factors, including seasonal fluctuations in milk supply and changes in consumer demand, potentially influenced by rising health consciousness among consumers. 

The immediate impact on the market could be multifaceted. On the one hand, a slowdown in production growth may help stabilize butter prices after periods of surplus-driven price-cutting. However, it may also signal a more cautious approach from producers, anticipating either a plateau in demand or strategic adjustments to manage cost and supply chain challenges. As butter remains a staple in the American diet, these shifts in production strategy could trigger broader market implications, from retail pricing to export capabilities—and demand forecasts will need to be analyzed closely in the coming months.

NFDM and SMP Dynamics: Treading New Grounds 

The Non-Fat Dry Milk (NFDM) and Skim Milk Powder (SMP) sectors are experiencing a notable downturn, with a 9% year-over-year decline. This decrease is more than just a figure; it reflects broader shifts within the dairy industry. Such a reduction prompts the question, why? 

This decline hints at an intentional realignment of resources, as fat and protein components, which would traditionally bolster NFDM and SMP output, are redirected elsewhere. The sectors seeing this uptick include Milk Protein Concentrates (MPC), which have increased by 84% year over year. Miscellaneous dairy products like ice cream, sour cream, and yogurt are also beneficial, as they are likely to receive the redirected fat and protein, leading to increased production and potentially higher margins. 

The reallocation of fat and protein specifically into MPC signals a strategic focus on products with potentially higher margins or demand, implying a calculated industry response to changing market needs. As dairy producers navigate these tidal shifts, understanding this resource reallocation offers insight into their broader production strategies. 

This strategic transition raises the question: Are producers scaling down NFDM and SMP production to optimize financial returns or adapt to evolving consumer tastes? Given the dynamic dairy market, these are essential considerations for stakeholders who aim to keep pace with shifting trends.

Supply Surprises: Navigating the Dairy Stock Dilemma

In an unexpected twist, the October Dairy Products report revealed that dry whey stocks were 10 million pounds lower than anticipated, while lactose stocks fell short by 5 million pounds compared to forecasts. This deviation from expected levels prompts a deeper examination of the factors at play and their potential implications on supply chains and the pricing strategies in the dairy sector. 

Industry experts suggest that the dwindling stock levels of dry whey could be attributed to increased domestic demand and expanding export markets. As consumer preferences evolve, there is a marked shift towards incorporating dairy-derived protein sources in daily diets, propelling demand. Concurrently, lactose stock reductions might stem from intensified competition for dairy solids among manufacturers focusing on enhanced dairy-based product lines, particularly in the infant formula and sports nutrition segments. 

Such discrepancies pose intriguing challenges and opportunities for stakeholders. Lower stock levels can exert upward pressure on prices, benefiting producers in the short term. Conversely, sustained shortages could lead to supply constraints, potentially hindering consistent product availability if not strategically managed. As the market grapples with these unexpected fluctuations, it remains pivotal for dairy producers and suppliers to adjust their operational and pricing strategies agilely to maintain equilibrium and capitalize on emerging demand trends.

Transformative Times: Navigating the Dairy Industry’s Evolving Landscape

The latest figures in US dairy production signal a transformative phase, raising critical questions for stakeholders. With cheese, particularly cheddar, witnessing subdued demand, production strategies could be re-evaluated. Cheese producers might benefit from exploring diversification to include trending varieties that align with evolving consumer tastes. 

Butter’s moderate growth, despite a slowdown, suggests stable consumer interest yet also highlights the need for sustained innovation to capture new market segments. Nonfat Dry Milk (NFDM) and Skim Milk Powder (SMP) sectors reveal pressures that might push processors to optimize efficiencies and explore alternative uses for these products. 

Emerging production trends also create a backdrop for strategic reassessment. Adopting advanced farming techniques and technology could enhance dairy farmers’ productivity and cost-effectiveness. Meanwhile, industry professionals may need to focus on supply chain flexibility and market adaptation strategies to buffer against unexpected shifts. 

As Miscellaneous Product utilization grows, pinpointing areas such as specialty ice creams or cultured dairy goods could unlock new opportunities. Understanding consumer preferences and proactively adjusting to shifts in demand could offer pathways to sustain and grow the market footprint in a competitive landscape. 

The current production insights call for an agile approach to navigating the future dairy terrain. Traditional practices should be blended with innovative foresight to ensure industry resilience.

The Bottom Line

The latest US Dairy Product Production Report paints a nuanced picture of an industry in flux. While cheese production is showing modest growth, Cheddar continues to face challenges, highlighting a cautious approach by cheesemakers amidst tepid demand. Butter production, although growing, indicates a cooling trend compared to earlier months, demanding strategic adjustments in response to changing market dynamics. Meanwhile, NFDM and SMP are navigating new terrains, reflecting dairy markets’ shifting preferences and priorities. Surprising variations in stock inventories, with lower-than-expected dry whey and lactose, signal complex supply chain challenges requiring vigilance and adaptability. 

As the dairy industry stands at a pivotal moment, how will these evolving trends reshape production strategies and market competition in the coming years? Dairy professionals must assess how these patterns will influence their business practices and growth potential in an industry that demands resilience and flexibility. We invite you to share your perspectives and experiences regarding these transformative trends in dairy production. Join the conversation on our website and social media channels—your insights are invaluable to forging a collaborative path forward.

Key Takeaways:

  • Total cheese production saw a modest increase of 1.0% year-over-year, indicating a slight uptick despite market expectations.
  • Cheddar production faced a significant decline of 3.1% compared to the previous year, highlighting ongoing challenges in this sector.
  • Butter production, although experiencing a slowdown, still grew by 3.1% from the previous year, showing resilience amidst fluctuating growth rates.
  • NFDM production exceeded forecasts by 7 million lbs. yet was partly balanced by lower-than-expected SMP production, resulting in a net 9% decrease year-over-year.
  • MPC production showed remarkable growth, increasing by 84% year-over-year, as the market adjusted to changing demands.
  • Lactose and Dry Whey stocks were below forecast levels, suggesting robust consumption or inventory adjustments.
  • Overall dynamics suggest a restrained approach by cheesemakers, especially in cheddar production, aligning with demand patterns.

Summary:

October’s Dairy Products report highlights subtle yet vital shifts in US dairy production. While total cheese output rose slightly year-over-year, Cheddar faced a significant 3.1% dip, showing lukewarm demand. Butter production, though below expectations, grew compared to the previous year but at a reduced pace, suggesting strategic supply management to align with market needs. Meanwhile, various outputs of non-fat dry and skim milk powder reflect broader market dynamics, with producers balancing product stocks to adapt to changing conditions. This suggests potential consumer preferences and competition shifts within the cheese sector, while butter’s upward trajectory indicates a stable supply chain. Declines in NFDM and SMP may imply strategic adjustments in production to enhance financial returns or adapt to market trends.

Learn more: 

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Global Butter Boom: Why Rising Prices Are Challenging Dairy Dynamics

The global butter boom reshapes dairy markets. What drives the rising prices, and how does it affect dairy farmers? Dive into the insights here.

Summary:

In a world where culinary trends wax and wane, the surge in butter demand has caused a ripple effect across the global dairy industry, driven by consumer cravings for this creamy staple and confirmed by FAO data showing a 13-month streak of rising prices. While the United States has mitigated butter prices through increased production, countries like Europe and New Zealand hold their positions at premium prices. Seasonally low milk production and unforeseen animal health issues like the recent bluetongue outbreak in Germany have further tightened European supply chains. Meanwhile, New Zealand sustains intense production levels, leveraging its natural advantages. The U.S. butter market, priced at around $2.55 per pound, reveals a significant differential compared to Europe, which faces complex supply constraints and economic strains from elevated prices, positioning butter as the new gold in the dairy industry.

Key Takeaways:

  • Global consumer demand has driven world butter prices upward for 13 consecutive months, as tracked by the FAO.
  • U.S. butter prices have recently decreased from previous highs due to increased production, even amidst strong demand.
  • Despite being third in world prices, the U.S. faces a potential opportunity to export butter, competing with higher butterfat content products from the EU and New Zealand.
  • Europe experiences significantly higher butter prices with tight supplies, exacerbating premium costs compared to the U.S.
  • New Zealand’s butter prices have risen by 40% from last year, indicating strong market positioning.
butter prices, dairy industry trends, global butter demand, milk production issues, European butter market, bluetongue outbreak impact, butterfat content pricing, U.S. butter market, dairy supply constraints, New Zealand butter production

Once a staple in the dairy world, butter has now become a commodity akin to gold. The numbers don’t lie over the past 13 months; global butter prices have consistently surged, a fact documented by the Food and Agriculture Organization (FAO). This isn’t just a blip on the market radar; it’s a significant trend shaking the dairy industry’s foundations. With butter’s popularity soaring, what does this rapid rise mean for dairy producers worldwide? Are we witnessing a revolution redefining the rules of dairy farming, or is this just another fleeting wave that will soon subside? 

Unchained: The Global Butter Phenomenon 

The dairy world has always been a delicate balance of supply and demand, but the stage is now set for a dramatic shift. With butter prices skyrocketing internationally, industry professionals must understand the ‘why’ behind this surge. At the heart of this phenomenon is an impressive rise in consumer demand for butter-centric products. According to the Food and Agriculture Organization (FAO), this growing appetite pushes inventories to their limits and creates a ripple effect throughout the sector [FAO]. 

Seasonally low milk production contributes to this scarcity, particularly in Western Europe. This region, a significant player in the global butter market, has experienced a notable decline in milk output, further fueling the price hike. The International Dairy Federation says this downturn arises from environmental factors and unforeseen animal health issues, such as the recent bluetongue outbreak in Germany [International Dairy Federation]. 

Moreover, while some regions have escalated their production levels, these efforts have not been enough to offset the burgeoning demand, which has resulted in depleted stocks. As butter becomes a sought-after commodity, global markets grapple with how to meet these challenges, leaving dairy farmers and producers with much to ponder as they navigate these uncharted waters.

A Balancing Act: The U.S. Butter Market’s Supply and Demand Tango

Recent trends in the U.S. butter market offer an insightful glimpse into the intricate dance of supply and demand. Despite sky-high demand, U.S. butter prices have taken a downward trajectory—a paradox driven not by faltering interest but by a production surge that’s heaving the scales. This results from U.S. butter manufacturers responding robustly to market signals by ramping up production to unprecedented levels. 

The heart of the matter lies in the numbers. Record monthly outputs characterized the past few months, with August alone witnessing a 14.5% increase compared to the same period in 2023. This was not an outlier. September mirrored this trend with an 11.3% surge over the prior year. The results of this production boost are evident in the market where the increased supply has outpaced even the strong consumer demand, leading to a price adjustment down to a more “normal” level of around $2.55 per pound, compared to the dizzying heights of earlier this year. 

This dynamic underscores a critical lesson in economics: not just the presence of demand that dictates market prices but the balance—or imbalance—of supply that holds sway. As the world continues its buttery affair, the U.S. is a testament to how production prowess can alter pricing landscapes, introducing volatility into what consumers might expect to be a serene market.

Butter Battles: Navigating the Global Market Stratosphere

The current global butter landscape reveals intriguing dynamics between the U.S., New Zealand, and European markets. U.S. butter prices hover around $2.55 per pound, reflecting an intense domestic situation overshadowed by international counterparts. Across the Pacific, New Zealand’s most recent Global Dairy Trade (GDT) auction showcased butter trading at $3.18 per pound. While New Zealand butter has a slight price advantage, it’s not the highest globally. 

Europe further amplifies the disparity with even greater premiums; butter prices have surged to $3.65 per pound in France and $3.93 per pound in Germany. These figures illustrate a significant gap from the U.S., reflecting a 40% to 60% year-over-year increase in Europe compared to U.S. prices declining by nearly 20%. 

Central to this discussion is the differentiation of butterfat content. Typically, U.S. butter comprises 80% butterfat, while European and New Zealand products offer a higher 82% content. This variance not only influences pricing structures but also shapes trade opportunities. European and Kiwi butter, with their richer content, cater more readily to international markets demanding premium quality. This presents an opportunity for U.S. producers to capitalize on niche markets or product innovation, inspiring them to explore new avenues in the global butter market.

The European Entanglement: Navigating Dairy Disruptions and Skyrocketing Prices

Europe has grappled with complex supply constraints that have increased butter prices. A prime concern among these factors is the unexpected bluetongue outbreak in Germany, at the heart of Europe’s dairy production. This viral disease has led to restrictions and heightened regulatory measures, causing a significant reduction in milk supplies. Such constraints naturally magnify the demand-supply pressure, pushing up butter prices to levels few anticipated. 

The repercussions are evident across Europe. In France, which traditionally boasts robust dairy outputs, butter prices have climbed substantially, highlighting regional shortages. This stark illustration of the interconnectedness of the European market, where a disruption in one area quickly reverberates through others, illustrates the challenges for dairy farmers, particularly in affected zones like Germany. They must navigate the direct impacts of disease management and the secondary economic strains of dealing with sharply escalated prices. 

Yet, there’s a dual-edged sword at play here. While consumers face steeper costs, farmers in less affected areas may temporarily benefit from the high-pricing environment. This windfall, however, is precarious, reliant on the continual shifts of market dynamics and the eventual containment of the disease. European dairy farmers, therefore, find themselves teetering on a tightrope of opportunity and risk, with their fortunes hinging on how swiftly and effectively these supply constraints can be alleviated. 

As the continent braces for the winter holiday demand surge, pressure mounts to restore supply chains swiftly. This intricate balancing act demands coordinated efforts and policy-driven solutions to stabilize the sector. For many, hope lies in ingenuity and resilience, qualities that have long defined Europe’s agricultural backbone. Strategic planning can play a crucial role in mitigating the impact of supply constraints, offering a ray of hope in an otherwise challenging situation. 

New Zealand: The Butter Bastion Guiding Global Supply

New Zealand, a titan in the dairy world, is at the forefront of the global butter market. With vast expanses of pastureland and favorable climates, the country has strategically positioned itself as a key exporter, leveraging its natural advantages to sustain intense production levels. The country’s strategic prowess is evidenced in its ability to not only maintain but often dictate terms on the global stage, a fact that industry professionals should be keenly aware of. 

The recent 40% surge in butter prices over the past year illuminates New Zealand’s pivotal role. This sharp rise mirrors the country’s adept handling of supply chain dynamics amidst fluctuating demand. As global butter supplies tighten, New Zealand’s ability to keep its production consistently high provides much-needed stability to the international market. 

New Zealand’s pricing strategy is a barometer and an anchor within the dairy sector. The $3.18 per pound figure, as revealed in the most recent Global Dairy Trade (GDT) auction, underscores a tactical decision to balance competitiveness with profitability. This ensures that while prices remain attractive for New Zealand’s butter exports, they also reflect the scarcity and value of high-quality products in an ever-competitive global market. 

New Zealand plays a crucial mediator role in shaping these trends. It absorbs shifts in production and demand from other markets, cushioning against the volatility that might otherwise ripple through the industry as other regions grapple with their dairy crises, whether due to disease outbreaks or resource strains, New Zealand’s steadfast output and savvy market maneuvers signal resilience and assure consumers and stakeholders alike. New Zealand stands as a cornerstone in what has become an increasingly unpredictable butter economy.

Butter’s Crescendo: Opportunities and Challenges in Today’s Market

The global surge in butter prices signifies more than just an economic wave; it heralds a shifting landscape for dairy farmers and industry professionals. As the demand for butter crescendos, this presents both opportunities and challenges. Have you pondered how this butter boom might ripple through your operations? 

On one hand, the prospect of higher revenues can be compelling. But consider this: How sustainable are these price hikes in the long run? With production on the rise, particularly in the U.S., the market is treading a fine line. Overproduction could eventually stifle profits if demand falters. 

So, what strategic moves can you make? Diversifying your product mix could be a prudent approach. You can cushion your operation against price fluctuations by not solely relying on butter. Moreover, exploring export opportunities, particularly in regions like Europe and New Zealand, where butter prices are soaring, could unlock new markets and revenue streams. 

Cost management is another critical strategy. Maintaining lean operations is key in a climate where input costs can skyrocket as quickly as product prices. This might entail optimizing feed efficiency or investing in technology that enhances productivity without proportionally increasing expenses. 

Engagement with industry networks and market data is indispensable. Are you leveraging the latest insights to anticipate shifts in consumer behavior or regulatory changes? By staying informed and adaptable, dairy farmers and professionals can weather the current butter boom and position themselves advantageously in an ever-evolving market. 

These challenges are not easy, and there are no singular solutions. However, by critically analyzing their implications and proactively strategizing, dairy stakeholders can transform potential hurdles into opportunities for growth and resilience in the global market.

The Bottom Line

The global butter boom has spotlighted the dairy industry’s intricate dance of supply and demand. These developments highlight opportunities and challenges, from the staggering price variance between the U.S., Europe, and New Zealand to the production spikes in North America. Europe grapples with tight supplies and elevated prices, showcasing the delicate balance disrupted by factors like the bluetongue outbreak. Meanwhile, despite escalating costs, New Zealand capitalizes on its position as a key supplier. The U.S., with its robust production capacity, finds itself in a unique position to redefine its participation in the global market. As the world craves butter, dairy professionals must ponder: How can we sustainably satisfy this growing demand while ensuring economic viability and addressing the inherent volatility in the dairy sector? It’s time to strategize, innovate, and collaboratively shape the future of dairy in this butter-dominated landscape.

Learn more:

Explore the global butter boom and its impact on dairy dynamics. Why are prices soaring, and what does it mean for dairy farmers? Discover the insights now.

New Zealand Milk Prices Surge: What This Means for Dairy Farmers and Global Markets

How are rising New Zealand milk prices affecting dairy farmers and global markets, and what do these shifts mean for the dairy industry’s future?

Summary:

The New Zealand milk market is cautiously optimistic amidst unfolding global dairy dynamics. This report dissects key developments impacting farmers and industry stakeholders, like milk price fluctuations and global demand trends. Fonterra has raised its payout forecast to $9.50, highlighting tension between expectations and reality. New Zealand’s milk price surge, above $11 per kg/MS, poses market competitiveness concerns, with the cheese sector facing challenges due to declining prices. Strategic navigation is crucial for maximizing profitability in this fluctuating landscape, as the GDT index rose 1.1%, with WMP up by 4.1%. Regional milk production nuances span from new opportunities in post-crisis California to EU growth exceeding forecasts and Argentina’s resilience with only a 0.4% decline in October. Despite higher prices, global dairy demand remains stable, driven by diverse patterns from key markets.

Key Takeaways:

  • New Zealand’s milk payout sees a boost, with Fonterra revising its predictions upwards amidst industry forecasts of over $9.50 per kg/MS.
  • The GDT index experiences a modest increase of 1.1%, propelled primarily by a 4.1% rise in Whole Milk Powder prices, with lesser activity in butter and SMP.
  • U.S. milk production grows slightly above projections, aided by an expanding dairy herd, indicating strong future growth potential.
  • EU27+UK milk production surpasses expectations with remarkable growth in milk’s fat and protein content, leading to increased component-adjusted output.
  • Argentina’s milk production decline slows, marking the slightest reduction in over a year, keeping farm gate prices favorable and promising future gains.
  • Despite higher global prices, dairy import demand remains stable, though high-fat prices significantly impact butter and cheese demand outside China                                                            .
  • China’s dairy imports are set to improve, though predictions remain cautious due to previously sluggish activity.
New Zealand milk prices, Fonterra dairy forecast, cheese market challenges, GDT index performance, Whole Milk Powder trends, North Asia dairy market, California milk output recovery, European dairy growth, Argentinian dairy resilience, global dairy import demand

The sudden surge in New Zealand’s milk price is a significant development in the global dairy industry, sparking crucial discussions about its potential to redefine global competitiveness. As Fonterra’s forecast climbs and prices soar past the $11 per kg/MS threshold, stakeholders are eager for insights. Understanding these complex changes is essential, especially as regional production shifts and import demands create ripples in commodity valuations and influence strategic directions. Adapting to this dynamic environment is not just advantageous—it’s a necessity for sustained success in the dairy industry.

Optimism in New Zealand’s Milk Pricing: A Double-Edged Sword for Dairy Farmers?

The current state of New Zealand’s milk payouts paints an optimistic picture for dairy farmers, with a notable increase to $11.15 per kg/MS significantly boosting the season-to-date average to $9.85. This upswing is a positive development for many farmers who rely on these payouts for their livelihood. Fonterra’s decision to revise their predicted payout upwards from $9.00 to $9.50 signals potential financial relief for dairy farmers. However, it’s important to note that most forecasters anticipate payouts that may exceed $9.50, underscoring an air of cautious optimism in the industry. 

Despite this generally positive outlook, the role of dairy professionals in strategically navigating market trends to maximize profitability amidst fluctuating demand and pricing signals cannot be overstated. Examining the performance of different dairy product streams is crucial. While the higher whole milk powder (WMP) prices help close the gap between varying streams, the cheese sector faces significant hurdles. The decline in cheese prices makes it the least lucrative among major dairy products, posing challenges for producers specialized in this line. These dynamics underscore the crucial role of dairy professionals in the industry.

A Global Tug-of-War: GDT Index Performance and the Subtle Art of Market Navigation

The recent  1.1% increase in the GDT index reflects an intricate dance between forecast expectations and market reality. While futures markets anticipated stronger movement, the results tell a nuanced story. Whole Milk Powder (WMP) ‘s rise by 4.1% emerges as the singular highlight among major products, defying broader market predictions. This suggests a robust, nearly universal demand amidst heightened pricing. Each region played its part in this development. 

North Asia maintained its marginal lead in the WMP market share, slightly edging its volume from the previous event. This indicates steady, albeit cautious, procurement strategies despite the cost hikes. Southeast Asia stood parallel, reflecting stable order books and a relentless appetite for dairy nutrition. Demand surged across Africa and South/Central America as these regions increased their purchases, pushing the WMP dynamics into a more competitive and price-resilient space. 

Turning to Skim Milk Powder (SMP), the narrative shifts. North Asia saw a dip in its SMP volumes compared to the last event, yet fared better than the previous year. Conversely, Southeast Asia and the Middle East saw an upswing in SMP procurement. These adjustments highlight a diversified demand landscape, where regional strategies adapt swiftly to align with emerging global price signals and local consumption patterns.

California’s Comeback: Will the U.S. Dairy Expansion Flip the Market Script?

U.S. milk production in October presented a cautiously optimistic picture, with a notable 0.2% increase from the previous year. This growth defies earlier forecasts that predicted a marginal decline, showcasing the resilience and adaptability of the U.S. dairy industry. At the heart of this unexpected boost is the expansion of the dairy herd, which saw an increase of 19,000 head in October, adding to the upward adjustment of 18,000 head made in September. This uptick signifies a strategic push from dairy producers to bolster output amidst a competitive global market, instilling a sense of stakeholder reassurance and confidence. 

A critical component influencing the landscape is California’s recovery from the avian influenza crisis, a factor expected to significantly bolster milk production growth as we move into late 2024 and early 2025. Historically, California has been a powerhouse in the U.S. dairy sector, so its complete rebound could catalyze a surge in national milk output, providing new opportunities and posing market saturation challenges. Dairy professionals must contemplate how this recovery will shape domestic milk prices and influence international trade dynamics, particularly in a world where global dairy demand remains robust but selectively volatile.

European Dairy Renaissance: The EU27+UK’s Path to Increased Production and Profitability

The EU27+UK milk production scene showcases a promising trend. In September, production increased by 0.2%, surpassing previous forecasts. This uptick in production is complemented by a rise in the fat and protein content of the milk, resulting in a component-adjusted production growth of 1.2% year over year. Such improvements are crucial as they not only indicate healthier herds but also enhance the profitability of milk products. 

Key contributors to this upward momentum include countries like France, the UK, and Poland, which have demonstrated robust production growth. Several factors fuel this trend. In France, favorable weather conditions and efficient feed management have bolstered output—meanwhile, the UK benefits from strong domestic demand that drives its dairy sector. Poland’s commitment to technological advancements in dairy farming practices ensures steady gains. 

Moreover, current economic conditions paint a lucrative picture for European dairy farmers. Farm gate prices trend upward, and feed costs remain subdued, paving the way for potentially record-high margins in the coming months. This environment injects further confidence in escalating production levels as farmers anticipate better returns, setting the stage for continued growth into 2025.

Argentinian Dairy Defies the Odds: Stabilizing for a Productive Future 

Weathering the anticipated downturn, Argentinian milk production showed resilience with a mere 0.4% decline in October—remarkably more minor than the predicted 1.2% drop. This deviation underscores a stabilizing trend in the sector, bolstered primarily by unyielding farm gate milk prices. Despite minor variations in milk composition, notably a slight dip in fat content even as protein levels increased, the component-adjusted production saw its most minor decrease in over a year, sliding by just 0.5%. 

The profitability margins sustained by robust milk prices have been pivotal, keeping the financial equilibrium for producers favorable. With these prices defying downward expectations, there’s an assurance for dairy farmers that elevates prospects for productivity. As we approach the new year, 2025 hints at a landscape ripe for substantial gains—after all, by January, the industry will compare against last year’s significant declines, positioning it to showcase notable year-on-year growth. This emerging optimism, with the potential for substantial gains, will likely fuel production increases, paving the way for recovery and expansion and instilling stakeholders a sense of hope and optimism.

Import Resilience vs. Price Pressures: Global Dairy Demand’s Balancing Act 

The global import demand for dairy products has shown resilience in 2024 despite the challenges posed by higher prices, which inevitably translate into increased landed costs. Notably, this trend is driven by divergent demand patterns across significant markets. China’s import activities were subdued as of September. Still, they saw a rebound by October, particularly for New Zealand dairy products, highlighting an adaptive response to fluctuating economic conditions. Meanwhile, Mexico exhibited robust import activity during August and September. However, anecdotal evidence suggests a tapering demand in the subsequent months of the third quarter. This points to a complex interplay of factors influencing demand beyond price considerations. 

Looking ahead to 2025, cautious optimism about the global dairy import landscape exists. While high-fat dairy products like butter, anhydrous milk fat (AMF), and cheese will likely face dampened demand due to elevated pricing, whole milk powder (WMP) remains vulnerable. However, the uncertainty surrounding China’s import trajectory remains a pivotal factor. Past trends indicate potential volatility, yet forecasts suggest that Chinese demand might gradually stabilize or grow, provided economic conditions are favorable. Such a scenario could shift the global balance, reinforcing optimism among exporters. 

In summary, while higher landed costs present a ubiquitous challenge, the overall demand outlook for global dairy imports in 2025 hinges significantly on the economic climates and consumption trends in key markets like China and Mexico. The ability of these markets to absorb costs and maintain demand will largely dictate the global import demand dynamics for the foreseeable future.

The Bottom Line

As we dissect the current landscape of the global dairy market, the key takeaway is the intricate balance and interplay between regions. New Zealand’s optimistic surge in milk pricing indicates a confident yet cautious market stance. Meanwhile, as the U.S. dairy industry bounces back with increased herd sizes and production, European producers also note significant growth, underscoring a promising upward trend buoyed by favorable farm gate margins and robust protein yields. These changes are reverberating through the market, resulting in shifts in global dairy imports that hint at strategic pivots in response to tentative Chinese demand and rising price pressures.

Given these dynamics, a pertinent question emerges: How will this evolving global dairy ecosystem reshape individual business strategies and farm operations, weathering price volatility and consumer demand? Navigating these complex currents will require forward-thinking adaptation strategies from dairy farmers and industry stakeholders. In the face of these challenges and opportunities, one must ponder the strategic shifts necessary to align with the constantly evolving pulse of global trade. Where do you see your operations on this rapidly changing map, and what steps are you considering to secure your place within it?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Navigating the Rollercoaster: How Global Shifts in Dairy Trade Affect U.S. Farmers and Markets

How do global dairy trade shifts affect U.S. farmers? Are price changes and export trends altering the market? Find out now.

dairy market volatility, U.S. dairy product values, butter and cheese prices, whey powder demand, nonfat dry milk prices, U.S. cheese exports, dairy farmers strategies, global trade dynamics, protein-rich products demand, dairy pricing fluctuations

The global dairy market is on a rollercoaster of unpredictability, where volatility reigns supreme. Recent dramatic shifts in U.S. dairy product values send waves through markets worldwide, crafting a challenging environment for farmers and trade sectors. Picture this: a 22% drop in U.S. butter prices since their late-summer peak, alongside a cheese market grappling with increased output and falling prices. These dynamics compel us to ask how these global shifts affect you as a dairy professional. The market’s challenges are more than just numbers; they’re realities affecting livelihoods and strategies across the globe. Stakeholders must remain vigilant and adaptive, as fortunes seem to change rapidly, making it crucial to understand these trends for navigating this ever-evolving landscape.

Turmoil in the Churn: Navigating Rollercoaster U.S. Dairy Markets

The U.S. dairy markets are navigating through a period of adjustment marked by noticeable fluctuations in product pricing. Butter and cheese, staples of the American dairy industry, are currently staring down significant price declines. Butter prices have plummeted by 22% from their peak in late summer, primarily propelled by an oversupply of butterfat. In parallel, cheese markets are grappling with a considerable upsurge in output, leading to price reductions. Cheddar barrels and blocks show substantial decreases of 48% and 32%, respectively, from their earlier highs. 

These price declines contrast starkly with a scenario in the protein segment of the market. A robust demand surge for whey powder has pushed its prices to levels not seen since March 2022. Nonfat dry milk has followed a similar upward trajectory, recently climbing to a two-year high. This upward drift is supported by ongoing global demand for protein-rich products, contrasting sharply with the surpluses seen in butter and cheese. 

The divergence in pricing trends across different dairy products can be attributed to varying supply-demand dynamics. While domestic production oversupply has softened butter and cheese prices, the relentless international quest for dairy proteins has buoyed whey powder and NDM values. This economic tension sets a complex stage for U.S. dairy farmers and processors, who must strategically pivot to capitalize on export opportunities even as some domestic prices remain under pressure. 

The Teetering Balance of Global Dairy Markets 

The teetering balance of global dairy markets reveals opportunities and hurdles for U.S. exports. Low-balling domestic prices have positioned U.S. cheese and anhydrous milkfat as tempting options on the global stage. Dethroned from their sky-high pricing klieg lights, these products are basking newfound international appeal. With cheese exports already on an upward trajectory, these stealthy inflation dips invite the world to join America at the dairy table (USDA, 2024). 

Yet, the shining opportunity blindsides specific lookout points on the global horizon. While cheese and milkfat have found their sweet spot, U.S. milk powder and whey products zigzag through choppy waters. Skyrocketing prices at home render these proteins prohibitively pricey overseas, leading buyers to rethink their suppliers. By September, imports of whey protein concentrates reached a substantial 14-month high, suggesting a pivot toward imported alternatives (USDA, 2024). 

This dichotomy in the dairy pipeline has painted a complex picture for stakeholders. Understanding these dynamics is critical in a landscape where the invisible hand continually recalibrates the scales. For U.S. processors, adapting to market signals with agility is now the order of the day. Navigating these straits requires a compass rooted in data, discernment, and diplomatic finesse.

Global Trade Winds: U.S. Dairy Farmers Navigating a Mosaic of Opportunities and Challenges

As global trade winds shift, U.S. dairy farmers navigate a complex landscape. On the one hand, plummeting domestic prices for products like butter and cheese have positioned U.S. exports as tantalizingly competitive on the international stage. The resurgence in cheese exports offers a breath of relief for many farmers, potentially offsetting the domestic oversupply and reviving bottom lines. The escalating demand for anhydrous milkfat adds another layer of optimism, promising a robust export market and helping stabilize prices at home. 

However, this optimism is not without its shadows. The rising tide of dairy protein imports, such as whey protein concentrate, places added strain on the U.S. market. Domestic producers face stiffer competition, with imports climbing to levels not seen in over a year. The allure of cheaper foreign proteins chips away at local market share, compelling U.S. farmers to reevaluate their strategy and production focus. 

These dynamics suggest increased complexity in dairy farmers’ decision-making. The potential for export profit must be balanced against the competitive pressures from imports. Farmers are now grappling with decisions that require careful consideration of fluctuating market prices, trade policies, and global demand trends. This balancing act could redefine strategies, pushing some toward niche products or markets and prompting others to scale back production. 

Ultimately, while these global shifts offer fruitful opportunities, the path forward requires astute navigation. The implications for profitability will demand rigorous analysis and perhaps even a paradigm shift in how U.S. dairy farmers operate in an increasingly interconnected global marketplace.

Ripple Effects: How Global Economic Shifts Redefine U.S. Dairy Export Strategies

International markets are increasingly pivotal in the fortunes of the U.S. dairy trade, creating opportunities and challenges for farmers and processors alike. As global demand ebbs and flows, American agriculture feels the ripple effects keenly. Notably, key players like Mexico act as linchpins in U.S. export strategies, and fluctuations in their purchasing patterns can substantially influence market stability. 

Traditionally a stalwart ally in U.S. dairy exports, Mexico is reassessing its import palette amid shifting global economics. As processors there pivot towards more affordable alternatives, such as U.S. cheese over milk powder, they indirectly steer the fate of U.S. dairy producers. This action underscores the delicate balance international relations hold over U.S. dairy, impacting what goods remain competitive abroad. 

The broader scope of global demand, marked by fluctuating product values and emerging markets, challenges U.S. dairy’s adaptability. American producers must navigate these tides, responding to variable pricing and demand, which, in turn, determines their domestic market stability. Thus, as international players reconfigure their buying behaviors, U.S. dairy markets brace for the undulating impact, ever at the mercy of global trading winds.

Geopolitics and the Dairy Dilemmas: A Complex Dance 

The intricate web of geopolitical factors continues to influence the global dairy trade, shaping the fate of U.S. exports and imports. As the world’s largest exporter of dairy products, the United States navigates a complex landscape marked by shifting trade agreements, ever-evolving tariffs, and nuanced international relations. Recent developments, particularly renegotiating specific trade policies, have added more variables to the equation, demanding that U.S. dairy producers remain vigilant. 

For instance, the U.S.’s trade relationship with China remains critical in the dairy sector. Tensions between these economic powerhouses have led to fluctuating tariffs, which impact the cost and competitive positioning of American dairy products. Similarly, renegotiations of the USMCA have resulted in updates to trade terms with Mexico and Canada, two of the largest U.S. dairy export markets. Such changes require U.S. farmers and processors to recalibrate strategies, which might involve adjusting production volumes or seeking new markets. 

  • Trade Agreements: The impact of renewed agreements can lead to shifts in export and import landscapes, potentially opening or restricting market access.
  • Tariffs: Alterations in tariff structures can significantly alter the pricing of dairy products, both domestically and internationally.
  • International Relations: Diplomatic relations affect the ease of trade, influencing everything from customs procedures to consumer perceptions.

These geopolitical variables underscore the potent mix of challenges and opportunities U.S. dairy exporters face. Therefore, staying informed about policy changes and maintaining strong international relations will be crucial for navigating global market dynamics.

The Bottom Line

As we observe the ebbs and flows within the global dairy landscape, it’s clear that the U.S. dairy market holds both potential pitfalls and bountiful opportunities. Key points from this dynamic environment include the misalignment of U.S. cheese and butter prices with global standards, which can bolster exports, contrasted with the challenges of milk powder and whey in foreign markets. With increased imports of dairy proteins, industry adaptability becomes crucial. 

For U.S. dairy farmers and industry professionals, the roadmap to navigating these global shifts demands strategic foresight and flexibility. Embracing new market opportunities while safeguarding against import pressures will be pivotal. Collaborative efforts towards innovation and cost-efficiency could pave the way for sustained growth. 

The future of the dairy trade calls for a proactive mindset. How will you position yourself and your enterprise in response to these evolving market dynamics? Perhaps now is the time to reevaluate existing strategies and boldly enter the new world of dairy trade.

Summary:

The U.S. dairy market is volatile, with a striking decline in butter and cheese prices contradicted by soaring demand for whey powder. A 22% dip in butter prices and a 48% fall in Cheddar barrels highlight market unpredictability, while nonfat dry milk and whey powder hit peaks, signaling discordant market dynamics. This challenges traditional market expectations, as U.S. cheese and anhydrous milkfat exports gain momentum despite rising dairy protein imports. Amidst this market upheaval, American dairy farmers stand at a strategic crossroads of opportunities and challenges, forced to rethink approaches in this shifting global tableau, where robust demand for protein-rich products shapes trade dynamics.

Key Takeaways:

  • U.S. dairy markets are experiencing price volatility, with significant decreases in butter and cheese prices and increases in whey powder and nonfat dry milk values.
  • Competitive international pricing influences U.S. export dynamics, particularly boosting cheese and milkfat prospects.
  • Although U.S. dairy proteins are becoming less competitive globally, whey and milk powder imports are rising.
  • Changes in export patterns could stabilize U.S. dairy market prices, even as international trade has the potential to limit market fluctuations.
  • Domestic and international shifts in demand and pricing are redefining dairy farmers’ strategic approaches to exports.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Fluid Milk Sales Waver But Organic and Value-Added Products Surge in the Dairy Market

The decline in fluid milk sales contrasts with the rise of organic and value-added dairy products. What does this mean for dairy farmers? Explore how these trends are transforming the market landscape.

Summary:

In the midst of a fluctuating dairy industry landscape, September 2024 saw a 1.6% drop in total fluid milk sales compared to the prior year. Despite this, the demand for more varied and organic products has surged. Organic milk sales rose by 9%, underscoring a strong consumer preference for perceived health benefits and environmental options. The ‘other’ conventional categories also soared with a notable 31% growth, pointing towards a burgeoning interest in non-traditional dairy options. Furthermore, value-added dairy products have carved out a significant niche, boasting a 44% year-to-date increase as consumers gravitate towards options like lactose-free milk and drinkable yogurt. This shift signals a broader transformation within the industry, prompting a strategic rethink in processing and supply dynamics to adapt to these evolving consumer trends.

Key Takeaways:

  • Despite a dip in total fluid milk sales in September, organic milk sales have surged by 9% compared to the previous year.
  • Organic products, including various types of fluid milk, are gaining popularity, showing year-over-year growth.
  • The “other” conventional fluid milk products category experienced substantial growth, indicating shifting consumer preferences.
  • Year-to-date milk sales show a modest increase, defying the long-term trend of declining milk consumption.
  • Whole milk sales continue to climb, bolstering overall fluid milk growth.
  • Interest in value-added products like lactose-free milk and eggnog is rising, suggesting a shift towards more specialized dairy items.
  • Increased demand for Class I milk could positively impact producer milk checks and milk supply dynamics.
  • Global dairy trade indicates potential rising prices, as shown by the increase in the Global Dairy Trade Index.

If you’ve ever needed clarification on why certain products gain popularity while others fade, you’re not alone. The dairy market is a dynamic landscape, shaped by consumer preferences. Traditional fluid milk sales may be slipping, but the rise in organic and value-added milk products continues to build momentum. With nearly 3.5 billion pounds sold in a single month, the numbers tell two tales: a 1.6% dip in conventional milk sales starkly contrasts with a robust 9% surge in organic milk products. Why are consumers abandoning traditional milk and embracing organic and value-added options? The market, seemingly in flux, leaves dairy producers and sellers contemplating this very question as they navigate a landscape that’s becoming increasingly complex and diversified. As we dive deeper into this trend, we uncover the reasons behind this consumer shift and the potential impacts on the agricultural industry.

Unraveling the Fluid Milk Saga: Changes in the Dairy Aisle

The fluid milk industry has recently experienced a nuanced shift, accentuated by a 1.6% drop in total fluid milk sales in September 2024 compared to September 2023. However, beneath these figures lies a story of change and opportunity. Notably, while traditional fluid milk sales face challenges, the demand for organic milk has surged. In September alone, the sales of organic milk—which account for about 10% of total fluid milk volumes—rose by 9% year-over-year. This uptick indicates a growing consumer interest in organic products, as demonstrated by the sale of 249 million pounds of organic milk during this period. 

Moreover, a particular category within the conventional fluid milk segment has emerged as a strong performer: the ambiguously termed ‘other’ conventional fluid milk products. This segment witnessed an impressive growth of 31% compared to September last year, suggesting a diversification in consumer preferences away from traditional milk types. This could hint at a transformation in how consumers perceive and utilize fluid milk, with a trend towards more specialized or functional milk products. 

The broader implications of these shifts could be significant for producers. A return of milk demand toward Class I could enhance producer milk checks and impact milk supply dynamics. As processors choose to bottle over processing into commodities, this might tighten supplies and potentially drive prices upward, offering a glimpse into the complex interplay of market forces at work.

The Green Revolution: Why Organic Milk is On the Rise

The organic milk sector is witnessing a notable surge, with a remarkable 9% increase in sales. This growth is a fleeting trend and an indicator of shifting consumer preferences. Why are more consumers reaching for that distinctive green label? The motivations predominantly revolve around perceived health benefits and environmental stewardship. Organic milk often boasts higher omega-3 fatty acid content and no synthetic hormones or antibiotics, making it an attractive option for health-conscious individuals.

Additionally, organic farms’ commitment to sustainable practices aligns with the growing consumer desire to reduce their environmental footprint. As we delve deeper, sales of specific products reflect this trend, with organic whole milk, reduced-fat (2%), and low-fat (1%) milk all showing year-over-year increases. This shift suggests a broader transition towards organic options, driven by nutritional awareness and ecological considerations.

Surging Ahead with Value-Added Dairy 

As consumer preferences evolve, the demand for value-added dairy products is carving a new niche within the market. This burgeoning category, marked by a 44% year-to-date increase, represents a shift in how consumers view and consume dairy. Products such as lactose-free milk and drinkable yogurts are leading this transformation, driven by their promise of health benefits and convenience. 

In an age where dietary restrictions and time constraints are commonplace, these value-added options offer solutions that traditional dairy products do not. Lactose-free milk caters to the lactose-intolerant demographic, ensuring they don’t miss out on the nutritional benefits of milk. Meanwhile, drinkable yogurts provide a quick, healthful alternative perfect for busy lifestyles. The function of these products goes beyond mere sustenance; they tap into contemporary health trends, offering probiotics, added vitamins, or reduced sugar variants that resonate well with health-conscious consumers. 

This trend is driven by necessity and an increased awareness of personal health and well-being. Consumers actively seek products that align with their dietary goals and lifestyle choices, leading to a diversification in dairy consumption. As shoppers lean towards these innovative products for added value, the industry must adapt, balancing traditional offerings with these new demands.

Riding the Wave: Opportunities and Challenges in the New Dairy Era

For dairy farmers and the industry, these evolving trends in fluid milk consumption present both opportunities and challenges. As consumers increasingly gravitate towards organic and other value-added fluid milk products, it signals a shift in market dynamics that could have profound implications for farm operations and profit margins. 

The uptick in consumption of whole and other ‘liquid’ milk products suggests a potential rise in demand for Class I milk, which could lead to higher producer milk checks. Higher demand incentivizes processors to allocate more milk to bottling rather than diverting it to manufacturing non-liquid dairy commodities. This shift could temporarily tighten milk supplies, consequently nudging prices upwards. For producers, this means adjusting production strategies to cater to this new demand while maintaining profitability. 

Moreover, the developing landscape encourages strategic recalibration in processing and price-setting approaches. Processing plants need to adapt their capacity to better handle the increased volume of fluid milk, particularly in categories seeing growth, such as lactose-free and other specialty products. Pricing strategies could also evolve, providing premiums for milk destined for these higher-value segments. This presents a challenge for the industry to adapt and innovate, ensuring that they can meet the changing demands of the market. 

For the savvy dairy farmer, the future seems ripe with opportunity. Focusing on producing milk that aligns with these trends could prove advantageous, potentially leading to higher revenues in a market slowly embracing diversity and quality over sheer volume. This shift in consumer preferences presents a promising opportunity for dairy producers to adapt and thrive. However, staying informed and responsive to these shifts will be key to navigating the ever-changing dairy landscape.

International Ripples: Navigating the Global Dairy Stage

The global dairy market is complex, and shifts and movements draw ripples across international borders. Recent indicators paint an intriguing picture. Notably, the Global Dairy Trade (GDT) Index marked a substantial 1.2% ascent—an unmistakable nod to the burgeoning demand revitalizing dairy economies worldwide. In particular, whole milk powder, a crucial commodity in the international dairy trade, surged to $3,984 per metric ton, achieving its highest valuation since mid-2022. 

This upward trajectory in global markets does not exist in a vacuum, and its repercussions extend deeply into domestic spheres. Rising global prices may lead to optimistic outcomes for dairy farmers at home. As international demand strengthens, it holds the potential to elevate milk prices locally, providing a more robust revenue framework for producers. Additionally, the increase in export opportunities could catalyze local markets, challenging them to meet swelling needs and adjust operational capacities. 

Yet, new complexities emerge as these global dynamics unfold. Enhanced prices can stimulate intensified domestic production, straining resources. Dairy farmers must remain vigilant, balancing the lucrative prospects with the implications for supply chain logistics, production costs, and sustainable practices. These intertwined global trends testify to the dairy market’s ever-evolving landscape, urging stakeholders to navigate with strategic insight and foresight.

The Bottom Line

While the ebb in traditional fluid milk sales might initially strike as a setback, it unveils an era rich with potential through burgeoning organic and value-added products. These areas are not merely bright spots but symbolic of a shifting tide in consumer preferences, charting a promising course for the dairy industry to explore and expand. As we navigate this evolving landscape, the question remains: will continued innovation and adaptation redefine the dairy aisle, or are these trends harbingers of a more profound transformation in how we perceive and consume dairy? The future beckons with possibilities yet to unfold.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

USDA Dairy Consumption Trends: Record Butter, Plummeting Ice Cream, and Shifting Milk Habits

Discover USDA dairy trends: record butter use, less ice cream, and shifting milk habits. What do these changes mean for the dairy industry?

Summary:

The USDA’s latest dairy data highlights significant shifts in consumption patterns, with Americans turning away from traditional fluid milk—now under 130 pounds per person—and embracing alternative dairy products. Cheese consumption has reached a new high, bolstered by interest in American and cottage cheese varieties. Butter demand has also surged, setting a new record that surpasses even pandemic-era levels. Conversely, ice cream has seen its worst performance on record, indicative of changing consumer preferences toward health-conscious alternatives. Meanwhile, whey protein concentrate (WPC) is gaining traction, driven by domestic and international nutritional value demands. To combat declining milk consumption and support overall dairy intake, the industry is enhancing milk’s nutritional profile and advocating for its inclusion in schools, particularly with organic options. These evolving trends require industry stakeholders to adapt strategically to thrive in a dynamic market environment.

Key Takeaways:

  • Milk consumption continues to decline, reaching under 130 pounds per person annually, marking the 14th consecutive year of decreases.
  • Cheese consumption is on the rise, setting another record in 2023, primarily driven by the popularity of American and cottage cheese.
  • Butter consumption has hit an all-time high since records began, despite the robust yet declining supply putting pressure on prices.
  • Ice cream consumption faces a significant drop, changing consumer preferences away from indulgent options.
  • Whey protein concentrates see increased demand domestically and internationally, with a positive outlook in market pricing.
dairy consumption trends, butter consumption record highs, ice cream consumption decline, fluid milk consumption drop, cheese consumption increase, USDA dairy initiatives, nutritional enhancements in dairy, health-conscious frozen desserts, market dynamics in dairy industry, consumer preferences in dairy products

Are we witnessing the dawn of a new dairy era? That’s the pressing question arising from the latest USDA data, a credible source showcasing eye-catching shifts in American dairy consumption. Butter has reached record highs, with two-stick lovers spreading more butter than ever before. But, in a move that could chill any dessert enthusiast, ice cream consumption has melted to an all-time low, signaling a turn towards less indulgent treats. Fluid milk, meanwhile, continues its steady decline, reflecting a broader shake-up in consumer preferences. These trends illuminate changing dietary habits and significantly affect the dairy industry’s future strategies. Dive into these findings to understand what they mean for producers and the market. 

Is Milk Getting Sour? A Paradigm Shift in U.S. Consumption Habits 

The decline in fluid milk consumption in the United States is not merely a passing trend but a long-standing shift that underscores significant changes in dietary habits. Historically, milk was a staple, celebrated for its nutritional richness, yet it has steadily lost favor over the decades. In 1985, the per-person milk consumption averaged significantly higher than today, as the decline began. Fast forward to 2023, and fewer American households view milk as a dietary necessity, reflected in a consumption dip below 130 pounds per person for the first time. 

This downward trend substantially impacts overall dairy intake, influencing nutritional imbalances. The USDA reports that 90% of Americans fail to meet the federally recommended daily intake levels, with dwindling milk popularity being a major contributing factor. This decline is most pronounced among teenagers, a demographic once pivotal to high milk consumption but now leading the charge in moving away from this traditional beverage. Since the early 2010s, teenage milk consumption has plummeted sharply, prompting concern within public health advocacy circles and the dairy industry. 

The dairy industry is revamping milk’s image to counter this trend through strategic nutritional enhancements. Efforts are underway to increase milk’s protein content while reducing fat and sugar levels, aiming to align milk with contemporary health trends. Moreover, incorporating probiotics seeks to bolster milk’s functional appeal, positioning it as more than just a drink but a health-boosting solution. In parallel, initiatives such as the recent USDA-backed program strive to expand milk offerings in schools, including organic varieties, to rejuvenate interest among younger consumers. These initiatives reflect a concerted push to redeem milk’s place in American diets, adapting the cornerstone of dairy amidst evolving consumer preferences.

Say Cheese! Americans Embrace a Dairy Delight Revolution

The upward trajectory of cheese consumption in the United States showcases an evolving palate and a keen interest in diverse cheese varieties. In 2023, Americans reached an unprecedented record of 42.3 pounds of cheese per capita, underscoring a significant year-over-year increase that reflects burgeoning enthusiasm for this dairy staple. Among the many factors driving this surge, two notable stars have emerged: American and cottage cheese. 

American cheese, a quintessential choice for burgers and sandwiches, continues to enjoy widespread popularity. Its versatile nature and familiarity make it a staple in households nationwide. Meanwhile, cottage cheese is enjoying a renaissance, captivating health-conscious consumers with its low-fat and high-protein profile. Often regarded as a wholesome snack, cottage cheese caters to those seeking nutrient-rich and satisfying dietary options. 

This shift in consumer preference towards healthier alternatives opens exciting growth avenues within the cheese market. As dietary trends lean more toward health, dairy companies have a rich opportunity to innovate and expand their offerings. Developing new variations of low-fat, high-protein cheeses can engage a growing segment of health-aware individuals eager for nutritious solutions without compromising taste. This innovation potential is a beacon of hope in the evolving dairy landscape.

Butter Boom: A Culinary Staple’s Historic Surge and Market Ripples

The year 2023 marked a remarkable chapter in the history of butter consumption in the United States. A combination of shifting consumer preferences and a robust supply chain culminated in a record-breaking figure, where Americans consumed an unprecedented 6.5 pounds of butter per capita. This milestone suggests a deeper connection between butter and the evolving patterns in domestic dietary habits. 

The pandemic’s amplified resurgence in home cooking played a pivotal role in boosting butter’s popularity. As more individuals found solace in preparing meals at home, the demand for kitchen staples, including butter, saw a significant uptick. This behavioral shift extended beyond the pandemic, becoming a sustained trend as consumers prioritize home-cooked meals, thereby maintaining high levels of butter usage well into 2023. 

However, the surge in butter demand can only stand with a strong backbone of supply. The U.S. dairy industry has demonstrated remarkable resilience by maintaining robust butter supplies, ensuring availability despite rising consumption. This resilience should reassure the industry of its ability to weather market fluctuations. Nonetheless, a slight dip in butter supply since May 2024 hints at tightening market conditions. This decrease has imparted pressure on butter prices, which, as per recent data, show grade AA butter trading at $5.495 per ton, reflecting a minor decline of 1.87% according to CLAL survey data from November 27, 2024. 

The economic implications of these consumption dynamics are multifaceted. On the one hand, the strong demand supports dairy farmers and producers by providing a steady market for their products. On the other hand, the fluctuating supply levels and subsequent price adjustments indicate a volatile market environment that requires strategic planning and foresight. Such market dynamics underline the need for dairy producers to remain agile, adapting to trends that blend tradition with modern consumption preferences, ensuring they thrive in a competitive landscape.

The Great Thaw: What’s Behind America’s Iced-Out Love Affair with Ice Cream?

As the sun sets on the once-vibrant tales of ice cream consumption in America, we’re left to ponder: why has this creamy delight seen its cold reception melt away? The plunge to historic lows in 2023 raises significant questions. First and foremost, consumer preferences are evolving. Health trends heavily influence dietary choices, increasing consumers scrutinizing sugar content and caloric intake. This shift is evident in the USDA’s data, which highlights a broader decline in the consumption of caloric sweeteners. 

Moreover, the allure of dessert indulgence is eclipsed by a growing affinity for health-conscious options. The steady ascent of non-dairy and lower-calorie alternatives hints at a market caught in the winds of change. Consider the burgeoning popularity of frozen yogurts, sorbets, and other less traditional options that cater to this health-savvy demographic. 

Speculating on future trends, the frozen dessert market may well pivot towards innovation that aligns with the wellness movement. We may see an uptick in products boasting natural sweeteners, plant-based ingredients, or added nutritional benefits. This potential for a rebirth in the frozen dessert market is an intriguing prospect, catering to consumers who still crave indulgence but demand health at its core.

Pumping Up the Protein: WPC’s Rise to Nutritional Stardom

The ascent of whey protein concentrate (WPC) within nutritional and food markets is driven by domestic appeal and global demand. The rise in WPC consumption, predominantly WPC34 and WPC80, underscores a burgeoning need for high-protein ingredients in food production. Domestically, health-conscious consumers increasingly opt for WPC due to its robust protein profile and versatility in diverse dietary applications. Internationally, improving sentiment, particularly from markets like China, amplifies this demand, spotlighting the importance of global trade dynamics in its trajectory. 

WPC34 is notable for its balanced composition, offering 34% to 36% protein and 48% to 52% lactose. It is suitable for incorporation in products where nonfat dry milk may traditionally be used, making WPC34 an attractive ingredient in baked goods and nutritional beverages. Meanwhile, WPC80, with its higher protein concentration of 80% to 82% and reduced lactose content, is favored in producing high-protein supplements and performance foods, catering to athletes and fitness enthusiasts seeking lean protein sources. 

From a market perspective, WPC’s growth outlook remains optimistic. According to the latest USDA AMS report, pricing is shifting upward, particularly for WPC34, reinforcing the strong market fundamentals narrative. Industry contacts report that the supply chain remains tight, with active trading despite slim inventories. Robust global demand and cross-border trade facilitation further boost this. This dynamic environment outlines a promising future for WPC, anchored by its nutritional merits and expansive application potential.

The Bottom Line

The latest USDA dairy consumption data presents a fascinating snapshot of shifting consumer habits. Butter has soared to new heights, capturing Americans’ kitchens more than ever. Meanwhile, milk is experiencing a prolonged downturn, with consumption levels consistently dipping. Ice cream is experiencing an unprecedented chill in popularity, reflecting a pivot away from high-calorie pleasures. 

For dairy professionals, these trends raise critical questions: How can we align with changing consumer preferences? Will the surge in butter consumption propel further innovations or invite a price recalibration? What opportunities exist to revitalize the appeal of milk? Should the decline in ice cream consumption prompt a diversification into alternative dairy indulgences? 

The broader implications for the dairy industry loom as we contemplate these trends. Strategic adaptation is imperative. Leveraging insights from these trends could unlock new pathways for growth. Are you ready to seize these opportunities and reimagine your business to align with the evolving market landscape? The time to act is now.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Global Dairy Market Dynamics: Unveiling Shifts, Challenges, and Opportunities

Uncover recent changes in the dairy market. Are you prepared to tackle challenges and find new opportunities? Gain insights for dairy experts.

Summary:

The global dairy market is a dynamic landscape marked by fluctuations and trends that ripple across continents, with trading hubs like the European Energy Exchange (EEX) and Singapore Exchange (SGX) reflecting these economic currents. EEX saw butter and skimmed milk powder (SMP) transactions dominate a softened market, while SGX recorded robust trades in whole milk powder (WMP), indicating firmer Pacific demand. European firms report mixed results with rising butter and whey prices but faltering cheese indices. Dominated by key players such as Nestlé, Danone, Lactalis, and Fonterra, the sector maintains extensive supply chains across North America, Europe, and Asia-Pacific. Technological advancements in farming and processing enhance efficiency and quality. Despite challenges like fluctuating commodity prices and evolving regulations, the dairy sector’s resilience is evident. Europe grows steadily, China falters, and Australia ascends, highlighting a mixed global dairy dynamic where Dutch milk collections fell by 1.6% year-over-year.

Key Takeaways:

  • EEX witnessed considerable trade activity with a noticeable shift in butter and SMP futures, indicating market softness for butter and slight volatility for other dairy products.
  • SGX trading showed strength in WMP and SMP futures, reflecting global demand resilience despite minor fluctuations in AMF and butter prices.
  • European dairy quotations experienced a positive week, with most product prices rising, suggesting a firming market that’s surpassing last year’s figures.
  • Cheese indices in Europe presented a declining trend, although current prices remain significantly higher than those of the previous year, indicating a complex market situation.
  • Fonterra’s GDT auction results highlighted an uptick in C2 WMP, showcasing continued demand in the global market and strategic supply adjustments.
  • Milk collection data revealed growth in some regions like Australia and the UK, while others like the Dutch market showed contractions, pointing to varied regional developments.
  • The US dairy sector faces a paradox of diminishing cheese inventories but falling prices, hinting at potential upcoming price corrections as demand catches up with supply.
dairy market trends, global dairy industry, Nestlé Danone Lactalis Fonterra, dairy supply chains, North America Europe Asia-Pacific dairy, technological advancements in dairy, climate change dairy sector, European Energy Exchange dairy trading, China Australia dairy market, milk production statistics

The global dairy market is in constant flux, shaped by many factors ranging from fluctuating global trade volumes to evolving consumer preferences. As we examine the latest data and trends, it becomes evident that the dairy industry is undergoing significant shifts with volatile prices, varying production rates across regions, and continuously morphing market demands. This underscores the importance of staying well-informed, as it allows dairy professionals to tackle challenges and capitalize on newfound opportunities, distinguishing leaders from followers in this ever-evolving landscape.

Milking the Market: The $700 Billion Dairy Revolution

The global dairy market continues to demonstrate its critical economic role. As of the latest reporting period, its valuation exceeded $700 billion, a testament to its immense scale and potential for growth. Forecasts predict continual growth, further underlining the market’s significance. Key players such as Nestlé, Danone, Lactalis, and Fonterra dominate this dynamic sector, driving innovation and maintaining extensive global supply chains that cater to diverse consumer needs across continents. 

Major markets span North America, Europe, and Asia-Pacific, contributing significantly to global consumption and production patterns. Europe is a powerhouse in dairy production, with countries like Germany, France, and the Netherlands leading output. At the same time, North America remains a leader in technological advancements and processing capacity. Meanwhile, Asia-Pacific, particularly China and India, is witnessing rapid growth due to rising consumer demand and expanding middle-class populations. 

Recent trends indicate a shift towards healthier and sustainable products as consumers become increasingly health-conscious and environmentally aware. Consequently, the popularity of organic and plant-based dairy alternatives has increased significantly, reshaping industry demand dynamics. Technological advancements in farming and processing are also pivotal, enhancing efficiency and product quality across the supply chain. 

The dairy sector‘s resilience and adaptability are reflected in its capacity to navigate challenges such as fluctuating commodity prices, evolving regulatory landscapes, and climate change impacts. These regulatory changes include [specific examples], which are reshaping the industry’s operations and strategies. With the ongoing integration of digital solutions, the industry is poised for further transformation and growth, ensuring its continued prominence in the global economy.

Trading Titans: Unveiling the Dairy Market’s Pulse through EEX and SGX

Recent trading activities on the European Energy Exchange (EEX) and Singapore Exchange (SGX) illustrate significant market dynamics in the dairy industry and offer keen insights into investor sentiment and market expectations. 

Last week’s EEX trading highlighted shifts across various dairy products. Four thousand three hundred forty tonnes were traded, with notable activity in Butter and Skimmed Milk Powder (SMP), which accounted for 2,365 and 1,975 tonnes, respectively. Thursday marked a high point with 2,620 tonnes exchanged. The EEX Butter futures exhibited a softening trend for the third consecutive week, with the December 2024 to July 2025 strip averaging €6,888, a 3.7% decrease. Conversely, open interests increased by 329 lots to 3,329, suggesting heightened investor involvement despite price reductions. SMP at EEX saw a minor dip of 0.4%, settling at an average of €2,772, with open interest up by 263 lots to 6,089. These patterns suggest a cautious market approach, where traders respond far beyond pricing signals, potentially speculating on future shifts. 

In contrast, SGX’s dairy trade displayed resilience, with 22,285 tonnes traded overall. Whole Milk Powder (WMP) drove the activity, with 15,577 tonnes exchanged, while SMP traded 6,645 tonnes. The firming of SGX WMP across the December 2024 to June 2025 curve, with a 2.2% price increase to $4,002, reveals bullish sentiment. SMP’s slight rise of 0.7% to $3,060 reinforces a subtle positive outlook as these commodities recover from previous lows. With Anhydrous Milk Fat (AMF) slightly declining by 0.2% and Butter edging by 0.4%, market confidence appears cautiously optimistic, preparing for potential upward trends driven by global demand. 

These trading patterns point towards a nuanced market sentiment. EEX indicates readiness for future bullish scenarios despite current soft prices, while SGX reflects growing confidence bolstered by demand expectations. The shifts across these exchanges underscore a balancing act between market cautiousness, where traders respond far beyond pricing signals, and strategic anticipation of future demand surges. This mindset is crucial for successful dairy market trading, as it allows traders to navigate current market conditions while preparing for potential future shifts.

Global Dairy Dynamics: Europe Steadies While China Falters and Australia Ascends 

The European Dairy Market has a mixed landscape. Although the prices of certain products like Butter and WMP are rising, as seen in EU Quotations, which show a gain of €47 for Butter, Dutch milk collections experienced a setback, with a 1.6% year-over-year decrease in October. The cumulative milk collections for 2024 show a downturn of 1.9% compared to the previous year. This decline highlights the ongoing challenges of balancing production with market demand, a critical factor for dairy farmers maneuvering amidst fluctuating pricing dynamics. 

In China, the scenario presents a different picture. The farmgate milk price for November was reported at 3.12 Yuan/Kg, a slight decline of 0.4% month over month. This price is significantly 15.7% lower than the previous year. This downturn speaks to broader economic challenges, including fluctuating demand influenced by domestic consumption patterns and international trade relations. 

The UK‘s dairy sector is showing an encouraging trend. Milk production in October stood at 1.25 million tonnes, up a notable 2.8% year over year. Despite a slightly decreased growth revision for September, the cumulative results for the year indicate a positive trajectory, indicating robust domestic demand and efficiency improvements—the increase in milk solid collections by 3.8% year over year further underlines potential resilience in the market. 

Australia appears to be on a solid upward path, with October milk collections up by 1.2% year-on-year. The cumulative milk collections for 2024 saw a 3.1% increase, reflecting positive momentum likely driven by favorable weather conditions and strong export demand. The milk solid collections for October, increasing by 1.7%, add to this optimistic outlook for Australian dairy producers. 

In the US, the dairy market is navigating contrasting dynamics; despite a consistent decrease in total natural cheese stocks, prices have also been falling for five consecutive weeks. Cheese stocks saw a significant reduction of 8.0% from the previous year. This deviation between stocks and prices suggests a lagging market reaction, and the industry might anticipate a price rebound as supply-demand paradigms realign. With component prices expected to adjust marginally, US farmers and producers must stay vigilant to potential market shifts.

Navigate the Churn: Turning Dairy Market Challenges into Opportunities

The global dairy industry faces many challenges that could reshape operations and strategies for many involved in this vital sector. One of the most pressing issues is fluctuating prices, as evidenced by the recent EEX and SGX futures market data. For instance, butter futures on EEX experienced a 3.7% decline, while SGX showed volatility of 2.2% in WMP prices over a week. Such fluctuations can make it difficult for dairy producers to plan effectively and impact profitability. Stakeholders must consider how these price swings can affect their bottom lines and potentially lead to financial instability. 

Another significant challenge is supply chain disruptions. Recent global events have underscored the fragility of supply chains, particularly in the dairy sector, where the timely transportation of perishable goods is critical. Disruptions can lead to delays, increased costs, and even spoilage, impacting consumers’ product availability and causing significant revenue losses. How are your operations fortified against such potential disruptions? 

Lastly, changing consumer preferences poses a continual challenge. Consumer tastes are shifting with increasing demand for plant-based alternatives and more sustainable production methods. This evolution requires dairy producers to adapt quickly, potentially altering production processes, investing in sustainable practices, or diversifying their product offerings to meet consumer demand. As a professional in the dairy industry, are you prepared to pivot strategies to align with these evolving consumer expectations? 

Given these challenges, dairy farmers and associated professionals must remain agile, keeping a pulse on market trends and being prepared to adapt strategies. How will these challenges impact your operations, and what steps can you take to mitigate risk and capitalize on emerging opportunities?

Seizing the Udder Side of Innovation: Embrace Change, Harness Potential

As the global dairy market experiences dynamic shifts, opportunities abound for those ready to innovate and adapt. Emerging markets are one of the most promising areas, where rising urbanization and increasing disposable incomes create new demand for dairy products. Asia, particularly Southeast Asia and parts of Africa, is seeing a growing appetite for diverse dairy offerings. Dairy professionals might consider expanding into these markets and customizing products to local tastes and nutritional needs. 

Technological advancements are further paving the way for transformative opportunities. Technology is revolutionizing dairy from farm to fork, from precision farming techniques that optimize milk production to AI-driven data analytics that enhance supply chain efficiency. Innovations such as automated milking systems, robotic milkers, and advanced genetic selection are making operations more efficient, reducing labor costs, and improving yields. 

Sustainable practices in dairy farming are not just necessary due to climate change concerns; they are also an opportunity to lead in environmental stewardship. Utilizing renewable energy resources, implementing water conservation techniques, and reducing methane emissions through feed additives can enhance a dairy operation’s sustainability profile. These strategies help meet regulatory requirements and appeal to environmentally conscious consumers who support green dairy brands. 

Moreover, product innovation presents a substantial opportunity for growth. With consumers increasingly seeking health-conscious food options, developing dairy products with added nutritional benefits or functional properties, such as probiotics, could tap into burgeoning health trends. Engaging with consumer feedback through digital platforms can offer valuable insights into market demands and guide product development. 

In summary, the future of dairy is ripe, and there is potential for those who are prepared to seize these opportunities. By strategically navigating emerging markets, leveraging advanced technology, adopting sustainable practices, and spearheading product innovation, dairy professionals can secure a brighter future for their operations and drive the industry into a new era of growth and resilience.

The Bottom Line

The global dairy market displays a complex tableau of opportunities and challenges. European markets are seeing variable trajectories, from strengthening Butter and whey indices to decreasing cheese prices, reflecting evolving demand and economic pressures. Meanwhile, China faces declining domestic milk prices, pointing towards potential shifts in consumer behavior. At the same time, Australia shows upward trends in milk production, hinting at a possible expansion in market share. The US market suggests a potential pivot point with decreasing cheese stocks yet falling prices, indicating potential future shifts in supply strategies. 

As we navigate these intricate dynamics, the question beckons: How are you positioning yourself and your enterprise within this multifaceted global dairy landscape to endure and thrive? The ever-changing market necessitates a proactive approach, harnessing innovation and adaptability. Are you ready to seize the udder side of opportunity and channel this period of change into growth and success? 

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

New Zealand Dairy Production Soars: Record-Breaking Milk Solids and Market Opportunities

Explore New Zealand’s dairy boom and strategic market moves. Ready to seize the growth?

Summary:

New Zealand’s dairy sector shines with a 2.1% year-over-year rise in October output, hitting nearly 6.8 billion pounds and bolstered by a 2.8% increase in milk solids. This growth trend provides stability despite market fluctuations. Fonterra forecasts a lucrative $9-$10 per kgMS, surpassing the $9.30 peak of 2021-22, showcasing a robust outlook. Strategically, Fonterra plans to exit its global consumer business to focus on food service and ingredient sales, alongside divestment from Fonterra Oceania and Sri Lanka, thus enhancing core operations and aligning with global demand. This repositioning promises a strong influence on international markets, paving the way for sustainable long-term growth and greater profitability through reinvestment in advanced farming practices and operational efficiencies.

Key Takeaways:

  • New Zealand’s dairy production has significantly increased, showing strong year-over-year output and milk solids growth.
  • The rise in Fonterra’s farmgate milk price promises improved profitability for local farmers, with current forecasts exceeding past all-time highs.
  • Fonterra is refocusing its business strategy towards food service and ingredients while divesting from its global consumer business, which may create new market opportunities.
  • Global market conditions, such as slowing European milk production and recovering U.S. output, provide favorable export prospects for New Zealand producers.
  • Recent increases in whole milk and skim milk powder prices at the Global Dairy Trade Pulse event highlight a growing global demand for New Zealand dairy products.
  • Ongoing global uncertainties present risks and opportunities for New Zealand’s dairy industry, emphasizing the need for continued innovation and strategic adaptation.
New Zealand dairy sector, October output rise, Fonterra forecasts, milk solids increase, dairy market stability, global consumer business exit, food service focus, ingredient sales growth, international market influence, sustainable long-term growth.

New Zealand’s dairy industry continues to break boundaries, posting stellar production figures that set new benchmarks for milk solids. With an impressive 2.8% year-on-year increase in October alone, kiwi farmers are not merely keeping afloat but are sailing ahead with robust numbers. This remarkable growth has carved out potential market opportunities. New Zealand has the capacity and the motive to influence global trade dynamics significantly. But what does this mean for the global dairy market? Let’s delve into the ramifications of this surge and how New Zealand’s dairy prowess could reshape the industry’s future. 

Month2023 Milk Production (Million Pounds)2024 Milk Production (Million Pounds)Percentage Change (%)
June1,2001,2352.9%
July1,3151,3553.0%
August1,5901,6463.5%
September1,7501,7982.7%
October1,9001,9402.1%

Moo-ving Forward: New Zealand’s Dairy Upsurge Propels Industry to New Heights 

New Zealand’s dairy industry is demonstrating robust growth, as evidenced by the recent production statistics. The industry is experiencing a notable 2.1% year-over-year increase in output, with collections closing in on an impressive 6.8 billion pounds. This uptick aligns with October being the peak month in New Zealand’s dairy calendar, which runs from June to May. Additionally, season-to-date production shows an encouraging 4.1% increase compared to the same period in the previous 2023-24 season.

The 2.8% year-over-year rise in milk solids in October is essential to this growth. Given that New Zealand dairy producers receive compensation based on milk solids, this increase translates directly into enhanced profitability. The rise in milk solids is even more significant as it ensures farmers gain financially, notwithstanding potential fluctuations in raw milk volumes or market demand. Consequently, these production gains highlight the strength of New Zealand’s dairy capabilities and ensure its producers’ financial sustainability and competitiveness in international markets.

Fonterra’s Bold Step: Empowering Kiwi Farmers Amidst Global Market Shifts

Fonterra’s recent decision to elevate the farmgate milk price to $9-10/kgMS is a strategic move that holds substantial significance for dairy farmers. This adjustment reflects the buoyant production metrics and robust market demand. It amplifies the producers’ confidence in sustaining and potentially increasing profitability. In an environment where farm margins are critically dependent on milk prices, this increment is poised to offer a tangible boost. With the midpoint of the forecasted price increasing by 50¢ from the previous estimate, it signifies a shift towards unprecedented highs, surpassing the earlier peak of $9.30/kgMS recorded in the 2021-22 season. 

Elevated milk prices and reduced third-quarter operating expenses form a promising financial outlook for New Zealand dairy farmers. Lower costs, when aligned with higher revenues from milk sales, inherently lead to improved farm margins. This financial cushioning allows farmers to reinvest in advanced farming techniques, elevate dairy herd health, and optimize operational efficiencies, ultimately contributing to sustainable long-term growth. 

Contextually, Fonterra’s moves are not isolated phenomena but embedded within a broader historical framework that underscores a commitment to maintaining a competitive edge in the face of global market fluctuations. As dairy farmers navigate these economic shifts, the industry’s trajectory towards stable, if not enhanced, profitability becomes clearer, potentially inspiring similar strategies in other milk-producing nations.

Redefining Success: Fonterra’s Strategic Shift Towards Profitable Niches

Fonterra’s decision to pivot away from its global consumer business and focus on food service and ingredient sales marks a significant strategic shift aimed at streamlining operations and boosting profitability. By concentrating on these areas, Fonterra can leverage its expertise and resources more efficiently, capitalizing on the growing global demand for food service products. 

Divesting from Fonterra Oceania and Fonterra Sri Lanka presents a significant move that could reshape the company’s operational landscape. The potential impacts of this divestiture include a more focused business model and the opportunity to allocate capital and management effort to the more profitable segments of food service and ingredient sales. This shift is expected to enhance the company’s capability to compete and innovate within these targeted markets, which are experiencing robust growth. 

As indicated by CEO Miles Hurrell, the exploration of sales or IPOs as divestment options showcases Fonterra’s strategic foresight in ensuring that these businesses can attract the right kind of investment for growth. A sale could provide immediate liquidity and streamline the company’s focus. At the same time, an IPO might offer a platform for these businesses to grow independently, tapping into capital markets to finance future expansions and innovations. Each option has pros and cons, and Fonterra’s choice will likely hinge on current market conditions and long-term strategic goals.

Carving Out a Niche: New Zealand’s Strategic Positioning Amidst Global Dairy Dynamics

The global dairy landscape is undergoing a pivotal transition, marked by a significant deceleration in European milk flows and the nascent recovery of U.S. dairy production. This dynamic shift presents a singular opportunity for New Zealand producers to leverage their robust output. With European supply dwindling, markets that typically depend on these sources are now gazing towards the Southern Hemisphere. 

Simultaneously, while U.S. production shows the first signs of rekindled growth, it remains insufficient to satiate the burgeoning global demand for dairy products, particularly in regions heavily reliant on imports. Consequently, with its intensified production and increased milk solids, New Zealand stands poised to fill this void, offering competitive, quality options in global markets. 

Such conditions are particularly advantageous when juxtaposed with New Zealand’s low operational costs and recent farmgate price elevations. These factors. Ensure that Kiwi farmers can profit from the rising international demand. Ultimately, these factors weave a narrative of opportunity, positioning New Zealand at the forefront of global dairy exports and potentially solidifying its status further as a leader in dairy excellence.

GDT Pulse: New Zealand’s Dairy Gains Momentum Amid Global Demand Surge

The recent Global Dairy Trade (GDT) Pulse event delivered promising results for New Zealand’s dairy export potential, showcasing significant price increases. Whole milk powder (WMP) surged to $3,910/MT, reaching its highest level since July 2022, while skim milk powder (SMP) settled at $2,895/MT, reflecting an upward trend from the previous week’s GDT auction. These escalations suggest a robust demand for New Zealand’s dairy products internationally. 

These developments are more than just promising for New Zealand producers—they’re transformative. As European and U.S. milk production shows signs of slowing, New Zealand is strategically positioned to capture more market share in the global dairy arena. The nation’s ability to meet increased demand with competitive pricing strengthens its foothold internationally. The favorable prices improve farmgate returns and provide an impetus for New Zealand to bolster its export capabilities. This positions Kiwi farmers uniquely to capitalize on shifting market dynamics, driving growth and profitability amidst fluctuating global supply conditions. 

These trends indicate a pivotal shift in the broader context of the global dairy market. Rising demand and price enhancements set a new tone for the global dairy trade, potentially reshaping sourcing strategies for significant importers. As New Zealand leverages these opportunities, it underscores its role as a critical player in the ever-evolving dairy production and trade world.

The Bottom Line

New Zealand’s dairy industry is experiencing success, as shown by the remarkable increase in output and milk solids and Fonterra’s strategic realignment to focus on more profitable segments. With reduced expenses and a high farmgate milk price, New Zealand producers are ideally positioned to expand their reach in export markets, particularly given favorable global economic conditions. 

As markets shift and new trade dynamics emerge, Kiwi farmers and industry players must remain vigilant, balancing profitability with sustainability and adaptability. Innovation will be vital in maintaining competitive advantage amidst changing consumer preferences and environmental pressures. 

As you reflect on these developments, consider how your operations will evolve to navigate these changes and what role New Zealand’s robust dairy sector will play in shaping the future of global dairy markets.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

China Intensifies EU Dairy Probe Amid Growing Trade Tensions

Uncover China’s expanded scrutiny into EU dairy subsidies amid trade tensions. What does this mean for dairy farmers and the global market? Find out more.

Summary:

Amid global trade tensions, China’s deeper dive into the EU’s dairy subsidies marks a pivotal moment in international commerce. By probing additional subsidy programs from major EU dairy players like Denmark, France, Italy, and the Netherlands, China keeps its sights on cheese, milk, and cream imports. This move, spurred by EU tariffs on Chinese electric vehicles, underscores a nuanced negotiation where dairy and electric sectors reassess cross-border strategies. As China’s investigation spotlights subsidy schemes that might skew the dairy market, potential disruptions loom over EU exports, prompting strategic recalibrations. With the EU as China’s second-largest dairy supplier, the investigation’s outcomes could alter trade dynamics significantly. Louise Perrin, CEO of EuroDairyCorp, voices urgency over the probe’s capacity to shift export dynamics.

Key Takeaways:

  • China has expanded its anti-subsidy investigation into EU dairy imports, including subsidy programs from multiple EU countries.
  • The investigation intensifies following recent EU tariffs on Chinese electric vehicles, suggesting potential trade tensions.
  • Despite the broadened probe, no new dairy products are being examined, indicating a focused approach to existing imports.
  • The EU is China’s second-largest dairy product supplier, highlighting these imports’ economic significance.
  • China’s commerce ministry actively engages with EU representatives, indicating a desire for dialogue during the investigation.
China EU trade tensions, dairy imports investigation, EU tariffs Chinese EVs, China automotive industry protection, EU dairy exports impact, skimmed milk powder import, dairy subsidy scrutiny, trade dynamics shifts, EuroDairyCorp CEO insights, competitive landscape dairy trade

Trade winds have become a storm, with tensions between two economic powerhouses—China and the European Union. The battlefield? An unexpected yet pivotal segment: the dairy industry. “The world’s second-largest economy launched the investigation into imports of some cheese, milk, and cream from the EU in August,” a recent report highlights, underscoring the gravity of the situation [Reuters]. With the investigation now encompassing additional subsidy programs in nations like Denmark, France, Italy, and the Netherlands, accusations of unfair advantages have sent ripples through an embroiled trade relationship. This move not only heightens the stakes within the sector but also raises an essential question: What does this mean for the future of international dairy trade? Are we witnessing the dawn of a reshaped dairy trade landscape?

A Milky Skirmish: When Cheese Meets Electric Sparks 

The tension began brewing in August when China initiated an extensive probe into the influx of EU dairy goods, focusing specifically on cheese, milk, and cream. This was a strategic maneuver in response to the EU’s imposition of protective tariffs, which reached up to 45.3%, targeting Chinese electric vehicles. These tariffs, which kicked in at the end of October, were part of a broader European strategy to shield its automotive industry from the burgeoning prowess of Chinese EV manufacturers. This sector is a significant contributor to the EU’s economy. Yet, they sparked what some describe as a tit-for-tat economic skirmish. 

In retaliation, China has scrutinized EU dairy imports significantly, considering that the EU is China’s second-largest supplier of dairy products, just behind New Zealand. The trade lanes are robust, with China ranking as the second-largest importer of skimmed milk powder globally and holding the fourth position for both butter and whole milk powder. These statistics underline the critical nature of the dairy trade between the two economic behemoths and the delicate balance they strive to maintain amid rising trade tensions.

A Broader Focus: China’s Probe Reaches New Depths 

The latest twist in the China-EU dairy saga has expanded China’s investigative lens, now honed on subsidy programs spanning Denmark, France, Italy, and the Netherlands. This development wasn’t plucked from thin air. It emerged from a formal request from China’s dairy sector, a keystone in the global dairy supply chain, highlighting specific subsidy programs perceived as distorting the competitive landscape. The rationale? China’s strategic move came from rigorous consultations with EU representatives, setting the stage for further scrutiny. 

So, what’s new on the radar? These subsidies are now under scrutiny for potentially distorting the competitive landscape of the dairy trade. By including these specific programs, China aims to dissect their impacts and question whether they tilt the playing field unfairly against its domestic industry. 

The stakes are high. If the investigation surfaces significant distortions, the ripple effect could jeopardize EU dairy exports, igniting shifts in trade dynamics and sectoral strategies. Will it precipitate a tilt in the trade winds or foster a new era of dairy diplomacy? It remains to be seen, but the dairy world watches, curiously holding its breath.

Balancing Act: EU Dairy’s Tightrope Walk Amid Sino-Euro Tensions 

EU dairy producers and trade experts are monitoring the situation with urgency and concern. The expanded scope of China’s investigation has sparked significant conversation within the industry. A leading figure in the EU dairy sector, Louise Perrin, CEO of EuroDairyCorp, expressed her concern: “This probe could redefine our export dynamics. We’ve relied on China as a critical market, and any shift could profoundly recalibrate our strategies.” 

Trade analysts quickly highlight the potential political maneuvering at play. “China’s response is a retaliatory move to the EU’s tariffs on Chinese EVs, a sign of growing tensions in the EU-China trade relationship,” remarks Dr. Hans Vogel, a senior analyst at the European Trade Institute [Source Needed]. He adds, “While the immediate impact might see disruptions in trade flows, the long-term ramifications could compel the EU to reconsider its subsidy frameworks.” 

From an economic standpoint, experts anticipate a ripple effect across European and Chinese markets. “The probe could lead to stricter scrutiny, potentially impacting the competitiveness of EU dairy products abroad,” says economist Jocelyn Wright, who specializes in international trade. However, this could also pave the way for greater transparency and reform within EU subsidy policies, offering a glimmer of hope for a more level playing field. 

Politically, the situation underlines an increasingly strategic dance between two major economic powers. As tensions simmer, stakeholders across both regions are urged to consider the broader implications. “It’s more than just about dairy,” concludes Perrin. “It’s emblematic of a larger geopolitical chess game that could influence policy decisions and trade norms for years to come.” This ‘chess game’ could potentially lead to shifts in global trade dynamics and the formulation of new trade policies, impacting the dairy industry and the broader international trade landscape. 

Steering Through the Churn: EU Dairy’s High-Stakes Odyssey 

As China’s scrutiny intensifies, dairy farmers across the EU are treading uncertain waters. The expanded investigation threatens to shake the foundation of a market upon which many in the industry rely. At the forefront is the question: How will this heightened focus affect the dairy farmers and businesses dependent on the intricate trade relations between the EU and China? 

First, let’s consider market dynamics. This investigation could increase scrutiny of subsidies, potentially curbing these programs’ competitive edge over EU producers. As China delves deeper, dairy farmers might navigate stricter regulatory landscapes, significantly influencing production and export timelines. The ripple effects may resonate through the supply chain, from farmstead to distributor. 

Pricing is another battlefield. Trade tensions often translate to price volatility. Should China’s actions result in reduced import volumes or increased tariffs, the immediate consequence could be a surplus of dairy products within the EU. This glut may depress prices domestically, forcing farmers to strategically consider cost management and efficiency improvements. Here, innovation and agility become indispensable allies. 

Lastly, consider export opportunities. Europe’s dairy farmers have long viewed China as a lucrative market. However, with the ongoing investigation, diversification may be a choice rather than a necessity. Seeking alternative markets could buffer against potential losses. This pivot could encourage farmers to explore partnerships in burgeoning regions tailored to absorb what might have been earmarked for China. 

How prepared are you in these tumultuous times? Every stakeholder must ask this question. Cooperation, forward-thinking strategies, and adaptability are not just options but necessities in these times. The dairy industry must reimagine its approach, embracing resilience and innovation to navigate these charged waters.

The Bottom Line

As China casts a broader net on EU dairy subsidies, this probe uncovers layers of intricacy in the global dairy market. With European entities facing heightened scrutiny, the repercussions may ripple through trade corridors across continents. Amid this brewing storm, what we’re witnessing is not just a tussle over butter and cheese—it’s the entanglement of strategic industries. The EU and China stand at a critical juncture. This probe might reshape the dynamics not only of their dairy sectors but also of their broader economic interactions. Could this be the beginning of a new era in the international dairy trade or another chapter in the ongoing trade tensions? The stakes have never been higher.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Global Dairy Markets: Profit Strategies Amid Tariff Tensions

Uncover global dairy trends and tariff threats. Learn how these factors can affect your profits and find strategies to adapt.

Summary:

The November 2024 scenario in the dairy industry reveals critical shifts requiring close attention, especially the buoyant international exports from New Zealand to China amidst perplexing U.S. trends where cheese and butter stocks remain low, yet prices fall. The looming specter of fresh tariffs from President-Elect Trump heralds a challenging future for U.S. dairy exports, especially with critical partners like Mexico, Canada, and China. Monitoring the evolving trade policies and understanding supply-demand dynamics will be crucial. As stated, “The dairy market is riding a wave of unexpected variables, from international export successes to domestic pricing puzzles, all under geopolitical uncertainties.” With a 42.8% YoY surge in New Zealand dairy exports to China and a 2.9% rise in Whole Milk Powder prices, global dynamics present both opportunities and challenges. However, U.S. cheese and butter stocks’ low levels remain unmoved in price terms on the CME spot market, prompting producers to be vigilant of geopolitical developments and consumer behavior to adjust strategies accordingly.

Key Takeaways:

  • New Zealand’s dairy exports are robust, with a notable increase in shipments to China, highlighting strong demand.
  • The GDT Pulse reflects positive trends, with Whole Milk Powder (WMP) prices seeing a measurable rise compared to the previous GDT Event.
  • U.S. cheese and butter stocks for October were lower than anticipated, pointing to better-than-forecasted consumption or exports.
  • CME dairy markets will observe a holiday closure; this may affect short-term trading and pricing dynamics.
  • Potential tariff threats by President-Elect Trump could reshape trade networks, particularly impacting U.S. whey exports to China if retaliatory tariffs are imposed.
  • Despite stock depletion, U.S. cheese and butter prices are not aligning with historical patterns, suggesting atypical market influences.
  • Strategic planning is essential for dairy businesses to mitigate risks associated with potential trading shifts due to tariff implementations.
dairy market trends, New Zealand dairy exports, Whole Milk Powder increase, global dairy demand, U.S. dairy market challenges, cheese and butter prices, international trade tensions, President-Elect Trump tariffs, whey product exports, dairy industry opportunities

The global dairy market presents opportunities and challenges, evolving with every trade deal and stock report. October’s statistics have caught attention: New Zealand’s dairy exports to China surged 42.8% yearly, highlighting strong demand, while U.S. cheese and butter stocks unexpectedly dropped. How will these shifts impact your bottom line? As we navigate these market changes, the critical question for every dairy farmer and related business is: Are you ready to adapt and thrive in this new landscape?

Riding the Dairy Wave: Navigating Opportunities and Challenges in a Changing Market 

Despite its mixed nature, the current global dairy market is a resilient and dynamically evolving landscape that demands attention from dairy farmers and industry stakeholders. 

New Zealand, a powerhouse in dairy exports, has shown remarkable strength in its shipments, particularly with a 42.8% year-over-year increase to China. This substantial growth underscores China’s enduring appetite for high-quality dairy products and New Zealand’s capacity to meet this demand effectively. Such robust export performance bolsters New Zealand’s dairy sector and positions it as a pivotal player in global dairy trade dynamics. 

The latest GDT Pulse result, which reported a 2.9% increase in Whole Milk Powder (WMP) compared to the previous GDT Event, further complements this scenario. These figures indicate a resilient demand trajectory, which benefits dairy producers with higher market rates and confidence in international demand. 

These trends present both opportunities and challenges for dairy farmers and industry professionals. On the opportunity front, strong export figures and firm GDT indices suggest a healthy global demand, providing a promising market environment for progressive dairy ventures. 

In conclusion, staying informed and adaptable as global dairy markets shift remains crucial for stakeholders who want to capitalize on emerging trends and sustain their competitive edge. This knowledge empowers you to make informed decisions and navigate the market effectively.

Decoding the Enigma: Why Lower U.S. Dairy Stocks Aren’t Boosting Prices

The U.S. dairy market presents a perplexing scenario where cheese and butter stocks, expected to boost prices due to their lower-than-anticipated levels, have yet to translate into anticipated gains on the CME spot market. U.S. cheese stocks were 32 million pounds beneath forecasts in late October, marking an 8% reduction from the previous year. Traditionally, such figures suggest CME cheese prices climb to around $2.00. However, a prevailing trend draws the market towards a price point closer to $1.70. This disparity can be attributed to several complex factors that affect the U.S. market and have implications for the global dairy market. 

A crucial component lies in the interplay between supply dynamics and broader economic forces. Despite reduced stock levels, the economic outlook remains a substantial concern. The anticipation of increased tariffs from the President-elect may have fostered apprehension about export potential and overall market health, prompting caution among buyers and a downward pressure on prices. Additionally, the availability of cream and a well-supplied retail sector have muted any aggressive upward movements in butter prices despite the ten-million-pound stock shortfall in October. 

Dairy producers must prepare for a potential shift in this delicate balance. The outlook suggests that if international trade tensions ease and consumer demand ticks upward during the holiday season, there may be opportunities for price stabilization or growth. Thus, producers should monitor geopolitical developments and consumer behavior to pivot strategies should market signals change. Monitoring such trends is essential for navigating potential price fluctuations strategically, ensuring that dairy businesses can maintain profitability amidst economic uncertainties.

When Trade Winds Shift: Navigating the New Tariff Terrain in the Dairy Sector

President-Elect Trump’s proposed tariffs on Mexico, Canada, and China present a significant turning point in international trade dynamics, particularly for the U.S. dairy sector. Such measures generally herald heightened trade tensions, which can invariably lead to retaliatory tariffs from the targeted countries, thus profoundly affecting the U.S. agricultural landscape. 

The most immediate impact could be seen in the U.S. dairy exports to China. Most of these exports comprise whey products, so a trade war ramping up could significantly strain this particular corridor. Whey, highly valued in China’s food and nutrition markets, faces the highest downside risk due to a potential increase in duties, which could render U.S. exports less competitive relative to other whey-producing nations. As demand in China grows, Chinese companies could turn toward alternative suppliers, potentially from Europe or New Zealand, which maintain favorable trade conditions with China. 

Moreover, the imposition of tariffs can reverberate through broader U.S. trade relations, leading to a recalibration of longstanding trade practices and agreements. With Mexico and Canada historically being two of the largest importers of U.S. dairy, any escalation might destabilize well-established supply chains and necessitate strategic pivots toward new markets. These new markets could be in Southeast Asia, the Middle East, and Africa, which might offer new opportunities and mitigate risk from targeted tariffs. This would be more pronounced for Mexico, given its proximity and dependency on U.S. agricultural imports. In contrast, Canada’s reaction would depend more heavily on the extent of additional tariffs levied. 

Such policy shifts also cast uncertainty over the international dairy markets, potentially leading to competitive pricing tariffs as global players adjust to new barriers. These competitive pricing tariffs could reduce the cost of dairy products, making them more affordable for consumers. The suggested tariffs challenge the integrative approach of trade blocs and free trade agreements, underscoring a critical juncture for U.S. policymakers who must weigh immediate political gains against long-term market access and economic stability. In briefing these unfolding events, dairy farmers and stakeholders are urged to monitor these international shifts closely and position themselves resiliently through diversified export strategies and competitive adaptations.

Strategic Moves for Tariff Turbulence: Fortifying Your Dairy Business 

  • Proactively Secure Contracts: Given the potential for new tariffs, dairy farmers should lock in contracts with critical buyers before changes take effect. Establishing long-term agreements can provide a buffer against price volatility.
  • Diversify Export Markets: Given the uncertain tariff landscape, consider exploring new markets beyond China, Mexico, and Canada. Countries in Southeast Asia, the Middle East, and Africa might offer new opportunities and mitigate risk from targeted tariffs.
  • Innovate Production Techniques: Evaluate current production methods and invest in technology that enhances efficiency. Streamlining operations cuts costs and positions businesses to maintain competitiveness internationally.
  • Focus on Value-Added Products: Strengthen your market by developing value-added dairy products. Offering unique, specialized products can open new revenue streams and differentiate your brand in domestic and export markets.
  • Collaborate with Industry Experts: Engage with trade associations and industry experts to stay informed about policy changes and market trends. Developing a network of knowledgeable contacts can provide timely advice and valuable insights.
  • Enhance Supply Chain Resilience: Assess supply chains for potential vulnerabilities to disruptions caused by tariffs. Building flexibility and resilience into logistics and sourcing could mitigate adverse effects.

Cheese Market: The Enigma of Unmoved Prices Amid Stock Decline

The cheese market reveals a curious case. Despite a significant drop in stocks, with U.S. cheese inventories at the end of October 32 million pounds below expectations and an 8% year-over-year decrease, prices are not climbing as anticipated. Usually, such a deficit would nudge prices towards the $2.00 mark. However, the market remains around $1.70, indicating potential market hesitancy or external factors curbing price elevation. As we look ahead, the cheese sector might face opportunity and risk; prices could rise if trade tensions ease or supply diminishes further. Yet, a bearish sentiment looms if market confidence doesn’t align with fundamentals. 

Turning to butter, even with a 10 million pound shortfall versus expectations by the end of October, stocks still show an 11.4% increase from last year. Consequently, CME spot butter continues to weaken. Retailers are seemingly well-stocked for holiday demands, but ample cream supplies suggest abundant production may cap price improvements.

Looking forward to late 2024 and early 2025, a stable or modestly declining trend might persist unless external demand surges unexpectedly or production dips significantly. 

Nonfat Dry Milk (NFDM) in the powders segment shows steady growth, while whey has experienced a notable surge, climbing to $0.69. This upswing in whey demands attention, as it might present lucrative opportunities if sustained. However, looming trade conflicts, particularly involving China, represent a potential threat, posing downside risks to U.S. whey exports. Strategic positioning in this market will be crucial, and agility to maneuver through possibly rocky trade landscapes will offer firms a competitive edge.

The Bottom Line

In today’s fast-evolving dairy industry landscape, staying informed and adapting to market changes is more crucial than ever. As we navigate the shifting tides of global trade policies, fluctuating stock levels, and evolving consumer demands, dairy farmers and professionals must remain vigilant and responsive to emerging trends and threats. The market’s volatility presents challenges and opportunities requiring strategic thinking and proactive measures. Consider this: Are you prepared to harness the upsides and confront the potential obstacles in the global dairy market? The decisions you make today could very well shape the futures of many businesses within this dynamic sector. 

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Cheese Conundrum: Unraveling the U.S. Cold Storage Trends and Their Impact on Dairy Markets

Examine unexpected shifts in U.S. cheese stocks. Do low supplies indicate changing demand or intentional production cuts?

Summary:

The October 2024 U.S. Cold Storage Report highlights significant shifts in dairy and poultry stocks that have industry experts puzzled. Cheese inventories are down by 8% from the previous year, leading to a market price disparity as cheese trades below its expected rate despite lower inventory levels. This discrepancy suggests potential mixed strategies by cheese producers or quick sales of excess supplies, contrasting with historical storage patterns. Meanwhile, butter stocks have decreased by 10 million pounds but remain 11.4% higher than last year, adding complexity to the supply narrative. Overall, the report underscores volatile dairy and poultry markets, urging stakeholders to reconsider strategies amidst uncertain demand and pricing landscapes. Factors like production capacity changes, consumer demand fluctuations, and inventory management strategies could explain these trends. The unexpected dip in butter stocks raises questions about milk’s channeling into butter production, further complicated by a surplus of cream, suggesting ample supply but an unexplained constraint in butter availability. The stability of cheese prices remains delicately balanced amidst these dynamics.

Key Takeaways:

  • Cheese stocks have decreased significantly, down 8% compared to last year, yet market prices do not reflect this scarcity, remaining lower than expected.
  • The discrepancy in cheese price despite low stocks suggests potential mismatches between production and sales or shifts in demand dynamics.
  • Butter stocks also surprise, with a decline of 10 million pounds from forecasts, although overall supply is still above last year’s levels.
  • Class III futures are firm, hinting at potential price corrections or future market volatility, especially given the tight cheese inventories.
  • The report highlights a broader issue in dairy market dynamics where production levels, stocks, and prices are not aligning as traditionally expected.
cheese stocks decline, October 2024 U.S. Cold Storage Report, cheese prices analysis, dairy industry trends, production capacity changes, consumer demand fluctuations, inventory management strategies, butter production impact, dairy market stability, supply and demand alignment

The October 2024 U.S. Cold Storage Report highlights a sharp 8% plunge in cheese stocks from last year, surprising the dairy industry at a time when many anticipated ample supplies. Despite this scarcity, cheese prices only averaged $1.72 per pound in October, well below the $2.00 per pound that tightening stocks typically suggest. This suggests that either cheese producers align their output efficiently with demand, or there is a deeper market issue, prompting dairy professionals to reevaluate their strategies.

The Dairy Sector‘s Puzzling Supply Maze: Navigating October’s Intricate Stock Shifts

The October 2024 U.S. Cold Storage Report reveals an intriguing puzzle in the dairy sector: Cheese stocks decreased 8% year over year, and butter stocks dropped 12% monthly. These figures suggest dynamic shifts within the dairy industry, which demand an examination of the underlying factors. 

The drop in cheese inventories might initially seem an anomaly, especially given the review of September inventories. However, several potential reasons could explain this trend. One compelling hypothesis involves changes in production capacity. With milk production reportedly healthy for October, cheese manufacturers could be faced with a balancing act between meeting immediate market demand and maintaining inventory levels that align with future forecasts. 

Another angle considers consumer demand fluctuations. It’s plausible that a softening in domestic cheese demand could have led manufacturers to curb production or push the stock into domestic and international markets more aggressively. Alternatively, heightened exports could pull the cheese out of storage quicker than anticipated, a possibility worth investigating given global dairy trade patterns. 

Butter stocks, which declined 12% from last month, might hint at inventory management strategies adjusting to seasonal demand shifts. Butter storage levels often correlate with demand cycles, particularly around the holiday season. This reduction might reflect manufacturers preemptively moving butter stocks into retail and wholesale channels in anticipation of increased consumer buying. 

Production strategies could also play a pivotal role. If cheese production required additional milk, this might inadvertently reduce butter production, influencing available inventory levels. Furthermore, processors may prefer to avoid the costs associated with long-term storage unless justified by market dynamics signaling favorable price movements. 

Ultimately, these fluctuations underscore the intricate dance of demand, supply, and strategic planning in dairy markets. They suggest that industry stakeholders must monitor evolving market conditions and adjust strategies to maintain equilibrium between production, inventory, and meeting market demand.

Unraveling the Dairy Paradox: Supply, Demand, and Price 

The intricate dance of supply and demand in the dairy sector often leaves industry professionals scratching. In October 2024, cheese stocks faced a significant shortfall, plunging 8% compared to the previous year. This decline should have theoretically buoyed cheese prices at the CME to around $2.00 per pound, yet the market bucked expectations, averaging only $1.72. This apparent contradiction speaks to a deeper issue: a potential misalignment between dairy production and market demand. 

From a conservative standpoint, one could argue that cheese makers are now adept at tailoring their production levels to current demand, allowing prices to slip as they adjust their output accordingly. The emphasis here is on the importance of market agility, with producers scaling back to mitigate the risk of surplus and thus maintaining low stock levels. While often celebrated in free-market paradigms, this notion of efficiency can lead to unforeseen vulnerabilities, such as sudden shifts in consumer purchasing patterns or international trade dynamics. 

The role of milk in this scenario is pivotal, serving as the foundational raw material for a myriad of dairy products. As cheese production adjusts to market signals, we must evaluate alternative allocations for milk. The unexpected dip in butter stocks—falling 10 million pounds below forecasts—despite an 11.4% increase from last year begs the question: is milk finding a more favorable economic channel in butter production, or are other factors at play? The apparent surplus of cream further complicates this equation, suggesting ample supply yet an unexplained constraint in butter availability. 

This dynamic highlights a potential inefficiency or misjudgment in processing priorities, reinforcing the conservative viewpoint that stresses reasonable resource allocation. Ultimately, the interplay between production levels and demand dynamics calls for a strategic approach to milk distribution across various dairy products, ensuring resilience and stability in market pricing.

Cheese Production and Demand: An Intriguing Conundrum

Cheese production and demand present an intriguing puzzle. On one hand, the lower-than-expected cheese stocks might suggest improved production efficiency. Imagine a scenario where producers tailor their output precisely to the market’s needs, preventing any accumulation of excess supply. This efficient production could signify a savvy adaptation to current market conditions, ensuring producers maximize sales while minimizing waste. However, if demand simultaneously experiences a marked decline, it could exacerbate the decrease in visible stocks, as products are not stored for long durations. 

It is imperative to consider the implications of these factors for future cheese prices and market stability. Improvements in production practices often spell good news for the market, potentially offering more stable prices. If producers consistently match supply with demand efficiently, volatility might decrease, creating a steadier market landscape for farmers and distributors. Yet, should the reduced stocks be a symptom of weakened demand, this could portend less promising prospects. Ongoing declines in consumer interest might depress prices, potentially destabilizing the market if producers fail to adjust their strategies swiftly. 

Thus, the future of cheese prices and market stability lies delicately balanced between these dynamics. Stakeholders should keep a vigilant eye on consumer trends and production developments, as shifts could rapidly influence the broader market environment. 

Butter’s Mysterious Disappearance: Unpacking the Dairy Enigma

October’s cold storage report reveals a curious decline in butter stocks, revealing an apparent contradiction: they dropped by 12% from the previous month (NASS, October 2024), even as milk production increased. This anomaly raises striking questions about the underlying currents in the dairy market. 

Dwindling butter inventories could paradoxically point to a changing consumer taste or a strategic maneuver by dairy producers. On the one hand, lower butter stocks could suggest heightened consumer demand outstripping supply. However, this theory seems to clash with butter’s annual uptick of 11.4% compared to last October, hinting that production was undeniably ramped up. 

On the other hand, are dairy producers deliberately limiting butter stock to manipulate market prices or as a defensive strategy against volatility? Given that cream supplies remain plentiful, production capacity seems less likely to be the limiting factor. If consumer preference is veering away from traditional butter towards alternative spreads or plant-based options, this could necessitate a recalibration of production strategies within the industry. 

Furthermore, with butter prices historically sensitive to stock levels, this shortfall could signal potential price hikes that the market has not entirely accounted for. Is the dairy industry poised for a shift in its structural dynamics, driven by evolving consumer trends, or are we witnessing market adjustments in response to broader economic signals? 

As we puzzle over these prospects, it becomes evident that the dairy sector’s strategic decisions will critically shape the trajectory of butter prices and availability in the coming months. Could this herald a new era of consumption patterns, or is it merely a passing phase in the cyclical ebb and flow of dairy market forces?

Cheese & Butter Market: A Precarious Dance Between Demand and Supply 

The October U.S. Cold Storage report paints a compelling picture of the dairy sector’s current state, urging us to take a step back and consider the broader market implications. Historically, the tightness in cheese stocks is notable. With inventories down 8% from last year, this contraction spells potential risk factors that cheese prices might encounter. 

In the grand scheme of dairy economics, such reduced stocks could fundamentally challenge market dynamics. When stocks are low, and supply can’t meet the fluctuating demand, prices inevitably face upward pressure. This scenario suggests a precarious balance that could tilt towards price elevation if demand climbed or remained stable. Market participants should be vigilant, as this tension between demand and availability could lead to price increases that echo through supply chains, from cheese manufacturers to retailers. 

Meanwhile, butter stocks present another layer of complexity. Despite a lower-than-expected inventory, bulk and retail packaged butter are assuredly available, cushioning against immediate shortages. Nevertheless, those engaged in dairy production and sales should remain attuned to shifts in economic conditions, such as consumer spending power and global dairy trade activity, which influence butter demand and supply dynamics. 

The uncertainty surrounding global economic factors, inflation trends, and consumer behavior could amplify these risks. Understanding these market intricacies and preparing for potential fluctuations is critical for stakeholders who aim to leverage challenges and opportunities in the dairy market.

The Bottom Line

As we conclude our analysis of the October 2024 U.S. Cold Storage Report, we see that the dynamics within the dairy sector are intricate and shifting. The unexpected reduction in cheese stocks and a surprising dip in butter inventories present a curious paradox, suggesting a disconnection between supply, demand, and pricing. These fluctuations indicate potential underlying issues in production efficiency and consumer demand, raising questions about future pricing strategies and the ability to maintain balance within the market. 

With inventories tight, yet prices not reflecting typical supply-demand logic, dairy farmers and professionals are prompted to reassess their operational strategies. Could this be a signal to diversify product lines or optimize supply chain management? Furthermore, the intricacies revealed in these stocks pose a critical question: How will these trends influence the sector’s competitive landscape and pricing stability in the coming months? 

We invite you, our valued readers, to join this conversation. Share your insights, experiences, and strategies in the comments or on social media. How are you tackling these challenges and preparing for future market shifts? Stay informed, stay adaptive, and let’s navigate these evolving market dynamics together.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

The Cheese Paradox: Why Futures Dive Despite Shrinking Supplies

Why are cheese futures dropping despite low stocks? What are the implications for dairy farmers and the market? Find out more now.

Summary:

In an unexpected twist, U.S. cheese stocks have dropped significantly, with inventories down by 8% year-over-year and a significant reduction of 26.3 million pounds in October, marking the most substantial decrease since 2019. Despite this, the futures market reflects a downward trend, befuddling industry experts and suggesting that market dynamics may not be as closely aligned with supply conditions as previously thought. Expectations of an eventual surplus due to increased production capacity have shifted market predictions, revealing a complex interplay of forces. Industry stakeholders are prompted to revisit their strategies and potentially invest in export markets or new products to maintain revenue in this uncertain environment.

Key Takeaways:

  • U.S. cheese stocks experienced a significant drop, marking the largest decrease from September to October since 2019, contrary to typical seasonal trends.
  • American-style cheese inventories decreased by 7.3% year-over-year, while other cheese varieties saw an even sharper decline of 9.3%.
  • Despite the previous summer’s rise in cheese and Class III markets, fresh cheese supplies now appear abundant, contributing to a slump in futures.
  • With new cheese production facilities coming online, the market anticipates a potential surplus despite low inventory levels.
  • Butter inventories, while reduced in October, remain higher than the previous year, influenced by commercial demand and falling spot market prices.
cheese futures, dairy industry trends, U.S. cheese inventories, cheese production capacities, supply chain disruptions, cheese market analysis, dairy pricing structures, cheese reserves decline, export markets for cheese, cheese production innovations

How can cheese futures be slumping when cheese stocks are at historic lows? This perplexing situation puzzles even the most seasoned industry experts. As dairy farmers and industry professionals navigate these turbulent times, understanding the forces at play becomes crucial. This phenomenon underscores the unpredictability of the dairy industry, highlighting the need for stakeholders to grasp complexities to strategize effectively, especially in the face of global competition that significantly impacts the U.S. cheese market. A decline in cheese stocks, a slump in futures prices, and new production capacities introduce unique challenges and opportunities. Delving into this cheese paradox is essential to comprehend how these elements interact and what they mean for the dairy industry’s future. 

The Great Cheese Conundrum: Navigating a New Normal in Dairy Stocks 

The current landscape of U.S. cheese inventories paints a striking picture of deviation from the norm. A significant downturn was registered in October, as stocks dwindled by 26.3 million pounds, marked by the USDA as the most significant September-to-October drawdown witnessed since 2019. This contraction in inventories defies the usual seasonal growth patterns, which traditionally see a build-up in reserves throughout the year. Historically, a rise of approximately 18 million pounds in stockpiles is expected over the first ten months. Remarkably, 2024 has derailed from this trajectory, witnessing a reduction of 99.9 million pounds, a figure that starkly contrasts with the average. As a result, cheese reserves now stand 8% lower than in the previous year, showcasing a troubling trend that raises several questions about future supply stability.

Unpredictable Patterns: Echoes of History in Today’s Cheese Futures 

Cheese futures have sometimes followed a predictable pattern, especially during periods of supply volatility. This can be traced back to the economic unrest of the 2008 financial crisis. Consumer buying power and global trade disruptions impacted dairy prices during that time. Cheese stocks plummeted while futures surged amid fear-driven speculation before stabilizing post-crisis. 

In the 1990s, the U.S. dairy market faced regulatory changes that affected supply chains and, consequently, cheese futures. Farmers grappled with new pricing structures, leading to temporary supply bottlenecks similar to today’s situation. Despite initial slumps, long-term trends corrected as markets adapted. 

The question remains: is today a repeat of the past, or are we entering uncharted territory? While patterns offer insights, each economic and agricultural environment presents unique variables. The current slump may be a hiccup, a minor correction before equilibrium. Or it could signal a need to reassess our approaches to supply management in an increasingly unpredictable climate.

Strategic Expansion or Imminent Glut: The Path Ahead for Cheese Production

As new cheese production facilities prepare online, the supply-demand landscape may undergo more significant shifts than anticipated. The promise of additional capacity brings the potential for increased output. However, will this automatically cater to the demand or exacerbate the current slump in cheese futures? 

New vats equate to an expanded arsenal for cheese producers, potentially flooding the market with a surplus when demand may not be strong enough to absorb it. Historically, dairy farmers have been cautious about the ‘build it and they will come’ philosophy. More production facilities do not inherently guarantee a synchronized increase in consumption. 

For dairy farmers and cheese producers, this mismatch could result in lower prices with more competition and pressure to innovate and seek broader markets. There’s a scenario where cheese prices could further plummet if the additional supply overshoots demand. It’s crucial to consider whether the global appetite for American cheese varieties will surge or producers might have to pivot strategies. 

Furthermore, producers might need to consider export markets or explore new product innovations to sustain revenue streams. Strategically, decision-makers must carefully assess market opportunities and potential constraints. As the industry expands its capabilities, prudent management and strategic forecasting are needed to avert a surplus-driven price drop.

The Double-Edged Sword of Supply and Demand 

The supply-and-demand puzzle is at the heart of the recent cheese paradox. On one hand, dwindling inventories suggest a tighter market and rising prices. Yet the futures market signals otherwise. What gives? 

Part of the answer lies in the supply chain dynamics. Over the past year, dairy farms have invested in new cheese vats, expecting an increase in milk production. This technological expansion aims to churn out a greater volume of cheese shortly. As these vats go operational, the market anticipates an influx of cheese, turning the current tight supply into a potential surplus. This expectation depresses futures prices despite present low stocks. 

The perception of future abundance shapes current market behavior. Suppose buyers believe that cheese will be more plentiful and cheaper tomorrow. In that case, they’re less inclined to purchase aggressively today, which counters immediate scarcity. This forward-looking mindset is critical to current market sentiments and price adjustments.

Navigating Uncertainty: Balancing Strategy in a Fluctuating Cheese Market 

For dairy farmers and industry stakeholders, the slump in cheese futures amidst dwindling stocks is a perplexing navigational challenge. In a world where supply doesn’t dictate market steadiness, pricing strategies hang precariously in the balance. Farmers are caught in a seesaw of anticipation and caution, questioning whether to ramp up production in hopes of a future price rise or to pull back, minimizing potential losses. 

Related businesses must tread carefully, too. With the anticipation of new vats emerging soon, the specter of an impending surplus looms large. This could drive prices even lower, affecting the entire supply chain. But what if demand surges unexpectedly? It’s a precarious guessing game emphasizing the need for agile, informed decision-making that blends experience with foresight. 

In this market landscape, long-term planning is more art than science. Now more than ever, stakeholders, from farmers to marketers, require crystal-clear communication and cooperative strategies to weather recent trends’ unpredictability. This is a test of resolve and adaptability. Are we ready for it?

Butter’s Balancing Act: A Tale of Surplus in a Sea of Cheese Shortages

The volatility in dairy commodities extends beyond cheese; butter presents its complexities. While cheese stocks have significantly declined, butter inventories paint a contrasting picture. Warehouses still hold an 11.4% surplus compared to the previous year despite a seasonal drop in October [USDA]. This surplus starkly contrasts the depleted cheese reserves, indicating divergent inventory trends within the dairy sector. 

Pricing dynamics differ as well. Once bullish, the market for cheese, especially fresh Cheddar, is now under pressure from potential oversupply, leading to lowered futures and spot prices. Conversely, butter prices have dipped sharply, influenced by hefty supplies and abundant cheap cream, marking a significant downturn over the last three months [CME]. These differences highlight the multifaceted nature of dairy markets, where supply shifts and pricing are not uniform across products, presenting unique challenges and opportunities for industry stakeholders.

Global Tapestry: The Unfolding Story of Cheese Futures 

The global cheese market is a tapestry of intricate interactions where international trade dynamics significantly shape U.S. cheese futures. As American cheese stocks shrink, eyes turn to the export demand that partly siphons away domestic supply. The U.S. has a growing presence in the global market. Still, it faces fierce competition from European powerhouses like Germany and France, whose rich cheese traditions make them formidable rivals in volume and variety. 

Trade policies further complicate the landscape. Tariffs and trade agreements dictate cheese flow across borders, impacting price and availability. For instance, recent trade tensions and tariffs have led to volatile market conditions, affecting U.S. cheese exporters’ competitiveness abroad. However, opportunities arise with favorable trade agreements that can open new markets or enhance existing ones, thus influencing futures. 

Foreign producers continue to challenge U.S. market share. Nations with solid cheese industries aggressively pursue international buyers, leveraging their unique product offerings. As these players gain ground, the U.S. must strategically adjust to maintain its competitive edge. This involves responding to international pricing pressures and anticipating changes in consumer preferences and global supply shifts. 

The intricate dance of export demand, trade policies, and international competition shapes the U.S. cheese futures landscape. As these elements shift, stakeholders must remain agile and continually recalibrate strategies to navigate this complex global market. The question remains: How will the U.S. adapt to ensure its cheese producers thrive amid these ongoing global changes?

The Bottom Line

The paradox of dwindling cheese stocks juxtaposed with plummeting futures is a testament to the intricate dance of supply and demand that defines our dairy markets. While inventories decline, expectations of future surpluses create a complicated scenario that challenges producers and traders. As we grapple with this volatile environment, what strategies might be required to ensure stability in the face of such unpredictability? How do we safeguard against the cyclical market shifts that risk profit margins and production capabilities? 

Your insights are vital. We invite you to share your thoughts and experiences on these dynamic market forces. How are you adapting to the changing landscape? Join the conversation by commenting below or connecting with us on our social media channels. Let’s navigate these dairy dilemmas and shape the industry’s future together.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Latin American Dairy Industry Turnaround: Navigating Production Shifts Amid Economic and Environmental Challenges

The rollercoaster of production adjustments in Latin America’s dairy sector speaks volumes. As climatic hardships and economic tides rise, the pressing question is: can exporters and importers navigate toward a harmonious equilibrium?

Summary:

As 2024 winds down, Latin America’s dairy industry faces significant changes amidst a complex web of economic volatility and environmental adversities. While Argentina has overcome economic challenges leading to a marginal recovery in milk production, Brazil grapples with environmental hurdles, resulting in a 0.6% decrease in dairy productivity for the third quarter. Meanwhile, Uruguay sees a recovery from weather setbacks, and anecdotal evidence in Mexico suggests a tightened milk supply despite official data. The contrasting production trends in Chile and Colombia further highlight regional disparities. Brazil’s increased reliance on imports exerts additional pressure on regional trade networks, leading to price volatility. As Mercosur facilitates trade among major dairy players, the trajectory of Latin America’s dairy industry appears promising and challenging.

Key Takeaways:

  • Argentina and Uruguay have experienced a shift from earlier production losses to recovery, driven by higher milk prices and moderate operational costs.
  • Brazil faces diverse challenges with its dairy production, notably adverse weather conditions such as flooding and drought.
  • Despite official data indicating rising production, anecdotal evidence suggests tighter milk supplies in Mexico, driving up prices and sustaining import levels.
  • Chilean dairy production has increased, attributed to improved margins, whereas Colombian output continues to struggle.
  • The dynamic interplay between exporters and importers within Latin America significantly influences regional production and consumption trends.
  • Rising milk supplies and reduced demand have recently exerted downward pressure on dairy market prices.
Latin American dairy industry, Argentina milk production, Brazil dairy imports, Uruguay dairy resilience, environmental challenges dairy, milk price volatility, Mercosur dairy trade, pasture management innovations, economic volatility dairy, water conservation measures

The Latin American dairy industry is witnessing dramatic shifts, challenging traditional production models amidst economic volatility and environmental adversities. This new norm prompts a re-evaluation of growth strategies. The question remains: how are these changes reshaping the future of dairy farming in Latin America? The answer lies in balancing opportunities from favorable price dynamics with risks from weather patterns and economic instability. As producers navigate these turbulent waters, the broader implications for exporters and importers will become increasingly significant. 

Fortune’s Divide: The Uneven Terrain of Latin America’s Dairy Domain

In the ever-evolving Latin American dairy landscape, a distinct divide has emerged between the fortunes of exporters and importers. This divide is not just a matter of economics but also reflects the unique local challenges and opportunities each country in the region is experiencing. 

Argentina and Uruguay are beacons of hope in the Latin American dairy industry. Both countries have shown remarkable resilience despite severe macroeconomic adversities and volatile climate conditions. Argentina’s milk production, for instance, has only seen a 0.4% decline from previous year levels as of October, a testament to the industry’s adaptability. Similarly, Uruguay is witnessing a revival in its dairy production, with milk volumes in September only 1% below last year’s figures. These success stories inspire confidence in the industry’s future. 

On the other hand, Brazil presents a worrying case. The dual assault of natural calamities—flooding in the south and drought in the central regions—contributed to a 0.6% decrease in milk production in the third quarter. This has undeniably pressured Brazil to meet domestic dairy needs through imports from Argentina and Uruguay. This underscores the disparate fortunes between exporters and importers in the Latin American dairy market. 

The current scenario presents a unique opportunity for regional exporters to cater to the increased demand from their struggling counterparts. However, challenges remain in balancing supply with market fluctuations. 

Economic Tides: Argentina’s Inflation and Mexico’s Peso Challenges

One ordeal stands out distinctly as we dive deeper into the economic web shaping Latin America’s dairy sector: Argentina’s inflationary spiral. The rampant inflation has left dairy producers in a predicament. Many initially curtailed production to shield themselves from the relentless rise in costs. This decision, however, triggered a chain reaction where reduced milk availability spurred higher prices, creating a paradoxical incentive for production escalation in subsequent months. Such volatile economic conditions demand swift adaptability from producers, altering market dynamics in real-time as profit margins fluctuate [Source: Argentinian Economic Analysis Journal]. 

Similarly, Mexico grapples with a different economic beast—currency fluctuations. The weakening peso has dented the financial might of importers, complicating purchasing decisions. Despite official statistics depicting steady production growth, real-world tales paint a scenario of tightening domestic milk supplies. This disconnect between reported data and market sentiment underscores how currency valuation intricacies can ripple through the supply chain, fostering robust import activities even amidst fiscal adversity. Consequently, producers and importers must navigate these economic waters, weighing cost against opportunity in a market that remains unyielding in its complexity [Source: Mexico Dairy Market Report].

Environmental Frontlines: Brazil’s Resilience Battle in Dairy Farming 

Environmental challenges are reshaping the landscape of milk production throughout Latin America. Brazil has seen its fair share of trials, with a complex mix of flooding and droughts challenging dairy farmers. These extreme weather events test resilience and are a significant factor in shaping production strategies and supply chains. 

Prolonged flooding in southern Brazil has severely impacted pasture conditions, making it difficult for farmers to maintain typical production levels. This unfortunate scenario forces farmers to adapt swiftly, seeking improved drainage solutions and focusing on water management techniques to protect their land and livestock. Meanwhile, the central region faces hurdles, with persistent droughts and wildfires exacerbating water scarcity. This dual crisis necessitates water conservation measures, feed supply adjustments, and pasture management innovations to mitigate losses. 

The repercussions of these environmental challenges extend beyond the farm gate, affecting supply chains throughout the region. With decreased local production, Brazil’s reliance on dairy imports has increased, placing additional pressure on regional trade networks. These supply constraints lead to higher volatility in milk prices and urge producers in neighboring countries to ramp up their exports to fill the gap. 

These dynamics underscore the critical need for adaptability and strategic planning in the face of climate-induced challenges. As farmers and industry stakeholders navigate these changes, the focus remains on implementing sustainable practices that ensure the stability and resilience of the dairy sector amid an unpredictable climate future. By emphasizing the importance of strategic planning, stakeholders will feel more prepared to face the industry’s challenges.

Latin American Dairy Landscapes: Navigating Economic Waves and Climatic Currents 

Argentina: The Argentine dairy landscape has pivoted remarkably amid economic upheaval. Following initial production cuts due to inflationary pressures at the beginning of 2024, scarcity-induced price increases have restored the sector’s vigor. Production is almost parallel to last year’s figures, underscoring a robust recovery backed by solid margins. 

Uruguay: Uruguay’s dairy path resembles Argentina’s tale of recovery. After a weather-induced production dip, producers’ profitability has rebounded thanks to favorable price trends at Global Dairy Trade events. Current output is nearing previous levels, signaling strengthened production after the second quarter declines. 

Brazil: Brazil has navigated an arduous terrain of environmental disruptions. Adverse climate phenomena, including southern floods and central droughts, soon tempered initial optimism in production. Consequently, the country noted a slight contraction in milk production by 0.6% in the third quarter, albeit maintaining robust import demand amidst declining domestic yields. 

Mexico: In Mexico, a paradox emerges between official statistics and market realities. Government data reflects a steady upward production trajectory; however, market sources reveal a contrasting narrative of tightened milk supplies, which have driven up prices and sustained vigorous import activity, even as the peso’s depreciation weighs heavily. 

Chile, on the other hand, presents a more optimistic picture. Favorable agricultural conditions have ignited a surge in Chilean milk production, with a notable 8.5% year-over-year increase reported in September. This growth, attributed to improved pasture conditions and enhanced profit margins, aligns with a positive production upswing. The potential for growth in Chile’s dairy industry is a reason for stakeholders to feel optimistic. 

Colombia: Contrastingly, Colombia experiences a subdued dairy output, marked by consistent production deficits over recent months. A September report details a notable 3.8% decline, indicating ongoing challenges in meeting past production benchmarks. 

Mercosur’s Market Ballet: Navigating Supply-Demand Dynamics in Latin American Dairy

The interplay between supply and demand is critical when evaluating Latin America’s dairy market dynamics. This volatile environment highlights the intricate balance of dairy production and consumption that this region grapples with. Whether sparked by macroeconomic variables or erratic weather conditions, production shifts have a domino effect on import and export activities. These fluctuations craft a complex landscape where demand’s constant ebb and flow negotiates with the vicissitudes of supply. 

As a regional bloc, Mercosur plays a pivotal role in smoothing these interactions between Latin America’s major dairy players. It acts as a conduit facilitating trade, reducing barriers that might otherwise hamper the flow of dairy products among its member countries: Argentina, Brazil, Paraguay, and Uruguay. This network is essential for bolstering trade among these countries, allowing them to mitigate regional production discrepancies through strategic import and export of dairy commodities. 

Changes in milk production in Argentina and Uruguay directly affect Brazil’s import levels. When Brazilian production wanes under environmental pressures, as seen with recent flooding and drought, it relies heavily on Mercosur allies to satisfy its domestic demand. Conversely, when Argentina and Uruguay experience favorable production conditions, the regional market finds a natural equilibrium as surplus supplies circumvent potential wastage by flowing into member markets with deficits. 

Through Mercosur, tariff reductions and streamlined cross-border processes significantly enhance trade efficiency, enabling member countries to react adroitly to supply-demand shifts. This regional collaboration not only buttresses local economies but also fortifies the overall resilience of Latin America’s dairy market against external shocks. Consequently, the situational flexibility afforded by Mercosur underscores the strategic advantage of regional integration in navigating both predictable and unforeseen market dynamics.

Forecasting the Tricky Pathways: Navigating Opportunities and Obstacles in Latin America’s Dairy Future 

Looking forward, the trajectory of the Latin American dairy industry appears promising but also fraught with challenges. Producers’ and importers’ ability to effectively navigate economic shifts and environmental unpredictabilities is the key to future success. High inflation rates, particularly in economies like Argentina, may continue to challenge cost structures, while fluctuating currencies could reshape import and export dynamics, especially for nations heavily reliant on dairy imports, like Mexico. 

Regarding environmental factors, the industry must adapt to the increased frequency and intensity of weather events. Countries like Brazil, facing drought and flooding, may need to invest in more resilient farming practices and infrastructure. This includes embracing technological advancements that mitigate these impacts, such as drought-resistant feed crops or improved water management systems. 

Furthermore, the interdependencies within the Mercosur trade bloc suggest that regional cooperation could be a boon for stabilizing supply chains. As such, there is an opportunity for enhanced collaboration in resource management and policy-making, which could ensure a steadier milk flow throughout the region, even as each country confronts its unique hurdles. 

Thus, Latin America’s future outlook for dairy will hinge on a delicate balance of economic agility and environmental foresight. As the region grapples with these challenges, Latin American countries have the potential to stabilize and possibly elevate their status in the global dairy sector—provided they can harness innovative and sustainable strategies.

The Bottom Line

As the year concludes, Latin America’s dairy landscape showcases a fascinating evolution marked by economic fluctuations and environmental adversities. While Argentina and Uruguay have bounced back from earlier production setbacks due to strengthening milk prices, resiliency has led to marginal gaps in output compared to the previous year. In contrast, Brazil’s production has faced environmental challenges that contributed to decreased milk supply, underscoring the diverse nature of dairy dynamics in this region. Mexico and Chile offer another complexity, fluctuating production narratives despite diverging economic pressures. These intricate shifts raise questions about the adaptability and strategic planning required for stakeholders in this volatile market. As Latin America grapples with domestic and global pressures, what strategies will dairy producers adopt to balance natural forces with economic opportunities? Readers must ponder whether their current business strategies could withstand similar pressures and how they might proactively engage with these evolving trends to thrive in this enigmatic dairy theatre.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Global Dairy Market Surges and Setbacks: Key Insights and Trends for November 2024

Uncover November’s global dairy market trends. Ready to tackle the highs and lows? Find essential insights for dairy professionals and farmers.

Summary:

The global dairy market is currently undergoing significant transformations, influenced by robust trading activities on the European Energy Exchange (EEX) and Singapore Exchange (SGX), with notable price fluctuations in butter, skim milk powder (SMP), and cheese across Europe. As major dairy-producing regions like Europe and New Zealand report mixed production trends, China’s 10.7% import downturn is pivotal, compelling the industry to reevaluate global trade dynamics. Meanwhile, the United States faces a critical juncture, aiming to seize export opportunities despite falling domestic prices. This dynamic interplay invites dairy professionals to rethink strategies and adapt to evolving market conditions. A recent strong trading surge at EEX and SGX showcases active market participation with varied price outcomes; price resilience in Europe for butter and SMP contrasts with cheese index declines, while global dairies witness a notable growth discrepancy between Europe’s steady push and New Zealand’s remarkable rise. The Global Dairy Trade (GDT) reflected international demand with a 1.9% index rise despite mixed trends in cheese values, emphasizing the intricate nature of today’s dairy landscape and the need for agile pricing strategies to capture emerging opportunities.

Key Takeaways:

  • EEX and SGX experienced high trade volumes with notable price fluctuations in butter and SMP.
  • Despite price declines in cheese indices, European dairy markets show resilience, especially in butter prices.
  • Global dairy production sees contrasting patterns: steady growth in Europe vs. a remarkable increase in New Zealand.
  • China’s significant drop in dairy imports highlights challenges in the global market dynamics.
  • The U.S. dairy market faces a crossroads with falling prices, presenting challenges and opportunities for exporters.
dairy market fluctuations, EEX SGX trading activity, butter SMP price trends, European dairy sector outlook, Global Dairy Trade index, WMP futures performance, cheese market stability, EU dairy quotations, international dairy demand, pricing strategies in dairy market

As tides turn in the global dairy markets, challenges and opportunities arise rapidly, challenging even seasoned professionals to keep up. Navigating these waters is essential for those dedicated to dairy farming and industry professionals aiming to stay ahead. The sector’s constant changes, like the drop in Chinese import demands or surges in European butter pricing, have significant implications. One industry veteran with over 30 years of experience in the dairy industry notes, “In the dairy world, the only constant is change, and it’s those who stay informed who thrive.” Remaining knowledgeable is crucial for strategizing effectively and sustaining growth amid the volatile marketplace dairy industry. 

Market Turbulence: EEX and SGX Navigate a Week of Surging Trades and Price Swings 

The global dairy market experienced notable fluctuations this past week, marked by variations in trade volumes and price shifts across critical exchanges such as the EEX and SGX. On the European Energy Exchange (EEX), 3,925 tonnes of products were traded, showing a slight decline in Butter and SMP prices. EEX Butter futures showed a 1.8% dip, averaging €7,276 for the Nov 24-Jun 25 strip. Meanwhile, SMP saw a marginal downturn of 0.2%, with average prices settling at €2,749. 

Conversely, the SGX observed substantial trading activity, with 20,542 tonnes exchanged. The markets saw a mixed trend, with WMP futures firming by 0.5%, reaching an average price of $3,914, while SMP futures declined by 1.3% to $3,038. This mixed trend indicates the complex and dynamic nature of the dairy market, with different products responding differently to market forces. AMF and Butter prices on the SGX showcased a stable trend, with AMF slightly down by 0.1% and Butter inching up by 0.2% across their respective curves. 

EU Quotations presented an optimistic outlook as butter prices climbed across various European markets, including Germany, France, and the Netherlands. The average jumped by €80 to €7,920. SMP prices also experienced an upward trend, reinforcing a broader positive sentiment within the European dairy sector.

The latest data from the Global Dairy Trade (GDT) painted a similarly bullish picture, with the index rising by 1.9% and reaching an average price of $4,089. Noteworthy movements included a 3.2% increase in the WMP Index and modest gains in AMF and Butter, reflecting vigorous international demand. Such trends underscore significant dynamics currently shaping the global dairy trade landscape, warranting keen observation from market participants.

Price Resilience in Butter and SMP Amidst Cheese Index Declines: Europe’s Dairy Market Transformation

The European dairy market has experienced significant shifts over the past week, primarily due to fluctuations in Butter, SMP, and whey prices. An upward trend in EU quotations marked the dynamic trading landscape. Butter prices showed resilience, climbing by €80 (+1.0%) to €7,920, with notable increases in German and French markets at €8,200 and €7,610 respectively. However, Dutch butter prices held steady, illustrating regional variations within the market. 

SMP prices also trended upwards, with an overall gain of €48 (+1.9%) to reach €2,598. The variations in SMP prices displayed marginal yet crucial gains across Germany, France, and the Netherlands, reflecting a nuanced and competitive trading environment. The overall SMP average, however, remains €44 (-1.7%) below last year, suggesting some lingering market pressures. 

Whey prices also modestly increased, with the index rising by €3 (+0.4%) to €860, driven by a €20 gain in the German market. French whey slightly declined, indicating potential market saturation or shifting demand dynamics. 

Despite these upward trends, the European Cheese indices painted a less optimistic picture, with declines across all tracked varieties. Cheddar curd dropped by €35 (-0.7%), and Mozzarella experienced a more pronounced decrease of €52 (-1.2%). Mild Cheddar and Young Gouda saw minor declines yet remained substantially above year-ago levels, providing a mixed outlook on European cheese market stability.

GDT Auction Reveals Complex and Contradictory Trends: A Call for Urgent Strategic Adaptations in Global Dairy PricingThe latest Global Dairy Trade (GDT) auction painted a mixed picture with its 1.9% increase in the overall index, nudging the average price up to $4,089. This uptick suggests a nuanced yet cautiously optimistic outlook for the global dairy market. The Whole Milk Powder (WMP) Index led the charge with a notable 3.2% rise, positioning the average price at $3,826, despite variability in offerings like Fonterra’s Regular WMP C2, which saw a $130 increase, diverging from Solarec’s Belgian Regular WMP’s $110 decrease. Such disparities indicate complex regional dynamics and the influence of product differentiation. 

Skim Milk Powder (SMP) posted a modest 0.9% gain, aligning the average price at $2,882. Meanwhile, contrasting movements were evident in the Butter and Anhydrous Milk Fat (AMF) sectors; Butter prices increased by 0.5%, while AMF recorded a more significant 1.0% increase. These shifts highlight the continued global demand for fat-rich dairy products. In stark contrast, Cheddar endured a 3.1% drop. In contrast, Mozzarella plunged by 6.6%, underscoring potential shifts in consumer preferences or competitive pressures within specific cheese categories. 

The auction’s outcomes have broader implications for global trade dynamics and pricing strategies. Rising averages in critical segments, like WMP and SMP, could invigorate producer confidence and shape future contract negotiations. However, fluctuations in cheese prices illuminate the volatility stakeholders must navigate, underscoring the need for agile pricing strategies to maintain competitiveness while capturing emerging opportunities across diverse markets. Additionally, the participation of 162 bidders at this auction reflects robust engagement, hinting at sustained interest yet highlighting the competitive landscape’s intricacies.

Major Dairy Producers Display Contrasting Trends: Europe’s Steady Push vs. New Zealand’s Remarkable Growth 

As the global dairy market ebbs and flows, regional production in major dairy powerhouses offers a glimpse into current affairs. The European Union (EU) and the United Kingdom saw milk production numbers for September climb ever so slightly by 0.2% year over year, reaching an impressive 12.62 million tonnes. Milksolid collections followed this upward trend with a 1.4% increase, resulting in a cumulative total of 2024 9.26 million tonnes, representing a growth of 0.6% yearly. 

Across the Atlantic, the United States mirrored a similar modest uptick. October’s figures showed a 0.2% increase in production from the prior year, aggregating 8.48 million tonnes. Notably, milk solid collections surged by 1.6% year over year, amounting to 644,000 tonnes for the month. This nudged the cumulative total to 6.41 million tonnes, up a robust 1.8% compared to the previous year. 

Moving to the Southern Hemisphere, New Zealand reported a standout performance in October, with a 2.1% year-over-year milk production growth of up to 3.08 million tonnes. The nation continues to defy expectations, with milk solids production experiencing a remarkable 2.8% year-over-year increase. Cumulatively, the country marks a 2.1% boost in milk solids production for 2024, totaling 1,449 million kg, while the season-to-date figures stand out with a whopping 5.0% rise year-over-year. 

Meanwhile, in the heart of South America, Argentina faces a less optimistic scenario. October’s milk production took a minor hit, dipping 0.4% year-over-year to 1.09 million tonnes. The challenges seem deep-rooted, as cumulative collections for 2024 have slumped by 8.5% year-over-year, clocking in at 8.84 million tonnes. The milk solid collections also reflected this downtrend, with a decrease of 0.5% for October and an annual downturn of 8.3%, up to 637,000 tonnes.

China’s Dairy Dilemma: A 10.7% Import Downturn Triggers Global Market Reevaluation 

The declining Chinese dairy imports, registering a notable 10.7% drop in October, have sent ripples through the global market. This downturn falls within the lower spectrum of expected outcomes, starkly contrasting the robust growth in demand at one time. The contraction, particularly of Whole Milk Powder (WMP) and Skim Milk Powder (SMP) imports from New Zealand, has accentuated vulnerabilities in the supply chain and sparked recalibrations in export strategies. New Zealand, traditionally reliant on a vigorous Chinese market, may need to diversify its export portfolio to mitigate risks posed by this downward trend. In time, the lag between import reductions and real-time market adjustments could paint a concerning picture of demand dynamics. 

Conversely, despite its challenges, the EU’s export landscape tells a different story. September witnessed a dip of 4.5% in milk equivalent exports, a statistic bolstered primarily by burgeoning butter demand from the U.S. This juxtaposition between product lines within the European market suggests a potential realignment in export focus. With cheese export figures slightly revising upwards and whey demand surging from regions like Indonesia, there’s an evident shift towards stabilizing through diversification. The significant downturn in SMP exports, nearly 17.4% less than the previous year, underscores a need for innovative pricing strategies and agile supply chain adaptations to counteract such fluctuations. 

These intertwined dynamics between Chinese import patterns and EU export shifts fundamentally influence global dairy supply chains. This environment necessitates strategic pricing adjustments and proactive market engagement strategies for producers and exporters. The apparent decoupling in import and export rhythms creates potential opportunities and challenges; the ability to pivot and adapt becomes a critical determinant of market success. As the global dairy landscape continues to evolve, the strategies employed today will undoubtedly shape the market dynamics of tomorrow.

The U.S. Dairy Market at a Crossroads: Seizing Opportunities Amidst Price Tumbles

The U.S. dairy market stands at a crossroads as recent USDA reports spotlight the dynamics influencing cheese and butter prices. These commodities, pivotal to the dairy industry, have experienced a marked downturn in cash and futures markets, leading to significant price reductions. Notably, the six-month price strip for cheese has dropped by 2.2%, while butter prices show a 3.0% decrease. Such declines reflect the market’s reaction to the USDA’s revised milk production figures, highlighting an unexpected surge in cow numbers and milk output. 

From an export perspective, this price dip could uniquely position U.S. cheese and Butter as competitive offerings in the global marketplace. U.S. commodities could find a solid footing as world markets hunt for affordability amidst fluctuating dairy prices. However, leveraging these export opportunities requires navigating complex challenges. Chief among these is the logistical hurdle of increased shipment volumes amidst ongoing supply chain disruptions. 

Moreover, the competitive global landscape demands strategic positioning from U.S. producers to maintain value and build long-term trade relationships. The challenge is to balance domestic supply with export aspirations while ensuring quality standards that meet international expectations. 

In conclusion, while the domestic price dip may present short-term pain, it simultaneously allows U.S. dairymen to explore broader horizons. Producers must adapt, innovate, and seize potential export markets, transforming current challenges into future opportunities.

The Bottom Line

In a week of diverse market movements, the global dairy sector experienced significant fluctuations, from buoyant trading volumes on futures to nuanced price shifts across global indices. The EU saw a mixed bag with resilience in Butter and SMP, juxtaposed against weakening cheese indices, hinting at a shifting market focus toward higher-fat dairy products. Meanwhile, GDT auctions presented a volatile landscape, demanding strategic foresight from stakeholders. 

The contrasting trends in major dairy producers highlight the regional variances in production dynamics. New Zealand exhibits potent growth, while China grapples with declining imports, urging a reconsideration of export strategies. Amid a backdrop of price drops, the U.S. market stands at a potential pivot point, offering export opportunities that could recalibrate domestic market perceptions. 

As these developments unfold, how will they influence your operational priorities? Could the shifting dynamics in import-export trends reshape your strategic goals or partnership alignments? Consider if your business is prepared to capitalize on potential price rebounds or navigate lingering volatilities. These pivotal market changes challenge us to rethink traditional approaches and inspire a proactive stance in decision-making.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

US Dairy’s New Heights: 2024 Margins Surpass 2022 Records

Dive into how dairy margins have exceeded 2022 levels and uncover the opportunities and challenges of these record profits for producers.

Summary:

As we delve into the dynamics of September 2024, dairy farmers are riding a wave of extraordinary profitability, with margins surging to record levels. This period marked a harmonious convergence of historically high milk prices and meager feed costs, creating fertile ground for unprecedented financial success in the dairy industry. Driven by soaring Class III milk prices and a favorable milk-to-corn price ratio, producers found themselves in advantageous positions unseen in recent years. Milk margins reached a remarkable $15.57/cwt, breaking previous records. However, this prosperity brings unique challenges and opportunities, as producers face strategic decisions involving debt management and reinvestment, with constraints such as heifer shortages and high interest rates impacting expansion plans. The current economic environment encourages stability and growth, offering a security measure that can be elusive in the agricultural sector. Yet, how long these conditions will last remains uncertain. In this landscape, the challenge lies in making the most of this providential scenario without becoming complacent, ensuring long-term success for dairy operations.

Key Takeaways:

  • September 2024 saw record-breaking milk margins, fueled by high prices and low feed costs.
  • Producers experienced substantial profit levels, with the milk-to-corn price ratio hitting its highest since 2014.
  • Debt repayment is prioritized over expansion due to limited heifer availability and high interest rates.
  • Improved cow comfort and diets are positively influencing milk production per cow.
  • The prospect of sustained strong margins extends into 2025, driven by favorable milk and feed price forecasts.
  • Milk supply remains weak, leading to stronger pricing in dairy products, with reduced milk output in the US, EU, and New Zealand.
  • The challenge of adding cows quickly due to limited heifer supply could sustain higher profit margins.
  • Dairy commodity production remains varied, with higher butter production and reduced milk powder output.
  • Raboresearch predicts continued strong dairy prices through the year, contributing to healthier margins.
dairy industry profits, All-Milk price, feed cost reduction, Dairy Margin Coverage, milk-to-corn ratio, economic opportunities for producers, debt repayment strategies, reinvestment in dairy, dairy market volatility, long-term success in dairy operations

The dairy industry is experiencing unprecedented record-breaking margins not seen since the highs of 2022. This sets the stage for a new era of opportunities and challenges, demanding immediate attention and strategic planning from dairy farmers and industry professionals. 

Historically, high milk prices and unexpectedly low feed costs have propelled September’s margins to unprecedented levels.

While these numbers might seem cause for celebration, they pose some fundamental questions: How can producers capitalize on these profits while preparing for potential market volatility? Is reinvestment the key, or should the focus be on expansion? The considerations are as enticing as they are complex. 

MonthMilk Margin ($/cwt)All-Milk Price ($/cwt)Corn Price ($/bu)Soybean Meal ($/ton)Hay Prices ($/ton)
August 202413.3423.254.00360230
September 202415.5725.503.95340227

 Unprecedented Profit Surge: Navigating Uncharted Waters in September 2024’s Dairy Sector

September 2024 was a landmark month for the dairy sector, characterized by historically high milk prices and meager feed costs. This combination drove margins to unprecedented levels. The All-Milk price reached $25.50 per hundredweight, a peak not seen since November 2022. Such high prices provided substantial profits, considering the last comparable surge nearly two years prior. 

Corn prices fell below $4 per bushel on the feed cost front, a threshold not crossed since early 2021, significantly alleviating financial pressure. Soybean meal and hay prices echoed this trend, further depressing expenses to levels unseen since that same year. This alignment of high milk prices against historically low feed costs is rare, exemplified by September’s remarkable milk-to-corn ratio of 6:4. This height has only been reached once since 2014, demonstrating the producers’ improved margins. 

To put this in perspective, the Dairy Margin Coverage (DMC) program, a federal safety net program for dairy producers, calculated the milk margin above feed costs at $15.57 per hundredweight for September — a record, supplanting the previously high August figure. Comparatively, margins had dipped to an all-time low of $3.52 per hundredweight just the year before, underscoring just how significant this year’s achievement is.

What makes these margins soar to unprecedented heights?

At the heart of this economic triumph is a confluence of factors that dairy producers have rarely witnessed simultaneously. High milk prices have been a significant boon, with September 2024’s All-Milk price reaching $25.50/cwt., one of the highest on record. Such robust pricing not only pads the bottom line but provides a buffer against any unforeseen dips in the market. 

Equally instrumental in this situation are the lower-than-expected feed costs. For the first time since early 2021, corn prices dipped below $4/bu., coupled with soybean meal under $350/ton and hay at $227/ton. This trifecta of reduced input prices means producers can maximize returns without sacrificing essential feeding practices that ensure productive and healthy herds. 

However, perhaps the most striking statistic is the milk-to-corn ratio, which soared to 6.4 in September—a peak not seen since 2014. This ratio is a crucial indicator of profitability, illustrating just how much milk one can produce relative to the cost of corn, a primary feed component. With milk so significantly outpacing the cost of corn, producers are essentially achieving more with less, stretching every dollar further. 

So, what does all this mean for the dairy industry at large? Simply put, the current blend of high milk prices and low feed costs is a rare alignment of favorable conditions, creating a golden opportunity for producers to thrive and plan strategically for the future. It’s an economic environment that encourages stability and growth, offering a security measure that can be elusive in the agricultural sector. 

How long these conditions will last remains uncertain. Still, they represent a chance for dairy producers to thrive and plan strategically for the future. In this landscape, the challenge lies in making the most of this providential scenario without becoming complacent, ensuring long-term success for dairy operations. At the same time, the window of opportunity remains open.

Strategic Navigation: Balancing Prosperity with Prudence in the Dairy Sector 

Amidst record-high margins, dairy producers are faced with pivotal decisions on how to utilize these economic advantages. For many, the imperative strategy is debt repayment. After weathering a financial storm in 2023, when margins plummeted to a historic low of $3.52/cwt due to high feed costs and low milk prices, clearing financial backlogs has become a priority. Reducing liabilities stabilizes operations and better positions farmers to face potential future downturns. 

For those with more solid financial standings, reinvestment emerges as a compelling avenue. This could manifest in various forms, such as upgrading facilities or investing in technology to improve efficiencies and milk production rates. However, the choice to reinvest isn’t solely about increasing volume; it’s also about enhancing quality. By improving cow comfort through measures such as better housing or optimized nutrition, farms can maximize the output and longevity of their herds, ultimately driving profitability. 

Yet, it’s not all smooth sailing. Challenges in acquiring replacement heifers impede expansion dreams. With inventories at historically low levels, adding to herds is neither quick nor cost-effective. Even if one could secure additional stock, sky-high interest rates further dissuade large capital expenditures. The dual pressure of livestock scarcity and financial costs is a formidable barrier, leaving many producers hesitant to embark on expansion plans. 

In navigating these opportunities and obstacles, producers must carefully balance taking advantage of today’s windfall and preparing for tomorrow’s uncertainties. The current landscape demands a growth strategy and a cautious approach that safeguards against the unpredictable nature of dairy markets.

Gazing Beyond the Horizon: Navigating a Future of Fertile Yet Fragile Dairy Margins

As we turn our gaze to the horizon, the future of dairy margins appears robust yet fraught with potential challenges. The current forecasts suggest a continuation of profitable margins bolstered by historically low feed costs and sustained demand. According to the USDA, milk prices are expected to hover around $22.75/cwt. Feed costs remain manageable the following year, with predictions of $4.10/bu. For corn and $320/ton for soybean meal. These figures indicate that the favorable conditions witnessed in recent months may persist, providing a fertile ground for continued profitability. 

However, the dairy industry is no stranger to volatility. A critical risk that looms is the increasing milk supply. Should the U.S. dairy herd numbers begin to climb, we might see downward pressure on milk prices, potentially eroding these favorable margins. The current constraint of low heifer inventories prevents a rapid increase in milk production, but this bottleneck may not last indefinitely. If producers find ways around this hurdle, possibly through technological advancements or changes in breeding strategies, the resulting increase in supply could disrupt the current balance. It’s essential to be aware of these potential challenges and plan accordingly. 

For dairy farmers and industry professionals, the path forward requires strategic decision-making. While the current market conditions offer opportunities to lock in profitable margins, vigilance is crucial. Monitoring supply trends and global demand dynamics will be essential to navigate the potential turbulence ahead. Ultimately, the ability to adapt and respond to these market signals will determine the durability of the current profit surge, ensuring that prosperity is not fleeting but sustained.

The Rhythm of Change: Navigating Dairy’s Price Fluctuations 

The volatility of dairy product prices is creating a new rhythm in the market landscape, challenging producers to strategize like never before. Throughout September and into October, we’ve witnessed a rollercoaster of price changes in critical commodities—Cheddar, butter, and nonfat dry milk. 

With its spot prices dancing up and down, Cheddar reached its zenith early in the week only to dip dramatically days later. Meanwhile, butter prices climbed past benchmarks yet couldn’t hold their ground by week’s end. Nonfat dry milk, although reaching a peak early, gently retreated as the week progressed. Such fluctuations demand diligent attention from producers, as these shifts directly impact the margins. 

Producers must pay attention to the dance of these products in the market. Producers work to balance highs in Cheddar and butter against the backdrop of nonfat dry milk’s softer stance. Increases in cheese prices typically encourage producers to prioritize milk flow towards cheese production, seeing it as a beacon of profitability. Meanwhile, high butter margins push butter churns into overtime. 

These dynamic price movements set the stage for strategic decisions. Producers weigh whether to lock in current prices or brace for further shifts with each fluctuation. As they adjust operations, such as redirecting milk streams to more profitable products or enhancing milk yield, each decision must account for potential market reversals. Ultimately, these fluctuating prices are a reminder of the delicate balance required to maintain profitable margins amidst an unpredictable market landscape.

Shadows of Stagnation: Navigating the Global Dairy Supply Squeeze

The persistent milk supply challenges in the U.S. and globally continue to cast a long shadow over the dairy industry’s future. For the U.S., milk production has suffered more than a year of stagnation, an unusual scenario for an industry that prioritizes expansion and growth. On the international stage, the European Union and New Zealand echo similar trends with declining outputs. These concurrent contractions in supply are pitting against a backdrop of rising costs and fluctuating demand, exerting upward pressure on milk prices. 

This decrease in supply is a driving factor behind the surge in milk prices. U.S. milk output has waned compared to prior years, an anomaly in a nation renowned for its dairy prowess. High value is assigned to dairy components such as protein and butterfat, which have, somewhat ironically, helped offset the tangible drop in milk volume. Consequently, prices remain robust, buoyed by domestic and international demand that stubbornly persists despite the squeezing supply. 

So, what does this all mean for the future of the industry? For one, this limited supply presents a dichotomy of opportunity and challenge. Producers may enjoy elevated margins in the short term. Still, without an uptick in production, these margins could come under pressure as cost structures shift and market dynamics evolve. The bottleneck in heifer availability and the resultant slow herd growth add complexity to supply chain adjustments. Furthermore, the specter of climate impact on feed costs tightens its grip as unpredictability in weather patterns continues to affect output and costs. 

Overall, these supply constraints serve as a wake-up call for the industry, urging stakeholders to rethink sustainable production strategies. While high margins can offer a buffer today, maintaining them tomorrow requires innovation and adaptation in addressing both production and environmental challenges. The future depends on how swiftly and effectively the industry can navigate these turbulent waters and establish a new equilibrium in milk production and supply chain operations.

The Bottom Line

The dairy industry is witnessing an extraordinary economic shift as historically high milk prices and lower feed costs converge. September 2024 marked an era of unprecedented margins, offering a glimpse into a prosperous yet challenging landscape. While high profits present debt reduction and reinvestment opportunities, the road ahead is challenging. Low heifer inventories and rising interest rates could limit expansion. While U.S. milk production shows signs of recovery, global output remains subdued. As we navigate this intricate terrain, the choices made now will shape future profitability. 

What does this all mean for you? As dairy professionals, I know the implications of these trends are vast and varied. Could these high margins be a harbinger of sustainable growth or a temporary respite before market corrections? Please consider these questions and consider how they might influence your business strategies. Please share your insights, comment below, and engage with us. Your thoughts are invaluable as we collectively chart the course for the future of dairy. Let’s discuss it!

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Australia’s Dairy Industry: Forecasted Growth and Challenges Ahead for 2025

Delve into Australia’s 2025 dairy growth forecast. Will it triumph over dry conditions to increase cheese production? Gain insights for dairy experts.

Summary:

Australia’s dairy sector looks to a promising 2025, aiming for a 1.1 percent bump in milk production, reaching 8.8 million metric tons, following a 2.7 percent growth in 2024 despite challenges like dry conditions in key regions. Fresh milk consumption is set to reverse a five-year decline while factory milk use rises, boosting export potential in cheese and butter. Southwestern Victoria and South Australia face environmental hurdles, but favorable weather forecasts and stable feed grain prices may soften the blow. As the industry maneuvers through these complexities, technological and genetic advancements are vital in boosting productivity and efficiency for a competitive 2025. Experts highlight that record milk prices have driven growth, overcoming obstacles like high beef prices and labor shortages, showcasing the resilience and adaptability of Australian dairy farmers.

Key Takeaways:

  • Milk production in Australia is expected to grow by 1.1% in 2025, reaching 8.8 MMT, up from 8.7 MMT in 2024.
  • The dairy industry’s recovery is attributed to easing challenges like high beef prices and labor shortages post-COVID-19.
  • Victoria and South Australia, significant contributors to national milk output, face drought conditions impacting production forecasts.
  • Fresh milk consumption is predicted to increase by 0.4% in 2025, reversing a five-year decline.
  • Factory use of milk is on the rise, focusing on cheese production, which remains the largest consumer of fluid milk.
  • While butter production sees slight growth, exports for SMP, WMP, and butter are projected to moderate in 2025.
  • Technological advancements and genetic improvements have led to increased production efficiency.
  • Australia’s dairy exports face uncertainties, with a shift in dynamics expected for 2025.
  • Preparing for changes and adapting to challenges can offer strategic advantages to dairy farmers.
Australian dairy industry, milk production growth, fresh milk consumption, dairy export markets, skim milk powder production, whole milk powder stability, butter output increase, dairy production challenges, Victoria dairy leadership, agricultural sector contributions

The Australian dairy industry, a cornerstone of the nation’s agricultural sector, has shown remarkable resilience in recent years. Despite periods of declining production, it has emerged on a growth path, contributing significantly to the economy and sustaining countless livelihoods. With milk production forecasted to increase by 1.1 percent to reach 8.8 million metric tons in 2025, following a 2.7 percent rise in 2024, the industry showcases its strength. This is particularly impressive given the challenging dry conditions in vital dairy-producing regions. The future of Australia’s dairy farmers looks promising as they navigate growth aspirations amidst environmental hurdles. 

Australia’s Dairy Industry Rides the Wave of Recovery Amid Challenges 

Australia’s dairy industry is witnessing a noteworthy recovery. In 2024, milk production increased by 2.7%, underscoring a rebound after years of decline. This upward trend is expected to continue, albeit slower, with a forecasted increase of 1.1% in 2025. Several factors contributed to this growth, mainly the easing of previously pressing challenges, such as labor shortages, which had hindered productivity. Labor availability has notably improved, allowing farms to maintain operations more efficiently.

Furthermore, the relatively stable prices of feed grains play a crucial role in supporting this growth trajectory. Although consistent with the five-year average, the average feed grain prices provide a conducive environment for dairy farmers to plan better and sustain their herds, thereby supporting milk production levels. This stability in feed grain prices offers security for the industry’s future. 

Nevertheless, certain adverse conditions pose challenges to this growth projection. Dry weather patterns in key dairy-producing regions, especially southwestern Victoria and South Australia, threaten to curtail potential gains. These regions contribute significantly to the national milk output, and their exposure to prolonged dry spells poses a risk. The dry conditions can lead to reduced pasture growth, increased feed costs, and potential health issues for the cattle, which can directly impact milk production. For instance, reduced pasture growth means less natural feed for the cattle, leading to increased feed costs for the farmers. However, forecasts from the Australian Bureau of Meteorology suggest average to above-average rainfall in the upcoming months, which could mitigate the negative impacts of drought conditions and help stabilize the production outlook.

Signs of Revival: Fresh Milk Consumption Set for a Turnaround as Industry Strives for Stability 

The reversal in the decline of fresh milk consumption marks a significant trend shift within Australia’s dairy sector. After a sustained five-year period of decreasing consumption, a forecasted increase of 0.4 percent in 2025 to 2.47 MMT presents a positive outlook. This change indicates a renewed consumer interest in fresh milk, possibly driven by evolving market preferences and nutritional awareness. Fresh milk now represents 28.1 percent of the total milk production, emphasizing its vital role within the industry and instilling optimism for the future. 

Factory use of milk is simultaneously predicted to rise, progressing to 6.2 MMT in 2025 from an estimated 6.1 MMT in the previous year. This uptick aligns with the growth in overall milk production, supporting the industry’s strategic tilt towards factory-based applications, including a marked focus on cheese production. Over the past decade, the sector’s dedication to expanding cheese output has been evident, underscoring cheese as the largest consumer of fluid milk. Despite a dip in cheese production in 2024, projections for 2025 anticipate a rebound to 375,000 MT, reflecting the levels seen in 2023 and reinforcing cheese’s importance in maintaining industry stability and economic viability. 

Meanwhile, skim milk powder (SMP) and whole milk powder (WMP) production is expected to remain stable, vital in sustaining the export markets and meeting domestic demands without market volatility. The slight increase in butter output further complements this stability. Driven by enhanced exports in 2024, which depleted stock levels, butter production is poised to rise, indicating adaptive measures within the industry to balance inventory and market requirements. These trends portray a dynamic yet stable industry poised to leverage domestic consumption patterns, and strategic production focuses on securing future growth. These strategic production focuses include increasing the production of high-demand dairy products, such as cheese and butter, and maintaining stable SMP and WMP production to meet domestic and international demands.

Victoria’s Dairy Dominance: Navigating Climate Opportunities and Challenges

Victoria remains the unrivaled leader in Australia’s dairy production, contributing a substantial 63% to the national output. This dominance is mainly due to its favorable climatic conditions that support extensive pasture-based dairy farming. Within Victoria, regions such as the West Vic Dairy and Gipps Dairy thrive on natural rainfall, minimizing the need for irrigation. However, the Murray Dairy region in northern Victoria continues to grapple with challenges stemming from water scarcity. Increasing water prices and limited availability, driven by rising horticultural competition, compel producers to innovate. Dairy farmers here invest in more efficient irrigation systems and diversify their water sources to sustain production levels. 

Tasmania is integral to the dairy sector, contributing approximately 11% to the country’s milk output. Its cool, temperate climate and reliable rainfall provide an ideal setting for predominantly pasture-based dairy production. The island’s geographical isolation and distinct climate allow for a unique advantage in milk quality and production sustainability, further strengthening its position within the industry. 

New South Wales, accounting for 12.4% of the national milk production, primarily focuses on the central and southern coastal regions and the southern irrigation zones bordering the Murray Dairy territory. These areas harness natural rainfall and strategic irrigation to maintain productivity. Despite these advantages, the dependence on supplemental feed remains due to the variability in rainfall, prompting farmers to employ advanced techniques in feed management and herd productivity. These advanced techniques include precision feeding, where the nutritional needs of each cow are carefully monitored and met, and selective breeding to improve the herd’s productivity. These measures help farmers maintain and even increase their output despite the challenges of variable rainfall.

Leveraging Technology and Genetics: Australia’s Path to Dairy Production Efficiency

The evolution of technological and operational practices within Australia’s dairy sector reflects a significant shift towards increased supplemental feeding and genetic advancements. This transformation amplifies milk yield per cow, offering a robust pathway to enhanced productivity. As dairy farms increasingly incorporate supplemental feeds like grains, hay, and silage, cows can achieve higher production levels, mitigating the limitations posed by natural pasture availability. These adjustments align with ongoing efforts to maximize production efficiency across varying climatic conditions. 

Genetic advancements further underscore productivity gains, with a notable shift toward scientifically driven breeding methods, such as artificial insemination and genotyping. These techniques primarily focus on optimizing herd genetics, significantly improving average milk production per cow. The integration of U.S. genetics and the acceleration of genetic selection through advanced genotyping have collectively contributed to this upward trajectory in herd performance. 

Simultaneously, the dairy industry is witnessing a burgeoning interest in advanced housing and milking processes, particularly in the move towards free-stall barn systems and robotic milking solutions. These innovations address persistent labor shortages and provide an efficient alternative to traditional milking operations. These systems are gaining traction in northern Victoria and southern Queensland, regions conducive to fodder crop production and near-feed grain supplies. 

While the initial investment in robotic milking facilities may seem considerable, the long-term benefits include streamlined operations and reduced dependency on manual labor. Consequently, dairy farm operations benefit from enhanced ease of management as producers overcome the constraints of sourcing and retaining skilled labor. As these systems become more widespread, they may redefine operational norms in the dairy industry, reflecting an adaptive response to evolving economic and environmental landscapes.

Exports in Flux: Navigating the Complex Terrain of Dairy Trade Dynamics for 2025

The forecasted moderation in Australian exports for skim milk powder (SMP), whole milk powder (WMP), and butter in 2025 captures a nuanced interplay of global and local factors. While domestic production is set for minor growth, external markets are adapting to shifting demands and preferences. Notably, Australia’s primary export destinations exhibit diverse concerns affecting trade dynamics. 

Critical markets for Australian dairy exports, such as China and Southeast Asia, have begun to recalibrate their import strategies. For instance, China’s domestic dairy production capability has increased, reducing reliance on imports. Additionally, an apparent pivot in consumer preferences towards plant-based and alternative dairy options signifies subtle downward pressures on traditional dairy imports within these markets. 

The geopolitical climate also presents significant challenges on the global stage. Trade agreements and diplomatic relations shaped by regional disputes or policy shifts can directly impact Australia’s export volumes. Moreover, regulatory changes, such as stricter import controls or tariff adjustments in major dairy-consuming regions, could further throttle export growth, necessitating strategic pivots to sustain competitiveness. 

The evolution of global dairy production and supply chains simultaneously influences market dynamics. Major producing countries boosting their output could alter their competitive advantages, necessitating a reevaluation of Australia’s positioning within the competitive landscape. Furthermore, fluctuating global dairy prices, driven by supply chain disruptions or economic instabilities, exemplify pressures on Australian exports. 

Overall, the anticipated moderation in SMP, WMP, and butter exports outlines a multifaceted scenario in which Australia’s industry stakeholders must remain vigilant. This requires adapting to market signals and leveraging innovative strategies to bolster resilience amidst these evolving challenges.

The Bottom Line

The Australian dairy industry stands at a crossroads of renewal and challenge, demonstrating resilience against fluctuating production levels, climate conditions, and market demands. Despite dry weather concerns, there’s a forecasted increase in milk production for 2025, driven by advancements in technology and genetics. After years of decline, fresh milk consumption might revive, alongside steady cheese and butter production. As the industry faces moderate export prospects, the focus sharpens on enhancing domestic efficiencies. The question looming for Australian dairy farmers is how they can continue to innovate and adapt in an unpredictable global market. In preparing for the landscapes of 2025 and beyond, foster dialogue on strategies to mitigate environmental impacts and leverage technological advancements. Are the current measures enough to sustain long-term growth, or is a more profound integration of innovative practices pivotal? The steadfast adaptability of Australian dairy farmers will be crucial in navigating these emerging realities.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

China’s Dairy Dilemma: October Import Slump Raises Red Flags for Global Markets

Discover how China’s October dairy import decline affects global markets and your business. Learn about potential impacts on the dairy industry.

Summary:

As China navigates the delicate terrain of economic recovery and geopolitical challenges, its dairy import patterns paint a picture of unmet demand and market volatility. In October, significant declines were noted across various dairy categories; skim milk powder (SMP) imports plunged by over 53% year-over-year and marked a fourteenth consecutive month of decline despite a slight uptick from the previous month. Whole milk powder (WMP) imports mirrored this downward trajectory, falling nearly 16% compared to the prior October, tallying 34.2 million pounds in October 2024, which improved by 11 million pounds from September. However, imports provided a glimmer of positivity by increasing by 4.6%, reflecting the United States’ stable market share. The implications of these import slumps point to a complex dilemma of domestic herd management and international trade tensions, with looming tariff threats potentially compounding future uncertainties. Industry experts predict China’s diminished dairy herd and milk powder reserves might trigger a rebound in demand and import volumes. Still, external economic pressures could further strain global trade dynamics.

Key Takeaways:

  • China’s skim and whole milk powder imports continued to decline year-over-year in October, persisting a long-standing trend of weakened demand.
  • Whey imports surfaced as a positive standout, with a modest increase compared to the previous year.
  • China’s dairy herd reductions and lower whole milk powder inventories may catalyze increased import activity in future months.
  • Potential US tariff hikes on Chinese goods could disrupt trade dynamics, possibly affecting China’s dairy inventory replenishment strategies.
  • The United States maintained its market share for whey imports, aligning with its average from previous years.
  • Despite slight improvements in some areas, overall dairy import volumes for butter and cheese in China remained low, further exacerbating concerns over demand stability.
China dairy imports, global dairy market, skim milk powder decline, whole milk powder imports, China demand trends, dairy-exporting countries, dairy herd reduction, milk powder stockpiles, international trade relations, global dairy supply chain

China’s position as the world’s largest dairy importer casts a long shadow across global markets, making its purchasing power a critical barometer for industry health worldwide. However, the October dip in dairy imports isn’t just a blip on the radar; it’s a glaring red flag that demands attention. The figures paint a stark picture of declining demand, with skim milk powder and whole milk powder imports plummeting to record lows. This trend raises a critical question for dairy farmers and industry professionals: What does this mean for the future of the global dairy market? The declining imports reflect underlying challenges that could reshape market dynamics, pointing to a potential ripple effect across international markets. For those with a stake in the dairy industry, the implications of these figures are profound, demanding a strategic reevaluation of market forecasts and supply chain decisions. Adapting to the changing market conditions is crucial. How will this import slump influence your business strategies?

Dairy Declines and Economic Entanglements: Navigating China’s Import Challenges 

China’s recent dairy import figures are challenging, particularly for skim milk powder (SMP) and whole milk powder (WMP). As of October 2024, the figures reveal a significant year-over-year decline in SMP imports, falling over 53% to a mere 23 million pounds. While this marks the fourteenth consecutive month of decline, it’s noteworthy that there was a slight improvement from September, with an increase of nearly 2 million pounds. 

The situation is similar for WMP imports, which decreased by nearly 16% year over year. Despite this drop, there was a noticeable month-over-month recovery, with imports reaching 34.2 million pounds in October, an increase of 11 million pounds from September’s figures. 

The implications of these declining import trends extend beyond China’s borders, impacting the global dairy market. As the world’s largest dairy importer, China’s demand trends can significantly influence global prices and trade dynamics. Persistent declines could suggest weakening demand in China, potentially affecting export volumes and prices for major dairy-exporting countries. 

On the other hand, industry insiders anticipate that China’s smaller dairy herd and reduced milk powder stockpiles might soon lead to increased demand and a rebound in import volumes. However, external economic factors, such as proposed tariffs, could further complicate the picture by affecting international trade relations and access to Chinese markets. The potential for trade tensions exacerbating the situation underscores the need to navigate these challenges carefully.

Butter and Cheese Imbalance: Is China’s Dairy Demand Drying Up?

The data indicates an apparent stagnation in these markets when examining the performance of China’s butter and cheese imports. With butter imports slipping by 3% and cheese imports seeing a more pronounced decline of 12% compared to October of the previous year, these figures mark the smallest import volumes in recent history. The reduction in butter imports is especially notable as it represents the smallest quantity imported in three years. Meanwhile, cheese imports have been relatively high for over two years, indicating a significant downturn. 

The reasons behind these declines are multifaceted. On the domestic front, reducing consumer demand, possibly influenced by changing dietary preferences and economic uncertainties, could contribute. Additionally, the ongoing challenges in China’s dairy sector, specifically the reduced herd size and depleted milk powder inventories, might further suppress the need for imports. On a broader scale, geopolitical tensions, such as the potential imposition of tariffs by the US, could exacerbate the situation, threatening to constrict trade flows further. 

Historically, China’s dairy import levels have been a barometer of its economic health and consumer behavior. China’s demand for imported dairy products surged during previous economic expansion and rising consumer affluence. However, the current contraction in butter and cheese imports suggests a shift in this trend, raising concerns among international dairy exporters aiming to tap into the Chinese market. 

These import contractions also have significant ramifications for the global dairy trade. Exporting nations, mainly those heavily reliant on the Chinese market, might experience surplus stock or price pressures as demand wanes. Furthermore, the global dairy supply chain, already reeling from disruptions over the past few years, could face additional challenges if China’s demand does not recover promptly. 

Butter and Cheese: The Slipping Pillars of China’s Dairy Imports

The data indicates an apparent stagnation in these markets when examining the performance of China’s butter and cheese imports. With butter imports slipping by 3% and cheese imports seeing a more pronounced decline of 12% compared to October of the previous year, these figures mark the smallest import volumes in recent history. The reduction in butter imports is especially notable as it represents the smallest quantity imported in three years. Meanwhile, cheese imports have been relatively high for over two years, indicating a significant downturn. 

The reasons behind these declines are multifaceted. On the domestic front, reducing consumer demand, possibly influenced by changing dietary preferences and economic uncertainties, could contribute. Additionally, the ongoing challenges in China’s dairy sector, specifically the reduced herd size and depleted milk powder inventories, might further suppress the need for imports. On a broader scale, geopolitical tensions, such as the potential imposition of tariffs by the US, could exacerbate the situation, threatening to constrict trade flows further. 

Historically, China’s dairy import levels have been a barometer of its economic health and consumer behavior. China’s demand for imported dairy products surged during previous economic expansion and rising consumer affluence. However, the current contraction in butter and cheese imports suggests a shift in this trend, raising concerns among international dairy exporters aiming to tap into the Chinese market. 

These import contractions also have significant ramifications for the global dairy trade. Exporting nations, mainly those heavily reliant on the Chinese market, might experience surplus stock or price pressures as demand wanes. Furthermore, the global dairy supply chain, already reeling from disruptions over the past few years, could face additional challenges if China’s demand does not recover promptly.

Sounding the Alarm: The Shrinking Dairy Herd and Rising WMP Import Necessities

Industry insiders are warning about the notable reduction in China’s dairy herd, a move driven by the pursuit of short-term cost efficiencies. This strategic culling directly correlates with reduced dairy output, resulting in dwindling inventories of whole milk powder (WMP). As these inventory levels shrink, the necessity for increased imports becomes more pronounced. Analysts speculate that this trend could have significant implications for global dairy producers. 

An uptick in China’s WMP imports could spell lucrative opportunities for dairy exporters worldwide, particularly in countries like New Zealand and the United States. The need to replenish China’s depleted stockpiles could spur a surge in demand, potentially offsetting recent declines in import volumes. However, geopolitical factors like evolving tariff policies remain a wildcard that could bolster or hinder this anticipated increase. 

Global dairy markets are closely monitoring these developments. Any significant boost in demand from China could influence international milk powder prices, benefiting producers by lifting profit margins. However, such dependency also carries risks; an overreliance on China’s buying behavior could expose global producers to volatility stemming from regional policy shifts. The unfolding scenario underscores an intricate balance of supply, demand, and international trade relations that dairy stakeholders must navigate vigilantly.

Tariff Turmoil: Navigating the Coming Storm in Global Dairy Trade 

As the Trump administration moves toward imposing substantial tariffs on Chinese goods—potentially exceeding 60%—the ripple effects could severely impact the global dairy trade, especially between the United States and China. Such aggressive tariffs could trigger retaliatory measures from China, potentially escalating into a full-blown trade war restricting US exports across multiple sectors, including dairy products. This scenario would directly affect American dairy farmers and the broader agricultural economy, which relies heavily on Chinese purchases to maintain market stability. 

Moreover, imposing these tariffs might reduce the competitive edge of US dairy products by inflating their prices in the Chinese market and encouraging China to seek alternative dairy suppliers. Such a shift could have a long-lasting impact on US dairy exporters who have heavily invested in establishing and expanding their presence in the Chinese market. For those in the dairy industry, it begs the question: How resilient are your supply chains and market strategies in the face of such volatile geopolitical factors? 

The potential trade tensions underscore a broader issue: the interconnectedness of global markets and the delicate balance required to maintain healthy trade relationships. Dairy professionals and agricultural business leaders need to consider long-term strategic planning that accounts for possible political and economic disruptions. Could diversification into other markets or developing new product offerings provide a buffer against such uncertainties? 

In this context, industry stakeholders are encouraged to remain vigilant and proactive, assessing not only the immediate impacts of changes in trade policy but also preparing for the broader implications. The complexity of today’s global supply chains demands foresight and adaptability, placing a premium on informed decision-making and strategic agility.

China’s Strategic Diplomacy: An Olive Branch Amid Economic Crosswinds

China extends an olive branch to the United States amid growing global economic uncertainties. Vice Commerce Minister Wang Shouwen emphasized China’s willingness to engage in active dialogue with the US, anchored in the principles of mutual respect. This move aims to foster the development of bilateral economic and trade relations. Wang articulated China’s intent to “expand areas of cooperation and manage differences” with Washington, reflecting a proactive stance in fortifying economic ties. Addressing concerns over impending tariffs from US President-elect Donald Trump, Wang remarked that China possesses the capability to “resolve and resist” the impact of external shocks. 

The Blacklist and Beyond: Navigating the New World of Dairy Trade Amidst Geopolitical Tensions 

The implications of these developments extend beyond political rhetoric, signaling a critical shift in international trade dynamics. The expansion of the blocklist to over 100 entities is not just a number; it’s a clear testament to escalating tensions and a deepening divide between two of the world’s largest economies. How will this affect the dairy trade, especially for those companies striving to navigate these choppy waters? As agricultural entities in China face increasing scrutiny, could there be ripple effects that influence global markets, potentially altering supply chains and trade agreements? 

For the dairy industry, particularly those engaged in exporting to China, this blocklist expansion means more than just heightened awareness. It could necessitate reevaluating market strategies and supply networks. The agricultural sector, heavily implicated by this blocklisting, will face increasing pressure to address ethical production practices or risk losing critical partnerships. Yet, there’s also an opportunity here. Companies demonstrating compliance and ethical sourcing could position themselves as preferred partners amid geopolitical uncertainties. 

This move highlights the intricate interplay between ethics and economics. Understanding these nuances could be pivotal for dairy professionals in decision-making processes. As the US tightens its stance, will companies be prepared to innovate and adapt, ensuring resilience against such geopolitical shocks? It’s a challenge worth contemplating, as the implications could reshape dairy exports and the fabric of global agricultural trade.

The Bottom Line

The global dairy market faces uncertainty as China’s import patterns fluctuate, with notable declines in crucial commodities like skim and whole milk powder, butter, and cheese. Imports have waned due to diverse factors, ranging from domestic herd reductions to economic and political intricacies. Meanwhile, potential trade tensions, such as the looming tariffs from the US, could further disrupt supply chains and market dynamics. 

The notable exception remains in whey imports, suggesting a silver lining with potential for growth and adaptation. This raises a critical question: Are dairy producers and allied businesses prepared to navigate the unpredictable waters of international trade amidst these shifting currents? The future of dairy trading hinges on this preparedness, urging industry stakeholders to remain vigilant, strategic, and innovative in the face of evolving challenges.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Dairy Market Forecast: Competitive Pressures Ahead

Uncover November 2024 dairy market trends. Can rising milk output keep profits up as bearish winds blow? Find strategies to tackle these challenges.

Summary:

The dairy industry confronts a pivotal moment as 2024 ends, grappling with rising powder prices and diminishing cheese values. This nuanced market landscape demands astute navigation from dairy farmers and industry professionals. Significant milk production growth in the U.S. and EU, driven by increasing cow numbers and improved milk components, raises the critical question of whether global demand can rise to match this supply surge without further eroding butter and cheese prices. The Global Dairy Trade (GDT) auction reflects this tension, with an overall 1.9% price increase, notably in Whole Milk Powder (WMP), yet a drop in cheese prices suggests an imbalance between production and market consumption. With headline production up by 0.2% in September and a robust 1.4% in October, heightened supply challenges the industry to align with modern consumer preferences. As the holiday season approaches, the emphasis remains on vigilant market analysis to anticipate potential price shifts.

Key Takeaways:

  • Global Dairy Trade showed a modest increase, but sentiment in key regions remains bearish despite positive GDT trends.
  • Milk production is growing in both the U.S. and EU, with increasing herd sizes contributing to the rising supply.
  • The growth in milk components adds further complexity to production and pricing, potentially impacting market balance.
  • Cheese market faces challenges with strong supply growth and weak current demand, awaiting a future market upswing.
  • The butter market outlook remains bearish, with ample supply and demand matching closely to retail expectations.
  • Powder prices exhibit weakness, although there is still some global demand for NFDM/SMP which may stabilize prices.
  • Producers and traders should prepare for quieter markets as the year-end holidays approach, impacting trading activities.
  • Strategic planning and agility will be crucial to navigate year-end challenges in the dairy market effectively.
dairy market trends, milk production increase, Global Dairy Trade auction, Whole Milk Powder prices, cheese price decline, U.S. dairy sector growth, consumer demand for dairy, plant-based alternatives, market analysis for dairy, holiday season purchasing patterns

Is the dairy market poised for a breakthrough, or are we on the brink of a price collapse? Understanding the intricate dynamics of the dairy market is crucial for farmers and professionals navigating this landscape. With global trends revealing a 0.2% increase in milk production across the U.S. and EU, coupled with an uptick in component adjustments, it’s clear that milk production is ticking upwards. However, despite the rise in global dairy trade (GDT) prices by 1.9%, the sentiment in major markets like the U.S. and EU remains bearish. The dairy industry stands at a crossroads where production growth meets skeptical demand. This scenario requires vigilant market analysis as we explore whether current production surges can be matched by demand without further destabilizing prices. Navigating this complex web of market signals is essential for strategic decision-making as we dissect the trends and sentiments shaping the dairy market today. 

Global Dairy Trade: A Balancing Act of Rising Powder and Sinking Cheese Prices

The recent Global Dairy Trade (GDT) auction results have showcased a modest, noteworthy overall increase of 1.9%. In particular, the rise in Whole Milk Powder (WMP) prices stands out, suggesting a shift towards higher demand or tighter supply conditions for this pivotal dairy product. Conversely, the decline in cheese prices highlights a mismatch between production growth and actual market uptake. This duality paints a complex picture for dairy markets worldwide. While WMP’s upward trajectory might indicate bullish outlooks in some regions, the softer cheese prices are a cautious reminder of potential oversupply – especially within the backdrop of significant milk production hikes in the U.S. and EU. As the global demand landscape evolves, these auction results underscore the intricate balancing between supply increase and market consumption. 

Churning Out Growth: Navigating the Challenges of Surging Milk Production

The latest statistics vividly show milk production growth across the EU27+UK and the U.S. The EU27+UK headline production rose by a marginal 0.2% in September. Still, when adjusted for components, the growth rate stands at a more robust 1.1%. Similarly, the U.S. reflects a steady increase; headline production in October is up by 0.2%, while component-adjusted figures reveal an even healthier 1.4% uptick over the same period. 

What truly stands out is the U.S. dairy sector’s addition of 46,000 cows in recent months. This increase in herd size is a clear indicator of expanding capacity, which invariably impacts market dynamics. As production levels rise, the market faces the challenge of balancing this heightened supply against consumer demand. A surge in supply typically applies downward pressure on milk prices, albeit temporarily, if not matched by equivalent growth in demand. 

Given these production trends, the market anticipates potential price fluctuations. The robust supply from both sides of the Atlantic could strain current prices unless a significant demand uptick is met. While increased output holds promise for economies of scale and potential profitability, it also necessitates caution against oversupply risks that might lead to price depreciation. Thus, market participants must remain vigilant and agile, ready to adjust strategies to navigate these shifting dynamics effectively.

Walking the Tightrope: Will Demand Match the Milk Supply Surge? 

The dairy market’s current landscape poses an inevitable question: Can demand keep pace with increasing milk supply without forcing prices into a downward spiral? This delicate balance largely hinges on global economic conditions and prevailing consumer trends. On one hand, we see pockets of economic resilience, even as some regions grapple with inflation and low consumer confidence. These economic nuances dictate purchasing power and demand for dairy products. 

Furthermore, evolving consumer preferences play a pivotal role. More consumers opt for plant-based alternatives, influenced by health considerations and environmental awareness. Yet, the demand for traditional dairy remains robust in regions that embrace dietary staples like milk, cheese, and yogurt. Understanding these dynamics is crucial for industry stakeholders. It requires keen foresight to gauge shifts and strategically position production and marketing efforts. Ultimately, the industry’s ability to align supply with demand amidst such variability remains a challenging yet critical endeavor.

Cheese Sector at the Crossroads: Will Supply Surge Outpace Tepid Demand?

The cheese market is navigating troubled waters as bearish sentiments overshadow recent upticks in average CME spot cheese prices. This paradox arises from a supply surge driven by the robust milk production in states bolstered by the presence of new cheese manufacturing facilities. The market feels the weight of this increased output, challenging the upward momentum seen in recent price trends. 

Notably, the expansion in these particular regions amplifies supply pressure at a time when demand appears tepid. The increased availability of milk undeniably supports cheese production but also raises the stakes. Market actors brace for potential price adjustments as supply outpaces the current demand landscape. 

The potential for demand recovery remains a critical factor. Although current demand appears subdued, any uptick could swiftly alter market dynamics. A revival of consumer interest or industrial demand could inject much-needed energy into the market, potentially reversing the bearish outlook. This interplay between supply exuberance and demand stagnation highlights the cheese market’s precarious position, leaving stakeholders watchful and poised for any shifts.

Butter’s Forecast: When Cream Turns into a Conundrum

The U.S. butter market is currently cloaked in a shadow of bearish sentiment, and its short-term outlook struggles to find a ray of hope. A large part of this comes from the heavy production levels that are overwhelming supply channels. Despite the festive season, traditionally marked by a spike in demand, retailers seem to have stocked up sufficiently well ahead of time. While generally prudent, this preparedness leaves little room for any usual holiday-driven price bounce. 

The weight of excess cream, a byproduct, often signals an oversupply situation, compounding the issue. It has led to a bulky stockpile that is pulling butter prices down. With warehouses full and demand not moving at its usual brisk pace, the market is in a holding pattern. These factors coalesce into a constellation of oversupply and muted demand, creating an environment where finding upward price momentum is challenging. 

Ultimately, while the holiday season typically offers a glimmer of hope for price recovery through increased consumer use of butter, the current outlook suggests that producers must wait longer. The market must work through this surplus before any significant reprieve from declining prices can be expected.

The Powder Predicament: Navigating the NFDM/SMP Price Puzzle

The powder markets present a perplexing scenario. NFDM/SMP prices are noticeably weak across all regions. Despite generally good global demand, the price dynamics could be more optimistic. What factors are contributing to this market softness? 

Firstly, while demand remains robust, regional disparities exist. Areas with solid import needs do not uniformly affect global price stability. For instance, burgeoning markets in parts of Asia and Africa may need to counterbalance the subdued demands elsewhere fully. 

Furthermore, production levels have continued to rise, potentially outstripping current demand. The Southern Hemisphere is entering a period of increased production capacity just as the Northern Hemisphere reaches peak output hikes. This oversupply could be a central element holding back price increases despite unfavorable demand. 

Several potential factors might be considered to see a reversal in this trend. A few scenarios seem plausible for NFDM/SMP prices to stabilize or climb. A significant uptick in import activities from essential international buyers could surge demand. Similarly, geopolitical developments affecting trade tariffs and export capabilities might alter the current supply-demand relationship, leading to upward price pressures. 

In some regions, weather patterns impacting production capabilities or logistic challenges could shift supply dynamics, creating localized shortages that benefit global pricing structures. Monitoring these variables will be crucial for stakeholders who navigate these tumultuous waters.

Year-End Strategy: Navigating the Dairy Domain with Agility and Insight 

Strategic vigilance becomes crucial for dairy farmers and industry professionals as we approach year-end. The current landscape is marked by fluctuations in the global dairy trade, with noticeable supply and demand dynamics shifts. Farmers should prioritize closely monitoring market trends to anticipate any changes in price movements, mainly because the impending holiday season could influence purchasing patterns. 

It’s essential to maintain operational agility. This means adjusting production levels or product focus in response to the ever-shifting market conditions. Given the bearish undertone in the cheese and butter sectors, staying informed about consumer demand and market prices can position businesses to capitalize on emerging opportunities or mitigate potential risks. 

Furthermore, dairy industry professionals should consider diversifying their product offerings or exploring new markets to mitigate market volatility. Agile thinking and swift adaptability will be critical assets as we navigate this complex market environment. Proactive rather than reactive could ultimately dictate the difference between profit and loss as we round out 2024.

The Bottom Line

The unfolding market dynamics present a convoluted picture, with cheese prices teetering amidst robust milk production. At the same time, butter remains subdued and predictably lackluster. Savvy navigation is crucial as demand patterns shift and production scales. Staying abreast of these fluctuations isn’t optional; it’s imperative. The looming question remains: How will dairy professionals adapt to this era of saturation and volatility? As we venture into this complex future, the ability to anticipate and react could make or break the resilience of the dairy industry. Will you rise to the challenge?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Resilient Dairy Surge: U.S. Milk Output Climbs Despite California Hurdles

How does U.S. milk production rise despite California’s setbacks? Can farmers maintain growth? Uncover key insights and trends.

Summary:

The USDA Milk Production report highlights unexpected growth as the dairy industry braces for unpredictable currents. U.S. milk output climbed by 0.2% year-over-year in October despite California’s avian flu challenge, which significantly dented production levels. Nationwide, producers adapted by leveraging strong market signals to expand strategically. While California saw a 3.8% decline, states like Idaho and Texas reported gains, underscoring the industry’s resilience amidst market challenges. The increase in cow numbers and improved yields have been pivotal, with a notable addition of 46,000 cows to herds in the last quarter. Meanwhile, dairy markets, particularly Class III milk futures, have experienced restrained shifts, with spot butter prices slightly dropping due to ample availability. As global trade dynamics shift, China’s milk equivalent imports significantly impact international transactions, making it a key player in the evolving dairy market landscape.

Key Takeaways:

  • The U.S. milk production saw a modest increase of 0.2% in October 2024, driven by a rise in cow numbers and herd expansion.
  • California faced a significant production decline of 3.8% due to the highly pathogenic avian flu strain H5N1 affecting yields and herd size.
  • Despite challenges in California, other central dairy states like Texas, Idaho, New York, and Michigan experienced production gains.
  • High milk prices encouraged producers to increase output, overcoming barriers to expansion with effective strategies.
  • The dairy markets displayed caution as the industry navigated increased production amidst varying regional performance.
  • China’s declining milk equivalent imports indicate a shift in global dairy demand, impacting market dynamics.
  • Future projections suggest continued growth in U.S. milk production, contingent on California’s recovery and nationwide performance improvements.
plant-based milk alternatives, dairy milk nutrition, protein content in milk, sugar levels in milk alternatives, vitamin D in dairy, calcium in milk, consumer preferences dairy, health-conscious milk choices, organic milk benefits, dairy industry trends

In the face of daunting challenges, U.S. milk production has showcased remarkable resilience, defying expectations even as California—America’s dairy powerhouse—struggled. Recently, the USDA’s eagerly awaited milk production report for October revealed that national volumes managed a modest, yet significant, increase. This report marked a pivotal moment in the industry and invited a closer examination of the underlying dynamics fueling this unexpected growth. Despite regional hurdles, the national dairy herd has expanded, and yields have seen improvements, hinting at strategic adaptations by producers nationwide. By delving deeper into rising cow numbers, improved yields, and regional disparities, we can better understand how the nation’s dairy industry continues to thrive under pressure. It’s a testament to the adaptability and tenacity of those driving milk production forward.

California’s Crisis: A Ripple Effect Across the U.S. Dairy Sector

California’s struggles have sent shockwaves through the national dairy landscape, primarily driven by the adverse effects of the highly pathogenic avian flu strain H5N1. As the largest dairy-producing state in the U.S., California historically leads the charge in milk output. However, the relentless grip of H5N1 has severely impeded this powerhouse. A notable decline in cow numbers and slumping yields has culminated in a staggering 3.8% year-over-year decrease in milk production. 

The impact of the avian flu resonates far beyond poultry, affecting broader agricultural operations. This has resulted in a tangible reduction of 4,000 cows in California this October alone. This statistic signals the grim reality facing producers. Moreover, yields in the Golden State have diminished by 3.6% compared to last year, adding another layer of complexity to this crisis. 

California’s centrality to the U.S. dairy sector cannot be overstated. Any fluctuation in its production has a ripple effect, influencing national output and market dynamics. This decline occurs as the rest of the nation seeks stability and growth in milk production amid fluctuating prices and demand. 

The broader implications are significant: As California grapples with these challenges, other states must intensify their efforts to balance the national scales. Yet the question looms: Can they sufficiently compensate for California’s downturn? This evolving narrative demands our attention, as the outcomes could reshape the competitive dynamics of the dairy industry across the United States.

Resilient Herds and Strategic Growth: The Unsung Heroes of U.S. Dairy’s Rebound

Amid California’s significant production decline, the U.S. dairy industry demonstrated resilience, largely thanks to several key growth factors. One major contributor to the national uptick in milk production is the increase in the dairy herd. After months of stagnation, dairy farmers across the country added approximately 46,000 cows to their herds in the last quarter, driving the national herd to levels not seen since early 2023. This strategic expansion has been pivotal in sustaining overall production levels despite regional setbacks. 

Alongside the rise in cow numbers, improved yields per cow have also played a critical role. Nationally, yields rose modestly but meaningfully, with each cow contributing more milk than in previous months. This incremental gain in productivity has been vital in offsetting the volume deficits seen in regions like California. 

States such as Texas, Idaho, and New York have exemplified how diversifying strategies can mitigate localized downturn impacts. Their efforts, particularly in Texas, have resulted in an 8.8% year-over-year increase in October volumes. This strategic growth, driven by efficient herd management and investment in technological advancements, offers a beacon of hope for the industry’s future. It shows that even in the face of challenges, the U.S. dairy industry can adapt and thrive. 

These contributions underscore a strategic recalibration within the U.S. dairy industry that capitalizes on high milk prices and robust demand to drive growth. This adaptability has allowed dairy farmers to navigate and often thrive despite the substantial environmental and health crises impacting key production areas like California.

Steadying the Ship: Dairy Markets Navigate with Caution Amidst Production Gains

The milk production report has had a noticeable yet restrained influence on dairy markets, particularly concerning Class III milk futures. The market reaction was muted, reflecting a degree of anticipation as trends hinted at production stabilization. With 1,691 contracts traded, the figure was lower than expected, indicating some market participants had perhaps already priced in the increases in milk production. 

The Class III market’s subdued reaction might signal a cautious approach from traders bracing for further data or adjustments in the forthcoming USDA updates. This caution is mirrored in spot prices, where stability is the current theme. Spot butter prices, which refer to the current market price for immediate butter delivery, fell slightly, indicating ample availability but also suggesting buyers are wary of pushing prices too low with the year-end in sight. 

Looking at forward premiums, the present environment might lead to a gradual reduction. This potential trimming reflects confidence in the supply chain’s ability to meet demand without artificially inflating prices. The broader trends underline this sentiment, showing that while the production figures indicate growth, they align with gradual, rather than explosive, expectations. 

Overall, the report fits within the broader market trends, suggesting a period of adjustment as the industry recalibrates in response to favorable production conditions outside of California and cautious market behavior. The implications for the coming months indicate that while optimism in supply remains, prudence in trading strategies will likely prevail.

China’s Shifting Demand: A Catalyst for Global Dairy Trade Evolution

As the global dairy market evolves, China remains a pivotal player, with its milk equivalent imports significantly impacting international trade dynamics. In October, these imports decreased by a remarkable 10.7% compared to the previous year. While this decline is at the lower end of anticipated figures, the consistent reduction over 15 consecutive months suggests a complex interplay between supply constraints and demand fluctuations within China. 

This downward trend in Chinese imports has had reverberating effects on the global stage. With China’s demand dwindling, exporters worldwide are recalibrating their strategies, and the U.S. dairy sector is no exception. Reduced Chinese imports could build inventory in other regions, prompting competitive pricing strategies and strategic shifts in export destinations. 

For U.S. dairy producers, these global shifts offer both challenges and opportunities. On the one hand, the reduced Chinese market might pressure American exporters to identify alternative markets or risk surplus. On the other hand, the potential stabilization or uptick in Chinese demand—evidenced by North Asia’s increased activity on the Global Dairy Trade (GDT) platform—could open doors for renewed partnerships and expanded exports. 

Domestically, U.S. producers may need more flexible production strategies to align with these global dynamics. This could involve enhancing production efficiencies, diversifying product offerings, or investing in market intelligence to anticipate international demand trends better. As the world’s dairy landscape shifts, U.S. strategy will inevitably hinge on the ability to adapt and anticipate changes in global market flows.

The Bottom Line

The October milk production report underscores a narrative of resilience and strategic innovation within the U.S. dairy industry. Despite formidable challenges, especially in California, producers nationwide have demonstrated adaptability. They have managed modest national output growth by focusing on herd expansion and leveraging high prices to increase production. This semblance of progress hints at their capacity to rise above adversities like the avian flu, which has impacted Californian yields. 

However, this presents the question: How will the U.S. dairy sector navigate future disruptions while capitalizing on emerging opportunities? As we mull over this query, it becomes crucial for professionals in the field to assess their operations critically. What adjustments are necessary to ensure survival and prosperity in this ever-evolving landscape? Understanding these dynamics and adapting strategies will determine resilience in imminent market fluctuations.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Class IV, Butter, and NFDM Set New Limits Amid Market Volatility: What’s Next for Dairy Farmers?

How will expanded limits on Class IV, Butter, and NFDM impact dairy farmers amid market shifts?

Summary:

Today marks a significant shift in the dairy futures market, with Class IV, Butter, and Nonfat Dry Milk (NFDM) reaching expanded limits that have drawn the attention of dairy professionals. These developments follow volatility in Class III and Cheese futures, where low points have rebounded due to substantial trading volumes. The Global Dairy Trade auction could significantly influence international dairy markets, with a predicted 3.4% index increase supported by favorable New Zealand pasture growth. Meanwhile, the upcoming October Milk Production report is expected to highlight disruptions from avian influenza in California, affecting U.S. dairy output, particularly in NFDM production. As the industry grapples with these dynamic conditions, stakeholders must strategically navigate immediate challenges and opportunities for long-term resilience.

Key Takeaways:

  • Class III and Cheese futures have shown a notable rebound, with a significant price increase following a period of decline.
  • Futures trading volumes for Class III and Cheese have seen fluctuations, reflecting market volatility and the impact of spot price stability.
  • The Global Dairy Trade (GDT) auction is anticipated to influence price trends, with expectations of a potential index increase.
  • California’s avian influenza outbreak is expected to affect October milk production figures, causing a downward trend in national growth rates.
  • Component analysis reveals a deceleration in fat and protein content growth compared to previous months, notably in California and the Pacific Northwest.
  • There is mixed performance in Class IV Milk, Butter, and NFDM futures, with NFDM maintaining stability amidst supply concerns in California.
  • The future outlook hints at supply chain challenges and the potential for global trading partners to adjust their powder inventory strategies.
dairy industry trends, Class IV milk limits, butter market analysis, nonfat dry milk production, Global Dairy Trade auction, California dairy challenges, avian influenza impact, milk production report, dairy price projections, supply and demand dynamics

Amidst the swirling eddies of market volatility, the dairy industry is witnessing a seismic shift with the expanded limits on Class IV, butter, and nonfat dry milk (NFDM). These changes are not mere figures on a graph; they are a wake-up call for dairy farmers and industry professionals who navigate the ever-fluctuating tides of supply and demand. As the faces behind the farm gate and decision-makers at the helm of industry giants see their margins pinched by oscillating prices and unpredictable futures, these developments have emerged as a beacon for strategic realignment and market adaptation. A seasoned market analyst recently noted, “Markets are pricing new realities – it’s time to adapt or be left behind” during an industry roundtable. This recalibration in limits ushers in significant implications, acting as both a barometer of market moods and a determinant of economic strategies that can fortify or crumble milk producers’ profitability. It calls for an agile approach, prompting industry stakeholders to rethink their short-term operations and long-term plans, with renewed limits highlighting the need for risk management strategies and sparking discussions on the future of dairy market negotiations and collaborations.

CommodityCurrent PricePrice Change (Last Week)Market TrendVolume
Class III Milk$17.50+$1.42Rising3,000 contracts
Class IV Milk$20.00StableMixed150 contracts
Butter$2.55-0.05Declining200 contracts
NFDM$140.00+0.50Stable500 contracts
Cheese$1.70FlatBullish Bounce530 contracts

Rolling Tide of Change: Navigating Class III and Cheese Futures 

Today’s dairy market illustrates a dynamic interplay between Class III and cheese futures, underpinned by recent bearish trends that have injected a dose of volatility into trading. Over the past month, traders have witnessed a consistently bearish sentiment in these markets, with considerable drops to new lows. These declines, however, were sharply counterbalanced by ‘bear bounces’—a term used to describe swift, significant upticks in prices following a downtrend. 

On Friday, the robust trading volume exceeding 3,000 Class III futures underscored the market’s resilience as it rebounded from new lows. This reflects ‘bear bounces,’ where the market reacts swiftly, resulting in considerable price movements in a short period. As prices have climbed back, trading activity has seen some contraction, with reduced volumes indicating cautious optimism among future investors as they assess the stability of spot markets around the $1.70 mark. 

With its penchant for reacting to market sentiments and upcoming economic indicators, the futures market is buoyed by expectations of supportive outcomes from global dairy auctions and production reports. As such, stakeholders are keen on potential developments that could further influence these fickle markets. The story of Class III and cheese futures is one of volatility underscored by rapid recoveries, challenging market participants to stay vigilant in navigating the complexities of this evolving landscape.

Global Dairy Trends: The Rising Tide of Opportunity

The upcoming Global Dairy Trade (GDT) auction holds significant potential to influence global dairy markets, with projections indicating a possible 3.4% rise in the index. This anticipated increase follows signals from the recent pulse auction, where Whole Milk Powder (WMP) and Skim Milk Powder (SMP) prices exhibited a positive trend. Such developments are integral for understanding the shifts in market dynamics as commodity prices play pivotal roles in shaping global dairy trade patterns. The potential of the GDT auction offers a ray of optimism in an otherwise volatile market. 

Moreover, the supportive New Zealand (NZ) pasture growth index lends additional credence to the expected uptick in dairy prices. For months, this growth index has surpassed last season’s figures and the five-year average, suggesting favorable conditions for dairy production in one of the world’s leading dairy-exporting countries. As pasture growth is a critical determinant of milk supply, its robust performance is likely to bolster market confidence and future price stability. 

These indicators present dairy farmers and industry stakeholders with a dual opportunity: to capitalize on potentially higher prices and to reassess production strategies in light of shifting global supply and demand. Therefore, the forthcoming GDT auction isn’t merely a price-setting event but a barometer for the broader landscape of international dairy trade. The results of this auction could significantly influence global dairy prices and trade patterns, providing valuable insights for industry stakeholders.

Anticipating Shifts: The Impact of Avian Influenza on October Milk Production

The eagerly awaited October Milk Production report is poised to reveal notable disruptions, chiefly attributable to avian influenza’s deleterious impact within California, a critical contributor to U.S. dairy output. This outbreak couldn’t have come more inopportunely, as the national scene witnessed a commendable rebound in production figures, shifting from a 1.7% downturn in June to a modest 0.4% uptick by August. However, the arrival of this viral adversary in late August has notably impeded California’s productivity, inevitably casting a shadow over national statistics, projected to dip by 3% or more due to this localized decline. 

Beyond raw volume, the underlying composition of milk has also captured attention, particularly as anecdotal insights underscore a striking ascent in fat content during October. Milk orders from Federal Marketing Orders reported an average fat content surge of 4.22%. Yet, this increment marks a slowdown from the more vigorous growth rates charted in August and September. This trend mirrored across most federal jurisdictions, denoting a significant deceleration. 

Protein levels, another vital metric, have paralleled fat content’s trajectory, edging upward by 0.8% from the previous year. While commendable, this growth remains pale compared to prior months, notably faltering within California and the PNW realms. The forthcoming report will indubitably serve as a litmus test for the industry’s resilience in the face of regional adversities. It will likely recalibrate expectations as the sector grapples with these unforeseen challenges.

Markets in Motion: Class IV Milk, Butter, and NFDM in the Balance

The landscape of the Class IV milk, butter, and NFDM markets reveals a tapestry of nuanced movements and underlying factors. The Class IV milk futures exhibit a steady to mixed trend, reflecting a market carefully balancing supply dynamics and future expectations. In contrast, butter futures have experienced a downward trend. This shift underscores the interplay between current consumer demand and producers’ readiness to place bids. The $2.50-$2.65 trading range, characteristic of last year’s period, presents a congestion zone, hinting at potential support levels amidst abundant cream supply and anticipated slowdown in seasonal sales. 

Meanwhile, NFDM stands on a plateau of stability, with prices rooted firmly around the $140 mark. This consistency suggests the market’s current contentment with its pricing amidst subdued immediate demand and looming supply concerns linked to California’s milk production challenges. In 2023, California plants were responsible for half of the nation’s NFDM/SMP output. Therefore, it is no surprise that recent disruptions in production have had a significant impact. However, the narrative is complete by considering the potential rise in demand as international trading partners deplete their existing, less costly inventories, offering a glimmer of hope in the market.

California’s Dairy Dilemma: Navigating Avian Influenza and Supply Chains

California, a pivotal player in the dairy industry, faces significant supply-side challenges that impact NFDM production. Compounding pressure from avian influenza exacerbates the state’s dairy sector, which was already responsible for half of the nation’s NFDM/SMP output in 2023. This situation constrains California’s milk production capacity, reducing supply, which inevitably reverberates through the NFDM market. The concern lies in meeting market needs while navigating these headwinds. 

Concurrently, as global trading partners exhaust their stocks of inexpensive powder inventories, potential shifts in demand could alter the market landscape. This depletion breeds an environment ripe for increasing demand, which could drive prices upwards if supply remains constrained. The observation here indicates a complex interplay between dwindling supply and the speculative rise in demand as international markets adjust to their inventory realities.

The Bottom Line

The dairy market presents a dynamic tableau of shifting trends and emerging challenges, demanding a strategic recalibration from industry stakeholders. Class III and Cheese futures have shown momentary buoyancy, highlighting the volatility that market participants must navigate. Meanwhile, global dairy trends signal a surge in opportunities, creating landscapes ripe for strategic exploration. However, the unforeseen impacts of avian influenza, particularly in California, underscore the susceptibility of production chains to biological threats, complicating supply forecasts and necessitating agile responses. 

The future remains uncertain yet promising as markets swell and recede with the motion of macroeconomic tides. How will dairy farmers and professionals adapt their strategies to leverage market fluctuations, and what concrete steps can be taken to hedge against unforeseen disruptions? The key to thriving lies in balancing production and demand scales, incorporating innovative processes, and fostering resilience. 

Consider this: How can the evolving landscape be turned into an advantage, ensuring sustained growth and profitability amidst inevitable market shifts? Will technology and innovation pave the way for a transformative leap forward in dairy operations, or will traditional methods prevail? 

Engage with the transformative forces shaping your industry. Evaluate, strategize, and act—because the future of dairy is written by those who dare to question and adapt. Where do you stand amidst the shifting sands of the dairy industry? Let’s shape the narrative together.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Global Milk Production on the Rise: How Top Exporters Overcame Challenges in 2024

How did top milk exporters boost production in 2024 amidst disease and market fluctuations?

Summary: 

Despite significant challenges, global milk production is growing among leading exporters, buoyed by rising prices and market adjustments. While European output remains nearly constant with previous years, the UK’s gains slightly drive regional growth above 2023 benchmarks. Conversely, Bluetongue disease significantly impacts Germany and the Netherlands, though recoveries in France, Ireland, and Spain provide a counterbalance. Oceania’s notable production surge offers compensation for Argentina’s downturn. The world’s top five dairy exporters recorded a modest 0.4% production increase compared to September 2023 amid ongoing trade market shifts and efficiency drives. The dairy sector must now navigate disease, high costs, regulatory challenges, and unpredictable weather patterns, which impact food security and economic stability. Leading exporters are urged to pursue strategic innovations to uphold and further propel their output levels. 

Key Takeaways:

  • European milk collections dipped slightly, with the overall output on par with the previous year, highlighting regional disparities influenced by disease and conditions.
  • Despite setbacks in northern Europe due to Bluetongue disease, gains in countries like France helped stabilize Europe’s milk production.
  • Oceania significantly boosted global milk production, counteracting deficits in Argentina and highlighting its growing role in the international market.
  • Top milk exporters collectively improved output by 0.4% from the previous year, signaling resilience amidst ongoing challenges like herd reduction and volatile markets.
  • Projected price increases for dairy products are anticipated to foster more robust milk production practices and encourage growth despite existing hurdles.
  • The global milk production trend remains below figures in the early 2020s, pointing to persistent obstacles, yet opportunities for adaptation and advancement remain ripe.
milk production, dairy-exporting nations, global trade, food security, milk prices, operational costs, environmental regulations, weather patterns, milk market volatility, sustainable farming practices

In a world where milk is more than just a staple beverage—it’s an economic powerhouse—understanding the ebb and flow of its production becomes crucial. The ripple effects of changes in milk output extend far beyond the borders of dairy farms, impacting global trade, food security, and economic stability. As the demand for milk continues to surge, how are the world’s top exporters tackling the myriad of challenges that threaten their supplies? What does it take to keep the milk flowing in a world of hurdles? Dive into the complexities of navigating disease, shifting markets, and climatic adversities—an essential journey for every stakeholder in the dairy industry. 

Churn Through Challenges: The Resilient Rise of Global Milk Production in 2024

The global milk production landscape in late 2024 reflects a cautiously optimistic trend, particularly among leading exporters. Despite numerous challenges, the industry has shown remarkable resilience. A slight uptick in milk output has been observed, with the top five dairy-exporting nations collectively increasing their production by 0.4% compared to the previous year. This modest growth is a testament to the industry’s ability to overcome hurdles and adapt to changing conditions.  The UK’s Department for Environment, Food, and Rural Affairs attributes this uptick to favorable market dynamics that have recently increased milk and dairy prices. These price increases are expected to incentivize production efforts despite the industry’s historical barriers to rapid growth. Furthermore, regional variations highlight a mixed picture, with some areas overcoming adverse conditions more effectively than others, thus contributing positively to the overall global output.

Farming on the Edge: Navigating the Complex Maze of Milk Production Challenges 

Milk’s journey from farm to table is fraught with hurdles that challenge even the most seasoned agricultural sectors. A particularly tenacious adversary is a disease. As evidenced by the recent outbreak of bluetongue in Europe, diseases have the power to drop off percentages from expected output drastically. Germany, for instance, has been grappling with its lowest September figures since 2016. Historical records show that disease outbreaks can lead to prolonged periods of reduced production as affected herds produce less and often require culling to prevent further spread, thus exacerbating production woes. 

Shrinking herds also play a pivotal role in shaping production prospects. Over the past three, perhaps even four, years, the number of dairy cattle has steadily declined, putting a natural limit on how much milk can be produced, regardless of other conditions. Factors contributing to this trend range from increased operational costs such as feed, labor, and equipment to stricter environmental regulations and shifts in land use priorities, reflecting an overarching restraint on growth. 

Moreover, weather patterns remain a capricious companion for the dairy industry. Prolonged periods of drought or unseasonal frosts can significantly curb grazing and feed availability, impacting milk yield and aggravating the precarious balance of supply and demand that dictates market equilibrium. 

Volatile milk markets compound these woes. The fiscal framework within which farmers and producers operate can pivot sharply, influenced by sudden demand shifts or unexpected economic policies. Such volatility often results in insufficient forecasting and planning, leading to surplus or scarcity, each with financial repercussions. 

History shows that milk production is a tightrope walk predicated on diverse, interdependent variables. Each challenge offers lessons, forcing the industry to innovate and adapt to survive another season.

Innovate or Stagnate: How Top Milk Exporters Are Pushing the Envelope

Top milk exporters have yet to rest on their laurels in the face of these challenges, opting instead to embrace innovation and strategy to maintain and improve production levels. France’s resilient 3.2% increase in milk production exemplifies the benefits of investing in technology and sustainable farming practices. In recent years, French dairy farms have adopted precision agriculture tools to optimize feed management and improve overall herd health, resulting in enhanced productivity despite adverse conditions. 

In the United Kingdom, leveraging data-driven strategies has become pivotal in helping farmers maximize yields. Technologies like real-time milk monitoring systems and automated milking machines have enhanced efficiency, reduced labor costs, and increased output consistency. 

Meanwhile, countries like Ireland and Spain have focused on bolstering their production through enhanced breeding programs and improved herd management. These nations have maintained steady milk output despite environmental and economic pressures by selecting genetic traits that enhance dairy yield and disease resistance. 

Looking towards a more sustainable future, many top exporters have prioritized reducing their environmental footprint through innovations such as biogas production from farm waste and improved water usage efficiency. These advancements contribute positively to the environment and enhance the profitability and resilience of milk production, paving the way for a robust industry in 2025 and beyond.

Dairy Dollars and Sense: Navigating the Price-Driven Surge in Milk Production

Price dynamics are pivotal in shaping production strategies for the world’s leading milk exporters. The recent uptick in milk and dairy product prices is a solid economic motivator for farmers and exporters to increase output. As prices rise, so do the potential revenues, enticing producers to overcome barriers such as disease and adverse weather conditions. This market environment encourages investment in improved farming techniques and technology to maximize yield, even amidst shrinking herds and resource constraints. 

For farmers, higher prices translate to better margins, enabling them to justify the costs of increasing production volumes despite ongoing hurdles. This could mean expanding herds, intensifying dairy management practices, or exploring new markets. Exporters, too, see this as an opportunity to enhance their competitive edge. As global demand remains robust, particularly from regions recovering from the pandemic, tapping into higher prices bolsters profitability and market share. 

Ultimately, while challenges persist, the economic incentives driven by price increases offer a compelling reason for industry stakeholders to push production boundaries. The allure of enhanced profits creates a dynamic landscape where innovation and resilience take center stage. This promises a gradual escalation in global milk production as producers adeptly maneuver through the complex demands of today’s volatile market. The potential for growth in the industry is significant, offering a hopeful outlook for the future.

Global Dairy Landscape: A Patchwork of Peaks and Perils

Regional variances in milk production offer a compelling tapestry of challenges and triumphs. Europe remains a juxtaposition of stability and struggle. While countries like France have seen production gains, others like Germany and the Netherlands grapple with natural adversities. The onset of bluetongue disease has muted growth, highlighting how external factors can dent established dairy operations [Eurostat]. Conversely, Oceania is experiencing a boom. With favorable weather and strategic investment in sustainable practices, regions like New Zealand and parts of Australia have surged ahead. This growth is not merely a stroke of luck but an orchestrated response to rising global demand that these producers are keenly aware of [clal. It]. South America, especially Argentina, presents another story. Economic instability and infrastructure issues create a labyrinthine scenario that even the most robust dairy sectors would need help to navigate. Despite these hurdles, there’s a silver lining: innovations in dairy farming and supportive policies are poised to propel Argentina towards stabilization shortly [Department for Environment, Food and Rural Affairs].

The Cutting Edge of Dairy: Embracing Innovation and Confronting Challenges 

The future of global milk production holds both promising advancements and formidable challenges. Technological innovations stand poised to transform dairy farming as we look ahead radically. Precision agriculture, AI-driven analytics, and automation are at the forefront, offering farmers tools to enhance productivity, reduce waste, and ensure sustainability. Imagine milking robots and sensors that monitor cow health and feed efficiency, leading to optimized herd management. 

Policy changes are another critical component influencing the future landscape. Governments worldwide may introduce environmental regulations to reduce milk production’s carbon footprint. Policies encouraging sustainable practices could drive investments in renewable energy and resource-efficient technologies within the industry. 

Market dynamics also play a pivotal role. Consumer demand is shifting towards healthier and ethically produced dairy products. This presents both an opportunity and a challenge for farmers to adapt to changing market preferences. Additionally, geopolitical factors and regional free trade agreements will influence global trade dynamics, export strategies, and competitive positioning. 

Navigating the future of milk production will require innovation, adaptability, and strategic foresight. Dairy farmers and industry stakeholders must stay abreast of these evolving trends to effectively harness opportunities and mitigate risks. Are you ready to adapt and thrive in this dynamic environment?

The Bottom Line

In summary, despite ongoing challenges such as disease, shrinking herds, and market volatility, global milk production has shown resilience by achieving modest growth among top exporters. Europe’s production saw a mixed performance, with gains in France and the UK compensating for setbacks in other regions affected by Bluetongue disease. Meanwhile, Oceania outperformed the previous year’s volumes, propelling the aggregate output higher globally. This demonstrates the ability of the dairy industry to withstand pressures and adapt to shifting economic landscapes. As we look forward, one must ask: How will technological advancements and strategic innovations drive future growth in milk production? It’s time for dairy farmers and industry professionals to embrace change and seize new opportunities to sustain operations in this ever-evolving market. Are you ready to take the next step in shaping the future of dairy?”

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Global Dairy Markets: Navigating Surplus Challenges and Protein Demand

Dive into 2024’s dairy market surplus challenges and rising protein demand. How can producers adapt and stay profitable in these changing times?

Summary:

In November 2024, the global dairy markets reflect a dynamic interplay of opportunities and challenges, with abundant cheese and butter production set against a growing demand for dairy proteins influenced by health trends. The market exhibits price fluctuations due to supply surpluses quelling cheese and butter prices, while dairy proteins enjoy rising popularity, reshaping competitive strategies on a global scale. As winter nears, dairy aisles brim with cheese and butter despite a demand mismatch, highlighting the paradox of abundance amid lean demand. As trading on major dairy exchanges underscores market volatility, dairy producers must adeptly navigate these complexities, reevaluating production and market focus to align with sustainable demand projections. “It’s a time for dairy leaders to rethink, recalibrate, and reinvent, or risk being left behind in the competitive marketplace,” asserts a prominent industry expert. 

Key Takeaways:

  • Dairy markets face a supply-demand imbalance, with cheese and butter experiencing surpluses and declining prices.
  • New cheese production facilities are increasing supply, further saturating the market and exerting downward pressure on prices.
  • The protein sector is experiencing a surge in demand, particularly for whey and milk powders, influenced by a shift towards nutrient-dense foods.
  • The global demand, especially from Asia, is boosting prices for dairy proteins, showcasing the international market’s influence on U.S. dairy producers.
  • Commodity markets are experiencing declining feed costs, which could benefit dairy producers facing economic challenges.
  • The U.S. dairy sector navigates between opportunities in global markets and domestic challenges, balancing exports with local market dynamics.
  • Producers must remain agile and adaptive to sustain profitability and leverage international demand amidst market fluctuations.
dairy market trends, cheese and butter prices, dairy protein demand, EEX butter futures, dairy trading activity, SMP futures performance, dairy production strategy, market volatility in dairy, grocery dairy sales, sustainable dairy production

As winter approaches, the global dairy market is at a fascinating juncture, with grocery aisles filled with cheese and butter amid a perplexing surplus for producers. In contrast, demand for dairy proteins climbs, driven by health-focused choices. This intricate market dynamic reveals a contrast in pricing trends—with cheese and butter prices struggling under the weight of excess as nutrient-dense dairy proteins enjoy a surge in popularity among health-driven markets. As U.S. dairy products capitalize on competitive pricing strategies globally, the coming winter season demands agility and foresight from industry players navigating these shifting currents. The need for strategic adjustments is urgent and cannot be overstated, underscoring the importance of the situation. 

Rolling Tides in Dairy Trading: Balancing Between Peaks and Troughs 

Last week’s trading activities on major dairy exchanges reflected the ongoing dynamics and volatility in the market. At the EEX, 4,590 tonnes were traded, with a notable distribution across different products: 1,685 for butter and 2,905 for SMP. The most active trading day was Wednesday, with 1,795 tonnes exchanged. 

On the futures front, EEX butter futures, after a four-week bullish run, witnessed a slight dip of 0.5%, with the Nov 24-Jun 25 strip averaging at €7,408. Contrastingly, EEX SMP futures experienced a positive uptick of 1.6%, settling at €2,754. 

Open interests in EEX butter futures increased by 182 lots to 3,402. In contrast, SMP futures saw a reduction of 131 lots, bringing the total to 7,114. 

Over the SGX, the dairy market showed significant activity, with 8,791 tonnes traded. WMP was notably active, with 6,202 lots, followed by SMP at 2,468. The NZX milk price futures contract observed 2,040 lots traded. Within this exchange, the SGX WMP saw a robust increase of 3.7%, with an average price climbing to $3,887. SMP futures also rose by 1.6%, with the average price at $3,066. 

These statistics reveal a mixed landscape across the exchanges, characterized by slight declines in some areas and robust growth in others. They offer traders a vivid picture of the current market conditions and general trends shaping the global dairy market. 

Milk Abundance Meets Demand Drought: Navigating Dairy’s Double Bind

In a landscape flooded with milk’s bounty, the dairy industry is caught in a paradox of abundance and scarcity, especially in cheese and butter. The surge in production is fueled by the rollout of new facilities eagerly designed to increase output, creating a wave of supply that threatens to drown under its weight. Initially hailed as triumphs of capacity growth, these expansions now appear as omens of oversupply. 

Yet, this upsurge in supply meets an unexpected roadblock—muted demand, particularly from sectors that once voraciously consumed these dairy staples. Food services, grappling with shifting consumer preferences and economic headwinds such as [specific economic factors], have not reached the plate as expected. Demand in restaurants and food processing has not kept pace with the heightened production levels. The mismatch between what is produced and what is needed is stark. This slack in demand hasn’t just slowed the gears of commerce—it has actively reversed them, turning price trends downward. 

The dairy producers, orchestrators of this milk-and-cream symphony, now face a dissonant tune. With declining prices and storage costs mounting for burgeoning cheese wheels and butter blocks, the profitability that once beckoned them has become elusive. Navigating this market of dips and crests requires acumen and strategy; carefully re-evaluating production volumes and potential shifts in market focus may be imperative. Indeed, the challenge now is not just to produce but to produce wisely, aligning output with realistic, sustainable demand projections. 

The price downturn has provocative undercurrents, urging dairy producers to reassess. As the gleam of high-value exports beckons elsewhere, managing domestic supply chains with precision and foresight becomes crucial. Thus, dairy producers are poised at a crucial juncture, balancing innovation in production with the wisdom of tradition as they seek to stabilize their footing on the tilting scales of the global market.

Price Plunge Alert: Cheese and Butter Markets Face a Stockpile Squeeze

The sharp decline in cheese and butter spot prices reflects a confluence of overproduction and insufficient demand, which has become a defining feature of current market conditions. Cheddar showed an acute decrease in blocks and barrels, with blocks settling at $1.6925 per pound and barrels dipping to $1.685, marking their lowest prices since April. Spot butter prices mirrored this downward trajectory, plunging to $2.63, the lowest point since January. Two primary factors drive this drop: a steady production capacity, high output levels, and a saturation of stocks surpassing current demand. 

These dynamics create a challenging environment for producers, who face declining profitability as the market absorbs more dairy products than it demands. The influx of new cheese facilities designed to bolster production adds another layer to this dilemma. Although intended to elevate output, these facilities risk exacerbating the prevailing supply-demand mismatch. Consequently, prices will continue their descent, compelling producers to reassess operational strategies and market engagements. On the other hand, the broader market could see a ripple effect as these low prices spill over into other dairy segments, further straining the entire dairy supply chain.

Protein Pivot: Dairy’s Strategic Shift in the Pursuit of Health

The dairy markets‘ narrative is shifting towards proteins as consumer demand finds new vigor, particularly among those using GLP-1 medications such as Ozempic or Wegovy. These drugs have fundamentally altered dietary needs, with millions prioritizing nutrient-dense foods amidst their reduced-calorie intake. This consumer pivot to nutritionally rich options elevates the demand for dairy proteins, catalyzing a noticeable ripple effect across the whey and milk powder markets. 

Whey protein isolates (WPIs) and concentrates (WPCs) have emerged as critical beneficiaries of this shift. Their appeal lies in their high protein content, which provides maximum nutrition in smaller quantities—a significant advantage for GLP-1 users. As a result, producers are seizing the opportunity and increasing production to meet this burgeoning demand. However, this focus on highly concentrated products has led to a notable decline in the availability of less concentrated whey products, such as WPC-35 and generic whey powders, subsequently driving their prices upwards. 

The trend is not isolated to whey products alone; nonfat dry milk (NDM) is also experiencing a price rally. International demand, especially from Asian markets, is boosting prices and putting upward pressure on NDM. The strategic realignment of milk utilization, drawn towards expanding cheese production capacities, means that less milk is available for drying into powders, further tightening supply and bolstering prices. This shift in milk utilization is a significant factor in the current market conditions.

Amidst Shifting Sands: The U.S. Dairy Sector’s Global Frontier

Amidst the shifting sands of international markets, the U.S. dairy sector navigates complex dynamics that offer opportunities and challenges. Competitive pricing strategies have become pivotal, allowing U.S. dairy products to gain traction in international arenas even as currency fluctuations pose challenges. Despite a strengthening dollar, which traditionally hampers export potential by making U.S. goods more expensive abroad, American dairy products’ intrinsic quality and value proposition have held firm in enticing foreign buyers. 

The Global Dairy Trade (GDT) auctions provide a clear barometer of international demand, with particular attention focused on milk powder and other high-demand staples. Robust purchasing from Asian markets underscores a persistent appetite for American dairy, bolstering overall export figures. This international demand has not only fueled a rise in milk powder prices but has also served as a counterbalance to the increased production capacities emerging from countries like Australia and New Zealand. 

Ultimately, this delicate interplay between competitive pricing and global market demands is a double-edged sword for U.S. dairy. On one hand, it underscores the sector’s capacity to remain competitive in an increasingly globalized market. Conversely, it accentuates the need for strategic navigation amidst currency headwinds and pressure from international dairy powerhouses. The future positioning of U.S. dairy hinges on its ability to leverage these international currents, ensuring that its products continue to captivate global markets despite the ebb and flow of economic tides.

Strategic Foresight: Navigating the Challenges of Dairy’s Economic Ebb and Flow 

In the current landscape, dairy producers contend with declining market conditions that echo through Class III and Class IV futures. The consecutive downturn in Class III futures marks an unsettling trend, with contracts shedding roughly 20ȼ and values rocking in the high $18s to low $19s range. This trajectory points to increasingly challenging economic circumstances, striking at the heart of revenue expectations that were more promising in prior months. 

Class IV futures are similarly beleaguered, weighed down by retreating butter prices. Contracts stretching from April through June see values dipping below the $21 threshold, signaling a broader trend of financial strain across the dairy segment. Such dynamics prompt producers to ponder strategic adjustments to maintain fiscal viability as milk checks inevitably shrink. 

Yet, amid these daunting futures, potential relief emerges from the feed markets. Recent climatic benefits—significant rainfall gracing the Southern Plains—have invigorated winter wheat crops, propelling wheat futures downwards. As a result, corn and soybean prices have also declined, with December corn prices settling at $4.24 per bushel, bringing some respite to dairy operators weighed down by production costs. 

This evolving cost landscape necessitates strategic foresight among dairy producers. While reduced feed costs are a beacon of hope, maintaining profitability in a volatile market requires financial strategy skills. These include exploring crop contracts to hedge against feed price volatility, optimizing herd management to boost milk yield efficiency, and mitigating risks through diversified product offerings to capture varying market demands. 

Though navigation remains complex, this multifaceted strategy offers a lifeline as the dairy market transitions through its current turbulent phase. It equips producers to brace against economic fluctuations and harness opportunities where they arise.

The Bottom Line

The current dairy market landscape reveals a striking contrast between production surpluses and shifting consumer demands. Cheese and butter face stockpile pressures amid declining prices, while dairy proteins experience a boom driven by health-conscious consumers. This dynamic creates a dual challenge: navigating the glut in traditional dairy products while capitalizing on the growing demand for protein powders. 

Producers must contemplate how to remain agile and competitive. With the allure of global markets buoying U.S. products abroad, are exports the key to sustaining profitability? Or should domestic markets realign to cater to the burgeoning interest in nutritional dairy options? As we witness these market shifts, producers must ask themselves what strategies will ensure survival and sustainable growth in an increasingly global and competitive arena. How can they strategically manage production to align with these evolving demands?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Argentina’s Dairy Dilemma: Navigating Weather Woes and Economic Tides

Delve into Argentina’s dairy hurdles. Climate and economic changes press on production and exports. Gain insights for dairy experts.

Argentina’s dairy industry is at a crossroads, grappling with the tumultuous twin forces of extreme weather conditions and economic upheaval. Amidst sweltering heatwaves and a relentless drought, milk production has faced an unforeseen dip, challenging even the most resilient farmers. Domestic consumption has taken a hit as a ripple effect, painting a grim picture for an industry already on shaky grounds. Yet, paradoxically, exports are rising, hinting at a complex web of supply and demand on the global stage. What does the future hold for Argentina’s dairy farmers, standing at the confluence of nature’s wrath and economic unpredictability? As we navigate these uncertain times, one must ask: How will Argentina’s dairy sector adapt and evolve in the face of such unprecedented challenges? Will innovation and resilience lead the way, or will further turmoil unravel the fabric of this storied industry?

Metric202320242025 (Projected)
Milk Production (1000 MT)11,66510,70811,351
Whole Milk Powder Export (1000 MT)111128139
Cheese Production (1000 MT)471452483
Butter Production (1000 MT)343134
Fluid Milk Consumption (1000 MT)1,1541,0501,160

Weathering the Storm: How Climate Chaos Tests Argentina’s Dairy Backbone 

Argentina’s dairy industry has faced fierce hurdles, primarily due to extreme weather conditions that have disrupted milk production. Severe droughts, particularly in recent years, have diminished pasture and feed supplies, directly affecting the quantity and quality of milk produced. Heatwaves exacerbate these challenges by inducing stress in cattle, leading to further declines in milk output as cows struggle to cope with the soaring temperatures. The resulting combination of water scarcity and intense heat weakens production, making it increasingly difficult for farmers to sustain robust operations. 

The Niña weather pattern plays a significant role in this climatic conundrum. Expected to bring below-normal rainfall to the Pampas region, the heartland of Argentina’s dairy farms, Niña conditions threaten the core of the nation’s milk production capabilities. While 2024 saw forecasts of a mild Niña, the intricate balance of rainfall and temperature remains crucial. Any deviation can spell disaster, as adequate precipitation is vital for crop and livestock health. In a region heavily reliant on consistent weather patterns, any shift has lasting repercussions, hampering production and influencing the overarching agricultural strategies. 

Climate change amplifies these challenges, altering traditional patterns and forcing farmers to adapt. Rising temperatures and changing precipitation rates demand shifts in farming practices, with producers exploring drought-resistant crops or altering feed composition to mitigate the risks. These adjustments, however, often come with increased costs and uncertainty, especially in an economic climate that may not be accommodating such investments. Moreover, the need for more resilient practices introduces a new era of agricultural management, where technology and innovative strategies must converge to effectively tackle the escalating climate threats.

Unveiling the Dairy Tapestry: Argentina’s Resilient Journey Through Flavors and Challenges

Delving into Argentina’s dairy saga unveils a history as rich and complex as its renowned flavors. The nation’s venture into dairy wasn’t just an economic endeavor but a cultural hallmark, threading through its agricultural identity. From its agrarian zenith in the 20th century, Argentina emerged as a formidable force in the global dairy sector, fueled by its vast pampas and a strong heritage of livestock farming. 

The post-World War II era marked a golden age for Argentine agriculture, and the dairy industry was no exception. Farmers embraced innovations, increasing milk yield and product diversity. This period saw Argentina become a pivotal dairy exporter, with its products prized in international markets. However, the path was not without its pitfalls. Economic upheavals, such as the late 1980s and early 2000s hyperinflation, imposed heavy burdens on production costs and farm profitability. 

Despite these tumultuous cycles, the resilience of Argentine dairy farmers became a defining narrative. The 2000s brought globalization challenges, compelling the industry to adapt rapidly to fluctuating global prices and trade barriers. Yet, Argentina’s dairy producers demonstrated an uncanny ability to pivot and thrive, leveraging technological advancements and sustainable practices to maintain competitiveness. 

Today, as the industry braces against climate adversities and economic shifts, it draws on a legacy of enduring perseverance. Each epoch has sculpted a dairy landscape that is as much about overcoming adversity as it is about innovation and market leadership. Understanding this historical tapestry contextualizes the resilience and strategic pivots currently seen in the sector, offering a lens through which to view both challenges and triumphs.

Argentina’s Dairy Dynamo: Navigating the Crosswinds of Economic Shifts and Market Fluctuations

Shifting economic policies and fluctuating market dynamics influence Argentina’s dairy sector. Recent governmental changes have implemented significant economic measures to influence domestic consumption and international trade. Removing domestic price controls and abolishing export duties in mid-2024 are pivotal changes poised to recalibrate the field. 

The impact on domestic consumption is notably profound. Without price controls, the market reacts based on pure supply and demand dynamics, potentially leading to variations in consumer prices for dairy products. Coupled with the overall economic recovery, this could stimulate a resurgence in local consumption to approximate pre-crisis levels of about 1,150 thousand metric tons (MT) in 2025, aligning closely with figures from 2023. 

The lifting of export duties enhances the competitiveness of Argentina’s dairy products in international markets. The duties, which previously stood at 9% for milk powder, presented a barrier that stifled export potential. With this restriction removed, analysts foresee a boost in export activities, expecting that whole milk powder (WMP) exports will rise by 15% in 2024, reaching 128,000 MT and further increasing by 9% in 2025. 

These changes, however, are not without challenges. As Argentina’s dairy exports gain traction, the pressure mounts to meet international demand amid internal production constraints. The nation’s milk production, estimated to decline by 7% in 2024 due to adverse weather, poses a hurdle in fulfilling burgeoning export orders without compromising domestic supply expectations. 

International trade relations, primarily with Mercosur partners like Brazil, constitute a crucial aspect of this framework. Brazil remains a steadfast recipient of Argentine exports, accounting for 63.5% of WMP exports in 2023. The stability and growth of this trade relationship are promising amidst regional climate challenges affecting milk producers throughout the southern cone. 

While recent economic reforms signal potential growth and re-stabilization, they bring a suite of uncertainties. Dairy producers must adeptly navigate this complex landscape, balancing domestic demand against export opportunities, all under the shadow of unpredictable climatic disruptions and policy shifts. In this volatile scenario, strategic foresight and adaptability remain the quintessential tools for stakeholders striving to seize the potential embedded within these economic tides. 

Turning the Milk Tide: Argentina’s Dairy Resilience Triumphs in Export Markets Despite Domestic Challenges

Amidst the turbulence of declining domestic milk production in 2024, Argentina’s dairy sector showcased an impressive export performance, with whole milk powder (WMP) and cheese exports witnessing a remarkable rise. Despite a challenging year marked by significant weather-induced production setbacks, these export figures have been on an upward trajectory, underscoring Argentina’s strategic market adaptability. 

Brazil undoubtedly remained the linchpin in Argentina’s export strategy. As the primary destination, Brazilian demand played a crucial role, accounting for a substantial portion of WMP exports. This partnership highlights the mutual dependency between the two nations, especially in light of the climatic adversities affecting the Mercosur dairy region, including southern Brazil. This regional alliance facilitated trade and buoyed Argentine exports amidst an otherwise contracting landscape. 

Moreover, the cheese sector illustrated resilience, with an 8% uptick in exports. Brazil also emerged as a significant player, alongside other strategic markets like Chile and new entrants such as the Middle East, which are increasingly receptive to Argentine dairy prowess. Notably, this highlights Argentina’s ability to leverage its rich dairy expertise, even in less traditional markets, paving the way for future growth. 

Looking ahead, the potential for further expansion in international markets appears promising. Projections anticipate a recovery in milk production by 2025, and Argentina is poised to capitalize on its export strength. The recent dismantling of export duties on dairy products could enhance competitiveness, empowering producers to amplify their presence across burgeoning international markets. As Argentina navigates this dynamic landscape, its focus remains steadfast on solidifying and expanding its export scope, ensuring its dairy products continue penetrating and thriving in global arenas.

Corn Silage Under Siege: Argentina’s Crucial Battle Against the Persistent Chicharrita Threat 

The relentless threat of the chicharrita, or corn leafhopper, lingers heavily over Argentina’s dairy farms, threatening to destabilize the backbone of their feed supply—corn silage. This pest, a vector for the Spiroplasma Kunkelli bacteria, has wreaked havoc on corn crops, leading to devastating losses in grain and silage yields. With corn silage being a critical component of the dairy diet due to its high energy content, any compromise in its availability severely tests the resilience of the farmers. 

In response, farmers are exploring innovative solutions to counteract the impact of this pest. One such approach is the potential switch to sorghum silage. Though traditionally considered a secondary silage option, Sorghum offers a viable alternative amidst the uncertainty posed by chicharrita infestations. With its natural pest-resistant properties and the ability to thrive in challenging conditions, sorghum presents a strategic shift that could mitigate the risk of feed shortages. 

Yet, the move to sorghum silage presents its own set of challenges. While sufficient, sorghum silage’s protein and energy content differ from corn’s, necessitating careful balancing in dairy diets to ensure production levels are maintained. Maintaining high-quality feed remains paramount for the health and productivity of dairy herds, making it essential that the nutritional values of alternative feeds are closely monitored and adjusted in real-time. 

As Argentina’s dairy industry navigates these feed supply challenges, maintaining quality feed cannot be overstated. Innovative farming practices and adaptive feeding strategies are not just options—they are crucial to sustaining herd health and milk production amid an evolving agricultural landscape. Farmers, therefore, must remain vigilant and agile, ready to implement changes as they work to secure a stable and nutritious diet for their dairy cows.

Navigating the Herd: Examining the Future of Argentina’s Dairy Landscape

In Argentina, the dynamics of dairy cow stock and production stratification play a pivotal role in shaping the dairy industry’s trajectory. In 2024, we witnessed a stabilization in cow stock, reflecting the favorable conditions anticipated for 2025. The liquidation trend, which saw an uptick in earlier years, appeared to reverse slightly, with a reported 7.2% decrease in dairy cow slaughter from the same period in 2023, marking a shift towards retaining more livestock. 

The substantial concentration of productive units highlights an ongoing shift toward larger-scale operations. In 2023, farms with over 500 cows comprised 5.6% of all productive units, yet these accounted for 25.2% of the country’s dairy cows. This trend indicates a gradual consolidation of production into larger farms, potentially enhancing efficiency and risking smaller producers’ marginalization. The distribution shift signals an industry gravitating towards economies of scale, possibly catalyzing more stable milk production levels as more extensive operations can mitigate fluctuations through better resource management. 

As of December 31, 2023, the dairy cow stock stood at 1,495,243 head, a drop of 4.3% from 2021 figures. This decrease underscores the challenges posed by drought and unfavorable price-cost ratios in previous years, which have driven increased culling rates. In 2023, approximately 231,582 dairy cows were slaughtered, notably higher than in previous years due to economic pressures, further contributing to the stock reduction. 

Analyzing these dynamics reveals the dual nature of this stratification process: potential gains in productivity and stability at the cost of increased industry concentration. Smaller farms continue to face consolidation pressures, which may lead to a homogenized industry landscape favoring more prominent players. While the outlook appears to favor stabilizing stock levels into 2025 under current projections, the balance between concentration benefits and diversity loss will remain a critical consideration for policymakers and industry stakeholders.

Fluid Milk’s Waning Fortunes: Navigating Argentina’s Shifting Consumer Landscape

The backdrop against Argentina’s embroiled dairy industry reveals changing consumption patterns that demand an astute analysis. Fluid milk consumption has declined, reflecting production woes and shifting consumer choices and economic realities. In the first seven months of 2024 alone, a staggering 12% fall in fluid milk consumption was recorded compared to the previous year, particularly peaking with a 21.6% decline in February. This vividly shows how deeply production levels and economic health intertwine domestic consumption habits. 

As production dwindles through harsh climatic and economic conditions, there’s a tighter grip on consumer behavior, pushing them towards alternatives that align better with their financial constraints and lifestyle changes. Long-life milk continues to overshadow refrigerated varieties, as evidenced by a consistent shift, where the refrigerated milk marketshare shrank from 38% in 2022 to 37% in 2023. This signals a cautious consumer eyeing the reliability and longevity of their dairy choices amidst economic strains. 

Economic downturns contribute heavily to this narrative. When wallets constrict, fluid milk often becomes a casualty, its demand retreating, mirroring the broader recessionary patterns. The domino effect continues as we see domestic consumption of fluid milk and dairy products like Whole Milk Powder (WMP) fall from grace, pressured by reduced production and weakened purchasing power. 

Yet, amidst these challenges, social programs emerge as a bulwark against plummeting demand. Particularly in election years, the government’s role in distributing dairy, notably WMP, through social assistance programs, provides a lifeline that sustains consumption at a stable level. These programs, intrinsically linked to public welfare endeavors, ensure that despite economic adversity, a baseline demand for dairy continues to exist, cushioning the industry against complete demand erosion. 

Understanding these fluid dynamics requires keen foresight as we navigate toward 2025, where the promise of economic recovery might once again make room for a resurgence in domestic dairy consumption through market forces and strategic social interventions.

Gazing Beyond 2025: Crafting Argentina’s Dairy Future Amidst Innovation and Uncertainty

As we gaze beyond 2025, Argentina’s dairy industry is at a crossroads of opportunity and challenge. Building on a projected recovery, the industry faces varying scenarios that hinge on multiple intertwining factors. One potential scenario sees technological advancements and intelligent farming techniques playing pivotal roles. With precision agriculture and data-driven herd management becoming more accessible, Argentine producers could boost productivity and efficiency, offsetting weather-related setbacks and optimizing resource use. This tech-driven prowess might position Argentina as a leader in exports and sustainable dairy practices. 

On the flip side, the industry remains vulnerable to climate variability. While a mild Niña currently forecasts a reasonable weather pattern, future oscillations towards either extreme could jeopardize gains. Hence, the sector’s capacity to integrate adaptive measures and innovate environmentally resilient strains of fodder, such as pest-resistant corn, will be crucial. 

Moreover, economic dynamics continue to wander through uncharted waters. Will Argentina maintain favorable trade terms with critical partners like Brazil and Algeria, or will geopolitical upheavals prompt a reorientation of its export landscape? Past volatility in feed prices suggests that economic stability at home—perhaps through policy solidity and financial investments—cannot be sidelined. 

The domestic consumption narrative also speculates an intriguing turn. A recovering economy may encourage a shift towards an increased appetite for dairy, potentially amplifying fluid milk and cheese consumption as local market confidence rebuilds. Meanwhile, the consolidation trend among productive units could further catalyze efficiencies but may also incite social concerns over agricultural livelihood disparities. 

Ultimately, the horizon for Argentina’s dairy sector in the aftermath of 2025 is painted with both caution and optimism. Industry stakeholders, from policymakers to producers, must be proactive, seeking agility in response to shifting winds. In an era where resilience complements tradition, the Argentine dairy tapestry may emerge sturdier and more diverse, preserving its iconic flavors while embracing new horizons.

The Bottom Line

As we look toward 2025, Argentina’s dairy industry stands at a pivotal crossroads, confronting arduous challenges and promising opportunities. While weather patterns, particularly the specter of La Niña, continue to loom over production prospects, there’s hope in herd resilience and the anticipated stabilization of climatic conditions. The persistent threat of the chicharrita to corn production remains a massive hurdle, urging the sector toward adaptive strategies and crop diversification. 

On the economic front, Argentina’s domestic and international market dynamics offer a dual-edged sword. As domestic consumption shows signs of recovery and favorable milk-to-grain price ratios, there’s potential for a robust bounce-back in both the production and processing sectors. Moreover, lifting export duties and favorable trade conditions could pave new avenues for Argentine dairy exports, bolstering its presence on the global stage. 

However, 2025 is set to test the industry’s agility in navigating these complexities. Will the Argentine dairy sector harness these challenges to drive innovation and sustainability? How can dairy professionals and farmers collaborate to secure a future that balances market demands with environmental stewardship? The answers lie in forward-thinking strategies and a collective commitment to the dairy legacy. 

As dairy stewards and stakeholders, it’s time to rethink the possibilities: How can you contribute to shaping a resilient and dynamic future for Argentina’s dairy industry?

Key Takeaways:

  • Argentina’s dairy production in 2024 faced a significant decline of 7% due to adverse weather and economic issues.
  • Despite lower production, whole milk powder exports increased by 23% in early 2024, projecting a 15% rise by year-end.
  • The cheese export sector also experienced growth, with an expected 8% increase by 2024’s close.
  • A recovery in milk production is anticipated in 2025, with projected growth in overall dairy exports.
  • The resilience of Argentina’s dairy sector is highlighted by its ability to increase exports despite domestic production challenges.
  • The Niña weather pattern will continue affecting rainfall, potentially influencing future dairy production.
  • Economic policy changes have eliminated export duties and facilitated imports to control inflation, impacting the dairy industry landscape.
  • Argentina’s shift towards exporting to countries like Brazil and Algeria underscores the strategic focus on international markets.
  • Future dairy production will heavily depend on climatic conditions and crop quality, such as corn and sorghum silage.
  • Changes in government policies, particularly post-2024, may impact the dairy sector’s market dynamics and pricing structures.
  • Sector-specific support, such as export duty removal and price control elimination, depict an evolving regulatory framework.

Summary:

In 2024, Argentina’s dairy industry confronts challenges from adverse weather and economic factors, causing a projected 7% dip in milk production. However, exports of whole milk powder (WMP) and cheese have risen significantly, demonstrating strategic adaptability amid regional droughts. The government’s policy changes, including removing export duties, could boost the sector by altering its dynamics. As climate change impacts farming practices with rising temperatures and shifting precipitation, Argentine farmers must adopt drought-resistant crops or modify feed compositions, increasing costs and uncertainty. Looking beyond 2025, the industry stands at a crossroads between technological advancement and vulnerability to climate variability, relying on innovation in adaptive measures and pest-resistant crops to ensure sustainability and growth.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Why Japan’s Tourism Revival is a Golden Opportunity for the U.S. Dairy Industry

Explore how Japan’s post-pandemic tourism surge might spark U.S. dairy export growth. Can American farmers capitalize on this chance?

Summary:

The post-pandemic surge in international tourism revitalizes Japan’s economy and reigniting interest in its dairy sector. For U.S. dairy farmers and professionals, this demand recovery signals opportunities for increased butter and cheese exports. Japan’s fluid milk production faces challenges, but the tourism industry’s appetite creates a ripe market for dairy innovation. The growing fondness for cheese and international varieties signifies a cultural shift, offering U.S. dairy producers a chance to innovate and expand. As Japan navigates these contrasting demands, American producers must strategize to capture this evolving market. “The complexity of the market demands adaptability. To succeed, one must weigh the challenges and opportunities this unique economic landscape presents.” 

Key Takeaways:

  • The increase in tourism following the COVID-19 pandemic is a potential booster for the U.S. dairy industry with growing demand in Japan.
  • Despite the stable and low consumer demand for butter and cheese, Japan’s rebounding tourism industry is driving food service demand.
  • Projected declines in Japan’s fluid milk production are anticipated, resulting in increased reliance on dairy imports.
  • Japan’s recent adjustments to its butter import quotas highlight the significant demand pressure in the food service sector.
  • While cheese imports to Japan are beginning to recover, challenges remain with consumer price sensitivity affecting sales.
  • The U.S. holds a notable share of Japan’s imported cheese market, presenting potential growth opportunities amid changing market dynamics.
U.S. dairy industry, Japan tourism resurgence, dairy product demand, Japanese distributors, dairy exports, USDA GAIN report, milk consumption trends, culinary innovation Japan, cheese market growth, flavor fusion opportunities

The resurgence of tourism in Japan not only presents a unique opportunity for the U.S. dairy industry but also a promising avenue for growth. As the world emerges from the shadow of the pandemic, Japan’s hospitality sector is poised for significant expansion, driving a robust demand for dairy products. How can U.S. dairy farmers and businesses capitalize on this trend? As tourism ignites Japan’s economy, tapping into this demand for dairy should be strategic. U.S. dairy producers can focus on providing high-quality products and forming solid partnerships with Japanese distributors and retailers. Adaptation and innovation will be critical drivers of success, paving the way for a bright future in the Japanese market.

Contrasting Currents: Navigating Japan’s Divergent Dairy Demands 

Japan’s dairy market has become a study in contrasts. Local demand for butter and cheese is still declining, which can be attributed to various economic and cultural factors influencing Japanese consumers’ dietary preferences. Despite these trends, another facet of the market is thriving: the tourism and food service sectors. These sectors are undergoing a robust resurgence post-pandemic, driving a new demand wave for dairy imports. 

As the USDA’s GAIN report highlights, the implications for U.S. dairy exports could be significant. While domestic production threads carefully against a backdrop of a reducing milk cow population, the flourishing appetite from international visitors and an evolving food service landscape are primed to boost imports. U.S. dairy stakeholders must focus on this dichotomy, recognizing opportunities where traditional consumption patterns dwindle, yet external demands offer new growth avenues. 

With a calculated approach, leveraging these insights from the GAIN report provides a clear path forward. The U.S. has the potential to capitalize on filling this demand void within Japan, particularly in areas where logistical and trade relationships are most vital. The challenge remains: are U.S. dairy producers ready to swiftly adapt to and meet these burgeoning demands? 

Flavor Fusion: Embracing Japan’s Evolving Dairy Palette 

The intricate tapestry of Japan’s culinary scene showcases a rich history steeped in tradition, where milk and butter hardly found a place. Yet, in recent years, this landscape has transformed dramatically. Thanks to Western influence, the subtle incorporation of dairy into dishes has opened new avenues for flavors and textures previously unexplored in Japanese kitchens. The growing fondness for cheese, including its varied international varieties, symbolizes a cultural shift that presents a rich opportunity. 

This cultural evolution presents a lucrative prospect for U.S. dairy producers to tap into a market ripe for innovation. By blending the authenticity of Japanese culinary elements with the richness of American dairy, producers can craft products that appeal to the dichotomy of taste – honoring age-old recipes while embracing modern palate innovations. Imagine a sushi roll enhanced with cream cheese or a traditional matcha dessert elevated using a dollop of U.S.-sourced butter. The possibilities are as expansive as they are exciting. 

In a society that values the seamless integration of foreign and domestic influences, U.S. dairy is uniquely positioned to introduce products that cater not only to Japan’s developing penchant for international cuisine but also resonate deeply with evolving consumer preferences. As this cultural shift continues, producers must ask how to best combine these world-class dairy flavors with Japan’s culinary finesse.

Tourism Waves: Reviving Japan’s Appetite for Dairy Delights

As Japan swings open its doors to a flood of tourists again, its food service sector returns to life. This rekindled enthusiasm in bustling restaurants and cafes is a game-changer for dairy imports, a sign that the global dairy community should heed closely. 

Tourism is a powerful catalyst in this recovery narrative. The influx of international visitors boosts the demand for local delicacies and raises the bar for imported ingredients that offer the unique flavors tourists seek. Butter and cheese, staples in many international cuisines, figure prominently in this revitalization. 

Statistics from Japan’s Ministry of Agriculture, Forestry, and Fisheries reveal a compelling trend: Butter imports surged 55% last year and 13% through August 2024. This upswing underscores a growing appetite that surpasses what local production can satisfy. 

Similarly, cheese imports are bouncing back, up 5% for the first two-thirds of 2024, signaling a gradual yet promising rebound from previous downturns. Such upticks are more than figures on a chart; they offer tangible opportunities for U.S. dairy exporters to step in and fill Japan’s evolving needs, demonstrating the crucial role that U.S. dairy plays in meeting the changing demands of the Japanese market. 

The U.S., which claims 10% of the import market share, stands poised to expand its footprint. As Japan’s visitors splurge on culinary experiences, American dairy suppliers could be the winning card in meeting this renewed demand. In essence, the tourist footprint in Japan is leaving more than just revenue trails; it’s interlinking global dairy markets in previously unseen ways.

Crossroads and Catalysts: Navigating the U.S. Dairy’s Path in Japan 

The U.S. dairy industry is at a crossroads. It faces stiff competition from countries within the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP). These countries enjoy tariff benefits, making their products more attractive to Japanese importers. As a result, the U.S. is at a disadvantage, battling both cost and perception challenges. 

Yet, all is not lost. The U.S. dairy industry has the power to turn the tide. Strategic maneuvers could be the key. Firstly, the U.S. needs to enhance negotiations within existing trade agreements. By pushing for more favorable terms that level the playing field, American dairy exporters can reduce the impact of these tariff discrepancies. Additionally, focusing on product differentiation can carve out a niche in the Japanese market. This means emphasizing the unique qualities of U.S. dairy—such as grass-fed, organic, or artisanal specialties—that might appeal to Japan’s evolving palates. With these strategic moves, the U.S. dairy industry can take control of its position in the Japanese market. 

Another strategy lies in storytelling. Sharing the rich heritage and quality of American dairy farming could resonate well with Japanese consumers who value tradition and craftsmanship. This narrative could be woven into marketing campaigns, bringing a personal touch that highlights the dedication of American farmers. U.S. producers might also consider collaborative efforts with Japanese companies to create products tailored to local tastes, thus embedding themselves more profoundly within the market. 

While challenges from CPTPP countries persist and import costs remain high, viable pathways exist for U.S. dairy to sustain and grow its presence in the Japanese market. By leveraging trade policies and doubling down on product uniqueness and compelling consumer stories, the U.S. dairy sector can aspire to capture a more substantial slice of the pie.

Crafting Excellence: U.S. Dairy’s Strategy for Success in Japan

U.S. producers must prioritize quality and innovation to create a sustainable niche in Japan’s competitive dairy market. The discerning Japanese consumer prioritizes both facets, seeking products that offer nutritional value and distinctive sensory experiences. This expectation extends to everyday consumption and the booming tourism market, where quality can significantly influence culinary reputation. 

U.S. dairy producers can achieve this by leveraging cutting-edge processing techniques that enhance flavor and texture and preserve the natural goodness of milk. Distinctive offerings, such as artisanal cheeses or gourmet butter with unique flavor profiles, can appeal to the Japanese palate that increasingly seeks novel culinary experiences. Brands that emphasize craftsmanship and exclusivity often see higher consumer interest. 

Sustainability is another critical factor in differentiating products. By adopting environmentally friendly practices, from pasture management to packaging, U.S. dairy companies can align with the values of conscientious consumers. This approach not only bolsters brand reputation but can also underpin long-term loyalty and market resilience. 

An example of success is the U.S. dairy brand Tillamook, which has begun making inroads in Japan by capitalizing on its reputation for high-quality cheese and sustainable farming practices. Similarly, Organic Valley’s commitment to organic production has resonated with health-conscious Japanese consumers. These cases demonstrate the potential of quality and innovation as vital tools for penetrating and prospering within Japan’s evolving dairy landscape.

The Bottom Line

The opening doors in Japan’s bustling tourism sector present U.S. dairy farmers with a remarkable opportunity. As the country’s fluid milk production faces challenges, the demand for cheese and butter is poised to soar, driven by the vibrant food service industry. While Japan’s butter stocks remain low, opportunities for imports abound, turning the U.S. dairy sector’s gaze toward this promising market. With a strategic approach, the chance to grow and expand in Japan is not just a possibility—it’s a potential reality. As the tides turn, we ask: Are you ready to tap into Japan’s tourism-driven dairy demand, setting the stage for sustained growth and international success?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Dairy Markets Brace for Winter: Surplus Cheese and Butter, Rising Whey and Milk Powder Prices

How will surplus cheese and butter, alongside rising whey and milk powder prices, shape the dairy markets this winter? Are you prepared for these changes in demand and supply?

Summary:

The dairy industry is bracing for an unpredictable winter as cheese and butter markets face a seasonal slowdown marked by a supply and demand misalignment. While early-year price surges have waned, a new cheese facility in Kansas threatens to exacerbate supply issues. Butter makers remain hesitant to ramp up production despite abundant cheap cream. Consumer focus has pivoted towards dairy proteins such as whey protein isolates due to GLP-1 medications, shifting demand away from traditional dairy products. An industry expert notes that “whey protein is experiencing a surge in popularity, leaving less room for traditional dairy products.” This has led to a market imbalance, causing a downturn in cheese and butter prices, with spot Cheddar blocks and barrels at their lowest since April.
Meanwhile, the strategic shift in milk production toward expanding cheese production reduces the amount of milk available for drying into powders, tightening supply and bolstering prices. The current market dynamics present economic challenges for dairy producers, with declining Class III futures and a drop in butter futures. However, milk revenues may still cover costs for some producers.

Key Takeaways:

  • The cheese and butter markets are experiencing notable price declines due to increased production and stockpile levels.
  • Demand for highly concentrated whey products is surging, driven by dietary trends and the popularity of GLP-1 medications.
  • Both whey and nonfat dry milk powder prices are reaching significant highs, influenced by global demand and competitive dynamics.
  • While the domestic market faces challenges, competitive pricing positions U.S. cheese and butter favorably for international markets.
  • Feed market prices have declined, promising cost-effective solutions for dairy producers amidst other economic pressures.
dairy market imbalance, cheese and butter surplus, dairy producers profitability, whey protein isolates, milk powder market trends, GLP-1 medications impact, American butter pricing, Class III futures decline, dairy export challenges, protein-rich consumer demand

As the chill of winter approaches, the dairy markets are at an intriguing crossroads. Store shelves are brimming with cheese and butter, yet beneath this abundance lies a story of market dynamics promising a nuanced winter. Cheese and butter makers face surpluses and declining prices, while the protein powder sector defies seasonal trends with rising prices for whey and milk powder. Butter makers note, “Demand is simply not keeping pace with current production,” as orders remain “steady to lighter” compared to the burgeoning interest in dairy proteins. This winter, the domestic dairy scene braces for a complex balancing act between excess and scarcity.

Cheese Overflow Meets Empty Plates: Navigating Dairy’s Winter Conundrum

The dairy market is currently grappling with a significant imbalance between supply and demand, leading to a surplus in cheese and butter production. There have been substantial production increases on the supply side, especially with the opening of new cheese facilities. These developments are set to elevate production levels further as additional expansions come online. However, this influx is met with tepid demand, particularly from the food service sector, which remains weak compared to the plentiful supply. This imbalance is causing a significant market price downturn, affecting dairy producers’ profitability landscape. The new facilities, intended to boost output, will likely saturate the market further, potentially exerting continued downward pressure on prices.

Price Plunge Alert: Cheese and Butter Markets Face a Stockpile Squeeze

The cheese and butter markets exhibit significant pricing trends with notable declines in spot cheese and butter prices. Specifically, spot Cheddar blocks and barrels have experienced their lowest prices since April, with Cheddar blocks closing at $1.6925 per pound after a modest rebound, while barrels plummeted to $1.685. Similarly, CME spot butter prices fell to $2.63, the lowest since January. These trends stem from a combination of factors, including the abundance of stocks and robust production levels that persist despite reduced demand. Ample stocks, bolstered by steady production capabilities, have created a surplus, exerting downward pressure on prices. These market dynamics, coupled with steady production and an influx of supplies, help explain the current pricing trends in the cheese and butter markets.

Protein Boom: Dairy’s Answer to the Nutrition Revolution 

The dairy markets’ narrative is shifting towards proteins as consumer demand finds new vigor, particularly among those using GLP-1 medications such as Ozempic or Wegovy. These drugs have fundamentally altered dietary needs, with millions prioritizing nutrient-dense foods amidst their reduced-calorie intake. This consumer pivot to nutritionally rich options elevates the demand for dairy proteins, catalyzing a noticeable ripple effect across the whey and milk powder markets. 

Whey protein isolates (WPIs) and concentrates (WPCs) have emerged as critical beneficiaries of this shift. Their appeal lies in their high protein content, which provides maximum nutrition in smaller quantities—a significant advantage for GLP-1 users. As a result, producers are seizing the opportunity and increasing production to meet this burgeoning demand. However, this focus on highly concentrated products has led to a notable decline in the availability of less concentrated whey products, such as WPC-35 and generic whey powders, subsequently driving their prices upwards. 

The trend is not isolated to whey products alone; nonfat dry milk (NDM) is also experiencing a price rally. International demand, especially from Asian markets, is boosting prices and putting upward pressure on NDM. The strategic realignment of milk utilization, drawn towards expanding cheese production capacities, means that less milk is available for drying into powders, further tightening supply and bolstering prices.

Global Dynamics: A Double-Edged Sword for the U.S. Dairy Sector

In a landscape where international market dynamics play an indispensable role, the U.S. dairy industry finds itself at an intriguing intersection of opportunity and challenge. The competitive pricing of American butter and cheese has captivated the attention of global buyers, even amidst a strengthening dollar that typically renders exports pricier. This underscores U.S. products’ inherent attractiveness and quality, allowing them to carve a niche in fiercely contested international arenas. 

The Global Dairy Trade (GDT) auctions are a barometer of dairy market sentiment, reflecting the waxing and waning of demand across continents. Notably, demand from Asian markets has reverberated through these auctions, pushing milk powder prices upward and signaling robust consumption patterns. This has provided a counterbalance to increased milk production in traditional dairy heavyweights like Australia and New Zealand. Consequently, the buoyancy in milk powder prices, as witnessed in the GDT’s price upticks, underscores the enduring global appetite that shores U.S. exports. 

Such international influences are pivotal in dictating the trajectory of U.S. dairy prices. The interplay between competitive pricing strategies and overseas solid demand is a dual catalyst, enabling the U.S. industry to maintain export momentum despite overarching currency headwinds. As these global currents continue to tilt market scales, they offer a window into the future positioning of U.S. dairy on the world stage.

Economic Weathering: Navigating Dairy’s Turbulent Market Shifts

As cheese and butter markets tumble, the prevailing market conditions pose significant economic implications for dairy producers. The steady decline in Class III futures—marking the eighth consecutive week of losses—suggests challenging times ahead. However, it’s important to note that dairy producers have shown remarkable resilience in the face of such challenges. Most contracts have lost approximately 20ȼ, pushing Class III values to the high $18s and low $19s. Meanwhile, Class IV prices are under strain from the drop in butter futures, with April through June contracts falling below the $21 mark. These shifts signal that while milk revenues might still cover costs for some producers, the lucrative checks experienced in recent months will dwindle by the year’s end. 

While feed markets are staging a retreat from their peaks, providing a silver lining, the overall economic landscape calls for producers to strategically navigate these fluctuating futures and feed dynamics to sustain profitability in an unpredictable dairy market. The resurgence of the winter wheat crop due to significant Southern Plains rainfall has triggered a decrease in wheat futures, subsequently dragging corn and soybean costs downward. December corn prices have dipped to $4.24 per bushel, with soybeans and soybean meal also witnessing considerable declines. This abundance and price competitiveness in the grain markets promises to lower feed costs, offering relief to dairy operators by reducing input expenses.

The Bottom Line

The article comprehensively analyzes the current cheese and butter markets, emphasizing a saturation in production and a notable price plunge. This reality contrasts with an increasing demand for dairy protein, mainly driven by health-conscious consumers and GLP-1 medication users, which has propelled whey prices upward. Meanwhile, the global market dynamics are reshaping competitive edges, especially with U.S. products gaining traction abroad due to their lowered cost. As feed markets present cost-effective options, dairy producers can maintain good profit margins despite fluctuating futures in the dairy complex. However, the question remains: How will these trends evolve, and what strategies will producers need to implement to stay competitive? Will exports continue to be a saving grace for U.S. dairy products, or will domestic adjustments become necessary? Producers should remain alert and adapt to these intricate dynamics to remain viable in the long run.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Australian Dairy Surge: Record Milk Production Spurs Market Opportunities Amid Global Competition

Discover how Australia’s record-breaking milk production unlocks fresh market opportunities amidst global competition. Will Aussie dairy farmers leverage this surge?

Summary:

In the backdrop of a flourishing start to Australia’s 2024-25 dairy season, notable production increases in Victoria and New South Wales have positioned the country favorably in the global market despite challenges from climate variability and economic pressures. September’s 1.79 billion pound output marked a 1.4% increase from 2023, with Victoria and New South Wales accounting for 75% of national production; Victoria’s volumes rose by 2.7%, and New South Wales by 5.4% for the season’s start. However, dry October conditions stressed dairy production due to soil moisture deficits in Victoria and New South Wales, prompting calls for higher milk prices to counter feeding costs. Meteorological predictions for above-average rainfall may provide relief, although risks of excessive moisture loom, impacting pasture management. Meanwhile, strategic free-trade agreements could leverage opportunities from slowing Chinese production amidst intensified competition from the US and New Zealand, requiring a refined balance in Australian strategies toward maximizing output while adeptly navigating climatic and economic adversities. 

Key Takeaways:

  • Australian milk production has grown significantly, with the strongest start since 2021-22, led by Victoria and New South Wales.
  • Dry conditions in October have affected soil moisture, prompting calls for higher milk prices to mitigate drought impact in some regions.
  • Forecasts suggest a potential increase in rainfall, which could benefit and challenge pasture conditions in key dairy areas.
  • Global dynamics, such as China’s slowed milk production, present export opportunities, while competition remains fierce with growth in U.S. and New Zealand production.
  • Australia’s and New Zealand’s participation in free-trade agreements with China offers a competitive advantage over other global dairy suppliers.
Australia milk production, dairy farmers Australia, milk production increase September 2023, Victoria New South Wales dairy, Australian dairy exports, feed costs dairy farmers, soil moisture dairy production, Bureau of Meteorology rainfall forecast, global dairy market trends, Chinese milk production slowdown.

The milk wave is rising Down Under! As Australia’s most robust milking season in years kicks off, September alone saw a record-breaking surge, with production soaring beyond 1.79 billion pounds, surpassing last year’s output for the same period by 1.4% and setting a promising trajectory for the 2024-25 season. The first quarter marks a 1.9% upswing, reminiscent of the 2021-22 season’s strength. Victoria and New South Wales significantly contribute to this increase, accounting for 75% of the national milk pool. Victoria, the crown of Aussie milk production, boosted volumes by 2.7% from July to September, while New South Wales rose by 5.4%. This growth strengthens Australia’s global dairy position. It opens export opportunities amidst slowed Chinese production, posing the pivotal question: What does this mean for dairy farmers and industry professionals?

Dairy Dynamics Down Under A Year of Growth for Aussie Milk 

It’s been a year of growth for Aussie milk, with the Australian dairy industry witnessing a compelling turn of events. The past year has seen an impressive surge in milk production, setting a robust start to the 2024-25 season. In September alone, the total milk output surpassed 1.79 billion pounds, marking a significant 1.4% increase compared to the same month in 2023 (Dairy Australia). 

A closer examination reveals that Victoria and New South Wales have been pivotal in this upward trajectory. Victoria, which accounts for a substantial portion of national production, saw its volumes swell by 2.7% from July to September, tapping into the potential that remained dormant the previous year. Meanwhile, New South Wales has outshone expectations, with collections soaring by 5.4% during the initial months of the season. This feat underscores the state’s dynamic contribution to Australia’s dairy sector (Dairy Australia). 

These figures illuminate the scale of the improvement and offer a promising outlook for Australian dairy farmers. They remind stakeholders of the critical role that regional production plays in the broader agricultural economy. As the season progresses, monitoring these developments closely will be essential for grasping the full implications of this growth on both local and global dairy markets.

Walking the Tightrope: Australian Dairy Farmers Battle Climate Extremes 

October’s dry conditions have undeniably put pressure on Australia’s dairy production, with the Bureau of Meteorology reporting extensive soil moisture deficiencies across Victoria and parts of New South Wales. These conditions stem from average to below-average rainfall, posing a significant challenge to the dairy sector in maintaining pasture growth, which is crucial for milk production. While the southern coast of Australia received sufficient rainfall to improve soil moisture marginally, the pressing issue remains in ensuring adequate feed for cattle, primarily as feed costs continue to escalate in drought-stricken regions. This situation emphasizes calls from Victorian dairy farmers for increased milk prices to offset these rising expenses. 

The Bureau of Meteorology provides a glimmer of hope, forecasting a 60-80% likelihood of above-average rainfall from December through February in major dairy-producing areas. This prediction could replenish soil moisture and boost pasture conditions, vital for sustaining and potentially increasing milk output. However, there’s a catch: unusually wet conditions might also ensue, particularly affecting the dairy-dense southeastern part of Australia. Such an occurrence could paradoxically lead to adverse impacts, as excessive rain may degrade pasture quality and complicate milk production logistics, underscoring the industry’s inherent unpredictability. 

Farmers, therefore, face a dual challenge: navigating the repercussions of dry spells and potential overabundance of rain. Balancing drought and floods to stabilize production levels is no small task, demanding strategic planning and responsive measures. The environment’s fickle nature highlights the need for adaptive strategies in farming practices to minimize weather-related risks and ensure consistent production flow amidst climatic uncertainties, showcasing resilience and innovation in the industry.

Milking Margins: Riding the Production Wave Amidst Economic Ripples

Australian dairy farmers are witnessing a notable upturn in milk production. Yet, the economic landscape presents a complex local and global scenario. A 1.4% increase in output from September of the previous year and a 1.9% rise in collections for the season signal positive production trends. However, rising feed costs threaten to outpace the benefits of increased production. 

As Graham Forbes, President of the New South Wales Farmers’ Dairy Committee, commented, “While increased production is promising, the surge in feed prices is eroding our margins faster than we can produce. Without adequate compensation in milk prices, sustaining production at profitable levels is challenging.” [Source: Dairy Weekly, November 2024] 

On the global stage, Australia’s increased output positions it favorably as China’s milk production slows, offering the potential for expanded exports. Yet competition remains fierce with New Zealand’s and the United States’ robust production seasons. The interplay of these dynamics could lead to price fluctuations, affecting the global supply chain. 

Furthermore, the calls for higher milk prices reflect the pressures faced by farmers in drought-hit regions, accentuated by the recent dry conditions. An industry representative stated, “Our farmers are working tirelessly under these tough conditions, and fair pricing will ensure the continued viability of the dairy sector amidst these climatic and economic challenges.” [Source: Victorian Dairy Insights] 

Ultimately, while output rises and the export market beckons, the profitability for Australian dairy farmers hinges precariously on the delicate balance of production costs and competitive market pricing.

Pivot Points in the Global Dairy Shuffle: Will Australia Seize the Advantage?

The international dairy landscape is a complex web where Australia’s recent production surge could play a pivotal role. As other major producers, like China, the United States, and New Zealand, lay out their strategies, Australia stands amid a potential crossroads. China’s milk production has recently slowed, suggesting an opening for exporters. This slowdown represents a golden opportunity for Australia, especially given China’s considerable demand for dairy imports. Additionally, Australia and New Zealand benefit from free-trade agreements with China, which bolster their export appeal over other global dairy contenders. 

However, the competitive dynamics are to be considered. While China’s demand offers promise, competition from the United States and New Zealand is formidable. The United States, experiencing a resurgence in milk production, and New Zealand, launching its season with zest, both seek to capture larger export markets. This increase in global supply could potentially drive prices down, intensifying the battle for market share. However, Australia’s strategic agreements and geographic proximity to Asian markets could tip the scales in its favor, even as the situation remains as fluid as ever.

Free-Trade Agreements: Australia’s Strategic Edge in the Dairy Game

Australia’s free-trade agreements with China bolster its strategic position in the global dairy market. These agreements offer Australian dairy exporters reduced tariffs and less restrictive trade barriers, providing them with more accessible and competitive access to one of the largest dairy-consuming markets in the world. This preferential access can be a game-changer for Australia, especially given China’s recent domestic production slowdown, which has created potential gaps in supply that Australian dairy farmers could fill. 

Moreover, competition is heating up, with rivals like the United States seeing a resurgence in milk production and New Zealand enjoying a solid start to its season. However, Australia’s unique trade relationship with China presents an opportunity to secure more stable and lucrative export channels. By capitalizing on this advantage, Australian exporters can position themselves more favorably against their competition. This could involve exploiting market niches that match the strengths of Australian dairy products, such as high-quality cheese and powdered milk, which are in demand in China. 

For Australian dairy farmers, leveraging these trade agreements goes beyond merely increasing export volume—it also involves optimizing market positioning to enhance profitability. Farmers and producers might consider aligning their product offerings with the preferences of Chinese consumers, possibly tailoring production techniques or product ranges to better meet these tastes and standards. Additionally, scaling up production in anticipation of increased demand is a strategic move that requires careful planning to ensure sustainability even amidst fluctuating climatic and economic conditions. 

Ultimately, these opportunities underscore the need for robust export strategies that examine long-term market trends. Australian dairy farmers could benefit from collaborating closely with trade experts to navigate the evolving landscape of international dairy markets, thereby strengthening their position in the global supply chain. This proactive approach will help them capitalize on current opportunities and anticipate future market shifts.

The Bottom Line

The Australian dairy industry stands at a crossroads, demonstrating resilience and growth potential amidst climatic challenges and global competition. The industry is poised for a strong year, with milk production on the rise, mainly fueled by output in Victoria and New South Wales. However, dry conditions and soil moisture deficiencies threaten to dampen this trajectory. While a forecast of above-average rainfall offers hope for pasture rejuvenation, the specter of overly wet conditions looms as a double-edged sword that could disrupt productivity. 

Globally, the slowing of China’s milk production presents a silver lining for Australian exports. Yet, the resurgence in the U.S. and New Zealand dairy sectors may intensify the competition in international markets. Australia’s strategic free-trade agreements position its dairy products favorably, yet climate volatility and global market dynamics remain significant hurdles. 

The industry’s adaptability will be pivotal as the dairy farming landscape evolves. Will Australian dairy farmers capitalize on their unique advantages and solidify their standing in the global arena, or will the elements of unpredictability and fierce competition steer them off course? The future of dairy farming in Australia is ripe with possibilities and perils, beckoning stakeholders to navigate with both caution and resolve.

Learn More:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Expansion in Cheese Production: Preparing for Surplus and Its Impact on Dairy Markets

How will the new cheese capacity affect dairy markets? Could a surplus lower prices? Explore potential supply and demand changes.

Summary:

The U.S. cheese industry is set to undergo a dramatic transformation with new production capacities, such as the advanced facility in Kansas, one of three major projects aimed at boosting national cheese output over the next six months. Currently, the industry sees vigorous export activity alongside a moderate rise in domestic consumption. As of September, U.S. cheese exports increased by 22% over the previous year, while domestic demand grew by only 0.6%, prompting questions about future supply and demand equilibrium. Forecasts a daily increase of 20 million pounds in cheese production by mid-2025, which presents potential surplus challenges unless domestic and global demand accelerates significantly. This expansion contrasts with tight inventories and record exports, as cheese inventories fell by 108 million pounds, marking a 7.3% decrease from the previous year. To prevent oversupply and price declines, the industry must strategically balance the growing supply against current demand trends, profoundly impacting cheese and Class III pricing. Practical strategies, including advanced refrigeration technology and dynamic distribution networks, can help manage increased production without leading to an oversupply crisis in 2025.

Key Takeaways:

  • Milk is flowing to a new cheese production facility in Kansas, with three significant expansions to U.S. cheese production expected in the next six months.
  • The rising cheese demand kept inventories in check, with a 7.3% deficit compared to the previous year.
  • U.S. cheese exports have surged 22% this year, outpacing the modest 0.6% growth in domestic consumption.
  • Additional processing capacity is projected to boost cheese output by nearly 20 million pounds daily by mid-next year.
  • A potential increase in supply could lead to lower cheese and Class III prices in 2025 if demand does not accelerate.
dairy industry trends, cheese production facility Kansas, cheese inventory challenges, U.S. cheese exports, dairy market pricing dynamics, supply chain solutions dairy, environmental sustainability dairy, advanced refrigeration technology, precision agriculture in dairy, Class III milk prices 2025

Welcome to a groundbreaking moment in the dairy industry—where the milk flow transforms into a deluge of cheese. The new production facility in Kansas, set to become one of the nation’s most extensive cheese production facilities, heralds the dawn of an era poised to redefine the nation’s cheese supply landscape. It significantly boosts production capacity, potentially adding nearly 20 million pounds of cheese output daily by mid-2025 and a wave of anticipation. With cheese inventories already tight and U.S. exports setting records, this development challenges us to consider: what does this mean for the future of the dairy market, and how will dairy farmers and industry professionals navigate this transformative shift amidst the ever-competitive dairy sector?

Navigating A Cheesier Future: Will Demand Match Supply? 

The cheese market is currently characterized by a complex interplay of supply and demand, with nuanced shifts shaping its landscape. Amidst these dynamics, the recent decrease in cheese inventories signals a pivotal moment for the industry, drawing attention to the intricacies of the domestic and global appetite for cheese. As of the end of September, inventories were down by 108 million pounds, marking a 7.3% dip compared to the previous year. This contraction highlights the intensifying demand outpacing production, a phenomenon primarily buoyed by a surge in exports. 

Exports have demonstrated a remarkable growth trajectory, boasting a 22% increase from the preceding year. This surpasses the tepid domestic consumption growth of a mere 0.6% over the same timeframe. This stark contrast between the international and local markets underscores a critical question: Can the domestic market catch up with the global enthusiasm for U.S. cheese? 

The market faces an imminent challenge with the anticipated influx of new production capacities, poised to add nearly 20 million pounds of cheese output per day by mid-2025. It must balance these burgeoning supplies against current demand patterns. This ‘delicate balance’ refers to the need to match the increased production with a corresponding increase in demand to avoid oversupply and price drops. The outcome of this balance will significantly influence pricing and inventory levels moving forward. Therefore, dairy professionals and stakeholders might ponder whether the robust export demand can continue to offset the slower-growing domestic consumption or if alternative strategies will be necessary to manage the evolving market conditions.

From Farm to Factory: A Transformative Era for Cheese Production

The upcoming cheese production facilities significantly enhance the industry’s infrastructure, commencing with the newly operational plant in Kansas. This facility and its counterparts aim to inject an impressive 20 million pounds of cheese daily into the market once all expansions reach total capacity. These projects are pivotal, marking the most significant increase in cheese production capacity in recent years and signifying a proactive stance toward meeting domestic and international projected consumption rates. 

With such robust increases in production, the industry might soon grapple with the potential for a surplus. Should consumer demand fail to keep pace with the burgeoning output, cheese prices could dwindle, potentially impacting dairy farmers and suppliers reliant on stable, higher-class III prices, traditionally buoyed by balanced supply and demand. This possible surplus could also reconfigure export strategies as the U.S. looks to capitalize on global markets amidst fluctuating domestic consumption patterns, reinforcing the intricate balance between supply chain stability and market growth.

Surge or Slump? The Complex Chessboard of the Cheese Industry

The anticipated surge in cheese production doesn’t solely spell opportunity; instead, it introduces a complex landscape of challenges for dairy farmers and industry professionals. However, with strategic planning, higher production capacity can be managed effectively, preventing an oversupply crisis. This approach can help mitigate the risks of declining cheese and Class III prices, potentially squeezing profit margins. How can farmers and producers mitigate these financial pressures? The solution might lie in strategic alliances or cooperative marketing efforts to enhance market access and stabilize prices. 

Furthermore, farmers must consider logistical issues while meeting the technical demands of increased production. How can transportation and storage infrastructure support such growth without incurring prohibitive costs? Implementing advanced supply chain solutions may prove vital. Innovations like enhanced refrigeration technology and dynamic distribution networks could optimize operations and ensure product quality isn’t compromised in transit. 

Conversely, shifting to this higher production capacity can catalyze innovation within the sector. Industry players should see the increased output as a challenge and an unprecedented opportunity to diversify product lines. Imagine leveraging the expanded capacity to explore cheese varieties that cater to niche markets or health-conscious consumers. This proactive approach could open new revenue streams, aligning production with evolving consumer preferences. The potential for innovation in this context is not just a necessity but an inspiring opportunity to transform the industry. 

Moreover, environmental sustainability concerns necessitate thoughtful consideration. How can companies implement greener practices to minimize ecological impacts as production scales? This is not just a question of profitability but a responsibility to the environment and future generations. Emerging technologies in precision agriculture and waste management present opportunities for sustainable growth. Adopting these innovations could enhance environmental stewardship and appeal to the growing segment of environmentally conscious consumers. 

In conclusion, dairy farmers and professionals must think absitively and act decisively. They can transform potential challenges into lucrative opportunities by embracing change and spearheading innovation. What role will you play in this evolving narrative of the cheese production landscape? How will you harness the power of innovation to navigate the delicate balance between supply and demand, turning risks into rewards?

Ripple Effects of Expanded Capacity: Navigating Pricing Dynamics in 2025

The ripple effects of expanded cheese production capacity are poised to reshape pricing dynamics within the dairy market, particularly concerning cheese and Class III milk prices in 2025. The pressing question is whether demand can keep pace with the substantial influx of supply. Suppose the current trajectory of domestic consumption, which shows a sluggish 0.6% increase, persists. In that case, dairy farmers and industry stakeholders may face downward pressure on prices. The growth in processing capacity can lead to oversupply scenarios unless balanced by matching demand upticks.” 

Moreover, global market trends play a critical role in determining price movements. With U.S. cheese exports exhibiting a robust 22% increase through September, driven by competitive pricing and global demand, the international market offers hope for excess supply absorption. Nevertheless, reliance on export markets brings uncertainties, especially with fluctuating trade policies and currency exchange rates impacting competitiveness. 

Broader economic indicators, such as inflation rates, consumer spending power, and alternative food trends, might influence the future pricing landscape for cheese and Class III milk. A confluence of global economic shifts and consumer behavior changes could cushion or exacerbate the expected pricing impacts from heightened production capacity.” These insights suggest a precarious balance between supply and demand, with far-reaching implications for the industry’s profitability and strategic planning in 2025.

The Bottom Line

As we stand on the brink of a transformative era in cheese production, several critical points rise to prominence. The new facilities in Kansas and beyond signal a profound shift in cheese processing capacity that could alter the supply and demand landscape. While international markets seem voracious, domestic growth remains a cautious climb. As supply threatens to outpace demand, a swollen inventory looms on the horizon, poised to challenge the pricing equilibrium. 

Industry leaders and stakeholders must ask themselves: How will they harness this abundance without allowing prices to plunge? The call to strategize becomes apparent as the cheese industry navigates these intricate dynamics. Are you ready to adapt your operations and marketing to meet these evolving demands, or will you allow the tides of change to dictate your path? Embrace the challenge, think creatively about sustaining demand, and ensure your position in this expanding market remains solid and unyielding.

Learn more:

New Zealand Milk Prices Soar Amid Global Production Shifts

High New Zealand milk prices signal changes in the dairy industry. Is your business ready?

Summary:

As New Zealand remains at the forefront of the global dairy industry, recent shifts in milk prices have brought both opportunity and challenge. The GDT index’s notable 1.2% increase underscores dynamic dairy economics influenced by global supply chains and regional consumption patterns. An estimated NZD 9.65/kg milk price highlighted by Fonterra’s forecast adjustment reflects these market shifts, requiring strategic consideration by dairy professionals. With milk prices rising to $9.68 per kg/MS, global concern mounts over potential impacts on profitability, trade agreements, and pricing strategies. The global dairy landscape, marked by varied US and EU milk production trends and increasing Asian market imports, reveals a complex interplay between declining production and rising demand, expected to persist into 2025. New Zealand’s role remains pivotal in shaping international pricing dynamics and production trends.

Key Takeaways:

  • The New Zealand milk price is estimated at around $9.65 – NZD 9.68/kg, reflecting a strong market despite mixed product performance.
  • Fonterra has adjusted its forecasted milk price range to $8.25 – $9.75, with current calculations trending toward the higher end at $9.48.
  • The Global Dairy Trade (GDT) Index increased by 1.2%, with Whole Milk Powder (WMP) being the primary driver of this growth.
  • A decrease in North Asia’s purchases, except for WMP, was offset by increased demand from Southeast Asia and the Middle East for various products.
  • New Zealand’s labor market faces challenges, including rising unemployment and a notable drop in participation, raising concerns about potential interest rate cuts by the RBNZ.
  • U.S. milk production is slightly down, though more robust milk components have offset headline declines; however, concerns rise due to the spread of bird flu.
  • EU milk production showed weaker than expected figures, with France significantly contributing to the lower output despite increased protein content.
  • Global dairy import demand significantly rose in July, especially from regions outside China, contributing to higher dairy prices.
New Zealand milk prices, global dairy market trends, milk production fluctuations, dairy farmer profitability, international trade agreements, Southeast Asia dairy imports, EU milk production decline, US milk production resilience, dairy pricing strategies, global milk supply and demand.

The sudden surge in New Zealand’s milk prices, estimated at an impressive $9.68 per kg/MS, has captured the global dairy industry’s attention, signaling potential shifts in milk production, trade, and pricing strategies. This upward trend is not just a local phenomenon. Still, it could impact everything from dairy farmer profitability to international trade agreements, sparking questions about the implications for farmer incomes, import and export flows, and strategic recalibrations by key dairy players. As the industry faces these challenges, discussing these price fluctuations becomes crucial, offering insights for those steering the dairy industry’s future.

Global Dairy Dynamics: Shaping the Future of Milk Pricing 

Over the past year, the global dairy landscape has substantially influenced milk prices internationally. Key production regions, notably the United States (US) and the European Union (EU) are experiencing nuanced milk output changes, directly impacting global supply and demand dynamics. 

In the US, milk production has demonstrated remarkable resilience despite minor fluctuations. August saw a nominal 0.1% year-over-year decrease in headline milk production, accompanied by a favorable uptick in fat and protein content. This resulted in component-adjusted production rising by 1.8% [US Department of Agriculture]. This strength in milk components has propped up the US’s overall output, instilling confidence in the industry’s stability. However, emerging threats such as the avian influenza outbreak in California might disrupt this trend in subsequent months. 

Conversely, the EU has faced a more pronounced decline across the Atlantic. The July figures revealed a 0.5% drop in headline milk production, slightly missing projections. France, a pivotal player in the EU dairy sector, experienced a mere 1.2% increase in production against an anticipated 2.3% [European Milk Board]. The EU’s struggles have been compounded by erratic weather patterns and fluctuating feed costs, contributing to lessened yields. 

These production dynamics are reverberating across global markets. Asian markets, particularly Southeast Asia and parts of the Middle East, have ramped up imports due to local shortfalls and increasing consumption demands. Despite a cooling in global dairy imports during May and June, July’s figures bounced back robustly, with an over 10% increase year-over-year, partially offsetting earlier declines. Such demand surges amid regional production challenges invariably strengthen milk prices, a trend expected to persist into 2025. 

Analyzing these trends, the interplay between declining production in critical regions and rising international demand underscores a complex dairy market landscape. Stakeholders and industry professionals must remain vigilant, as these variables will likely continue to shape pricing and availability in the foreseeable future. This alertness is critical to navigating the ever-changing market dynamics.

New Zealand: The Vanguard of Global Dairy Dynamics

New Zealand is pivotal in the global dairy market, often serving as a bellwether for international pricing dynamics and production trends. As a leading exporter, New Zealand’s dairy farms are honed to maximize efficiencies and adapt to global demand shifts. This adaptability is essential in a market characterized by fluctuating international trends. While initially renowned for its substantial rural landscape and climate conducive to extensive pastoral dairy farming, New Zealand’s position in the industry now interlaces complex strategies that reflect a global interplay of supply and demand forces. 

Recent adjustments in Fonterra’s milk price forecast offer a clear window into how external pressures influence local pricing strategies. By raising its forecasted milk price range to between $8.25 and $9.75, Fonterra’s cautious optimism indicates expectations of robust demand in the future despite recent market volatility. This shift highlights New Zealand’s responsiveness to global market signals. Fonterra’s adjustments reflect an interpretation of current and anticipated international dairy demand and production conditions. 

The Global Dairy Trade (GDT) auction results illustrate New Zealand’s interconnectedness with global markets. October’s GDT auction, showing a moderate increase in the index, underscores the high stakes of New Zealand’s dairy sector as it reacts to ongoing fluctuations in global demand. Especially noteworthy is the rise in Whole Milk Powder prices, which bolsters Fonterra’s confident pricing outlook. The auction results reveal nuanced consumer demand patterns in critical regions such as North and Southeast Asia. These regional purchases impact pricing strategies, aligning with examples from other regions like the aggressive purchasing strategy seen in the Middle East for Anhydrous Milk Fat. 

Overall, milk production strategies in New Zealand must remain fluid to fully leverage shifts in global demand. The local market’s susceptibility to international trends in employment, currency exchange rates, and global milk production analyses—as evidenced by strategist observations post-GDT events—demands an acute perception aligned with both micro and macroeconomic Dairy Market dynamics. The intersection of these multiple influences continues to challenge New Zealand to innovate and engage strategically, sustaining its premier standing in the global dairy market.

Navigating the Crosswinds: Economic and Political Influences on Milk Prices

The interplay between economic and political spheres undeniably shapes the milk price landscape. As the US election unfolds, it casts a long shadow over global market dynamics, including the dairy sector. The uncertainty surrounding the election results has already sent ripples through the currency markets. The NZD/USD exchange rate, particularly volatile in this period, reflects the market’s anticipation of potential political shifts. A potentially divided Congress could buoy the New Zealand dollar. At the same time, a decisive victory for either party in the US might spell trouble, exacerbating volatility. This volatility could impact the cost of imports and exports, potentially affecting the competitiveness of New Zealand’s dairy products in the global market. 

New Zealand’s recent employment report paints a sobering picture regarding economic indicators. A rise in unemployment paired with diminishing wage growth sets the stage for potential monetary policy shifts. Should the Reserve Bank of New Zealand opt for a substantial interest rate cut, as some speculate, this could further influence the Kiwi dollar’s performance against the US dollar. A significant interest rate cut could weaken the New Zealand dollar, making New Zealand’s dairy products more competitive globally. 

These currents of economic and political change ripple through the dairy industry, shaping market expectations and influencing milk pricing. The intertwined relationship between currency exchange rates and product pricing becomes particularly crucial for exporters reliant on competitive exchange rates to maintain margins. 

Moreover, global trade policies and the specter of increasing US tariffs inject additional complexity into the equation. Higher bond yields and protectionist measures could contract the competitive landscape, placing additional pressure on dairy exports from regions like New Zealand. Dairy professionals must navigate these uncertain waters, continuously adapting strategies to weather the political and economic headwinds that threaten to impact global milk prices. Increased tariffs could reduce the demand for New Zealand’s dairy products in the US, affecting the overall global market dynamics.

Navigating New Realities: Unpacking the Implications of Rising Milk Prices

The rising milk prices herald a complex landscape for dairy farmers in New Zealand and globally. While the immediate implication might be a promising surge in revenue owing to higher market prices per kilogram of milk solids, the path ahead is beset with challenges that demand strategic thinking and adaptability. 

For New Zealand farmers, the increase in milk prices could initially seem like a boon. The SGX/NZX MKP estimate increased to NZD 9.70/kg, underscoring a potentially profitable season. However, the narrative is full of complexities. The ongoing rise in operational costs, spurred by inflationary pressures on inputs such as feed, labor, and fuel, could erode the financial gains from higher milk prices. The essence lies in effective cost management and strategic investments within this intricate balance of costs and revenues. 

The scenario mirrors similar dynamics globally. Dairy farmers across continents are witnessing shifts in demand and supply chains, which, coupled with climatic events and trade policies, complicate the economic landscape. In regions where dairy is a significant economic activity, milk price fluctuations can also have ripple effects on rural employment and community well-being. 

Innovation within the dairy industry presents a significant opportunity. As the industry advances towards sustainability, investing in adaptive solutions like precision farming, alternative feed sources, and energy-efficient practices could mitigate rising costs. Moreover, exploring diversified income streams through dairy-based products might offer financial resilience in volatile markets. 

Readers, especially those within the industry, should consider the strategic pivots their operations might require. Could technological adoption be the key to reducing production costs? Can a cooperative approach help negotiate better prices for inputs? Ultimately, embracing a forward-thinking mindset might be the key to converting today’s challenges into tomorrow’s opportunities.

Strategic Vision: Navigating the Complex Terrain of Global Dairy Markets

As global dairy dynamics evolve, the future holds a spectrum of possibilities shaped by persistent market volatility and economic fluctuations. Present economic indicators and milk production data suggest a complex landscape for the dairy sector. With uncertainties surrounding international trade regulations and potential shifts in consumer demand, the industry must brace for varied scenarios. Geopolitical tensions and their impact on currency fluctuations further complicate the forecast. 

Dairy leaders must, therefore, engage in strategic planning more than ever. Anticipating the ebbs and flows of milk prices will require agility and foresight. Diversifying market reach, optimizing production efficiencies, and staying abreast of technological innovations could offer competitive advantages. Collaborative efforts and robust risk management strategies will be pivotal in navigating potential supply chain disruptions and sudden shifts in global demand. 

Ultimately, while challenges abound, opportunities for growth and transformation within the dairy industry are abundant. Professionals equipped with strategic foresight will not only withstand today’s uncertainties but also spearhead innovation and sustainability in dairy production for the future.

The Bottom Line

Conclusion: Summarize the key points discussed in the article. Leave the reader with a thought-provoking statement or question that encourages them to reflect on the future of the dairy industry and their role within it. Reinforce the importance of staying informed and adaptable in a rapidly changing market.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

U.S. Dairy Exports Hit Record Highs in September: A Boost for Farmers Amid Global Price Surge

Explore the record-breaking highs of U.S. dairy exports in September and what this means for the future. How will global price surges impact farmers?

Summary:

In September, U.S. dairy exports experienced significant growth, reaching $707 million, marking a six-month peak, as global demand for American dairy products surged. Cheese exports set a record with 86.3 million pounds, mainly due to a 19.4% increase in shipments to Mexico compared to the previous year. While nonfat dry milk and whey exports increased year-on-year, they fell short of the exceptional volumes in 2022. These trends have stabilized domestic markets by preventing oversupply and have driven up prices. Simultaneously, global dairy markets have strengthened, as evidenced by rising prices at the Global Dairy Trade auction, with most products, except lactose, hitting two-year highs. The U.S.’s position as a foremost dairy exporter reinforces its role as a critical player in the international dairy sector, distinguished by its products’ high quality and safety standards.

Key Takeaways:

  • U.S. dairy exports reached a six-month high in terms of value in September, driven by robust cheese shipments and significant sales growth to Mexico.
  • Despite some declines compared to previous years, nonfat dry milk and whey exports remain strong, helping manage U.S. inventory levels.
  • Market dynamics show increasing prices across dairy products at the Global Dairy Trade auction, except for lactose, which declined.
  • The boost in U.S. dairy exports positions the country as a competitive player in the global dairy market amid evolving trade patterns.
  • Industry stakeholders face opportunities and challenges as they adapt their strategies to leverage export growth while managing market volatility.

U.S. dairy exports, demonstrating remarkable resilience and strategic acumen, surged to an impressive $707 million in September, reaching the peak of the past six months. This remarkable milestone highlights the growing global demand for American dairy products and instills confidence in the strategic capabilities of the U.S. dairy industry. As the industry revels in this resurgence, a significant question emerges: What implications does this hold for the future trajectory of the U.S. dairy sector? As demand trends shift and markets continue to evolve, the impacts of this growth are extensive, encouraging a thorough examination of the long-term sustainability and adaptability of this upward trend. The record-setting statistics from September mark a crucial juncture for U.S. dairy, with extensive consequences that could redefine its global standing.

Riding the Wave: The U.S. Emerges as a Dairy Superpower

The global dairy market has been experiencing a significant uptrend characterized by rising prices and burgeoning demand. Several factors drive this escalation, including increased consumer desire for dairy products in emerging markets and the growing appetite for protein-rich foods. According to recent statistics, worldwide dairy consumption has surged, reflecting a 20% increase over the past five years, with a notable demand spike in Asia and Africa. 

The USDA’s Global Agricultural Trade Systems (GATS) is pivotal in this dynamic landscape. GATS meticulously gathers data on U.S. agricultural exports, providing critical insights into trade volumes, destination markets, and price movements. This information is essential for stakeholders across the dairy supply chain, allowing them to make informed decisions and anticipate market shifts. GATS essentially serves as a compass, guiding the industry through the ever-changing currents of the global dairy market. 

The United States stands out as a formidable force in the global dairy arena, not only as a leading producer but also as a significant exporter. U.S. dairy products, renowned for their quality and safety standards, are in high demand globally, with exports expanding by more than 31% over the last decade. American dairy exports have been instrumental in meeting the growing global demand, making the U.S. an indispensable player in the international dairy sector and a benchmark for other countries engaged in dairy trade.

From Farm to Fiesta: U.S. Cheese Exports to Mexico Surge 

In September, the cheese export narrative took a robust turn. The United States marked a paradigm shift by dispatching an impressive 86.3 million pounds of cheese beyond its borders. This figure represents the highest September cheese export volume on record and a 6.8% increase compared to last year. This data, sourced from the USDA’s Global Agricultural Trade Systems, underscores the growing international demand for U.S. cheese, further propelled by strategic market maneuvers such as targeted marketing campaigns and competitive pricing strategies. 

Mexico, a perennial powerhouse in U.S. cheese exports, continues to play a pivotal role, reflecting its burgeoning appetite for American dairy products. Shipments to this key partner surged by an extraordinary 19.4% from the preceding year, cementing Mexico’s status as a crucial market destination and showcasing its economic symbiosis with the U.S. dairy sector. 

This uptick is manifold, effectively offsetting the deceleration in cheese sales to certain Asian territories. It exemplifies dynamic adaptability within export strategies focused on bolstering relationships with proximate neighbors. Such strategic targeting cultivates closer economic ties and supports broader trade balances amidst fluctuating global conditions.

Nonfat Dry Milk and Whey: Balancing Act for Market Equilibrium

The export performance of nonfat dry milk (NDM) and whey is multifaceted, presenting both hurdles and growth opportunities. Notably, exports of NDM surged by 15.6% compared to the previous year, breaking a new September record for shipments to Mexico. However, it is critical to highlight that current figures still lag behind those achieved in 2022 and 2021, reflecting a tapering off from earlier highs. 

In contrast, whey product exports also exhibited a robust performance, marking a 15.3% increase over the September 2023 numbers. Despite this growth, these figures fell short of the unparalleled pace set in 2022. The deviation showcases the ebb and flow characteristic of international demand and market dynamics, directly affecting inventory management practices. However, the robust performance of whey product exports reassures the audience about the industry’s adaptability to market dynamics. 

These export volumes have weighed heavily on U.S. milk powder and whey powder stockpiles. The industry successfully regulates inventory levels by maintaining a healthy outflow of products, preventing oversaturation. This capacity to keep stocks aligned with market demand is pivotal, as it directly influences commodity prices. 

Ultimately, the positive uptick in exports helps rein in inventories, reflecting an agile response to fluctuating market conditions. As the CME spot market prices for whey and NDM edge close to their 2024 peaks, it becomes evident that balancing production output with export activities is critical to sustaining favorable price thresholds.

Market Momentum: Riding the Bullish Waves in Dairy Trading

The upward trajectory in market responses has been a significant focal point for analysts and dairy farmers alike. In September, the CME spot market and the Global Dairy Trade (GDT) auction reflected bullish tendencies. Whey and nonfat dry milk (NDM) prices rallied within a whisker of their 2024 highs on the CME spot market, showcasing remarkable resilience. This price strengthening indicates robust market demand, buoyed by substantial export volumes that have helped keep domestic inventories from ballooning. 

The GDT auction provided another bullish narrative worldwide, with the GDT Index reaching its highest point since July 2022. This resurgence was echoed in the elevated prices for a spectrum of products, including anhydrous milkfat, which achieved its highest price since it started trading on the platform in January 2018. The price rallies for cheddar, whole milk powder, skim milk powder, and buttermilk powder underscore a market willing to pay a premium for these commodities, reflecting improved purchasing power and demand from international buyers. 

For U.S. dairy farmers, these price trends are more than just a welcome reprieve; they signify a potential shift in economic conditions that could spur increased profitability. Farmers adept in adjusting their production strategies in response to such market signals stand to benefit significantly. As the market volatility continues to unfold, the ability of U.S. producers to adapt to these trends will be crucial in sustaining their competitive edge in the global dairy landscape.

The Bottom Line

U.S. dairy exports reached new heights in September, with cheese, nonfat dry milk, and whey setting notable records. This upward trajectory boosts the nation’s standing in global markets. It signifies a robust demand that could influence supply chains and inventory management. The impressive figures point to strong international relationships, particularly with Mexico, which are testaments to the expanding markets for American dairy products. As dairy farmers and industry stakeholders, pondering these. developments and their long-term implications is essential. How might these changes shape your business strategies? Could this surge affect domestic prices or inventory levels down the line? These trends are more than just statistics; they are indicators of potential shifts in the market that warrant close attention and strategic response. The challenge lies in adapting to and capitalizing on these dynamic market conditions to foster sustained growth and competitiveness in the global arena.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Countdown to 2024 Election: Will the Toss-Up Race Between Trump and Harris Tip the Scales?

Discover the tight 2024 race between Trump and Harris. Can swing states decide it? Expert insights and impacts on dairy farmers await.

Summary:

The 2024 presidential race between Donald Trump and Kamala Harris is intensely unpredictable, described as a “pure toss-up,” with Trump holding a slight edge at 51.5%. The decisive battlegrounds of Georgia, North Carolina, Pennsylvania, Wisconsin, Michigan, Arizona, and Nevada are pivotal. Both candidates present contrasting policies with significant implications for industries, including agriculture, and potential global economic ramifications, especially concerning China. Trump’s fiery rhetoric contrasts with Harris’s unifying discourse as they campaign vigorously. Control of Congress also adds tension to the election landscape, making the outcome uncertain and impactful beyond U.S. borders.

Key Takeaways:

  • The 2024 presidential race remains highly competitive, with analysts labeling it a “pure toss-up” due to the narrow polling margins between Trump and Harris.
  • David Wasserman notes Trump’s recent inflammatory statements have tightened the race, although he remains a slight favorite.
  • Polling data from crucial swing states will be critical indicators of which party may prevail, emphasizing the importance of North Carolina and Georgia.
  • Both candidates actively engage voters in critical regions, with Harris focusing on unity and Trump rallying his base provocatively.
  • The election’s outcome could substantially impact economic policies, influencing factors like corporate tax rates and tariffs, affecting dairy industry markets and consumer prices.
  • Overseas American voters have gained attention in the tight race due to low past voter turnout, making their participation potentially significant.
  • Security measures in Washington, D.C., are heightened in anticipation of potential post-election unrest, with businesses preparing for disruption.
  • Market indicators like the dollar index and stock futures reflect investors’ reactions to potential election outcomes, highlighting economic uncertainties.
  • Control of the U.S. Senate is contentious, with Republicans favored, but possible Democratic victories could alter this dynamic.
2024 presidential race, Trump vs Harris, battleground states, swing states election, voter mobilization strategies, economic impact election, pro-business policies, global trade tensions, market volatility, Fed rate policy

The clock is ticking down to one of the most unpredictable elections in U.S. history, with the 2024 presidential race a true ‘pure toss-up,’ as former President Donald Trump and Vice President Kamala Harris are locked in a battle that could tip either way. This razor-thin contest does more than determine the next leader of the free world; it holds critical implications for sectors like dairy farming, which are at stake. Policy decisions made in the days and years ahead will ripple through marketplaces to the very land where dairy farmers labor each day. From trade policies affecting exports to potential environmental regulations, the outcome of this election could change the landscape in which you operate. As elections have consequences stretching beyond immediate politics and into America’s heartland, understanding the nuances of these policies isn’t just important—it’s essential.

Polling Paradox: The 2024 Presidential Race Balancing on a Knife’s Edge

The current polling landscape for the 2024 presidential race presents an intriguing picture of a contest teetering on the edge of unpredictability. In his razor-thin forecast, renowned analyst Nate Silver assigns only a marginal advantage to former President Donald Trump, with a 51.5% likelihood of clinching the Electoral College, versus Vice President Kamala Harris at 48.1%. Similarly, David Wasserman of the Cook Political Report underscores this tenuous balance, acknowledging how recent missteps by Trump have tightened what once seemed to be his advantage. 

Adding to the complexity, the latest Des Moines Register poll findings have injected a jolt into the political betting markets. It revealed a surprising three-point lead for Harris in a state that many had presumed favored Trump. This unexpected turn has roiled market expectations, triggering a visible shift in prediction platforms such as Polymarket. Just days ago, Trump’s odds peaked at 67% as of Wednesday, yet they tumbled to 58% following the poll’s release, illustrating the market’s sensitivity to new data. 

The fluctuating odds and volatile market responses signal an election far from decided. Silver and Wasserman’s analyses reflect that the voters’ leanings in crucial swing states remain fluid, and even minor developments could tip the scales as election day approaches. The battleground states are poised to play a decisive role, and both campaign teams will likely intensify their efforts to sway those still contemplating their choice. 

The Decisive Seven: Swing States that Could Swing the Nation

The 2024 presidential election hinges on the outcomes in seven pivotal swing states: Georgia, North Carolina, Pennsylvania, Wisconsin, Michigan, Arizona, and Nevada. These states collectively hold the power to shape the electoral landscape due to their history of fluctuating political allegiances and diverse voter demographics. Both Trump and Harris strategize heavily on these battlegrounds, aware that winning a majority here could tip the scales decisively. 

Georgia and North Carolina emerge as particularly significant. Both states, representing the broader Sun Belt region, carry substantial electoral votes that can influence the overall outcome. Early results from these states offer crucial insights into the evening’s direction. A strong performance by Trump here might signal an underestimation of his support in other battleground states, prompting a reevaluation of Harris’s prospects. Conversely, if Harris gains ground or secures victories in these states, it could indicate a shift toward Democratic favor, reflecting changing demographics and increasing urbanization. 

In contrast, the Rust Belt states of Pennsylvania, Wisconsin, and Michigan are essential for building a winning coalition, given their significant electoral votes. Historically known for their swing nature, these states are critical for either candidate’s path to 270 electoral votes. A sweep by Harris in this region could effectively counterbalance Trump’s potential gains in the Sun Belt, reaffirming the Democratic hold on these vital industrial areas. 

Meanwhile, Arizona and Nevada augment their critical roles, emerging as bellwether states due to their growing and diversifying populations. Close attention to their outcomes is warranted, as victories here could serve as early warnings or confirmations of national trends. 

Ultimately, the intersection of these seven states encapsulates the election’s essence—a contest not solely of national prominence but of strategic victories within specific state borders. As results unfold on election night, all eyes will follow North Carolina and Georgia, serving as the initial barometers of either candidate’s electoral strength and the night’s overarching narrative.

Quiet Undercurrents: Overseas Americans Could Tip the Scale

The influence of overseas American voters often resembles an undercurrent, quietly weaving beneath the surface of more overt election forces. Numbering over 4 million, their potential impact is significant even as turnout historically hovers around 7.8%. Recognizing this untapped reservoir, both parties have intensified efforts to mobilize these voters, emphasizing digital outreach and localized campaign strategies. 

Foreign policy stands out as a resonant chord in this outreach, as those living abroad keenly feel the repercussions of U.S. strategies on international diplomacy, trade agreements, and military presence. These issues are abstract concepts and factors directly influencing their daily lives in host countries. 

Another pivotal issue is the taxation framework applied to expatriates. The dual-tax system, often called “double taxation,” remains a rare point of bipartisan interest. Overseas Americans face the unique burden of filing taxes in both the U.S. and their country of residence, a situation both Democrats and Republicans are capitalizing on to sway this voter demographic. 

For Republicans, Trump’s pledge to alleviate overseas tax filing burdens offers a point of attraction, potentially drawing in those frustrated by current regulations. Meanwhile, Democrats are highlighting broader foreign policy stances that emphasize international cooperation, seeking to appeal to progressive values among expatriates. As these efforts unfold, the overseas vote emerges as a compelling wildcard, a demographic whose impact on the tight 2024 presidential race is yet to be fully realized.

Contrasting Campaign Chronicles: Trump’s Fiery Fervor vs. Harris’s Harmonious Hope

In the feverish run-up to Election Day, the campaign trails of Donald Trump and Kamala Harris offer a striking study in contrasts. Both camps are laser-focused on the pivotal swing states that could ultimately decide the presidency. Trump storms key battlegrounds with fervor, utilizing an aggressive rhetoric that seeks to energize and mobilize his base. His campaign rallies resonate with fiery critiques of his opponents and evocative declarations aimed at reigniting the fervor of past victories. His speeches in crucial states like Pennsylvania and Michigan are marked by combative tones and controversial claims, reflecting his strategy to dominate the narrative and seize the spotlight through bold proclamations and media-baiting tactics. 

Conversely, Kamala Harris charts a different course. Her campaign strategy zeroes in on uniting a divided electorate. As she graces the stages in Michigan and Pennsylvania, her addresses weave a narrative of hope and reconciliation. Harris endeavors to transcend partisan divides by focusing on positive, uplifting discourse. Her message offers a distinct alternative to Trump’s approach — reaching out to independents and disillusioned conservatives, promising a future anchored in cooperation and empathy. 

Both candidates understand the stakes in these final days, yet their paths diverge in method and tone. Where Trump’s approach rides on confrontation and stark contrasts, Harris’s is a call to collective action and harmony. These varying strategies reflect broader themes each candidate hopes will resonate with voters in the crucible of the swing states, ultimately proving decisive in shaping the outcome of this tightly contested race.

Financial Fortunes and Dairy Dilemmas: The 2024 Election’s Economic Impact

The unfolding 2024 presidential election holds significant implications for financial markets and economic policies. Each candidate’s victory likely will dictate divergent trajectories for the U.S. economy. The equity and bond markets are keenly poised, anticipating either Kamala Harris or Donald Trump shaping interest rate decisions and broader fiscal policies. 

Financial Markets and Interest Rates: Should Trump reclaim the presidency, markets might expect a continuation or enhancement of pro-business, low-tax policies, potentially buoying corporate earnings and investor sentiment. However, Trump’s aggressive stance on tariffs, mainly targeting China, could ignite global trade tensions. Such measures might induce market volatility, forcing the Fed to reassess its rate policy paths, possibly stalling or reversing rate-cutting plans. 

Conversely, a Harris administration would likely prioritize environmental and social governance, balanced federal spending, and increased taxes on corporations and high-income earners. This may result in initial market pressure, as investors anticipate lower profit margins dampening stock valuations. However, Harris’ approach to stabilizing foreign trade relationships might appeal to the bond market, with expectations of reduced global economic friction. 

Impact on the Dairy Industry: The election results could usher in poignant outcomes for dairy farmers and related industries. Trump’s proposed tax cuts might translate into reduced operational costs for large agricultural enterprises, but his tariff policies could hike input prices for feed and equipment, affecting profitability. His stance on immigration could also impact labor supply, which is crucial for the dairy sector. 

On the other hand, Harris’s tax policy aimed at higher-income brackets could prove challenging for large dairy operations falling within these thresholds. However, her push to combat price gouging and regulate market fluctuations could stabilize consumer costs. Harris’s infrastructure plans, including transportation improvements, could enhance supply chain efficiency, benefiting the dairy industry long-term. 

The dairy sector is at an economic crossroads as election day draws near. Each candidate offers potential benefits and pitfalls, urging farmers to consider how these political shifts could ripple through their livelihoods.

Congressional Crossroads: The Power Struggle and Its Agricultural Fallout

As the 2024 election unfolds, the battle for control of Congress is as fiercely contested as the presidential race. The Senate landscape offers a possible shift in control favoring the Republicans, who are predicted to gain a majority. The Cook Political Report anticipates the GOP securing 51 to 54 seats, a shift that could dramatically alter legislative priorities. Such a majority could empower Republicans to advance their agenda more decisively, impacting everything from tax policy to regulatory approaches. 

This potential shift poses significant implications for agricultural policies critical to dairy farmers. With a Republican majority, legislative efforts might swing towards deregulation, which could benefit the agriculture sector by reducing compliance costs. However, these changes might also mean less government intervention in agricultural subsidies, directly affecting farm income stability. 

In contrast, the House races are more unpredictable. Described as a “jump ball,” both parties have plausible pathways to securing control. The competitive nature of these contests heightens their significance, as the House’s composition will critically influence the next administration’s legislative agenda. A Republican-controlled House paired with a Republican Senate would facilitate the passage of more conservative economic policies, potentially fostering a tax-friendly environment for businesses. On the other hand, a Democratic House could act as a check on conservative legislative initiatives, pushing for continued investment in environmental and infrastructure projects, which could benefit rural communities and farming operations. 

The results will have far-reaching implications for the dairy industry stakeholders monitoring these dynamics. The congressional makeup will define policy directions affecting agricultural trade, environmental regulations, and farm support programs, which are crucial for strategic planning and long-term business viability.

Global Ripples: The World Holds Its Breath as the U.S. Election Approaches

As the 2024 U.S. presidential election looms, international stakeholders brace for its far-reaching effects. Particularly concerned is China, monitoring the race with heightened interest. The potential for the Trump administration’s steep tariffs on Chinese imports looms large, threatening to disrupt economic balances. This specter has catalyzed preemptive discussions within China’s legislative circles, where economic stimulus measures are actively being considered. The outcome of these deliberations could dictate China’s fiscal strategies, potentially recalibrating investment channels and trade policies to offset anticipated economic turbulence. 

Further afield, global markets display a cautious stance, underscored by fluctuating indices as the possibility of policy shifts looms. While the Trump scenarios project a more tumultuous trade landscape, Kamala Harris’s focus on diplomacy could herald different international engagements. Yet, both campaigns leave little room for complacency among foreign governments, prompting preparatory adjustments to safeguard economic interests. As election day draws near, the world waits, watches, and strategizes, underscoring the global interconnectedness of political tides.

The Bottom Line

The final stretch of the 2024 presidential race underscores a landscape rife with uncertainty. With polls and prediction markets swaying like a pendulum, there is no clear frontrunner between Donald Trump and Kamala Harris. The implications for dairy farmers and stakeholders are vast—whether in taxation, international trade, or economic policies. As swing states play a pivotal role, their decision could dictate the presidency and the regulatory and economic environment that frames your day-to-day operations. 

As the election nears, it’s crucial to ponder: how will either administration’s policies ripple through the dairy sector, affecting everything from pricing to international trade agreements? What strategies should you consider to safeguard and potentially capitalize on the shifts in the political landscape? The future of your business might hinge more than ever on the choices made at the ballot box.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Class IV Dairy Products Surge: Navigating the Industry’s Growing Demand and Production Challenges

Dive into the rise of Class IV dairy products. How are farmers handling increasing demand and production hurdles? Uncover the trends and insights molding the industry.

Summary:

The dairy industry is undergoing significant shifts, with an 11.3% increase in butter production in September, leading to concerns about excess storage as demand falls behind. Manufacturers are anticipating future market changes. Meanwhile, milk powder production remains stable, with a notable 14.3% rise in nonfat dry milk (NDM) favored for local markets. Cheese production reflects changing preferences, driven by strong export demand for Italian varieties like Mozzarella, up 2.7%, while American-style cheeses like Cheddar fell by 2.6% to 311.761 million pounds. In whey, a shift towards higher protein products is evident, with a 22.5% increase in whey protein isolates to 17.11 million pounds, despite a decrease in dry whey for human consumption. These trends highlight evolving consumer preferences and market dynamics in the dairy sector, providing critical insights for stakeholders.

Key Takeaways:

  • Market trends indicate shifting production priorities in response to export demand and regional consumer preferences.
  • Butter production saw a notable 11.3% increase in September compared to last year, driving significant amounts into storage—a potential indicator of production outpacing demand.
  • Milk powder production stabilized, with a minimal year-over-year decline, suggesting a shift in focus towards local and Mexican markets.
  • Overall cheese production remained steady, though a preference for Italian cheeses like Mozzarella grew, while American-style cheese production lagged.
  • The whey stream increasingly favored higher protein products, with whey protein isolates production surging by 22.5% year over year.

The dairy industry’s shifting landscape is gaining momentum with a notable rise in Class IV products, catching the eye of dairy farmers and industry professionals alike. September revealed an uptick in butter and milk powder production, highlighting promising market dynamics. These Class IV products emphasize a growing segment that cannot be overlooked. With butter production up 11.3% over last year, dairy operations are reevaluating strategies to meet evolving market demands. Are these shifts indicating a stable, lucrative market or adding complexity to dairy production? Understanding this trend is crucial for affecting operational decisions and profit margins in the coming months.

Butter Overload: Are We Churning Our Way to a Glut?

The latest data showcases a remarkable upswing in butter production, an increase driven significantly by robust butterfat tests and soaring butter prices throughout September. This surge is not without its concerns. With production climbing to impressive heights, an inevitable question emerges: is production outstripping demand? According to the Dairy Products report, while butter production soared by 11.3%, a substantial volume was relegated to storage, hinting at a possible imbalance. 

This scenario could reflect a production overshoot versus the current market appetite. Elevated butter prices initially spurred churn activity but might not necessarily translate into stable, long-term demand. The storage figures suggest manufacturers are banking on future market needs or price shifts, a strategy not without risk. 

The statistics show that the industry’s ability to calibrate production in real-time with market demands will be tested. Should the market swiftly absorb this backlog, manufacturers might face a glut, potentially impacting pricing strategies and profit margins.

The Powder of Consistency: A New Era for Milk Powder Production

Stability has finally found its footing within the milk powder production landscape, marking a stark contrast to the erratic declines witnessed in recent months. This newfound steadiness reflects a strategic shift by manufacturers zeroing in on nonfat dry milk (NDM) production with keen attention. 

Unlike past fluctuations, September’s milk powder output saw a minor dip of 0.1%, signaling a departure from earlier months where numbers tumbled more significantly. A notable preference emerged for producing NDM, evidently tailored to satisfy the demands of local and Mexican markets—a move echoing broader strategic objectives within the industry. 

With NDM production expanding by 14.3% over the previous year, manufacturers’ inventories swelled to 249.7 million pounds. This increase hints at a readiness to cater to emerging market needs while ensuring readiness should export dynamics shift. 

Such adjustments in production strategy and inventory management reflect a responsive industry poised to leverage regional opportunities while cushioning against potential supply chain disruptions. Companies seem to align operations with consumer preferences, pointing towards a calculated push for stability amidst broader market volatility.

Cheese Choices: The Continental Shift in Cheese Production

Despite the stability in total cheese production, which remained virtually unchanged at 1.16 billion pounds in September relative to the prior year, a noteworthy shift is evident in the cheeses favored by manufacturers. This month, strong export demand has guided the market’s hand, evidenced by a notable preference for Italian cheese varieties. Mozzarella, a local and international popular choice, saw its production rise by an impressive 2.7% year over year. This uptick indicates the robust global appetite for Italian cheese, a trend producers are eager to satisfy. 

Conversely, the production of American-style cheeses paints a different picture. Cheddar, a staple in the American cheese repertoire, experienced a decline of 2.6% compared to the same month last year, falling to 311.761 million pounds. Several factors could be contributing to this downturn. Changes in domestic consumer preferences, possibly opting for more diverse and international cheese varieties, might be one reason. Additionally, the global market’s tilt towards Italian cheeses due to their versatile culinary uses could influence manufacturers to shift their focus. 

The influence of the export market cannot be understated. With U.S. dairy exports reaching broader markets, the demand for cheeses that cater to international tastes, like Mozzarella, is increasing. This aligns with the global proliferation of cuisines that prominently feature these types of cheese, ensuring they remain in high demand. On the other hand, Cheddar, while still popular, may not experience the same level of export-driven growth, particularly in regions where it doesn’t hold the same cultural or culinary prominence.

Whey Forward: The Ascendance of High-Protein Dairy Ingredients

In a notable development reflecting the ever-evolving landscape of dairy derivatives, the whey stream has markedly shifted towards products boasting higher protein concentrations. This realignment is evidenced by the substantial 22.5% year-over-year surge in the production of whey protein isolates, reaching 17.11 million pounds in September 2025. Such growth underscores a burgeoning demand for potent protein ingredients, likely driven by the dietary preferences of health-conscious consumers and the sports nutrition sector’s expanding reach. 

Conversely, this pivot to more concentrated protein offerings parallels a discernible decline in the production of whey protein concentrates, which witnessed a contraction of 9.8%. Moreover, dry whey for human consumption experienced a significant drop of 14% to just 65.18 million pounds. This decrease highlights a gradual phasing out of less refined whey products in favor of those providing more value and superior nutritional properties. 

This shift presents intriguing opportunities for dairy producers. The increased focus on higher protein isolates potentially opens new markets and applications, from dietary supplements to specialized food products catering to diverse consumer needs. As the demand for premium protein ingredients grows, manufacturers must innovate and adapt their processes to harness these lucrative prospects, potentially reshaping the industry’s future dynamic. Could this be a harbinger of a more tailored approach to whey production, prioritizing quality over quantity?

The Bottom Line

The article has unwrapped the dynamics within the Class IV dairy sector, highlighting a juxtaposition of surging butter production alongside steady milk powder output. While high butter output destined more products to storage, it presents the opportunity for dairy producers to capture potential market dips by leveraging stockpiles. Meanwhile, milk powder’s steady course reflects a preference shift with emerging markets near the United States, particularly Mexico, poised to benefit. 

As protein gains traction within the dairy stream, one must weigh the opportunities in higher protein products against traditional cheese outputs, where Italian varieties are currently favored over American styles. 

How might these trends reshape your strategies as a dairy farmer or industry professional? Will you pivot towards products gaining traction or reinforce your current production mix to navigate these shifts? The evolving landscape of Class IV products offers ripe opportunities—but only for those astute enough to seize them. Are you prepared to adapt your operations to align with these emerging patterns and maximize profitability?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

US Dairy Production Shockwave: Cheese Surprise and Skim Soar in September 2024 Report

Explore the unexpected changes in September 2024 US dairy production. What do lower cheese and higher skim milk outputs mean for the industry? Keep reading to learn more.

Summary:

The September 2024 U.S. Dairy Product Production Report offers a complex view of the dairy industry, marked by a mix of production outcomes. While cheese production fell 18 million pounds short of forecasts, particularly affecting non-Cheddar American styles, butter production exceeded expectations by 4 million pounds, leading to a 7 million pound increase in stocks. Nonfat dry milk and skim milk powder also saw an unexpected 18 million pound rise, highlighting weak domestic demand and shaping a bearish trend. This diverse production landscape impacts market dynamics, with cheese showing bullish potential due to tighter inventories, while the rise in butter and nonfat categories suggests different stock trajectories. These developments present challenges and opportunities for dairy stakeholders, influencing supply-demand balance and potentially affecting farmgate prices and consumer costs.

Key Takeaways:

  • The September 2024 dairy production report reflects mixed results, highlighting disparities in cheese and nonfat dry milk production.
  • Cheese production fell short of forecasts by 18 million pounds, contributing to lower-than-expected stock levels.
  • Unexpectedly high butter production resulted in a surplus, influencing stock dynamics.
  • Nonfat dry milk and skim milk powder production exceeded expectations by 18 million pounds, marking a year-on-year trend shift.
  • Whey production followed the downward trend in cheese production, indicating broader market implications.
  • Analyzing these trends is essential for industry stakeholders to adapt strategies and anticipate market changes.
dairy product production, cheese production decline, nonfat milk production, butter production increase, dairy market dynamics, cheese inventory trends, domestic dairy demand, skim milk powder production, dairy industry analysis, supply-demand equilibrium

The September 2024 U.S. Dairy Product Production Report has surprised industry experts with its unexpected findings. Cheese production fell short by 18 million pounds, while nonfat and skim milk production surpassed forecasts. The decline was particularly pronounced in non-Cheddar American-style cheese, which saw a 6.1% year-over-year decrease. These shifts raise significant questions: What do these changes mean for the future of dairy farming? Are these trends indicating a move away from traditional favorites, or are they merely adapting to changes in consumer demand? One thing is clear: strategic adaptations are not just necessary but urgent.

The September 2024 US Dairy Product Production Report delivered a mixed bag of surprises, with fluctuations across various categories indicating shifting market dynamics. Analyzing these trends provides critical insights for dairy farmers and industry professionals. Let’s delve into the numbers that matter. 

Unpacking the September 2024 Dairy Production Puzzle: A Tale of Divergent Trends and Market Realities

The September 2024 U.S. Dairy Product Production Report reveals a nuanced production-level landscape. Grasping the intricacies of this report is crucial for dairy farmers and industry professionals, as it presents a mix of outcomes that shape market dynamics. On the one hand, there is a notable dip in cheese production, particularly in non-Cheddar American styles, drawing attention to the market’s bullish potential in the cheese sector. Conversely, butter production surpassed expectations, suggesting a different trajectory in stock alignments. The unexpected rise in nonfat/skim milk powder production underscores a bearish trend, raising queries on domestic demand. These findings underscore the importance of strategizing by these varied production signals, impacting operational and market decisions.

Cheese Production Dip: A Ripple Effect on the Dairy Market’s Horizon

In September 2024, the cheese production scene saw a notable 18 million-pound shortfall against forecasts. This drop in output, particularly in non-Cheddar American-style cheeses like Colby and Jack varieties, which fell by 6.1% year-over-year, contributed to cheese stocks being 33 million pounds below expectations. The reduction in cheese production was separate from individual types; cheddar and mozzarella, typically the powerhouses of U.S. cheese production, also experienced a slight downturn compared to their anticipated numbers. But what sparked this production dip? 

Several factors might be at play. A possible cause could be market dynamics within the supply chain, where feed costs and dairy herd health might have unintentionally triggered lower milk production, squeezing the supply for cheese manufacturing. Weather patterns have also historically played a role in agricultural outputs, potentially impacting dairy feed crop yields and milk supplies. Such disruptions in raw milk availability can directly suppress cheese production. 

Consequently, the impact reverberates across the market. Lower cheese inventories might push prices up, creating a tighter market that could benefit producers. Yet, it also poses challenges for processors and retailers who now navigate replenished stocks and manage customer expectations and pricing strategies. Hence, stakeholders should not just monitor the trend but actively stay ahead of it because prolonged production declines could reshape the supply-demand equilibrium, affecting everything from farmgate prices to consumer costs. We are in a dynamic environment where market forces and production realities continually intertwine, setting the stage for strategic adaptations. 

The Butter Boom: Navigating the Surplus Sparked by September’s Unexpected Production Surge

The unexpected uptick in butter production during September 2024, reaching 4 million pounds more than projected, has sparked much discussion among dairy industry analysts. This upsurge coincided with a noteworthy increase in butter stocks, which soared by an additional 7 million pounds above expectations. 

The surge in production, combined with the amplified stock levels, conveys nuanced insights into current market dynamics and consumer behavior. Traditionally, elevated production would align with heightened consumption demands; however, the simultaneous rise in stocks indicates a more complex scenario. It suggests that while production capabilities have increased, consumer demand has not matched this pace, resulting in a stockpile. 

One possible interpretation is a strategic pivot by producers, anticipating future market shifts such as holiday surges or export opportunities. Another factor could be a conscious decision to harness profitable production opportunities within the current economic climate, driven by stable or declining raw milk prices, even as immediate consumer demand lags. 

Looking forward, these trends hint at potential market corrections or strategic realignments. Dairy producers might need to recalibrate strategies, possibly placing a stronger emphasis on marketing or exploring new distribution channels to align production levels with consumer requirements. The challenge lies in balancing robust production capacity with the intricate ebbs and flows of demand, a reminder of the complexities inherent in dairy sector management.

Surprise Surge: Unraveling the Unexpected Rise in Nonfat Dry Milk and Skim Milk Powder

The sudden uptick in Nonfat Dry Milk (NFDM) and Skim Milk Powder (SMP) production surprised the industry. Output soared 18 million pounds above forecast figures and aligned closely with last year’s production levels. This plateau, the first we’ve seen since June 2023, signals a significant shift in dairy processing dynamics. But what does this mean for domestic demand? The unexpected rise in production could lead to a surplus in the market, potentially impacting prices and the balance of supply and demand. 

Despite the production increase, the domestic market appears to be struggling to absorb the excess, as evidenced by stock levels ballooning by over 25 million pounds. This suggests that domestic demand for these dairy products remains weaker than anticipated, prompting questions about shifting consumer preferences or economic pressures impacting purchasing behavior. 

One possible explanation for the surplus is a change in skim milk utilization. It’s plausible that less ultrafiltered skim milk is being diverted into cheese production, nudging more toward the drying process, hence the rise in NFDM production. The aftermath is a challenging scenario where producers must balance production volumes with consumer demand, all while adjusting strategies in response to evolving market realities.

Whey’s Wobble: Navigating the Complexities of Reduced Production Amidst Cheese Market Shifts

The September 2024 report highlighted a noticeable decline in whey product production, directly correlating with the weaker cheese production figures—particularly from non-Cheddar American cheeses like Colby and Jacks. This shortfall may ripple through the whey market, impacting the supply of whey protein and related products. With whey being a critical component in numerous industries, from nutritional supplements to food processing, the decrease in production could lead to potential price adjustments and supply chain challenges. Companies relying on whey as a raw material might need to reassess their sourcing strategies to mitigate disruptions. As whey products have become a staple in diverse markets, this reduction calls for stakeholders to stay alert and possibly consider alternative options to maintain their product offerings competitively.

The Bottom Line

Examining the September 2024 Dairy Production Report reveals a complex tapestry of gains and losses in dairy product manufacturing. Lower-than-expected cheese production starkly contrasts the surge in nonfat dry milk and skim milk powder production. This disparity affects market dynamics and challenges existing operational strategies for dairy farmers. 

Dairy professionals must now grapple with these shifting landscapes, questioning the broader implications for their businesses. What do these production shifts mean for pricing, supply chain logistics, and long-term sustainability? Are there opportunities to be seized amid the volatility or threats that need strategic mitigation? 

As we stand on the cusp of yet another transformative phase for the dairy industry, one must ask: how will these production shifts shape the future of dairy farming? The answers may hold the key to thriving in an increasingly unpredictable market.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Global Dairy Market Insights: Rising Trends and Challenges for November 2024

How will rising dairy prices and production changes affect your business in November 2024? Get the latest insights now.

Summary:

The global dairy markets are facing dynamic shifts, with futures trading revealing significant activity in butter and SMP, underscoring a vibrant yet volatile landscape. Notable trends include a rise in butter prices, contrasted by weaker whey performance, reflecting evolving dietary demands. European quotes show slight declines across dairy products, except for resilient WMP, which highlights market adaptability. U.S. markets confront challenges such as the bird flu in California, impacting cheese and butter dynamics, while global milk production sees nuanced progress with regional hurdles. Future growth depends on navigating these fluctuations adeptly as stakeholders adjust to changing consumption patterns and enhance strategies for sustained success in the dairy sector.

Key Takeaways:

  • Market Volatility: Butter led in price increases on both the EEX and SGX futures, while SMP and Whey displayed mixed results, reflecting ongoing market volatility.
  • European Divergence: Despite declining prices of most European dairy products, WMP bucked the trend with a slight increase, showcasing regional market peculiarities.
  • Cheese Market Challenges: All cheese indices in Europe declined, yet they remain significantly higher than last year, highlighting a complex market situation.
  • Fonterra’s Consistency: Fonterra maintained steady offerings for global auctions, signaling stability despite regional challenges in milk production volumes.
  • Rising Milk Collections: Sharp increases in Fonterra’s milk collections in New Zealand and Australia contrast with Italy’s slight decline, indicating differing regional dynamics.
  • U.S. Cheese Demand: Strong U.S. cheese demand evidenced by declining stocks suggests robust export activity, though market signals suggest potential volatility ahead.
  • Global Output Recovery: A modest upturn in global milk production points towards gradual recovery despite ongoing challenges such as flu in the U.S.
  • Stable Milk Prices: While October milk prices dipped slightly, they remained strong enough to support U.S. dairy producers, signaling financial resilience amidst market fluctuations.
  • Favorable Harvest Conditions: Optimal weather conditions in the U.S. and South America have led to a swift harvest, impacting commodity prices and potentially benefiting dairy feed costs.

This week’s report offers timely insights critical for dairy professionals strategizing for the future. As farmers and industry executives brace for the implications of harvest projections, milk price forecasts, and evolving consumer preferences, strategic planning becomes more crucial. Understand how pricing impacts margins, explore strategic planning amidst market dynamics, and gain insights into upcoming dairy trends and regulations to stay ahead in this dynamic market.

Futures on the Rise: Butter Leads the Charge While SMP and Whey Show Mixed Signals

The European Energy Exchange (EEX) trading activities have shown a noteworthy movement, with butter futures presenting a significant uptick. Over the past week, EEX butter futures traded firmer, marking the third consecutive week of increased prices, averaging at €7,300 for the Nov 24-Jun 25 strips, a 4.9% rise. This uptick in butter prices reflects a bullish sentiment in the market, potentially driven by expectations of increasing demand or reduced supply. With the total open interest climbing by 220 lots to 3,166, this indicates a strong interest from market participants, possibly anticipating further price increases. 

In contrast, the Skim Milk Powder (SMP) scenario was slightly less optimistic, with futures rising by 2.9% over the same period, settling at an average price of €2,688. The reduction in total open interest by 79 lots to 6,706 suggests a cautious approach from traders, who might perceive the price level as a temporary peak or wait for more precise market signals. This modest increase in SMP prices might hint at stable demand conditions. Still, the reduction in open interest could indicate hesitance about the sustainability of the current price levels. 

Whey futures presented a notable downturn, dropping by 3.5% to an average of €885. The unchanged open interest in whey futures suggests that traders hold their positions, perhaps expecting market corrections. The decline in whey prices could indicate shifting demand dynamics or an oversupply situation, which may pressure the market in the short term. 

The mixed trends in the EEX futures for dairy products suggest a market in flux, reacting to various supply and demand factors. While butter experiences a robust price rise, indicative of demand strength or constrained supply, SMP’s cautious gains and whey’s price dip point to more nuanced dynamics affecting the dairy sector. These trends underscore the importance of closely monitoring evolving market conditions, as they offer insights that could significantly impact pricing strategies and inventory decisions for dairy market stakeholders.

SGX Futures: A Fine Dance Between Demand and Supply 

Last week’s SGX futures trading activity paints an intricate picture of the global dairy market landscape. Whole Milk Powder (WMP) was slightly firmer, showing a promising uptick of 3.6%, with prices reaching an average of $3,694. This rise indicates a steady demand for WMP, likely influenced by growing consumption needs in crucial importing countries and potential supply constraints in major exporting regions. 

Skim Milk Powder (SMP) followed a similar trajectory, albeit with a modest increase of 1.9%, settling at an average price of $2,981. The strengthening price suggests a robust market with healthy demand and tight supply conditions. Such trends often mirror macroeconomic factors like currency fluctuations, trade policies, and seasonal production changes in leading SMP-producing nations. 

Anhydrous Milk Fat (AMF) saw a 2.7% increase, reaching an average price of $7,078. The surge in AMF prices could be attributed to its diverse applications in food industries, such as in the production of confectionery, bakery, and dairy products, and increasing preference over traditional fats due to its longer shelf life and stability. This reflects a broader shift toward premium dairy derivatives. This trend underscores the global food market’s growing appetite for high-value dairy ingredients. 

Butter futures increased by 2.1% to an average price of $6,633. Although a modest rise, it highlights the ongoing anticipation of holiday season demand and the dynamics of stockpiling versus actual consumer consumption. This increase in butter prices might relate to the overall tightness in dairy fats amid rising production costs and supply chain challenges. 

These SGX futures trends collectively illuminate the interplay between supply constraints, demand fluctuations, and global economic conditions. They reflect broader market dynamics characterized by a struggle to balance between burgeoning consumer demand and the ability of producers to meet this demand efficiently. This struggle can lead to potential challenges such as supply shortages and increased production costs, but it also presents opportunities for producers to innovate and meet the changing consumer demands.

Tracing the Tides: European Dairy Market’s Dance with Dynamic Forces

Examining the latest shifts in European dairy product quotations reveals a market in flux, grappling with macroeconomic and industry-specific influences. The European Quotations for the week ending October 30, 2024, highlight various movements across essential dairy products such as butter, SMP (Skim Milk Powder), whey, and WMP (Whole Milk Powder). 

Butter prices saw a modest decline overall, with indices dropping across various European markets—€26 for the general index and, more significantly, a €75 decrease for German butter. In contrast, the Dutch butter market showed remarkable resilience with a €20 rebound, indicating varying demand dynamics across Europe and the potential for stability in certain regions. 

SMP displayed a mixed performance, indicating a market under pressure. With the general index slightly down by €2, noticeable regional variations were present; German SMP prices fell €25, while French SMP saw a slight increase of €20. These shifts suggest localized demand fluctuations and competitive pricing influencing market outcomes. 

Meanwhile, the whey market experienced a palpable downward trend, with a €10 decline on the index. Dutch and French whey products faced drops, reinforcing the narrative of diminishing demand or potential overproduction in these segments. 

Contrary to these trends, the WMP index bucked the overall downtrend, climbing by €5. The variations in WMP quotations, with French WMP rising by €50 in contrast to a €35 decline in German prices, underscore the complexity behind these movements, possibly driven by supply chain adjustments or export demand influences. The European dairy market’s recent pricing volatility aligns with broader economic uncertainties and specific supply and demand considerations. The disparate movements among dairy products highlight the sector’s sensitivity to global market influences and the ever-present impact of regional trade flows, seasonal production trends, and consumer demand shifts. As these dynamics play out, industry stakeholders must navigate a challenging landscape with potential opportunities contingent on evolving market conditions.

Navigating the Cheese Market: Challenges and Opportunities in a Dynamic Landscape

The European cheese indices display a downward trajectory, signaling potential challenges for cheese producers and exporters. However, this also presents opportunities for strategic planning and market positioning. Cheddar Curd, Mild Cheddar, Young Gouda, and Mozzarella all experienced price declines over the past week. Cheddar Curd dropped by €56, marking a 1.1% decrease. Yet, it remains significantly above last year’s levels, highlighting a mixed sentiment in the market. 

Mild Cheddar followed a similar pattern, with a €47 decrease (0.9% drop), boasting a 35.3% increase year-over-year. Young Gouda and Mozzarella fell by €60 and €54, respectively, with Gouda down by 1.3% and Mozzarella by the same percentage. Still, both maintain a price above year-ago comparisons, indicating resilient underlying demand. 

For cheese producers, these trends imply a period of adjustment, as declining prices may pressure profit margins. Exporters might view these indices as a mixed blessing. At the same time, current price drops suggest competitive challenges. However, higher year-over-year prices could still offer favorable trading conditions, particularly in markets with robust demand. 

Ultimately, staying vigilant about production costs and exploring diversified markets could help cheese producers navigate this complex landscape. Additionally, leveraging existing price advantages in year-over-year figures may aid exporters in maintaining competitive edges amid fluctuating dynamics.

GDT Auction Signals: Subtle Shifts Point to Strategic Gains in Global Dairy Markets

Recent Global Dairy Trade (GDT) auction results reflect a cautiously optimistic outlook for the global dairy landscape. Whole Milk Powder (WMP) emerged with a subtle yet significant price adjustment, logging an increase of $75 (+2.1%) from the previous pulse auction, landing at an average winning price of $3,610. This uptick from the prior GDT mark also suggests an upward trajectory of $110 (+3.1%), aligning well with market expectations and indicating a steady demand. 

Skim Milk Powder (SMP) followed a similarly positive trend, with its average winning price rising by $55 (+2.0%) from the last pulse auction, climbing to $2,860. Compared to the GDT C2 price weeks earlier, this reflects an affirmative vector by $110 (+4.0%). Such movements in SMP indicate an adjusted market sentiment, likely driven by shifts in export demand targeting specific markets influenced by varying geopolitical and economic conditions across the globe. 

From a broader perspective, these price evolutions in the GDT auction serve as critical indicators of the global dairy trade’s health. The steady increase in WMP and SMP can be viewed as a response to shifting consumer preferences, supply constraints, or possibly accelerated purchasing due to forecasted shortages in certain regions. These upward trends could incentivize increased production, mainly pivoting toward markets with latent demand potential amidst fluctuating supply dynamics. 

However, stakeholders within the dairy industry must monitor these market movements closely, as they could herald a stabilization period or foreshadow more dynamic shifts ahead. While reflective of current market conditions, such auction results provide strategic insights that could influence future trade strategies, pricing mechanisms, and supply chain calibrations across the global dairy sector.

Fonterra’s Surge: Can Robust Milk Collections in NZ and Australia Tilt the Global Dairy Balance?

Fonterra’s recent data on milk collections paints a picture of robust growth. In New Zealand, milk collections for September reached 174.2 million kgMS, marking a substantial increase of 4.9% year over year. Northern Island (NI) contributed 104.6 million kgMS, up 4.8% yearly. In comparison, Southern Island (SI) added 69.6 million kgMS, posting a 5.0% increase year over year. Season-to-date collections in New Zealand totaled 307.2 million kgMS, a solid 6.1% rise compared to the previous year. 

Across the Tasman Sea in Australia, Fonterra’s collections also reflected positive growth. Reports indicate 10.2 million kgMS collected, a 4.7% increase yearly. Season-to-date Aussie collections exceeded their last season by 2.6%. 

The upward trajectory in Fonterra’s milk collections in both regions suggests a potential boost to the global milk supply. As Fonterra is a significant player in the international dairy market, this increased output could help stabilize global milk prices, especially if other regions struggle to keep up with demand. However, the market could see varying impacts depending on how these increased supplies align with global demand trends and potential production slowdowns in other vital regions due to climate impacts or herd health challenges. A more robust supply from New Zealand and Australia might exert downward pressure on prices, but only if global demand does not escalate proportionately.

Nuanced Performances: Italy’s Quality Focus and China’s Competitive Pricing Reshape Global Dairy Dynamics

Italian and Chinese dairy sectors continue to showcase nuanced performance amidst evolving global market dynamics. Italy’s milk production in September stood at 975kt, signaling a slight decline of 0.6% year-over-year, following a similar downtrend in August. Despite this dip, cumulative collections for the year’s first nine months climbed by 1.2%, indicating resilience and adaptability within the Italian dairy landscape. Additionally, improvements in milkfat and protein levels point towards a focus on quality enhancement, thereby potentially fetching premium market pricing. 

Conversely, China’s October farmgate milk price averaged 3.13 Yuan/Kg, stabilizing over three weeks but marking a significant 15.9% decline year-over-year. This trend underscores mounting pressures within the Chinese dairy sector, potentially due to economic challenges and fluctuating domestic demand. However, this price correction could render Chinese dairy competitive globally, opening avenues for export. 

These developments mirror broader global dairy challenges and opportunities. Italy’s focus on quality amid fluctuating output and China’s competitive pricing highlights the push-pull dynamics affecting international markets. The global dairy market now faces the dual pressures of maintaining quality and competitive pricing, which are essential for sustaining profitability amid varying regional milk production patterns.

Riding the Waves: U.S. Dairy’s Tango with Cheese and Butter Innovations

The U.S. dairy market dances to the changing cheese and butter dynamics. Last week’s Cold Storage report unveiled a significant reduction in cheese stocks from March to September, hinting at a robust demand driven by noteworthy exports. However, the Milk Production report signals a stabilization in U.S. milk output, causing the market to brace for an uptick in cheese production, especially with new plants coming online. Should demand cool off, stockpiles could swell, nudging prices downward and unsettling market participants. 

Cheddar blocks have already felt the squeeze, sliding to $1.8375 per pound—the lowest since May—while barrels slipped slightly to $1.8675. Butter, too, retreated slightly as storage levels burgeon, preparing for the holiday season. Despite the flurry, when prices dip, buyers quickly stockpile, evidenced by the record-setting trades recently. 

Cream, cascading from elevated butterfat levels, saturates the market, pushing cream multiples below seasonal norms—a siren song for opportunistic buyers like butter churns. Consequently, butter production is at a historic high, up 5.3% year-over-year for January through August, with the potential to rise further as lower cream multiples incentivize production. 

For U.S. dairy producers, these dynamics present a mixed bag. While current cheese and butter demand pushes market activity, a potential shift or decline could bring lower prices as supply exceeds demand. The bird flu’s impact on California’s dairy herds also looms, potentially further tightening the milk supply. Strategic planning and adaptability will prove crucial for sustaining profitability and navigating the nuanced market landscape amid these challenges and opportunities.

Reviving the Flow: Global Milk Production Sees Glimmers of Recovery Amid Regional Hurdles

Global milk production is recovering amid shifting dynamics, with the top five dairy exporters showcasing mixed performances. This resurgence is primarily anchored in regions like Australia, New Zealand, and the United States, which posted year-over-year gains compensating for downturns in Argentina and Europe. Notably, August ended a 12-month streak of declining outputs, slightly outpacing August 2023 by 0.2%. However, this figure remains below the production levels of 2021 and 2022, underscoring a deep downturn experienced in late 2023. 

Regional challenges remain prominent, with European and U.S. producers facing constraints due to disease pressures and a shortage of breeding heifers. In contrast, despite battling avian influenza concerns in California, the U.S. contributed positively compared to year-earlier figures. This backdrop sets a cautious tone as producers in both regions navigate these hurdles, potentially capping the pace of production increase. 

These trends expose vulnerabilities in sustaining continued price hikes for dairy products globally. While current pricing levels encourage more production, these persistent barriers likely tempered the extent of expansion. As China’s import activity remains tepid, competition stakes for exports are heightened, signaling a potential standoff in increasing prices. 

The interplay between production recovery and regional constraints paints a nuanced picture. Stakeholders must monitor these developments closely, as they will play a pivotal role in shaping the trajectory of global dairy prices. Market participants should brace for a landscape where growth spurts could be short-lived, especially if supply surges fail to align with global demand, leading to price adjustments that reflect these underlying regional disparities and challenges.

The Bottom Line

As we unravel this week’s global dairy market report, a nuanced picture emerges of a sector both adapting and challenged by an intricate weave of factors. Rising futures, particularly in butter, contrast with the mixed signals from SMP and whey, suggesting a potential realignment in demand and pricing dynamics. The European market hints at shifting consumer preferences and regional economic factors with its price adjustments. 

Fonterra’s strong milk collection figures portray a robust sentiment in the Oceania region, which may influence global supply chains. Meanwhile, Italy’s focus on quality and China’s competitive pricing strategies underscore the diversity in global dairy strategies and market responses. 

In the U.S., despite challenges like bird flu impacting certain regions, the market for cheese and butter shows resilience, suggesting a possible pivot towards innovative solutions and product diversification. 

The overall production recovery in major dairy-exporting nations hints at a stabilization. Still, it leaves us pondering: How will these dynamics evolve amidst environmental pressures and global economic shifts? Will producers pivot to sustainability and technology-driven solutions to gain a competitive edge? And crucially, what strategic shifts should industry leaders embrace to harness growth opportunities while navigating the turbulent tides of global market demands? 

These questions will undoubtedly shape the future landscape of the dairy market, encouraging stakeholders to remain vigilant and strategically agile.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

The Rise and Fall of Dairy: What Shifting U.S. Consumption Trends Mean for Butter, Cheese, and More

Explore U.S. dairy consumption trends. Uncover how butter, cheese, and milk shifts affect prices and the dairy sector. Learn more.

Summary: 

As U.S. dairy product consumption patterns evolve, distinct changes emerge in critical categories like butter, cheese, nonfat dry milk (NDM), and dry whey. Butter enjoys renewed popularity due to changing health narratives, driving up demand. In contrast, cheese consumption remains stagnant, possibly influenced by economic uncertainties or health trends. NDM’s heavy reliance on exports underscores vulnerability amid declining global demand. Conversely, dry whey’s domestic demand surges as its reputation as a protein source gains traction, illustrating the complexity of the dairy landscape. These shifts reflect broader dietary preferences and international trade dynamics, highlighting both opportunities and challenges for the industry.

Key Takeaways:

  • Butter consumption rebounded significantly in 2023 due to changing medical opinions on its health benefits.
  • Cheese demand has been slow, with American cheese withdrawal growth turning negative despite a recovery post-COVID restaurant sector.
  • The production dynamics of Cheddar cheese, a major milk protein price influencer, are influencing the decline in 2024.
  • Nonfat dry milk struggles with declining domestic and export growth, putting downward pressure on its pricing.
  • Dry whey domestic consumption is on the rise, driven partly by its nutritional reputation, although exports have declined.
  • The U.S. is grappling with finding a profitable market for NDM and dry whey, crucial byproducts in the dairy sector.
  • The U.S. per capita cheese intake remains below many European countries, suggesting potential growth opportunities.
dairy industry trends, butter demand increase, cheese consumption decline, nonfat dry milk challenges, dry whey health benefits, saturated fats research, COVID-19 impact on dairy, economic uncertainty dairy market, dairy exports decline, protein-rich dairy products

The American dairy industry stands at a curious crossroads—one foot planted firmly in its storied past while the other steps uncertainly into an evolving future. Despite the challenges, the industry’s resilience is evident as it navigates through changing consumer preferences. Dairy has long been a staple of American diets, celebrated for its nourishing properties and culinary versatility. Yet, surprisingly, current consumption patterns paint a picture of contrast within the sector, raising the question of why some dairy products like butter and dry whey thrive while others such as cheese and nonfat dry milk (NDM) face decline. This article delves into this paradox, exploring the seemingly contradictory trajectories of butter, cheese, NDM, and dry whey. It’s a complex tale of consumer demand, health trends, and market dynamics that challenge traditional perceptions and call for an industry reassessment.

Butter: A Comeback Story 

Butter is making a notable comeback in Americans’ dietary habits. After a steady decline from 2019 to early 2023, the tide began to turn in favor of butter consumption. This reversal, observed as early as 2023, can be attributed mainly to evolving medical opinions on saturated fats. 

Historically, butter fell out of favor due to its high saturated fat content, which was long believed to impact heart health negatively. However, recent medical research and revised dietary guidelines have started recognizing the health benefits of moderate saturated fat consumption, including those found in butter. This shift resonates with consumers, leading them to reintroduce butter into their daily meals, as evidenced by increased butter withdrawals from wholesale inventories. 

Table I Annual Growth Percent of Butter Domestic Disappearance

YearAnnual Growth Percent
20172.5%
20181.8%
20190.5%
2020-1.2%
2021-3.0%
2022-4.1%
20233.9%
20245.2%

The implications of this behavior change are significant. Table I underscores a dramatic surge in butter withdrawals beginning in 2023, indicating heightened demand. As more consumers embrace butter, supply chains face increased pressure, ultimately driving prices upward. Consequently, dairy producers navigate a challenging landscape where demand outpaces current supply capabilities, leading to an inflationary effect on the cost of butter. 

In summary, the revitalized interest in butter, fueled by changing health perceptions, showcases a market ready for adaptation. The upward trajectory in butter consumption signals a new era where the nostalgia of traditional eating meets contemporary health awareness. This potential for growth in the dairy industry should inspire optimism for the future. 

Cheese: A Tale of Two Trends

Table II Annual Growth Percent of Total Cheese Domestic Disappearance

YearAnnual Growth Percent of Total Cheese Domestic Disappearance
20172.1%
20181.8%
20191.5%
20200.0%
20210.2%
20220.4%
2023-0.3%
20240.1%

The tale of cheese consumption in the U.S. tells a story of bifurcated trends that demand astute analysis. Through observed fluctuations in Table II, we gather a picture that reflects the broader socio-economic shifts that impacted dietary patterns during the tumultuous COVID-19 pandemic. The mandated lockdowns and restrictions altered the landscape for dining habits, eerily flattening cheese consumption. As communal dining spaces shuttered, domestic and commercial demand for cheese plateaued. This illustrates a rare instance where consumption demand did not grow despite the perennial love for this versatile food. 

However, the story didn’t end there. Gradually, as the nation emerged from pandemic protocols, a slow resurgence in cheese consumption appeared on the horizon. Despite this, the hoped-for rebound lacked the robust momentum seen in other dairy segments, reflected in the tempered growth rates. This stagnation could not simply be attributed to a lack of consumer interest; instead, it suggested deeper undercurrents—perhaps economic uncertainty or shifting health trends playing a role. 

Table III Annual Growth Percent of American Cheese Domestic Disappearance

YearAnnual Growth Percent
20171.5%
20182.0%
20191.8%
2020-0.5%
20211.2%
20220.8%
2023-0.2%
2024-1.0%

Conversely, Table III offers a more nuanced narrative when it narrows down to American cheese, with Cheddar—integral to pricing models—taking center stage. Here, we witness declining withdrawal rates, painting a stark picture of diminishing demand. As Cheddar cheese production decreased in 2024, the repercussions extended to pricing dynamics, signaling the opportunity for dairy producers to reassess their portfolio strategies. Less pressure on American cheese, particularly Cheddar, invariably led to softer pricing. Yet, it poses the question—what might revitalize this once stalwart segment? 

While the cheese market is navigating through challenging times, the two trends suggest that understanding consumer behavior after global disruptions could be vital to unlocking new growth trajectories. Will American cheese make a comeback, akin to butter, or will it continue to tread water amidst evolving consumer preferences? The potential for a comeback is there, and it’s up to the industry to seize it.

NDM: A Linchpin in the Dairy Dilemma 

Table IV Annual Growth Percent of NDM and SMP Domestic Disappearance

YearAnnual Growth Percent (%)
20171.5%
20182.3%
20193.0%
20201.8%
20210.5%
2022-1.2%
2023-2.5%
2024-3.1%

Nonfat dry milk (NDM) is pivotal in the dairy market, serving as a crucial ingredient in domestic consumption and a significant export commodity. As detailed, the role of NDM extends beyond its primary function in the domestic culinary sphere, where it is prominently utilized in baked goods. Its expansive reach into international markets underscores its essential nature in global dairy trade dynamics. 

Table IV Annual Export Growth of NDM and SMP

YearAnnual Export Growth of NDM and SMP (%)
20172.8%
20185.6%
2019-1.2%
20204.1%
2021-3.5%
20221.9%
2023-0.8%
2024-2.4%

However, as reflected in Tables IV and V, there has been a marked decline in domestic disappearance and export growth of NDM and skimmed milk powder (SMP). This downturn poses a formidable challenge for the dairy industry, as the oversupply of NDM on the market precipitates a cascade of economic impacts. 

Reduced pressure on NDM supply inevitably decreases prices, directly influencing Class I and IV milk pricing structures. Class I milk, primarily used for drinking, and Class IV milk, integral to the production of butter and nonfat dry milk, both see their profitability affected by these fluctuations in NDM market dynamics. Consequently, the industry faces a complicated economic landscape where ensuring profitability becomes increasingly challenging amidst dwindling NDM demand globally. 

This situation encapsulates the interconnected nature of dairy products, where a decline in one sector, such as NDM, echoes across the broader market, affecting a myriad of components, including the pricing strategies of milk classes.

Dry Whey: Riding the Wave of Protein Popularity

Table VI Annual Growth Percent of Dry Whey Domestic Disappearance

YearAnnual Growth %
20173.2%
20185.4%
20194.1%
20206.7%
20218.0%
20227.5%
202310.3%
202412.0%

The substantial increase in domestic consumption of dry whey, as demonstrated in Table VI, marks a significant trend within the U.S. dairy industry. This rise contrasts sharply with the decline in exports depicted in Table VII. The surge in internal demand can be attributed partly to the growing awareness of dry whey’s health benefits, particularly its high protein content. As more consumers incorporate it into their diets, the demand pressure increases domestically, reducing the quantity available for international markets.

Table VII Annual Export Growth of Dry Whey

YearAnnual Export Growth (%)
20172.5%
20184.3%
2019-1.8%
20200.5%
20213.7%
2022-2.4%
20235.6%
2024-0.9%

 This shift in demand dynamics has profound implications on supply and pricing. As domestic consumption climbs, the supply specifically reserved for export diminishes, potentially leading to heightened prices within the local market due to increased demand pressure. Conversely, with fewer exports, international buyers may explore alternative sources or substitutes, thus affecting U.S. market competitiveness overseas. 

For the broader dairy market, the trend signals a transformation in consumption patterns, possibly prompting producers to reassess their production strategies and focus more on meeting domestic needs. As the market evolves, dairy farmers and businesses must consider these shifts, analyze how the decrease in export growth could impact long-term profitability, and adjust production and marketing strategies accordingly to optimize returns.

The Bottom Line

The landscape of dairy consumption in the U.S. paints a multifaceted picture, accentuated by the varying trends across different products. Butter, once vilified, is witnessing a resurgence, likely driven by shifting perceptions in health research. This rekindled demand underscores the impact of changing public opinion on market dynamics. Conversely, despite its integral role in American cuisine, cheese is experiencing stagnation, raising questions about its declining growth compared to its global counterparts. 

Nonfat dry milk, a pivotal player tied to multiple dairy categories, faces challenges primarily in export, affecting its domestic viability. Meanwhile, the rising appreciation for dry whey as a protein-rich option showcases an optimistic trend. However, it hints at a delicate balance between domestic consumption and export potential. 

These complexities suggest that simply forecasting based on past consumption will no longer suffice in anticipating future markets. Dairy professionals and stakeholders must remain vigilant, adapting quickly to consumer preferences and production economics shifts. As we navigate this evolving landscape, a critical query emerges: how will the U.S. dairy industry innovate to ensure sustainability and growth amidst these dynamic trends?

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

How Russia’s Inflation Crisis Pivots to Turkish Butter Amidst War Economy Woes

Can Turkish butter soothe Russia’s economic woes as inflation reshapes dairy imports and spikes prices?

Summary:

As Russia grapples with economic pressures from its ongoing war and international sanctions, it faces a new challenge: sourcing butter. The recent decision to import Turkish butter underscores a larger struggle within Putin’s administration to balance military expenditures with consumer needs, known as “guns-and-butter” economics. With traditional suppliers like New Zealand retracting, Russia’s turn towards Turkish dairy farmers serves as a short-term fix while highlighting vulnerabilities in supply chains. Inflation has pushed butter prices up 26% since December, reshaping daily life as the Ruble’s purchasing power dwindles. This shift reveals the strain of maintaining affordable goods amid disrupted supply chains and resource reallocation toward military expenditure.

Key Takeaways:

  • Russia’s economy faces inflationary pressures, affecting staple commodities like butter.
  • Increasing butter prices prompt Russia to import Turkish butter despite political tensions.
  • One-quarter of Russia’s butter is sourced from international suppliers, and it is now facing logistical barriers.
  • The reallocation of dairy cream for cheese and ice cream production exacerbates the butter shortage.
  • Instances of butter theft reported in Russia due to escalating consumer costs.
  • Russia’s strategic pivot to Turkish butter supplies highlights the impact of geopolitical shifts on domestic markets.
Russia economy, military expenditures, breakfast spread, Turkey arms Ukraine, Russian pastries, inflation crisis, butter price increase, Ruble purchasing power, international sanctions, consumer goods affordability

In a world where bullets and butter seem worlds apart, Russia’s economic paradox starkly comes to life. Struggling to juggle the hefty weight of military expenditures with the simple pleasure of a breakfast spread, Russia finds itself in an improbable dance with Turkey—a nation sending arms to Ukraine on the one hand and enriching Russian pastries with its butter. This irony underlines a more profound crisis brewing within Russia’s economic cauldron, as soaring inflation and systemic disarray threaten basic consumer needs. Since December, the price of butter has skyrocketed by 26%, reshaping daily Russian life in unsettling ways. The urgency of this crisis is palpable, with consumer inflation showing no signs of relenting, distorting dairy markets and drawing an acute line between wartime ambition and the humble necessities of domestic markets. As the Ruble’s purchasing power dwindles, Russia’s pivot towards Turkish butter seems less a choice than an obligation in a market squeezed by international sanctions and internal mismanagement.

Butter or Bullets? The Fragile Balancing Act of Putin’s Economic Strategy

Russia’s economic strategy under Vladimir Putin has long revolved around the ‘guns-and-butter’ approach. This doctrine is rooted in a delicate balancing act: maintaining robust military capabilities while ensuring consumer goods are affordable for citizen welfare. It is a challenging dual mandate, especially in a nation with extensive geopolitical ambitions and diverse domestic requirements. 

However, this strategy is increasingly shaky as the global economic climate shifts. Western-led sanctions, imposed in response to geopolitical actions such as the annexation of Crimea and, more recently, the invasion of Ukraine, are exerting significant pressure on Russia’s economy. These sanctions hinder Russia’s access to international markets, restrict financial transactions, and curtail foreign investments, effectively narrowing the country’s economic leeway. 

Simultaneously, Russia grapples with surging inflation, a byproduct of international isolation and internal mismanagement. Consumer prices are spiraling upward, making it increasingly difficult for the average Russian to afford the essential goods that underpin their daily lives. This inflationary pressure is further exacerbated by disrupted supply chains and the reallocation of economic resources towards sustained military expenditure, straining the government’s ability to uphold its promise of accessible consumer goods. 

Putin’s ‘guns-and-butter’ strategy is thus facing its most severe test. The current economic environment challenges the Russian government to either recalibrate its approach or risk eroding public confidence in its capacity to deliver economic prosperity and national security. As inflation eats into consumer purchasing power and sanctions limit economic growth, the sustainability of this strategy remains in question, demanding innovative policy responses to navigate the storm.

The Delicate Dance: Balancing Defense and Domestic Needs in Russian Economics

Historically, Russia’s economic strategy has been heavily influenced by the ‘guns-and-butter’ model. This model strives to maintain an equilibrium between military expenditures and the production of consumer goods. This delicate balance is essential for ensuring the country’s security while also satisfying the needs of its civilian population. 

In theory, this model allows a nation to fortify its defense capabilities without compromising its citizens’ standard of living. However, executing such a strategy is inherently tricky, especially in conflict. During wartime, countries often find themselves forced to prioritize military spending over consumer welfare. As pressure mounts on the battlefront, governments may reallocate resources from consumer goods production to bolster their defense efforts, leading to a strain on the civilian economy. 

For Russia, this challenge is compounded by the ongoing conflict in Ukraine, which has necessitated a substantial increase in military spending. The resulting strain on consumer goods production manifests as inflation and scarcity of everyday items such as butter. This disrupts the economy and affects public morale, as citizens feel the pinch of rising prices and dwindling supplies. 

The difficulties in maintaining this balance reveal a fundamental tension within the guns-and-butter model: the simultaneous pursuit of military capability and consumer economic stability during an extended period of conflict. Such scenarios test the resilience of economies and require nimble strategies to mitigate the impacts on the populace, all while sustaining national defense objectives.

The Butter Burst: Inflation’s Squeeze on Russian Wallets

The inflation crisis in Russia has sent ripples through its economy, drastically affecting the prices of everyday commodities such as butter. This staple’s price, for instance, surged by 26% since December, a clear indicator of the broader inflationary trend hitting Russian households. According to the Russian state statistics service, this surge represents a significant rise in consumer price inflation, placing a heavy burden on the average Russian’s wallet. 

Every day, consumers are feeling the heat. Take the “Brest-Litovsk” high-grade butter in Moscow, for instance. Its price has gone up by 34% this year alone. This increase compounds Russian consumers’ struggles, already grappling with surging costs across various sectors. The implications of this are far-reaching. Shoppers like Sergei Popov, a typical Russian citizen, are finding their purchasing power increasingly strained as even the most basic grocery items like milk, cheese, and eggs become dearer. This personalization of the crisis helps the audience empathize with the average Russian’s plight. 

The economic ramifications extend beyond individual budgets, influencing broader market behaviors. Russian authorities recently convened with dairy producers to monitor butter production to curb this trend. However, the underlying issues—rerouted supply chains and an overheated economy—persist, driving butter and many commodity prices up, straining an already pressured market.

Turkish Delight: A New Dairy Savior for Russia’s Economic Woes

In this maelstrom of economic challenges, Turkish butter is emerging as an unexpected protagonist in Russia’s strained landscape. With the scarcity of traditional suppliers—New Zealand and Latin America retreating from the Russian market due to geopolitical sanctions—Turkey has stepped in, aiming to satiate Russia’s insatiable hunger for butter. Russia’s economic plight has transformed Turkey from a mere culinary neighbor to a critical ally, with its dairy industry ready to capitalize on the opportunity. 

The inaugural delivery of 20 tons of Turkish butter marks the beginning of a potential trend introduced to alleviate the skyrocketing prices unsettling Russian households. Turkey’s strategic geography and robust dairy network in provinces like Marmara and Aegean make it a prime candidate to replace former suppliers. While Russia grapples with overheating markets and consumer discontent, Turkey’s timely intervention could offer a balm, cushioning the blow of absent Western butter brands and ensuring that Russian tables—at least where dairy is concerned—do not stay barren for long. This emphasis on potential solutions can invoke a sense of hope in the audience.

The Ripple Effect: Russia’s Dairy Demand Revitalizes Turkish Industry 

The growing demand from Russia has certainly made waves in the Turkish dairy industry. Turkish dairy farmers and industry experts highlight a notable shift in operations and economic returns. Orhan Yildiz, a dairy farmer from the Marmara region, explains, “We’ve had to increase our production capacity by 20% to meet the new export demands. Initially, it was challenging, but the economic benefits are undeniable.” 

The intensified production, however, has come with its challenges. An industry expert, Ahmet Cetin, says, “Logistics have become crucial. We must ensure a consistent supply to Russia, which requires coordination across multiple channels. This push towards efficiency is something we’re embracing for long-term gain.” Data supports this, showing a 15% export boost within the first quarter of 2024. 

Economically, this relationship appears beneficial. The influx of Russian demand has not only provided Turkish dairy farmers with a significant income boost. Still, it has also strengthened the trade ties between the two nations, albeit amidst a complex geopolitical backdrop. As engagements deepen, industry stakeholders remain optimistic yet cautious, observing the developments closely.

From Cart to Crisis: Butter as a Luxury in Moscow’s Supermarkets

In Moscow’s supermarket aisles, ordinary citizens like Sergei Popov see the repercussions of Russia’s economic policies etched on their faces. For Sergei, a simple breakfast staple like butter has become a symbol of financial strain. “Every morning, starting the day with butter is a routine,” he laments, “but now, it seems like a luxury.” 

As the price of butter creeps steadily upward, households feel the squeeze. The cost has surged by 26% since December, leaving many to make difficult choices about their grocery lists. Sergei’s shopping habits have shifted—his cart is lighter, yet his wallet is equally so. “We buy the basics: milk, cheese, sausages. But where has the 1,500 rubles gone? It’s disappearing faster with each trip,” he says, frustration underlying his words. 

These rising prices are prompting changes in consumer behavior. Families reevaluate their purchases, prioritize necessities, and sometimes substitute margarine for the once-sacred butter on their tables. As another shopper shifts through the dairy section, she quietly notes, “Butter thefts have become a strange reality. The shoplifters are desperate, just like any of us.” 

This economic turmoil reaches beyond mere statistics, becoming a palpable hardship and altering everyday routines. As a result, once confident in their purchasing power, the Russian middle class navigates a new landscape of scarcity, further exacerbated by international tensions and sanctions. The rising costs aren’t just economic—they’re personal, reshaping lifestyles and expectations in unprecedented ways.

Butter Battle: Russia’s Strategic Manoeuvres to Tame a Spreading Crisis

Russian government officials have engaged in strategic discussions with local dairy producers in response to the escalating butter crisis. An agreement has been struck focused on stringent tracking of butter production to curtail skyrocketing prices. This collaborative effort aims to stabilize unstable market conditions. The critical strategy revolves around enhancing domestic production efficiency while simultaneously exploring international alternatives for imports, as evidenced by the recent surge in Turkish butter imports. Additionally, measures are being implemented to monitor retail practices closely to prevent profiteering and ensure consumer prices do not spiral further out of control. These steps represent a concerted effort by government and industry stakeholders to mitigate the impact of inflation on Russian households’ purchasing power, explicitly targeting the essential commodity of butter.

Geopolitical Churn: The Strategic Unraveling of Russia’s Butter Supply Chain

The ripple effects of Russia’s geopolitical decisions have created a complex web of challenges in its butter import landscape. The imposition of international sanctions since the 2022 invasion of Ukraine has dramatically reshaped Russia’s trading relationships, leaving formidable gaps in its supply chain. Traditional trade partners like New Zealand and Latin American countries have halted butter exports to Russia, illustrating a global stance against its actions through trade restrictions and logistical barriers. 

In response, Russia pivoted to alternative suppliers. Belarus, Iran, and India quickly seized the opportunity, recognizing the economic potential and the geopolitical significance of maintaining trade ties with a global power like Russia. These nations have become unexpected lifelines, navigating various logistical and payment obstacles imposed by the sanctions. 

Despite this, their role as critical suppliers is challenging. Maintaining steady butter supplies demands adjustments in production capacity and distribution networks, which still adapt to Russia’s specific needs. Additionally, these countries must balance trade benefits with Russia against potential diplomatic backlash from the broader international community. 

Turkey’s emergence as a new supplier showcases the dynamic shifts in global trade as nations recalibrate their economic strategies amidst fluctuating geopolitical landscapes. As these nations grapple with the challenges of fulfilling Russia’s butter needs, they also underscore the strategic interplay between politics and trade in today’s interconnected world.

The Bottom Line

As we survey Russia’s current predicament, the intricate dance between guns and butter reveals significant strains. Inflation soars, household budgets stretch thin, and reliance on imports, such as Turkish butter, highlights Russia’s economic fortification vulnerability. The ongoing shift in supply chains, exacerbated by geopolitical tensions, requires expansive strategic realignment from Russian officials seeking to stabilize domestic markets. 

This economic balancing act raises urgent questions: Can Russia sustain its war economy without further disrupting its citizens’ daily lives? And what repercussions will this turmoil hold for the global dairy market, now intertwined with Russia’s geopolitical strategies? As butter becomes emblematic of Russia’s broader economic challenges, the world watches to determine whether emerging markets will fill the void left by Western sanctions, reshaping trade routes and the fabric of global commodity supply.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 
NewsSubscribe
First
Last
Consent

Canadian Dairy Commission Cuts Milk and Butter Prices for 2025

Are you prepared for the 2025 milk and butter price cuts by the Canadian Dairy Commission? Discover what these changes mean for your farm.

Summary:

The Canadian Dairy Commission’s decision to reduce farmgate milk and butter prices for 2025 signifies a strategic attempt to synchronize production costs with consumer affordability. Although the Farmgate milk price adjustment represents a minor dip, less than a cent per liter, it emerges from comprehensive stakeholder consultations and the National Pricing Formula’s meticulous analysis, reflecting the intricate balance between production expenses and inflationary pressures. Despite expectations that these adjustments could lower milk component costs destined for products like yogurt and cheese, retail price outcomes remain unpredictable due to labor and transportation costs. Interestingly, the slight reduction in butter’s support price mirrors enhanced operational efficiencies to stabilize the market under the Domestic Seasonality Program. As these changes await provincial approval, the potential ripple effects on dairy farmers‘ profitability and overall market conditions unfold gradually, with an eye on the scheduled implementation date of February 1, 2025.

Key Takeaways:

  • The Canadian Dairy Commission (CDC) is slightly adjusting the farmgate milk and butter support prices for 2025, reflecting reduced production costs and increased farm efficiency.
  • While the farmgate milk price sees a modest reduction, its impact on retail prices for dairy products like yogurt and cheese remains undetermined due to other supply chain factors.
  • Changes in the butter support price align with decreased milk component prices, aiming to stabilize supply and demand within the domestic market.
  • Various market factors beyond farmgate adjustments, including labor and transport costs, influence retail prices.
  • The pricing revisions are pending provincial approval, with execution expected in early 2025, highlighting the importance of stakeholder involvement in the process.

The Canadian Dairy Commission has announced a price reduction for milk and butter that will take effect in 2025. This significant decision challenges us to evaluate the role of these critical products in shaping our agricultural landscape. Despite 2024’s elevated inflation, the CDC underscores a noteworthy balance between consumer demand, farmer stability, and market conditions. Is this a simple adjustment, or does it have the potential to transform the financial framework of our dairy industry?

YearFarmgate Milk Price ($/liter)Milk Price Adjustment (%)Butter Support Price ($/kg)Butter Price Adjustment (%)
20231.00+1.5%10.35+2.0%
20241.01+1.0%10.40+1.5%
2025 (Projected)0.99-0.0237%10.35-0.0147%

Exploring the Ripple Effects of Farmgate Adjustments: A Synchronized Dance Between Costs and Consumer Demand

Understanding the Canadian Dairy Commission announcement requires examining the Farmgate milk price adjustment mechanics. Although the exact reduction of 0.0237% may seem minor, it plays a significant role in realigning the costs at the production level. 

The pivotal instrument in this adjustment is the National Pricing Formula. This formula is meticulously designed to account for various economic factors, allowing it to act as a balancing scale for production costs and the consumer price index. By incorporating these elements, the formula ensures that the price set reflects not only what it costs to produce milk but also what it costs for households to sustain their dairy consumption. This perspective is crucial in maintaining an equilibrium between farmers’ profitability and consumer affordability. 

A closer look at farm economics reveals the impact of diminished feed costs and heightened productivity as critical components of this pricing decision. Feed costs represent a substantial portion of dairy farmers’ expenses, and any reduction, no matter how slight, can considerably alleviate financial pressures. Farm productivity advancements—including improved farming practices or technological integrations—also contribute to higher milk yields without proportional cost increases. This interplay of reduced expenditures and enhanced output underscores the strategic thinking and careful planning behind the Commission’s decision, providing reassurance about the industry’s future.

Ultimately, these subtle yet impactful adjustments underscore the ongoing dialogue between economics, efficiency, and sustainability within the dairy industry. This conversation, which continues to play out in boardrooms and barnyards alike, is one in which all industry stakeholders are actively engaged and part of the conversation.

Decoding the Dairy Price Puzzle: Will Farmgate Reductions Translate to Consumer Savings?

The Canadian Dairy Commission’s announcement to decrease farmgate milk prices may suggest a broad wave of relief for consumers hoping for reduced costs in dairy products such as yogurt and cheese. This potential relief offers a hopeful outlook for the future, yet the impact on retail prices is complex. 

Consider labor and transportation costs, two chief components that constitute a significant portion of the retail price. As these remain volatile and often show upward trends due to economic conditions, they might absorb much of the price decrease from the farmgate level, effectively neutralizing consumer benefits. Retailers may maintain current price levels, opting to enhance their profit margins instead. 

Moreover, supply chain dynamics and unexpected shifts in consumer demand can further influence pricing strategies. Retailers may adjust their pricing models differently based on regional market conditions, competitive pressures, and overall demand elasticity. These interconnected variables hampered complete transparency in how these reductions affect the end consumer, leaving the retail price impact as a moving target. 

Therefore, while a decrease in the cost of milk at the source might initially suggest forthcoming savings, the complexities inherent in retail pricing structures present significant challenges in forecasting exact outcomes for consumers. It leaves industry watchmen and consumers alike in anticipation, scheming through economic indicators for more evident signs of relief.

The Subtle Art of Dairy Price Choreography: Butter Supply Management to Balance the Scales

The forthcoming alteration to the butter support price, slated for early 2025, denotes a slight dip from $10.3505 to $10.3489 per kilogram. This adjustment comes amidst an environment where lower milk component prices have permitted the Canadian Dairy Commission (CDC) to execute this change. These component prices are crucial as they directly influence the cost structures associated with dairy production, fostering a climate where such price adjustments become feasible. 

The CDC’s Domestic Seasonality Program is vital in stabilizing the dairy market. This program effectively manages the ebb and flow of butter supply and demand nationwide. During periods of surplus, typically in the spring, the CDC strategically purchases butter to thread the line between overstock and necessity. Conversely, when demand spikes, especially in seasons of high consumption, such as during holidays, the CDC releases this stored butter, ensuring consistency in supply and retail pricing. 

This carefully orchestrated strategy supports the market price of butter and provides a bulwark against potential shortages. By aligning the release or purchase of butter with market cycles, the CDC mitigates drastic fluctuations that could disrupt industry stability. The reduction in milk component prices has enabled such adaptability, making this price change not merely a financial maneuver but a step towards achieving long-term equilibrium in the dairy sector.

Navigating the Labyrinth: Farmgate vs. Retail Pricing in the Canadian Dairy Sector 

The regulatory landscape of farmgate pricing in Canada presents a structured framework meticulously maintained by the Canadian Dairy Commission (CDC). This regulated pricing ensures that dairy farmers receive a fair value for their milk, helping to stabilize the industry amidst fluctuating production costs and economic variables. By employing the National Pricing Formula, the CDC adjusts prices while considering essential factors like consumer price index fluctuations and production expenses, providing a semblance of certainty to dairy operations. 

In stark contrast, retail pricing exists with significantly less regulatory oversight. Here, market forces of supply and demand prominently dictate pricing strategies, often leading to variable consumer costs that may not reflect adjustments made at the farm level. Retail prices are influenced by various factors outside dairy component costs, including labor expenses, transportation costs, and broader supply chain intricacies, making direct correlations to farmgate price reductions complex. 

The credit belongs to dedicated industry stakeholders actively engaging in the pricing review process. By participating in rigorous discussions and assessments, these stakeholders contribute crucial insights that guide decision-making. Their involvement ensures that any price adjustments align with economic realities and the fair and sustainable advancement of the Canadian dairy sector overall.

Sailing Through Approval: Navigating Provincial Waters in the Wake of Dairy Price Adjustments

The journey from announcement to reality requires the Canadian Dairy Commission’s pricing adjustments to navigate the waters of provincial approval. Each province holds the authority to sanction these changes before dairy farmers can enact the new prices. While vital for creating regional alignment and support, this multi-layered approval process introduces variability in the timeline for implementation. Experts anticipate the final roll-out will occur in early 2025, aligning with the February 1st target. However, unforeseen delays in provincial endorsements could shift this schedule. 

For dairy farmers, the transition involves adapting to new price structures and reassessing operational strategies to align with adjusted expectations. A key challenge lies in managing cash flow against slight price decreases. Farmers must optimize production efficiency and cost management to maintain profitability with reduced revenue per liter. Additionally, external pressures such as fluctuations in feed prices or labor shortages may amplify the impact of these changes, demanding strategic foresight and agility from farmers. 

Considering the broader implications, stakeholders must weigh the potential for increased competitiveness and market share against the need to sustain viable incomes. As these adjustments move towards realization, the dialogue between the Canadian Dairy Commission, provincial bodies, and dairy farmers remains instrumental in smoothing the path forward. 

The Bottom Line

As the Canadian Dairy Commission implements the 2025 price adjustments, dairy farmers face a landscape of strategic recalibration. With balanced production costs leading to slightly reduced farmgate prices, potential implications for retail pricing, and a fine-tuned butter supply strategy, the industry stands at a pivotal threshold. The intricate dance between regulated farmgate adjustments and market-driven retail prices underscores a transformative phase. This shift invites stakeholders to ponder the long-term sustainability of dairy farming within an evolving economic framework. 

Will these price adjustments herald a new era of opportunity, enabling farmers to enhance productivity while aligning with market demands, or will they pose unforeseen challenges necessitating innovative adaptations? As we navigate these changes, the resilience and ingenuity of dairy professionals will shape the future of this vital industry.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Dairy Market Report: Surging Cheese Demand Amid Milk Production Fluctuations and Market Dynamics

Unpack the latest in dairy markets: How do cheese demand and milk output shifts affect your business? Get critical insights and strategies here.

Summary:

The dairy market’s recent dynamics offer food for thought with shifts in the cheese, butter, and powder sectors. The Cold Storage report reveals a drop in cheese stocks, indicating strong export demand, while stable milk production points to potential changes in cheese output. Cheddar and butter prices reflect supply-demand volatility, with an abundance of cream leading to increased butter production despite low cream multiples. Dairy powder markets remain stagnant amid limited supply and fierce export competition as global milk production recovers. In California, avian influenza challenges add complexity. Milk prices have slightly dipped, but favorable weather conditions usher in a promising season. The U.S. dairy market sees a surge in cheese demand, prompting plant expansions, but there’s caution; oversupply risks could lead to price dips. Meanwhile, strategic opportunities in the butter market arise from surplus butterfat, and dairy powder markets remain under pressure due to global competition and weak demand from key markets like China.

Key Takeaways:

  • Impressive decline in cheese stocks suggests strong U.S. cheese demand driven by exports.
  • Stabilized milk output raises questions about future cheese production amid demand fluctuations.
  • Market jittery as Cheddar and butter prices decline; potential supply growth looms if demand falters.
  • Cream oversupply leads to lower prices, encouraging butter production growth.
  • There is a stagnant dairy powder market, with low output supporting prices, but global competition remains fierce.
  • Global milk production sees recovery, although longstanding deficits highlight recent challenges.
  • Bird flu severely impacts California’s dairy farms, raising biosecurity concerns and testing industry resilience.
  • October milk prices slightly dip yet remain favorable for farmers, ensuring financial security.
  • Ideal harvest weather conditions lead to efficient crop yields, posing beneficial opportunities for dairy farmers.

With cheese demand soaring to unprecedented heights, the U.S. dairy market is excitedly buzzing. Yet, milk production tells a more reserved tale, balancing on the edge of stability. Are we on the cusp of a dairy renaissance, or is it merely a mirage? The dichotomy between surging cheese exports and stagnant milk production raises eyebrows and questions alike. Let’s dive into the dynamics and uncover what lies ahead for dairy professionals navigating this complex landscape. 

Are U.S. Cheese Stocks Vanishing, or Is Demand Skyrocketing?

One key takeaway from the recent cold storage report is the striking decline in cheese stocks from March to September. This isn’t just a statistic; it’s a narrative of growing demand, particularly for U.S. cheese. But what drives this demand? Primarily, it’s an impressive surge in exports. American cheese has been flying off the shelves and into international markets, contributing significantly to the stockpile reduction. 

The implications of this are two-fold. First, the thriving export market underscores the robust global interest in U.S. cheese. This trend can bolster domestic producers with increased revenue streams. Second, with cheese stocks depleting faster than expected, there’s an inevitable call to ramp up production. This brings the broader market dynamics into play. More and more cheese plants are expanding, and new facilities are coming online to meet this heightened demand. 

However, there’s a cautionary note to this growth tale. If cheese production outpaces demand, we could see a quick turnaround in stock levels, leading to potential market oversupply and subsequent price dips. Therefore, while the current export-driven demand is a beacon of opportunity, it also requires strategic navigation by producers to align with market needs without succumbing to the cyclical perils of oversupply.

Stable Milk Output Raises Questions on Future Cheese Production

According to the latest Milk Production report, the U.S. milk output has stabilized after fluctuating in previous months. This stabilization indicates that the milk supply remains consistent despite increasing demand, laying a foundation for potentially bolstering U.S. cheese production. This potential for growth in cheese production should instill a sense of optimism in producers and marketers. But here lies the conundrum: as new and expanded cheese production facilities begin operations, the output is poised to spiral upwards. But what happens if demand doesn’t keep pace? This potential disparity spells the risk of an oversupply. Any faltering in demand could lead to unprecedented stockpiles, effectively pressuring prices downward. 

As trade participants digest these implications, it’s crucial to ponder whether the current market dynamics will suffice to absorb increased cheese production. With such a delicate balance, the call to action for the industry is to strategically manage supply chain operations while keeping a close watch on consumer trends and export opportunities that could mitigate the fear of surplus. This emphasis on strategic management should make the audience feel empowered. The question remains: will the demand engine remain robust enough to align with the forthcoming wave of cheese output? These questions are vital for stakeholders navigating the evolving dairy landscape with agility and forward-thinking strategies.

Market Tremors: Cheddar and Butter Prices Reflect Supply-Demand Jitters

The recent decline in CME spot Cheddar blocks and barrels has been noteworthy. Blocks fell 6.25ȼ to $1.8375 per pound, marking the lowest point since May, while barrels saw a slight dip, slipping a quarter-cent to $1.8675. The driving factor behind this reduction seems to be the looming uncertainty over cheese demand, coupled with stabilized milk production, which suggests that cheese production could rise if demand doesn’t keep pace. This potential surge in supply appears to have unnerved the markets, which quickly reacted to shifts in the supply-demand balance. 

Simultaneously, butter prices experienced a pullback, with CME spot butter dropping 2.5ȼ to $2.67. After prolonged concerns over supply, there’s confidence that current stocks are sufficient for the upcoming holiday season. The market’s behavior indicates a tendency to lock in supplies when prices fall to attractive levels, as evidenced by the substantial trades witnessed in mid-October. Yet, this week, trading volumes were meager, with only nine loads moving, suggesting specific stability or caution among buyers, possibly waiting for more favorable buying opportunities.

The Butter Market: A Surplus Story Unfolds Amidst Cream Abundance

The butter market is navigating an intriguing landscape characterized by a surplus in butterfat production and ample cream availability. The surge in butterfat, up 1.9% year over year, has been pivotal in reshaping market dynamics. High butterfat levels translate into more cream, giving rise to strategic purchasing opportunities. These opportunities, particularly for those invested in butter production and related products, are crucial in leveraging the lower input costs to bolster supply. 

With cream multiples trading below seasonal averages, the cost-effectiveness of acquiring cream products is piquing the interest of industry players. This environment provides a fertile ground for butter producers to ramp up output, leveraging the lower input costs to bolster supply. Indeed, U.S. butter production has witnessed a notable increase, up 5.3% from previous levels, indicating a robust response to the favorable market conditions. 

The implications for pricing, however, are nuanced. While increased production typically suggests a potential price decrease due to supply expansion, the high trading volumes observed in mid-October highlight a sustained demand, which could counterbalance this effect. Nonetheless, the overall outlook suggests that butter prices may soften if production continues to outpace demand, potentially leading to a more competitive market. 

The current market presents valuable opportunities for cream users, particularly those in butter churning. Lower cream costs can enhance competitiveness and profit margins, encouraging further investment in cream-heavy product lines. This scenario benefits those directly involved in butter production and downstream industries reliant on cream-intensive inputs, such as confectionery and bakery sectors, which could see improved cost efficiencies. This potential for cost efficiencies should make the audience feel optimistic.

Unsettled Waters in Dairy Powder: Riding the Tide of Stagnation

In dairy powder markets, stagnant is the word of the week. Has your focus been on the chewy status of staying afloat in these waters? Both whey powder and nonfat dry milk appear to be riding the still tide with no significant movements. While spot whey powder remains steadfast at 60.5ȼ, nonfat dry milk has increased by a mere quarter-cent to $1.3775. 

But why is this stagnation persisting? The answer lies in a tangled web of low output, fierce global competition, and notably weak demand from traditionally critical players like China. As more milk flows into bottling and cheese-making, milk powder production diminishes. Additionally, whey manufacturers’ focus on high-protein concentrates and isolates further diverts resources, tightening the noose on available whey for drying. 

Is global competition more fierce than ever? It appears so, especially in Chinese markets that are experiencing leaner times. Their muted appetite has allowed for intense competition among exporters, vying for the smaller pie of consumer demand. As the global milk supply begins to recover, with a noted uptrend in production from dairy giants, the export battle is unlikely to soften anytime soon. 

Could the market swirling with fierce competition eventually boost prices? While low output might ideally elevate them, current conditions suggest that price support holds firm without a soaring leap. Unless demand dramatically rebounds or competition ebbs, the horizon may hold much of the same for powder markets.

Breaking Free: A Revival in Global Milk Production Amid Challenges

Over the past year, the deadlock we’ve observed in global milk production among the world’s foremost dairy exporters has begun to break, signaling a potential shift. Notably, by August, production rebounded with incremental gains emerging from powerhouses like Australia, New Zealand, and the United States. This resurgence was impactful enough to neutralize earlier production deficits in Argentina and Europe, resulting in a year-over-year increase of 0.2% compared to August 2023. However, one should note that production figures for August 2024 still trail those recorded in the same months of 2021 and 2022, painting a picture of the profound impacts wrought by the downturn experienced through 2022 and late 2023. 

Considering the implications of this budding recovery, it’s pivotal to recognize that global dairy product values may now face headwinds against climbing too high. Key influencers such as China’s subdued import levels are crucial, dampening the prospects for escalating prices. While current price points might be sufficient to encourage ongoing production upticks, particularly in Europe’s established dairying regions, rapid output growth remains unlikely. This hesitance is driven by persistent hurdles—disease outbreaks and a scarcity of breeding heifers, serving as tangible constraints reining the capacity to expand swiftly across major exporting nations.

Avian Influenza Outbreak: Testing Resilience of California’s Dairy Sector

The bird flu hits California’s dairy industry hard, highlighting a significant regional challenge. California, which contributes roughly 16% to the U.S. milk output, is experiencing an alarming decline in production. Why? The avian influenza outbreak has taken a heavy toll on dairy herds here, more so than in other states. The reasons could be manifold. Perhaps the cows in California are grappling with a virulent strain of the virus, or maybe they’re still recovering from the extreme temperatures of the past summer. Whatever the cause, the result is clear: a substantial drop in milk production in the nation’s top dairy state. 

So, what does this mean for the broader U.S. dairy market? It puts additional pressure on the national milk supply when production needs to catch up to domestic and international demand. If California’s production woes persist, it could lead to tighter milk supplies nationally, potentially driving prices upward. Conversely, if other states manage to ramp up production, they might buffer against California’s shortfall. Still, the challenges posed by disease outbreaks like bird flu underscore the vulnerability of regional supply chains and the need for robust biosecurity measures across the dairy industry.

Milk Prices: A Slight Dip with Promising Horizons

The USDA’s recent announcement of the October milk price at $22.85 per cwt marked a notable decrease of 49ȼ from September. Yet, it remains optimistically positioned for dairy producers. This dip might not disappoint their spirits harshly as the future trajectory remains promising. October’s Class IV price closed at $20.90, showing a descent of $1.39 from September, with futures aligning around $21 for the foreseeable future. This stability in Class IV may bring a level of reassurance. 

However, Class III prices are anticipated to dip below the peaks in September and October. November Class III concluded at $20.25, with December and subsequent contracts hovering in the mid-$19 range. While these figures may not replicate the profitability seen earlier in the year, they provide a sustainable revenue stream for covering operational costs. 

The economic outlook appears cautiously optimistic. Producers could expect less lucrative revenues than those recorded during the summer and early fall. Nonetheless, with stabilizing prices and reasonable future forecasts, there remains a silver lining. Additionally, saving on feed costs due to favorable crop conditions may positively offset some of the margin compressions expected from declining milk prices.

Weathering the Harvest: A Bounty of Opportunity for Dairy Farmers

This autumn, agricultural conditions have been ideal, offering a respite to farmers after past challenges. With September and October being exceptionally dry, the harvest was swift and smooth, leading to a more efficient collection of crops with minimal disruptions. The welcomed sight of heavy rains now replenishes the soil, promising nutrients for the upcoming planting seasons. 

In South America, Brazil’s agricultural activities look promising as well. Following delays due to an arid winter, recent rains have rekindled the planting of soybeans, ensuring a continuity of agricultural practices. 

The favorable weather and a steady hand on the fields have led to a leveling of key crop prices, with corn and soybean prices stable and competitive. The significant dip in December soybean meal prices to $295 per ton further highlights the current state of surplus and affordability. 

So, what does this mean for dairy producers? Feed costs are a long-standing part of the equation for dairy production economics. With cheaper feed, primarily corn and soybeans, dairy farms can maintain and potentially increase their herd’s productivity without stress on their financial outlays. Lower feed costs translate to reduced expenses in dairy farming operations, potentially increasing profit margins or allowing for strategic reinvestments into other areas, such as technology or herd health. 

The Bottom Line

As we wrap up this week’s dairy market report, it’s clear that the interconnected dance of cheese demand, milk production, and market prices is as intricate as ever. The declining cheese stocks signal a robust demand that could lead to a surge in production, especially with upcoming plant expansions. This, coupled with steady U.S. milk output, suggests a potential rise in cheese supply, which could dramatically alter market dynamics if demand slows. 

Meanwhile, falling Cheddar and butter prices reflect the nervousness lingering over supply-demand imbalances. In contrast, the abundant butter market offers a fresh opportunity amidst an overflow of cream. On the global stage, the revival in milk production among leading exporters should not overshadow the challenges faced, such as the avian influenza outbreak impacting California’s dairy farms. 

Milk prices, though experiencing a slight dip, hold promising prospects. A bountiful harvest season further enhances the outlook for dairy farmers by ensuring affordable feed costs. These elements, all playing their part, paint a vibrant picture of the current dairy landscape. 

As a reader, what do you think about these trends and developments? How might they impact your work or business? We’d love to hear your thoughts. Share your insights in the comments, and remember to engage with your peers by sharing this article.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent
Send this to a friend