Archive for producer price differential

USDA Raised Class I $1.84. Upper Midwest Gets 10 Cents, the Northeast 48.

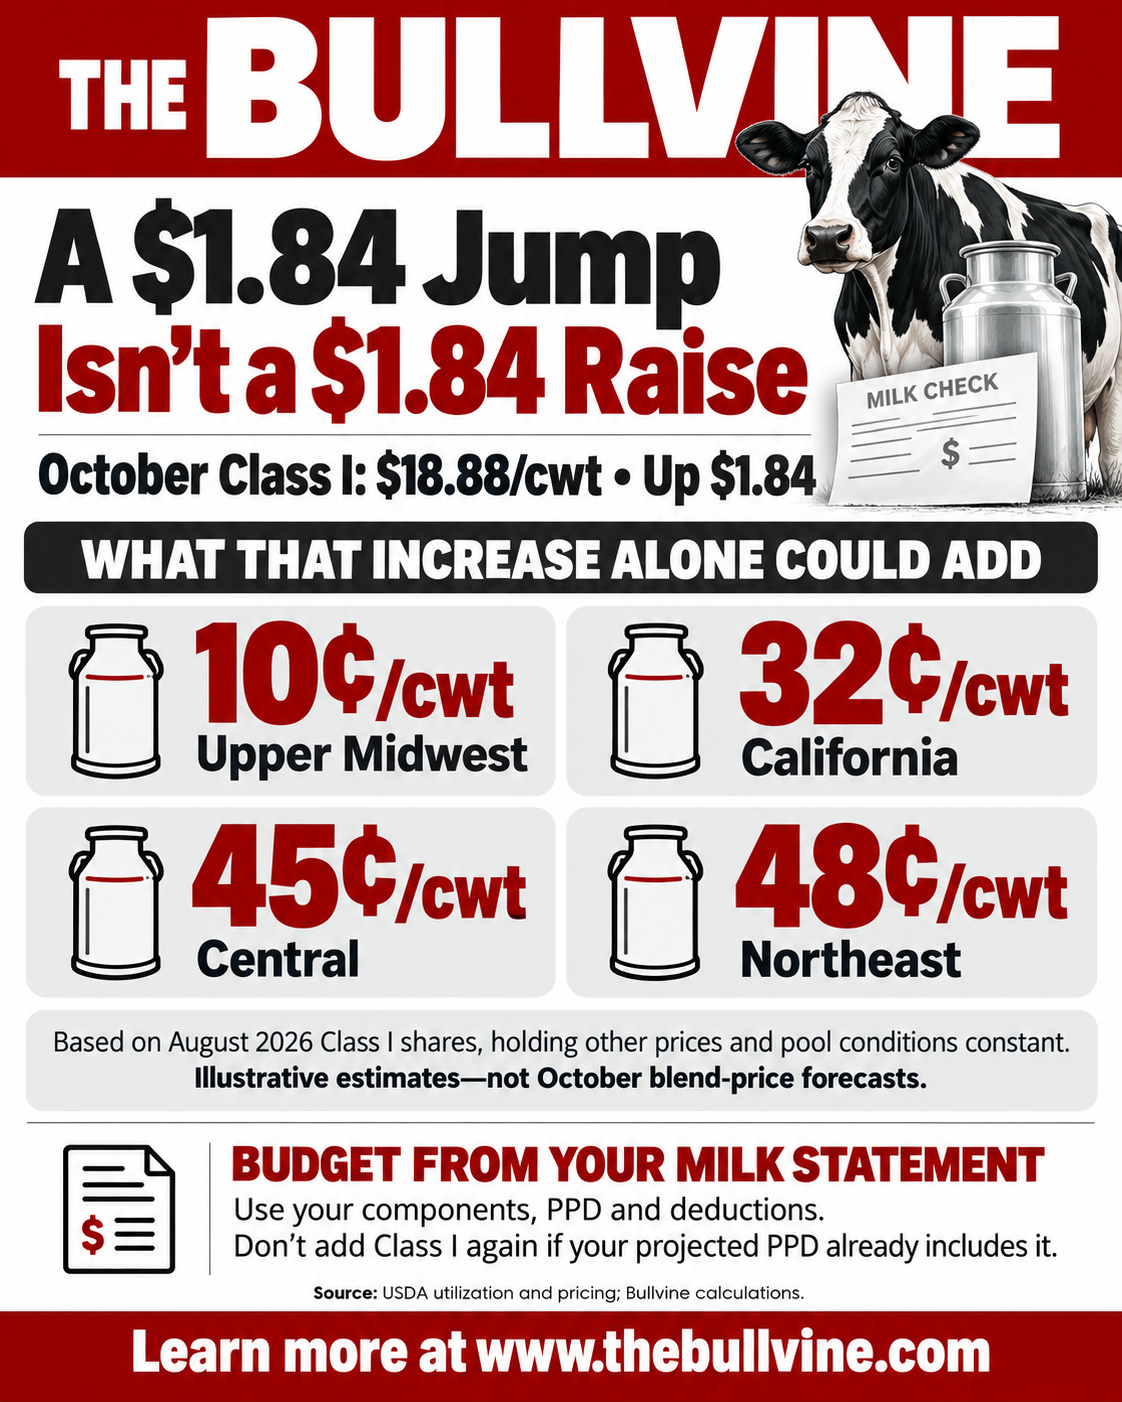
October’s base Class I hit $18.88. Run the $1.84 jump through August pool use and, on our math, an Upper Midwest blend picks up about a dime. The Northeast gets about 48 cents.
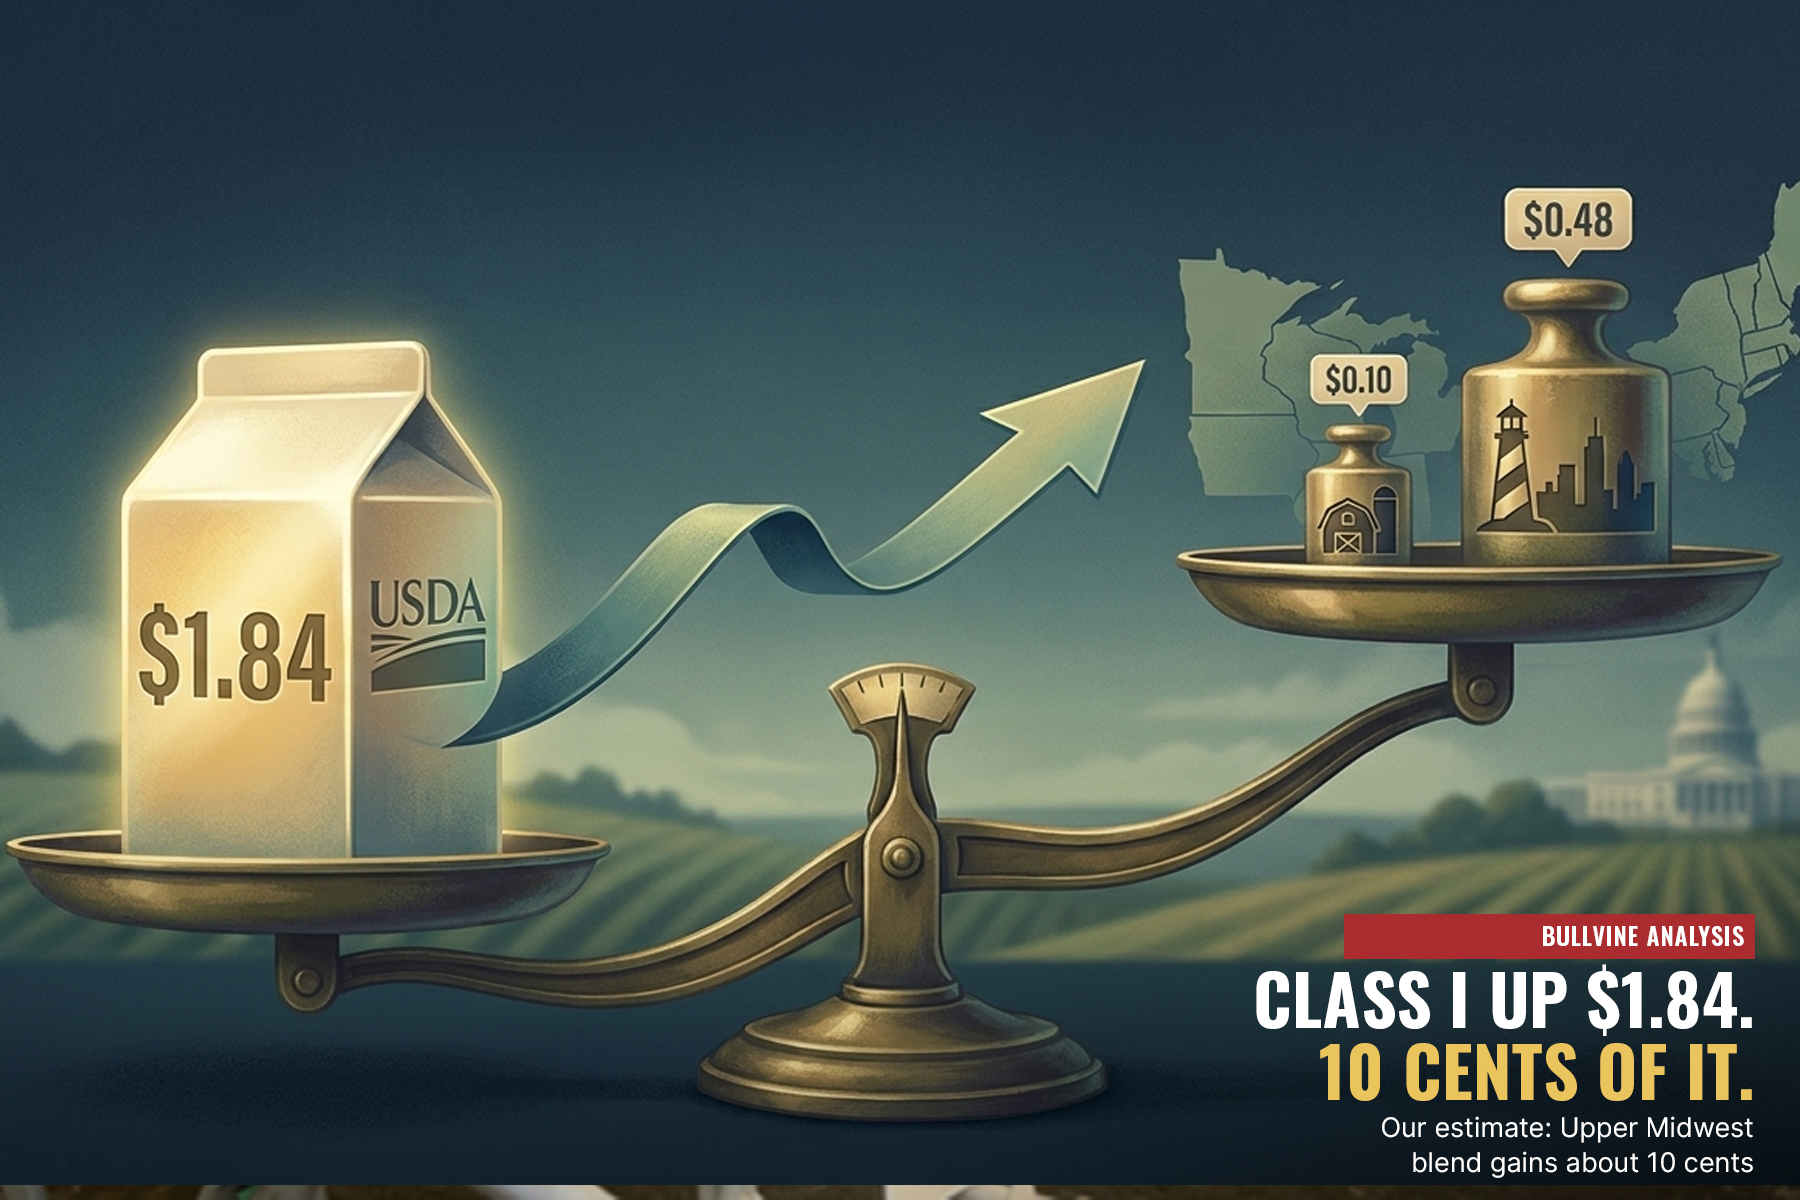
USDA set October’s base Class I milk price at $18.88/cwt. That’s $1.84 above September’s $17.04 and $2.53 above January’s $16.35. Run that $1.84 through actual August pool utilization and the first-pass blend effect is about 10 cents in the Upper Midwest, 32 cents in California, 45 cents in the Central Order and 48 cents in the Northeast.

All of those numbers are correct. None of them is $1.84.

The base Class I price is the minimum starting value for milk used in fluid products, before the location differential at the receiving plant. It isn’t the all-milk price or an order’s uniform price. It’s definitely not what’s left after components, the PPD, hauling, marketing charges and capital retains go through your statement.

Why October rose $1.84

USDA brought back the higher-of Class I mover on June 1, 2025. Updated Class I differentials and make allowances started the same day, and higher skim composition factors followed on December 1, 2025.

For October, the advanced Class IV skim value beat the Class III side. Nonfat dry milk carried the powder side, while weak butter capped the butterfat contribution. September’s final prices showed the same split: Class IV at $18.94 and Class III at $16.04.

That makes October a stronger price for fluid milk. It doesn’t mean every hundredweight in an order gained $1.84.

Utilization does the first cut

Bullvine math: simplified Class I pass-through

Blend change=Class I change×Class I utilization share

This leaves out moves in the other classes, components, location differentials, depooling and pool expenses. It’s not a forecast of the uniform price. It’s a way to keep a Class I headline in proportion.

USDA’s August 2026 utilization data, published September 24, gives each order a different multiplier:
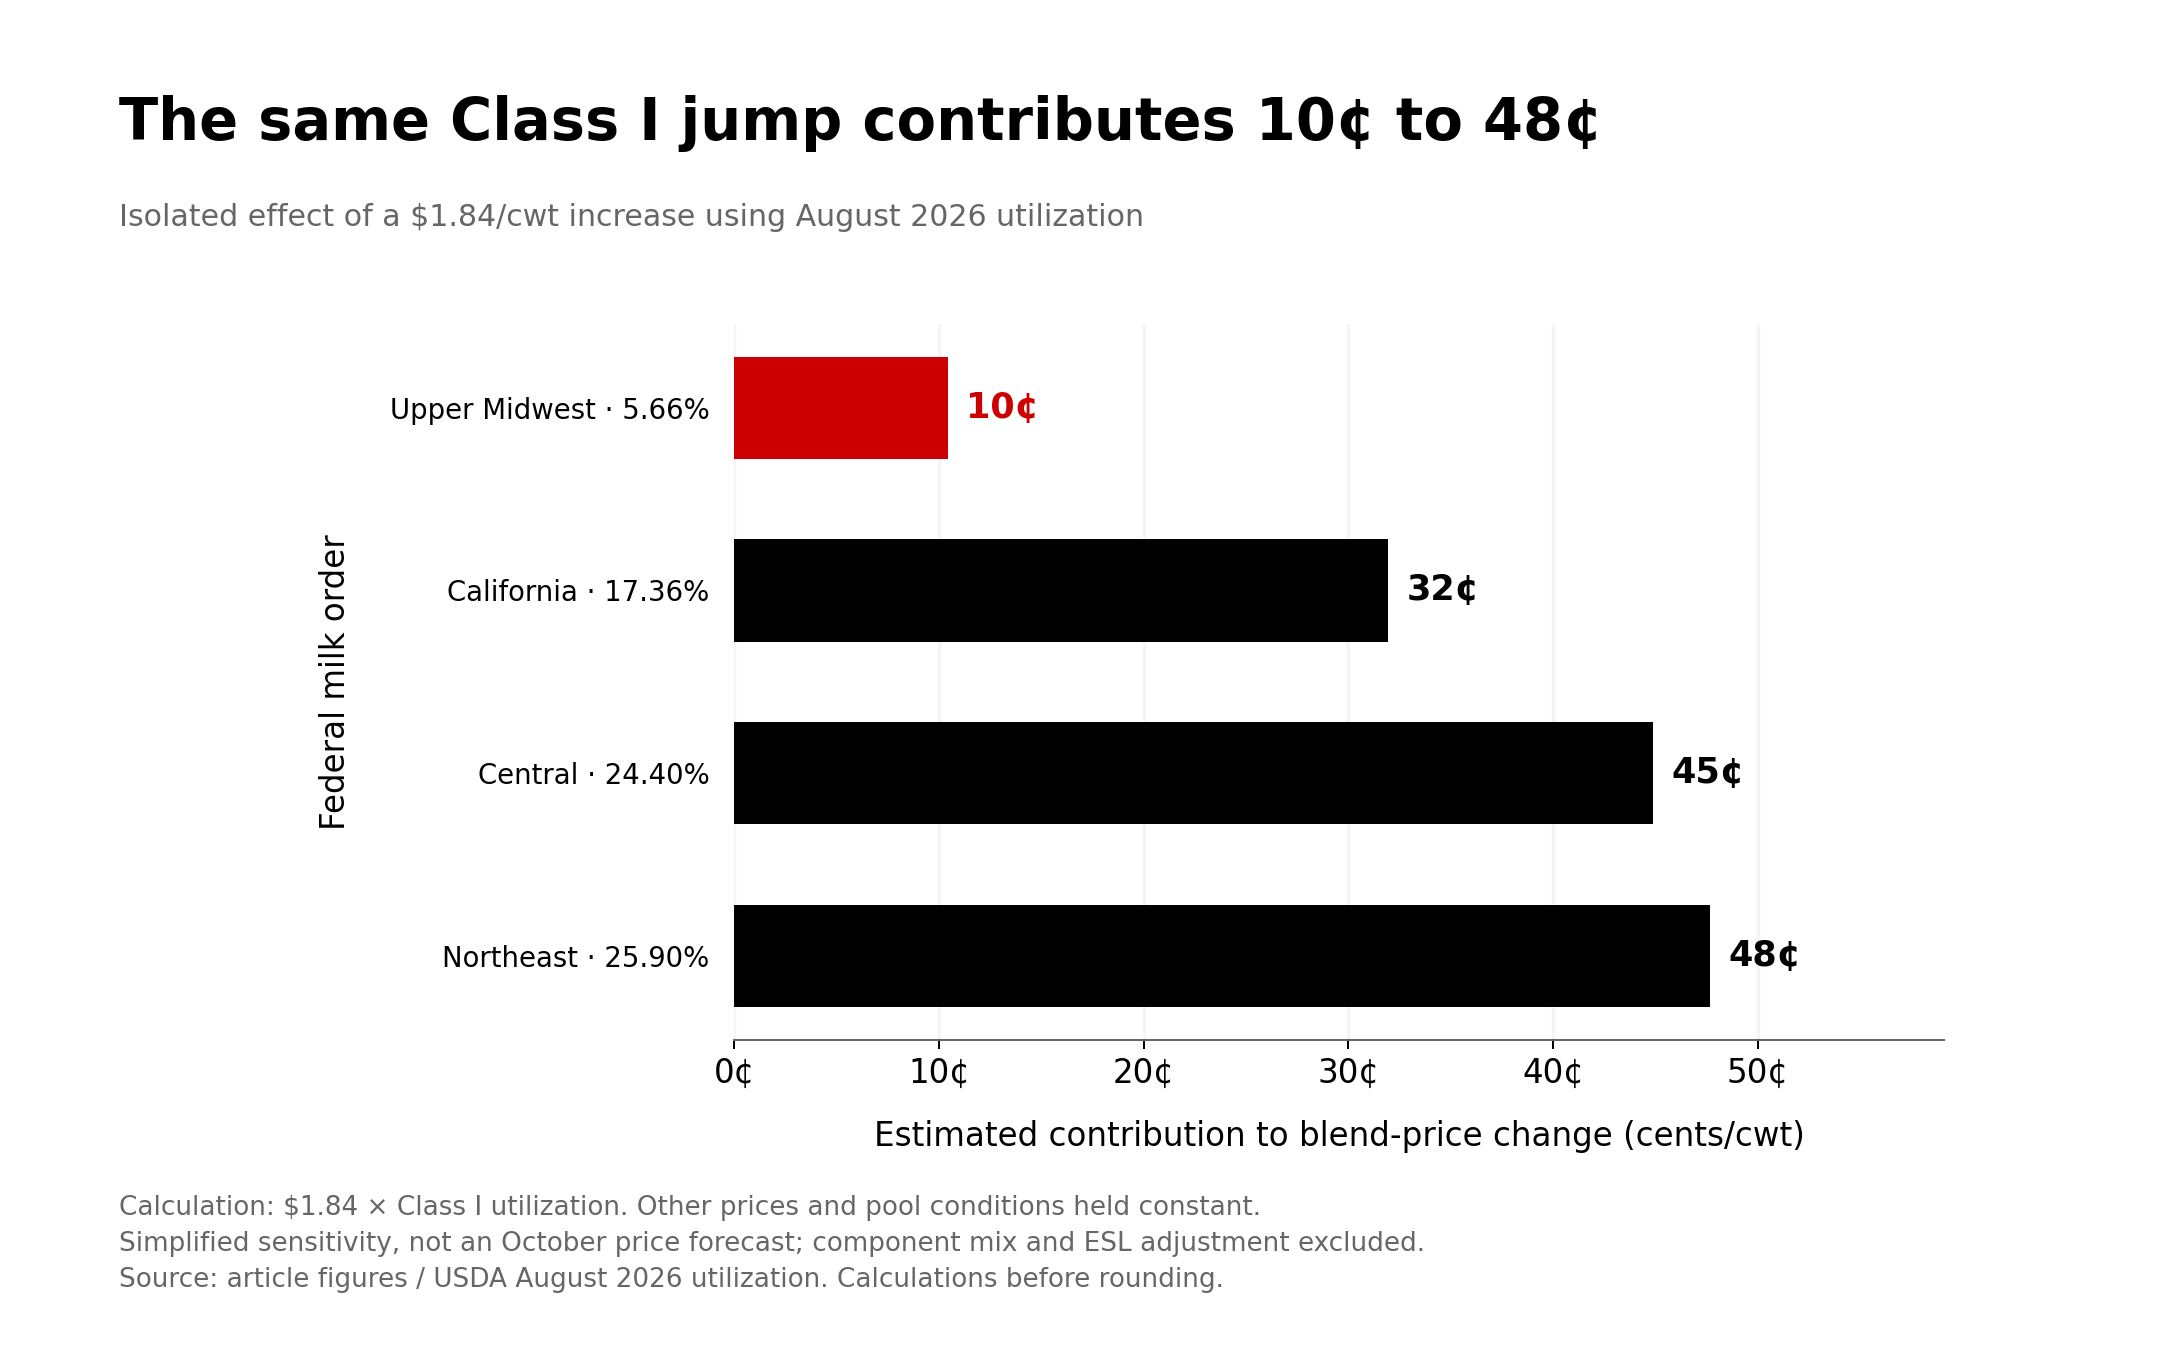
OrderAugust Class I utilization2026 range, Jan–AugBlend effect of October’s $1.84 (Bullvine math)
Upper Midwest, FMMO 305.66%5.66–12.25%about $0.10/cwt
California, FMMO 5117.36%17.36–23.13%about $0.32/cwt
Central, FMMO 3224.40%24.40–32.30%about $0.45/cwt
Northeast, FMMO 125.90%25.90–28.88%about $0.48/cwt

August is the conservative month for comparing the four orders. Order 30’s September report has since come out at 6.4% Class I, which would push its pass-through to about 12 cents. At January’s utilization, the same $1.84 would have added about 23 cents in Order 30 and 53 cents in Order 1.

The counterevidence holds up. Fluid-heavy orders get far more of a Class I move. Order 1 passes through about four and a half times what Order 30 does. Farmshine’s analysis put the combined PPD benefit from the updated differentials at about $0.71/cwt at the Northeast base zone over the first four months of 2026, with the amount depending on plant location.

Herd math

The herd blocks use 24,390 lb per cow per year, the 2025 U.S. average cited in CoBank’s recent component analysis. That’s 243.9 cwt per cow, or about 20,325 cwt a month on 1,000 cows. Production is assumed flat across months and the same at every herd size.
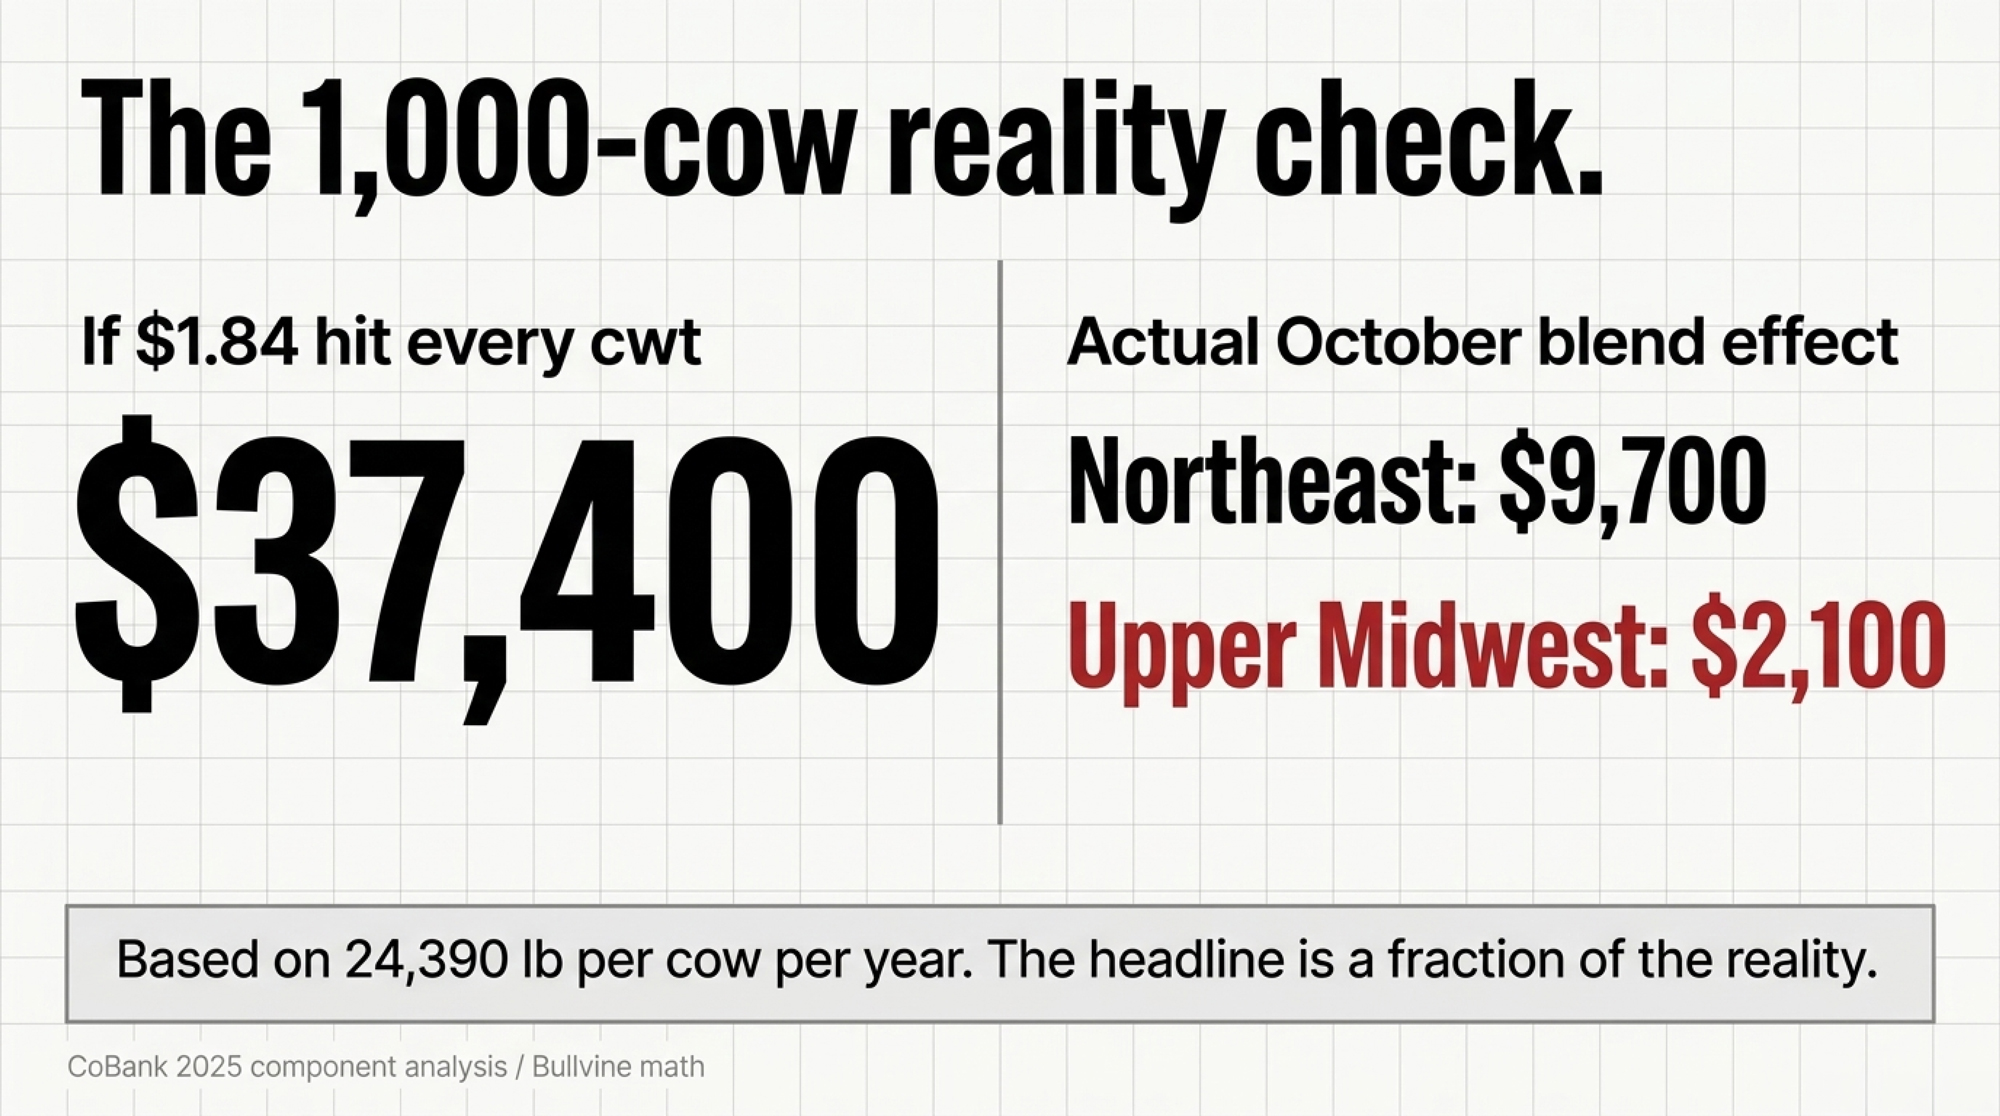
Bullvine math: October’s $1.84 Class I move, one month, 1,000 cows
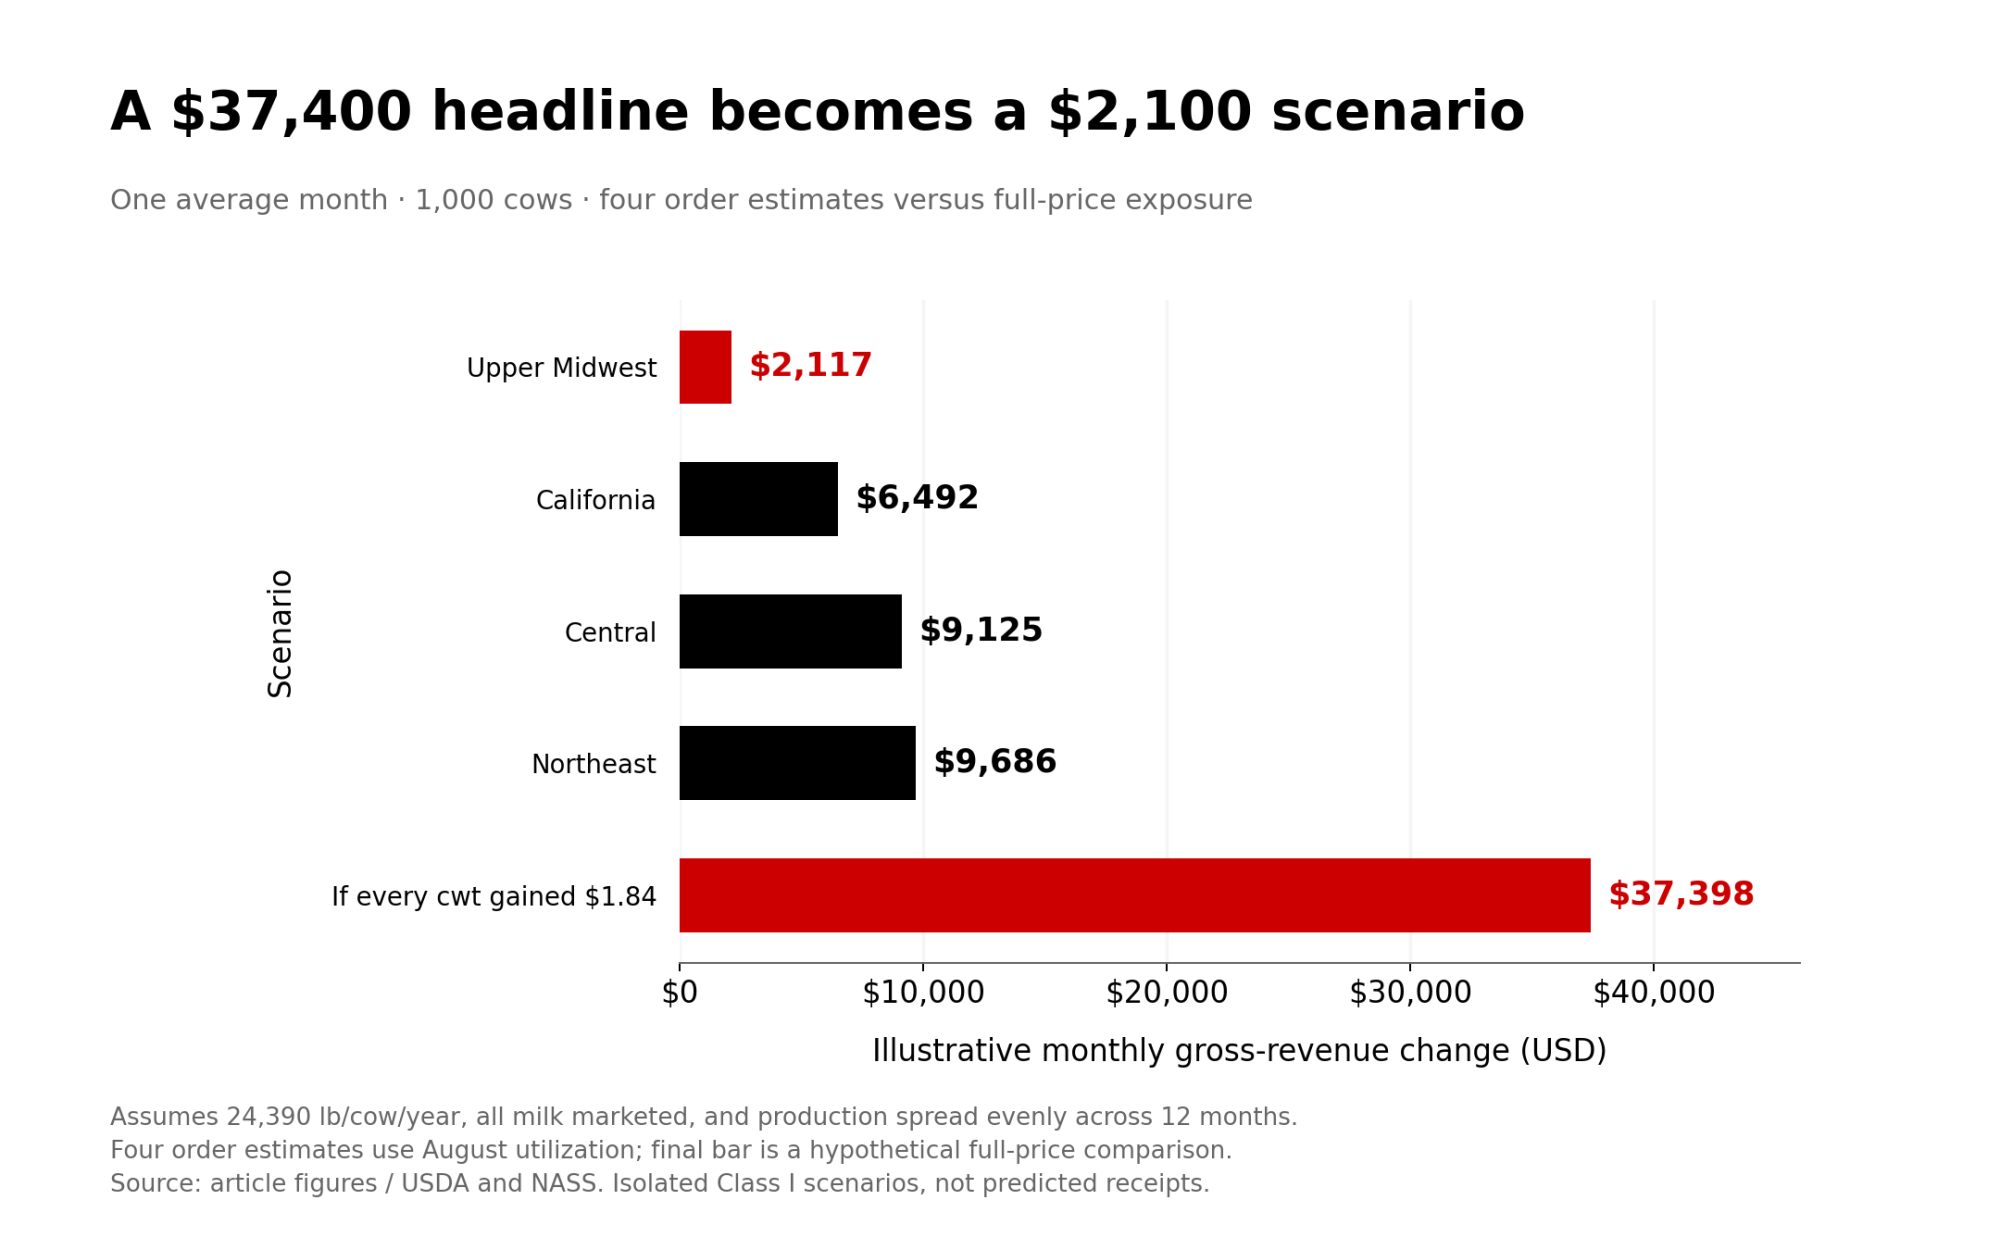
OrderApproximate blend effectOctober dollars
Upper Midwest$0.104about $2,100
California$0.319about $6,500
Central$0.449about $9,100
Northeast$0.477about $9,700
If the full $1.84 hit every cwt$1.84about $37,400

Bullvine math: annual effect of each lever, if it held for 12 months
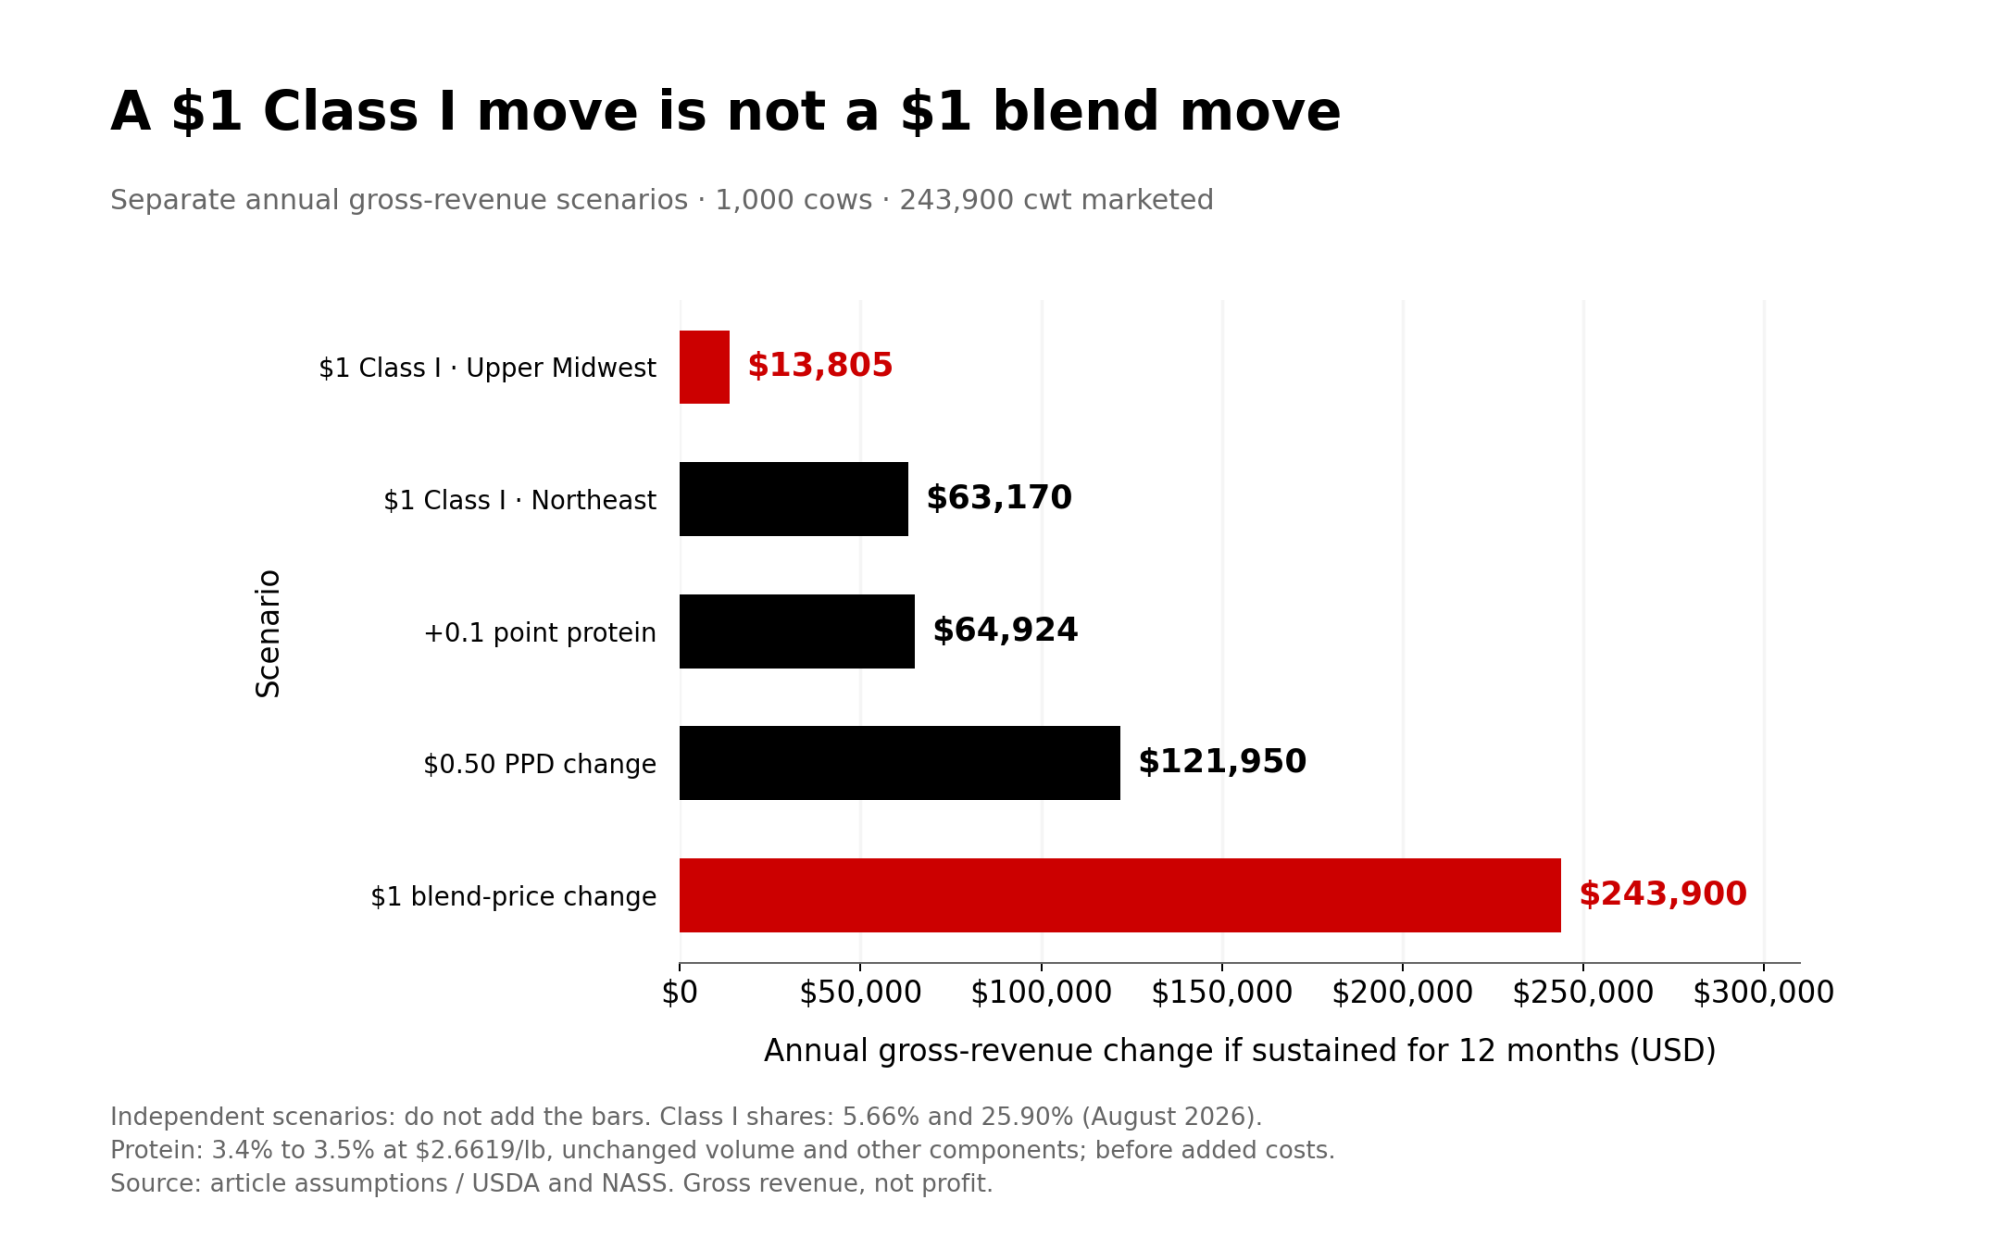
Lever300 cows (73,170 cwt)500 cows (121,950 cwt)1,000 cows (243,900 cwt)
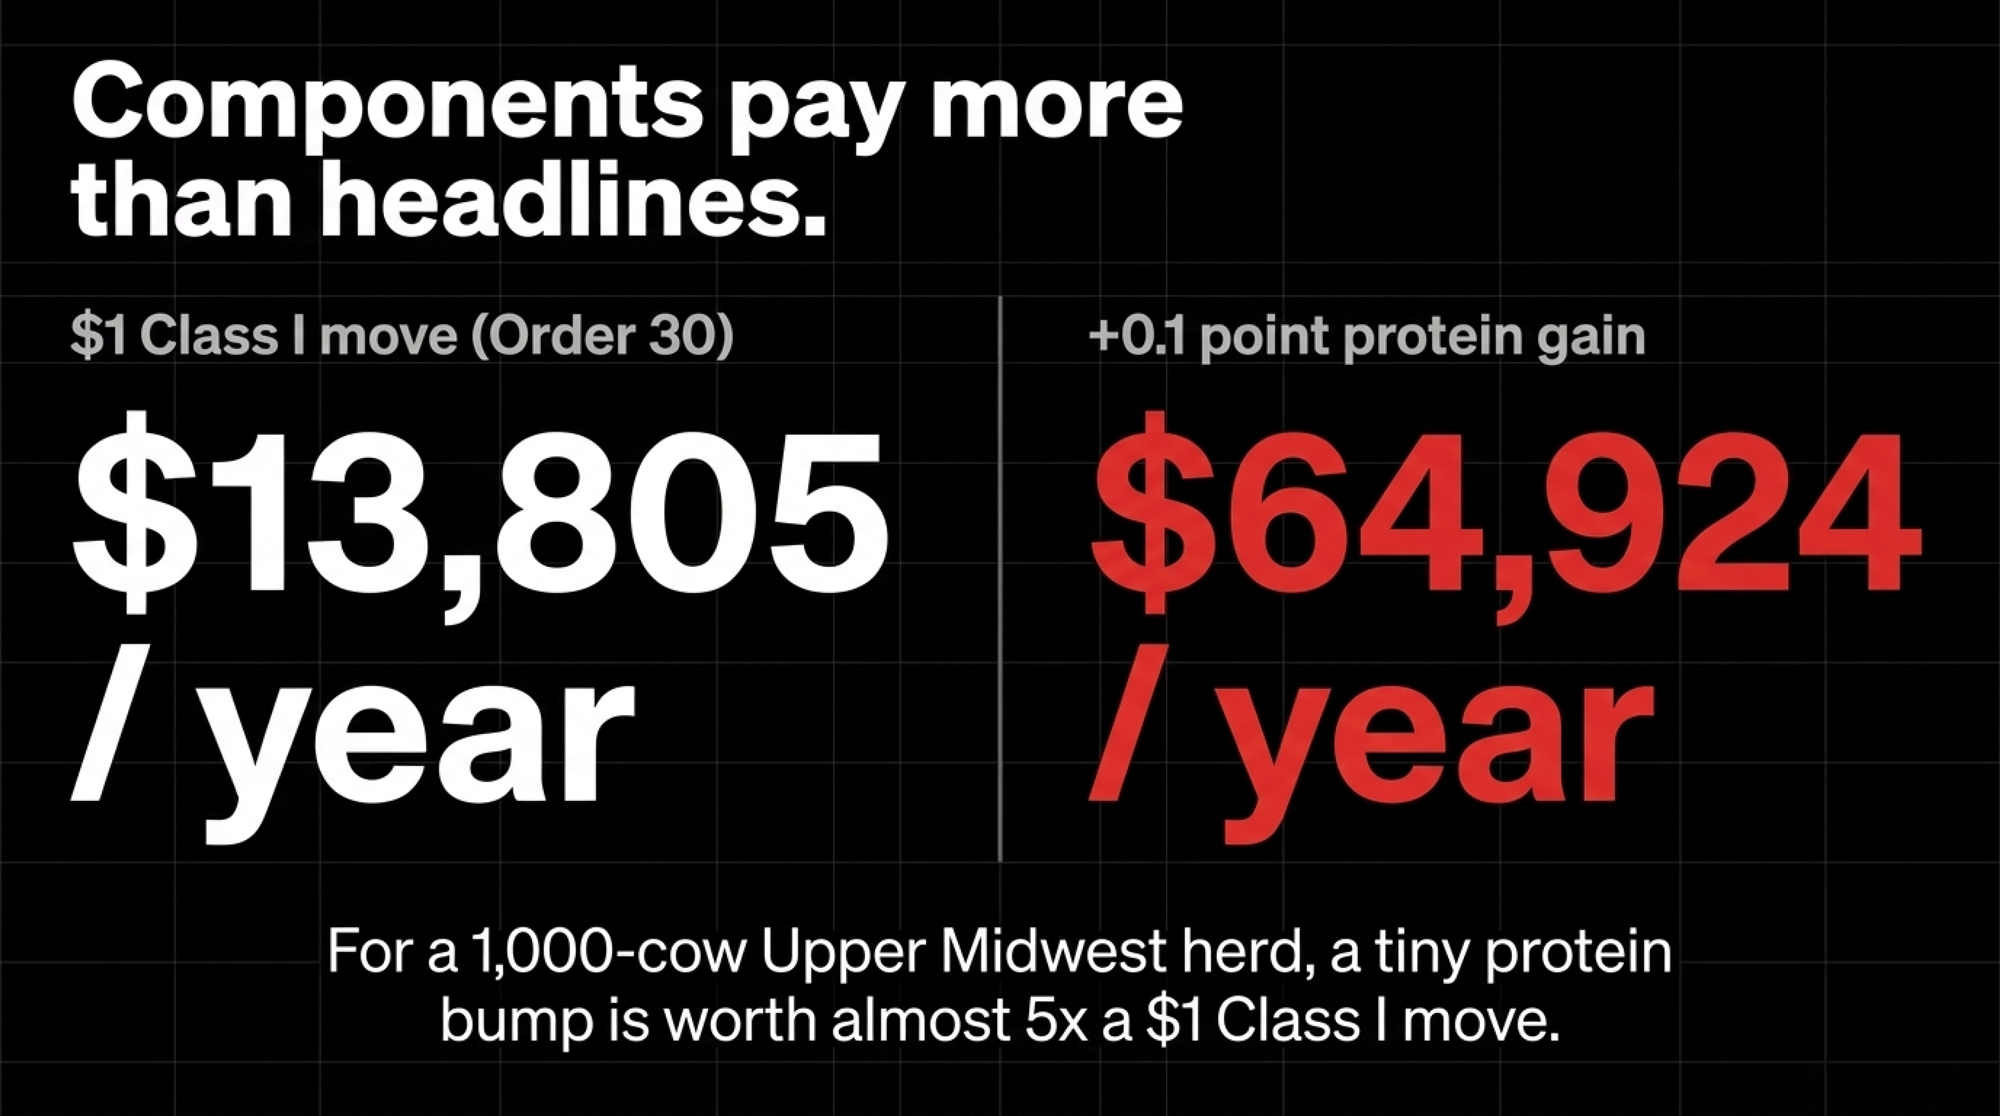
$1 Class I move, Order 30 (5.66%)$4,141$6,902$13,805
$1 Class I move, Order 1 (25.90%)$18,951$31,585$63,170
$1 blend move$73,170$121,950$243,900
$0.50 PPD swing$36,585$60,975$121,950
+0.1 point protein at $2.6619/lb (September price)$19,477$32,462$64,924

That’s the fix for the line that “$1/cwt equals $250,000 on 1,000 cows.” It’s roughly right for a $1 move in the blend, at this yield. For a $1 move in one class covering a fraction of the pool, it’s way off.

On a 1,000-cow Upper Midwest herd, a 0.1-point protein gain is worth almost five times a $1 Class I move, and a 50-cent PPD swing is worth more than that.

The PPD carries the rest

USDA announces a PPD in seven federal orders: Northeast, Upper Midwest, Central, Mideast, California, Pacific Northwest and Southwest. Those orders pay for butterfat, protein and other solids, plus the PPD, which is the uniform price minus the Class III price.

That makes the PPD sensitive to class spreads and to which manufacturing milk stays in the pool. Class I has to be pooled. Class II, III and IV milk can be left out when handlers meet the order’s rules. The incentive is strongest when a manufacturing class sits well above the uniform value.

That happened in 2026. Iowa State Extension reported Central Order pooled milk at about 1.35 billion lb in March, down from more than 1.50 billion a year earlier, with Class IV at only 12% of pooled milk. That pattern fits depooling while Class IV sat above Class III, but a drop in pooled volume alone doesn’t show which handler pulled which pounds.

Depooling is allowed under the order rules. The point isn’t that someone took farmers’ money. It’s that a high Class IV price can’t lift the blend if much of the high-value Class IV milk isn’t in the pool.

Walk one cheque

This is a constructed September example for an Upper Midwest Order 30 producer shipping at Order 30’s average tests. It’s not an actual producer statement. Every regulated line comes from USDA’s September Order 30 computation, released October 12. 

Step 1: Class I at the plant. USDA set September’s base Class I at $17.04. At a Cook County, Illinois plant, the $3.20 differential made it $20.24. That’s what fluid handlers owed the pool, not what the producer got paid.

Step 2: pool result. Class I was 6.4% of Order 30’s September producer milk and Class III was 91.6%. The statistical uniform price was $16.62 at 3.5% butterfat. 

Step 3: components at actual pool tests. Order 30 producer milk averaged 4.24% butterfat, 3.29% protein and 5.80% other solids in September. 

Bullvine math: component value

  • Butterfat: 4.24×1.4762=6.264.24×1.4762=6.26
  • Protein: 3.29×2.6619=8.763.29×2.6619=8.76
  • Other solids: 5.80×0.4147=2.415.80×0.4147=2.41
  • Component value: about $17.42/cwt

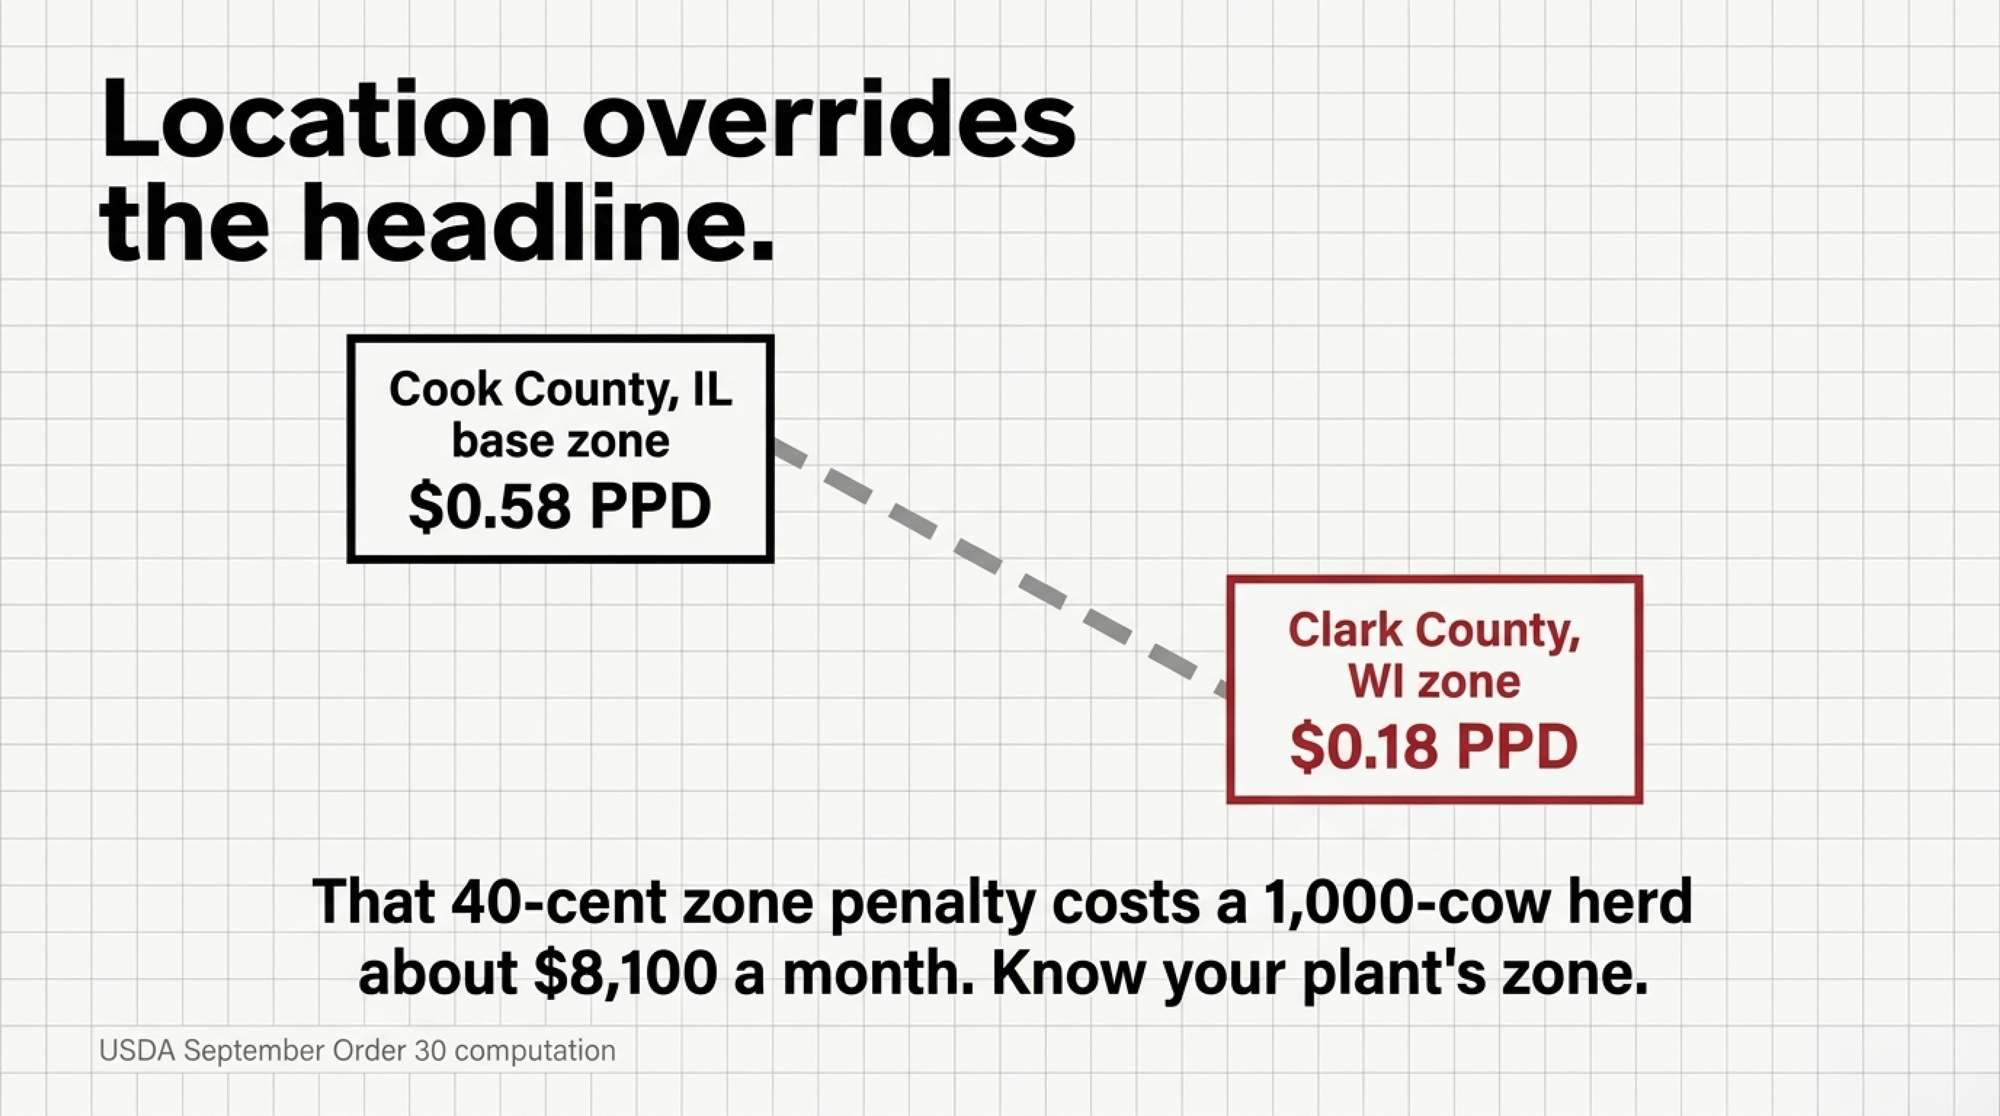
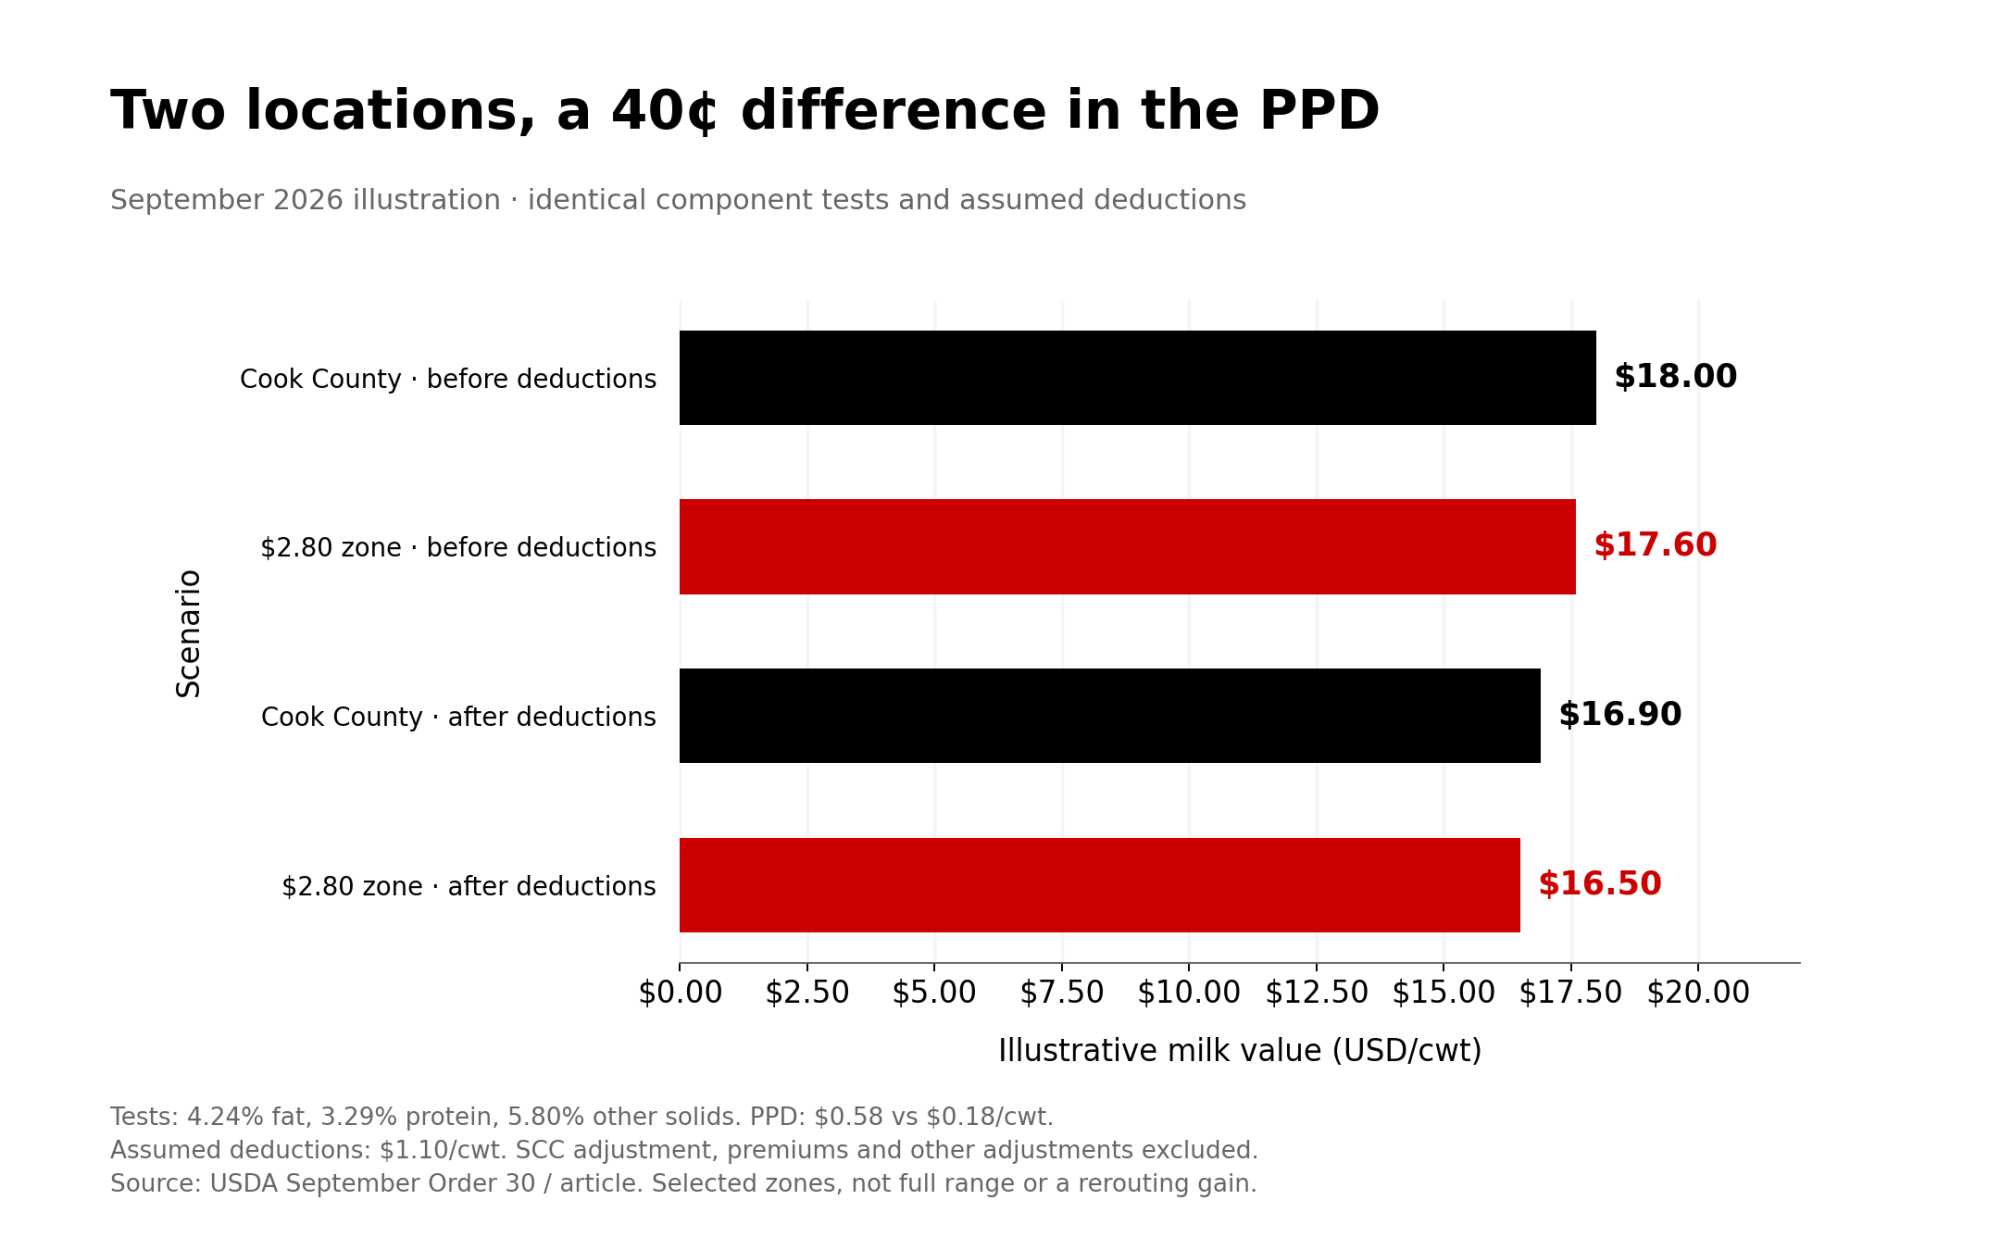
Step 4: PPD by zone. September’s PPD was $0.58 at the Cook County base zone. In the lower-differential zones it fell to $0.48, $0.28 and $0.18. Plants in Clark County, Wisconsin carried a $2.80 Class I rate, 40 cents under Cook County’s $3.20, which puts them in the $0.18 zone. 

Delivery pointPPDGross regulated value (Bullvine math)
Cook County, IL base zone$0.58about $18.00/cwt
$2.80 zone, e.g. Clark County, WI$0.18about $17.60/cwt

Step 5: co-op lines. These are assumptions, not reported figures:

  • Marketing charge: $0.15
  • Capital retain: $0.25
  • Hauling: $0.70
  • Constructed net: about $16.90/cwt at the base zone and $16.50 in the Clark County zone, before quality and volume premiums, assessments or other member-specific lines

The $20.24 Chicago Class I price never showed up on the cheque. It went into the pool at a 6.4% share. Then components and a PPD that depends on location set the regulated value. Notice too that this producer’s $18.00 gross beat the $16.62 uniform price, but only because the milk tested above the standard.

Location turned out bigger than the headline. Bullvine math: the 40-cent PPD gap between the base zone and the Clark County zone is about $8,100 for one month on 1,000 cows. Order 30’s entire October Class I pass-through is worth about $2,100 on the same herd.

No standardized public schedule of co-op hauling, marketing charges and retains turned up. Those three lines stay labelled as assumptions until a published schedule or a consented statement replaces them.
Mailbox data run behind

AMS mailbox prices are the better yardstick for what farms actually got. They’re net of hauling, co-op dues, assessments and capital retains, they include premiums, and they’re regional averages that come out well after the class prices.

That lag rules out a clean October comparison today. October’s Class I price is known before the milk is marketed. October components, uniform prices, PPDs and mailbox prices come later.

The board moved this week

On October 1, USDA’s table had November Class III at $15.96 and November Class IV at $20.65, a $4.69 spread. The October contracts showed $15.13 and $20.34.

Class III has rallied since then. November Class III closed at $16.87 on October 14, up 34 cents on the day. That’s $1.89 above the October 9 quote and 91 cents above October 1. 

The direction matters more than any one day. If Class IV holds near $20 while Class III climbs, the depooling incentive shrinks. If Class III gives the rally back, the March-style setup returns.

Market advisory firms that read this split for producers usually sell hedging and insurance services too. Weigh their recommendations with that in mind.

DMC and DRP measure different milk

USDA’s August DMC margin was $9.34/cwt: a $19.80 national all-milk price minus a $10.46 formula feed cost. Against $9.50 coverage, that’s a 16-cent shortfall before payment factors.

Put the same $19.80 milk price against a herd spending $12/cwt on feed. Its simple milk-over-feed margin is $7.80, not $9.34 (Bullvine scenario). DMC protects the national formula margin. It doesn’t know your mailbox price or your feed bill.

DRP protects quarterly revenue based on your elected Class III/IV weighting or component pricing, settled on announced USDA prices plus an area production adjustment. It doesn’t cover your mailbox price, your hauling bill or your zone PPD.
What this means for your operation

  • Budget from the statement, not the headline. Start with shipped cwt, actual tests and your plant’s zone. Add your zone’s PPD history and subtract your own deductions. Bring in the Class I price last, multiplied by your order’s utilization.
  • Know your multiplier. In August, a $1 Class I move was worth about 6 cents/cwt in Order 30 and 26 cents in Order 1. Check your market administrator’s latest monthly report before every budget run.
  • Know your zone. In September, the Order 30 PPD ran from $0.58 to $0.18 depending on location. Your statement’s PPD line should line up with your plant’s zone. If it doesn’t, ask why. 
  • Watch the Class III/IV spread. November’s spread was $4.69 on October 1, and Class III has gained 91 cents since. A narrowing spread eases depooling pressure on PPDs.
  • Price the protein. At September’s $2.6619/lb, 0.1 point of protein was worth about 27 cents/cwt. That beats a $1 Class I move in every order in the table.
  • October 21–22: USDA’s November advanced prices come out. Rerun the pass-through table.
  • December 18, 2026: 2027 DMC enrollment closes. Locked-in operations still have to file CCC-801 and pay the administrative fee. Tier 1 now covers the first 6 million lb.
  • Before buying DRP: check with your agent which quarters are still open. Then compare your elected basis against your last 12 statements.
The Bullvine: FMMO Reality Check Calculator

Stop budgeting on USDA headlines. Plug in your herd size to see exactly how much of a Class I price jump actually makes it to your uniform blend price.

The Headline Illusion (1 Month)
\$37,398
What the headline implies you’ll make
The Bullvine Reality (1 Month)
\$2,116
Your actual blend effect based on FMMO utilization

Copy this code to add this calculator to your own website:

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.

NewsSubscribe
First
Last
Consent

$51 to $90 a Cow in Wisconsin. Zero in Ontario. Same Tariff, Same Week.

Canada’s counter-tariffs are live. Extension puts Wisconsin at $51–$90 a cow. Ontario’s formula has no tariff line at all — which sounds like protection until you need the warning.

Executive Summary: Class III is built from cheese and dry whey — the two products Canada just tariffed at 25 and 50 per cent — and Federal Order 30 carries the thinnest pooling cushion in the country, 64 cents year-to-date against $3.54 in the Northeast. That’s why UW–Madison Extension’s $0.20 to $0.35/cwt estimate lands nearly whole on a Wisconsin cheque: $51 to $90 a cow, or $15,300 to $27,000 a year on a modelled 300-cow herd. Ontario’s number, through the pricing formula, is zero. Canada’s National Pricing Formula runs on cost of production and CPI with no tariff input anywhere — the P5 boards defend income by moving volume, so you’ll see fewer incentive days long before you ever see a lower base price. Two more U.S. measures land this month, a wider cheese list September 15 and an outright ban on Canadian dairy September 29, all resting on a 1930 statute nobody had ever used to impose tariffs and nobody has yet challenged in court. Pull your last three cheques, find your PPD and your statistical uniform price, then call your plant before the 15th.

Canada dairy tariffs 2026

Fifty-one to ninety dollars a cow a year. That’s what the University of Wisconsin–Madison Division of Extension estimates the Canada dairy tariffs now cost a Wisconsin herd, published September 7, 2026 — one day before Canada’s counter-tariffs took effect. On a modelled 300-cow herd, that’s $15,300 to $27,000 off the year. Cross into Ontario, and the same trade fight moves a P5 milk cheque by zero through the pricing formula.

Same tariffs. Same week. Two milk cheques that don’t feel it the same way at all.

Darin Von Ruden, president of the Wisconsin Farmers Union and a third-generation dairy farmer near Westby, told WEAU in late August that Wisconsin’s butter sector leans on Canadian buyers to move inventory the domestic market can’t absorb. He attached no dollar figure to it, and the syndicated version of his remarks says so plainly.

Butter sits on neither tariff list. Not Canada’s. Not the U.S. one. So the pressure he pointed at doesn’t travel through the tariff schedule at all — it travels through demand, which is a slower and quieter road.

Rates, dates, and litigation status are current as of September 9, 2026. Two further U.S. measures land September 15and September 29.

What Got Tariffed on September 8, and What’s Still Coming

Canada’s counter-tariffs went live at 12:01 a.m. on September 8, 2026. The dairy portion is specific: 50% on U.S. milk and cream powders, whey, casein, milk protein concentrates, and milk protein substances — and 25% on every named U.S. cheese, from cheddar and mozzarella through parmesan, gouda, brie, provolone, and blue.

Finance Canada describes it as matching the U.S. Section 338 tariffs dollar for dollar — 15, 25 and 50 per cent rates across C$27.6 billion in goods. For scale, the U.S. shipped US$333.6 billion north last year.

The U.S. move came first. Three presidential proclamations signed July 20, 2026 imposed a 50% ad valorem duty on Canadian goods including dairy, alcohol, motor vehicles, timber, and clothing. The dairy annex covers milk and cream, whey and whey protein concentrates, milk protein concentrates, casein and caseinates, milk albumin, lactose, and bakers’ mixes containing butterfat. Effective 12:01 a.m. Eastern on August 19, implemented August 22 — days after Prime Minister Mark Carney called off trade talks.

It didn’t stop there. In a flurry of proclamations issued Tuesday, September 8, the administration added a wider range of cheese to the Section 338 list, along with steel and aluminum products, mattresses, golf carts, printer paper, motorboats, and animal hides. Those take effect September 15 at 12:01 a.m. EDT. No outlet had published the line-level cheese codes at press time — check the annex itself, not the news summaries.

A separate set of measures goes further. The U.S. will ban Canadian dairy products, most alcoholic beverages, and motorcycles outright, effective September 29 at 12:01 a.m. EDT. A tariff becoming an import prohibition in five weeks. Different instrument, different math.

What’s Exempt — Both Directions

  • Not tariffed by either country: butter, fluid milk, cream, yogurt, ice cream (UW–Madison Extension, Sept 7, 2026)
  • Quota status doesn’t help: AgCanada reported Aug 26 that Canada’s counter-tariffs hit U.S. dairy in-quota and over-quota alike
  • Origin is a separate question: secondary reporting says Ottawa removed counter-tariffs on CUSMA-qualifying U.S. goods on September 1 — confirm how that interacts with the September 8 list through your customs broker rather than assuming it either way

Running the Numbers: A Modelled 300-Cow Wisconsin Herd

Extension’s model is the only published farm-level estimate from these tariffs. No second institution has released a competing or corroborating figure, so treat the range below as one land-grant model — documented and transparent, but not a consensus. It also predates the September 15 cheese expansion, which means it likely understates rather than overstates.

The trade base (UW–Madison Extension, September 7, 2026):

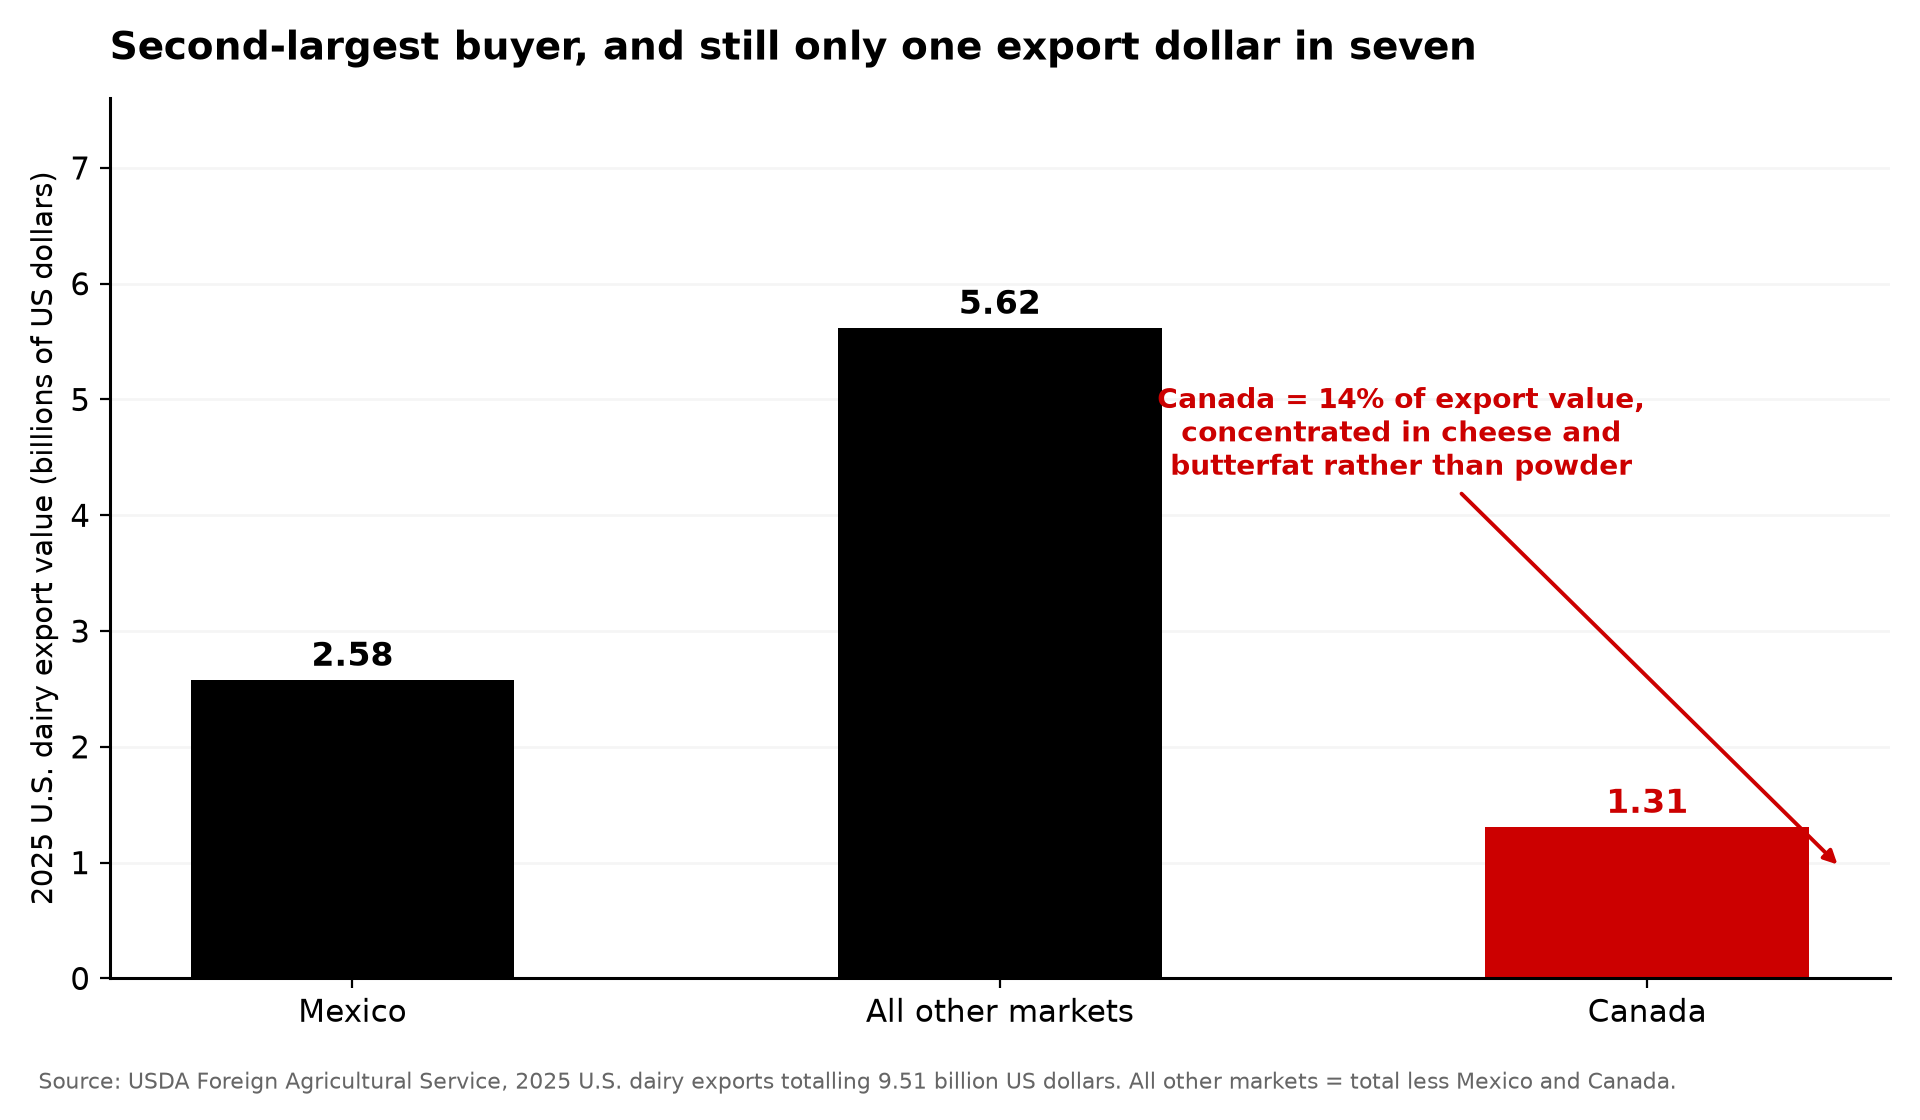
  • U.S. dairy sales to Canada, 2025: about $1.3 billion — second only to Mexico, roughly 14% of all U.S. dairy exports
  • U.S. dairy imports from Canada, 2025: $432.7 million, per Extension’s reading of customs data
  • Tariffed products with measurable customs value: about $255 million

The floor calculation — lost export value only, no price transmission:

  • $250 million ÷ 2.3 billion cwt of U.S. milk production = $0.11/cwt
  • On a modelled 300-cow herd at 25,600 lbs/cow/year: 76,800 cwt × $0.11 = $8,448/year
  • Across Wisconsin: about $35 million

That’s the floor. It spreads lost revenue across every hundredweight in the country and assumes no knock-on price effect.

The anchor estimate — price transmission into Class III, not just lost volume:

  • Class III effect: $0.20 to $0.35/cwt
  • Wisconsin statewide: $65 to $113 million/year
  • Per cow: $51 to $90/year, at Extension’s 25,600 lbs/cow assumption
  • Wider planning range: $0.10–$0.50/cwt, or $32 to $162 million statewide — $26 to $128 per cow

Now scale it to your barn. Your cows × your annual lbs/cow ÷ 100 = your cwt. Multiply by the range.

  • 300 × 25,600 = 7,680,000 lbs = 76,800 cwt
  • Anchor: 76,800 × $0.20 = $15,360 … × $0.35 = $26,880
  • Wider range: 76,800 × $0.10 = $7,680 … × $0.50 = $38,400
  • Cross-check on the per-cow method: 300 × $51 = $15,300 … 300 × $90 = $27,000 ✓

Call it $15,300 to $27,000 on the anchor for a 300-cow herd. Not catastrophic. Not nothing, either.

Why Order 30 Feels a Class III Move Harder Than Anywhere Else

That figure is a Class III number, not a mailbox number. What reaches your statement is the blend price — Class III plus your order’s producer price differential — and the PPD is where most tariff coverage stops paying attention.

Wisconsin milk pools mostly under Federal Order 30, the Upper Midwest. USDA AMS publishes every order’s PPD monthly, and Order 30’s 2026 run tells you something no other order’s does.

Federal OrderJanFebMarAprMayJun2026 YTD
Upper Midwest (30)$0.46$0.58$0.50$0.61$0.69$0.87$0.64
Northeast (1)$2.05$2.37$2.66$3.43$4.42$6.22$3.54
Mideast (33)$1.33$1.50$1.58$2.32$3.01$4.77$2.35
Central (32)$1.16$1.39$1.49$2.10$2.70$3.59$2.10
California (51)$0.26$1.10$1.06$1.46$1.84$2.66$1.38
All markets combined$1.14$1.49$1.48$1.96$2.44$3.48$2.02

Source: USDA AMS, “2026 Uniform Producer Price Differential — Monthly and Year-to-Date,” dollars per cwt, base zone. Order 30’s base zone is Cook County, Illinois. The Order 30 market administrator’s own February and March computation statements independently confirm $0.58 and $0.50.

Order 30 runs the smallest PPD of any federal order — 64 cents year-to-date against $3.54 in the Northeast, more than five times higher. That’s not a disadvantage. It’s a structural fact about a market that pools overwhelmingly into cheese.

And it cuts the way most people don’t expect. A small PPD means your blend price tracks Class III closely. Order 30’s June 2026 statistical uniform price came in at $16.85/cwt — Class III plus that 87-cent differential — down $0.76 from May and $2.25 below the year before.

The Class III Rule of Thumb

  • A 1¢/lb drop in cheese pulls Class III down roughly $0.10/cwt
  • A 1¢/lb drop in dry whey pulls Class III down roughly $0.06/cwt
  • Class III + PPD = your statistical uniform price. In Order 30 that PPD has run 46 to 87 cents all year, so Class III moves arrive nearly intact
  • The PPD is announced on or before the 14th day after month-end — a date most producers never put on a calendar
  • Extension’s range assumes a sustained tariff, and it was built before the September 15 expansion. Four-plus consecutive data points is the honest threshold before calling anything a trend

So a Wisconsin herd doesn’t get much cushion from the pool. A Northeast herd riding a $3.54 differential built on Class I utilization does. Same tariff, same Class III formula, different insulation — and Wisconsin has the least of it.

One thing complicates any single month: depooling. Manufacturing milk in Classes II, III and IV can be kept out of the pool under each order’s qualification rules, which distorts the differential. It’s real and active in 2026 — Iowa State Extension documented aggressive Class IV de-pooling in the Central order in March, where pooled volume fell to 1.35 billion pounds from more than 1.50 billion a year earlier. Different order than Wisconsin’s, same mechanism available.

What the whole thing costs you also depends on your balance sheet. A debt-free 300-cow operation absorbs $27,000 as a rough year. The same herd carrying a heifer barn and a robot note treats it as the difference between covering the payment and calling the lender.

Worth remembering too: cheese and whey prices move on Chinese demand, EU output, and CME activity — not just Canadian buying.

Why the Same Tariff Moves an Ontario Cheque by Zero

Everyone reading “dairy farmers hit by tariffs” assumes the hit lands symmetrically. It doesn’t, and the reason is plumbing, not politics.

USDA’s National Dairy Products Sales Report put 40-pound cheddar blocks at $1.6140/lb for the week ending August 29, 2026 — down 1.1 cents from the prior week. Run that single week through the coefficient and you get about $0.11/cwt on Class III. That’s a coincidence of arithmetic, not the same figure as the floor calculation above — this one is a single week’s price move, arriving in an Order 30 cheque nearly whole. August 2026 Class III landed at $16.64/cwt, up $1.12 from July; Class IV at $17.36, down $0.98.

Canada’s farmgate price doesn’t work like that at all.

Running the Numbers: What Actually Reaches an Ontario Cheque Walk the Canadian Dairy Commission’s National Pricing Formula component by component and look for the tariff input:

  • Component 1: 50% of the change in cost of production, from a producer cost survey — no tariff input
  • Component 2: 50% of the change in the Consumer Price Index — no tariff input
  • Result, February 1, 2026: +2.33%, on a cost-of-production figure of $92.82 per standard hectolitre
  • Processor make allowance — the first place an import cost would register — held explicitly unchanged in the February 2026 butter support-price adjustment

There’s no line in that calculation where a processor’s import bill enters. The tariff cost sits with the processor. It doesn’t get an invitation into the room where your price gets set.

But don’t confuse a protected pricing formula with immunity. The P5 boards don’t defend producer income by moving the base price. They move volume — and volume is the lever that actually responds to a market shock.

Run it on a modelled 150-cow Ontario herd. At roughly 1.1 kg butterfat per cow per day, that’s 165 kg BF/day of quota. At the P5 policy cap of $24,000/kg BF, the quota asset alone carries about $3.96 million. None of that moves on a tariff. What moves is days.

The P5 boards announced conventional incentive days for fall 2026 on a non-cumulative basis — one day in each of August, September, October and November, explicitly to complement the SNF/butterfat payment policy change and pull more milk into a system short on protein (Milk Producer, Dairynomics, April 28, 2026). Four days. For that 165 kg BF/day herd, that’s 660 kg of butterfat in additional saleable production this fall.

The lever runs both directions. DFO waived Ontario’s over-quota penalty for April 2026 outright as protein demand outran supply, then reinstated it May 1. Right now the days point up — the system wants milk.

If the September 29 U.S. ban strands Canadian dairy that would otherwise have crossed south, the boards will pull back incentive days first. But watch the pool: any displaced volume forced into Class 4(m) or Class 5 surplus disposal erodes the P5 pooled blend price, taking pennies off your net payout without ever touching the CDC base price.

The trade at stake is small — $432.7 million moving south in 2025 against $1.3 billion coming north. But a ban is a different animal than a duty, and volume is where a Canadian producer should be watching.

We priced the access side of this fight at a nickel back in August, before any of it went live: The Access Fight Is Worth 5¢. Class III Already Took 64¢. And the component squeeze already running underneath P5 cheques is broken down in SNF butterfat ratio: $2/kg below 2.14 in P5.

Why Is Wisconsin More Exposed Than Other States?

Concentration — and USDA’s own production data shows it cleanly.

MetricFigureSource
U.S. total cheese output (July 2026)1.26 billion lbs (+2.1% YoY)USDA NASS
Wisconsin cheese output (July 2026)308.9 million lbs (+2.4% YoY)USDA NASS via Cheese Reporter
Wisconsin share of U.S. output~24.5%Calculated
Wisconsin ag/food exports to Canada (2025)$1.38B of $3.99B globalWisconsin DATCP
U.S. cheese exports to Canada (2025)51.5 million lbsUSDEC / WCMA

Wisconsin leads the nation in cheese and makes roughly a quarter of all of it. Canada takes about 35 per cent of the state’s total agricultural export value. So when Canada put 25 per cent on cheese, it aimed at the product line carrying the bulk of Wisconsin’s milk, in the state that has the most of it — and, per that PPD table, in the order with the least pooling cushion. The September 15 expansion widens the same channel from the other direction.

One figure circulating this week deserves a caution flag before it reaches a lender conversation. DATCP reports $468 million in Wisconsin dairy exports for 2025, up 13.98 per cent from $406 million. Whether that’s Canada-only or all-destinations isn’t resolvable from the public page, which presents dairy in a product table and Canada in a separate country table. Confirm the destination breakdown with DATCP directly before you build anything on it.

Ohio’s $17.5 billion in 2025 exports to Canada gets cited in this fight too, and it’s real. But Ohio Capital Journal reporting from August 28, drawing on Scioto Analysis, a private economic consultancy, describes it as dominated by machinery and auto parts. It isn’t a dairy number.

How Solid Is the Legal Ground Under Any of This?

Thin, and that changes how hard you commit to the number.

The U.S. tariffs run on Section 338 of the Tariff Act of 1930 — the Smoot-Hawley Act. According to Georgetown legal scholars Peter Harrell and Jennifer Hillman, it has never actually been used to impose tariffs. It was last seriously considered against Spain in 1932 and China in 1949.

Ninety-six years on the books. No president had ever reached for it.

Ryan Majerus, a partner at King & Spalding and a former U.S. trade official, told the Associated Press in late August: “This law is literally a blank canvas because it’s never been litigated.”

Ilya Somin, a law professor at George Mason University who was involved in the litigation that overturned the IEEPA tariffs, told The Canadian Press on August 26 that a challenge is coming — “It’s just a matter of exactly when and by which groups.”

As of September 9, nobody has filed, and lawyers are still hunting for an importer with standing. Part of the reason is arithmetic: the Section 338 tariffs cover about 5 per cent of Canada’s exports to the U.S., far narrower than the 2025 worldwide tariffs, which means fewer companies can claim injury. The Liberty Justice Center, a libertarian legal advocacy group that won the IEEPA challenge, has been looking for businesses willing to sue.

Canada has also gone to the forums that exist for this — WTO consultations, with a CUSMA Chapter 31 panel still available.

You’re modelling an annual cost on a foundation nobody has tested in court. Plan around it. Don’t carve it into a five-year budget.

The 30/90/365-Day Playbook for Export-Exposed Herds

30-Day Actions

  • Put September 15 and September 29 on the wall. The cheese list widens on the 15th; the U.S. dairy import ban lands on the 29th. Requires: a call to your plant asking which of their SKUs sit on the expanded annex. Trigger: if your processor’s Canada-bound product appears on the September 15 additions, your exposure runs higher than Extension’s model captures. Where it backfires: annexes get amended — verify against the published list, not a news summary.
  • Find your PPD, then find your statistical uniform price. The market administrator publishes it on or before the 14th day after month-end. Requires: five minutes and your order number. Trigger: Order 30’s PPD ran 46 to 87 cents through June. If yours sits in that band, assume a Class III move reaches your cheque nearly whole and size the tariff range accordingly. At $3.54 year-to-date in the Northeast, discount it. Where it backfires: a depooling month badly distorts the differential. One reading isn’t a pattern.
  • Watch cheddar blocks against the August 29 print. Trigger: two consecutive weekly NDPSR reports with 40-pound blocks closing below $1.55 — roughly six cents under $1.6140 — is a signal worth acting on. Where it backfires: over-reading the first release. One data point isn’t a trend, and you’ll be tempted.

90-Day Actions

  • Ontario and Quebec producers: watch incentive days, not just the price announcement. The CDC held its 2025 pricing consultations on October 15 and announced the adjustment at 1 p.m. on October 31, effective February 1. Requires: tracking P5 board messages alongside the CDC release. Trigger: the fall schedule currently runs one non-cumulative conventional day in each of August through November. Any retraction of those days, or a tightened over-quota penalty, is your volume signal — and it moves before any base price does. Where it backfires: incentive days respond to protein demand as much as trade. Don’t attribute a change to tariffs without reading what the boards actually said.
  • Get the share of your plant’s volume that rides on tariffed lines. Neither country tariffs butter, fluid milk, cream, yogurt or ice cream; cheese, whey, powders and protein concentrates are all on the list. Requires: a conversation with your fieldman about product mix, not contract terms. Trigger: if more than half your plant’s throughput runs into cheese and whey, treat the Extension range as a floor rather than a midpoint — that’s the Order 30 profile, and it’s why Wisconsin sits where it does. Where it backfires: today’s exemption isn’t permanent. September 8 showed how fast a list grows.

365-Day Moves

  • Treat the legal fragility as a planning variable, not a reason to ignore the math. The tariffs are in force and costing money now, regardless of what a court eventually does. Requires: holding two ideas at once. Where it backfires: betting a capital decision on the assumption this gets struck down, on a timeline nobody has offered.
  • Watch for the opportunity signal. If blocks hold above $1.60 through both the October 5 and November 5 AMS releases while Class III stays within about fifty cents of the August $16.64 mark, this fight lived and died inside processor margins. That’s your cue to stop pricing tariff risk into next year’s capital plan. Requires: patience through two full release cycles. Where it backfires: mistaking two quiet months for a resolved dispute — the escalation pattern is running on a two-week clock.

The quota squeeze already hitting Ontario producers independent of any tariff is covered in Canada’s Cheese Quota Filled 99% in 2024. Your DFO Exchange Just Got Cancelled, and a parallel tariff story is running in beef — Beef Tariff Waiver 2026: Dairy Has 90 Days.

Why the Untariffed Product Is the One to Watch

Go back to the butter, because it’s the cleanest illustration of how this pressure actually moves.

The U.S. Dairy Export Council reported on February 24, 2026 that Canada remained the top U.S. butterfat buyer in 2025, with U.S. butterfat exports to Canada up 50 per cent — a gain of 14,225 metric tonnes. Over the same stretch, Canada’s share of total U.S. butterfat export volume fell from 62 per cent in 2024 to 35 per cent in 2025, as U.S. sellers moved product elsewhere. Rising volume into a shrinking share.

No duty was involved in any of that. Demand relationships shift before customs schedules do, and they don’t announce themselves in a Federal Register notice.

Which is the trade-off at the centre of this story. On the Wisconsin side you get a number you can calculate, arriving through the thinnest pooling cushion in the country — 64 cents year-to-date against $3.54 in the Northeast — sitting on a legal foundation nobody has tested in court. On the Ontario side you get a base price insulated by a formula that was never built to notice a tariff, defended by a volume lever that moves quietly and gets announced as days, not dollars.

You gain visibility on one side. You gain insulation on the other. Nobody gets both, and neither one is the same as protection.

So pull your last three milk cheques and find two numbers on them: your PPD, and your statistical uniform price. Then make the call you can still make before September 15 — does your plant ship cheese or whey into Canada, is any of it on the expanded annex, and what has that volume done since August 22?

Key Takeaways

  • Extension’s $51 to $90 a cow is a Class III number, not a mailbox number — but with Order 30’s PPD running 46 to 87 cents against $3.54 in the Northeast, Wisconsin gets less pooling cushion than anyone, so it arrives nearly whole.
  • Pull your PPD and statistical uniform price off your last three cheques. If your differential sits in that Order 30 band, size the tariff hit at the anchor range; if you’re riding a $3-plus differential, discount it hard.
  • Ontario’s zero is real but only through the pricing formula. The CDC runs on cost of production and CPI with no tariff line anywhere, so if pressure comes it shows up as fewer incentive days — not a lower base price, and not with any warning.
  • Two deadlines before month-end: the cheese list widens September 15 and the U.S. bans Canadian dairy September 29. Call your plant about Canada-bound cheese and whey volume before the 15th, not after.

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.

Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.

NewsSubscribe
First
Last
Consent

The Access Fight Is Worth 5¢. Class III Already Took 64¢.

Canada’s dairy tariffs land September 8: what the fight is actually worth on your herd — and what already cost you four times more

Darin Von Ruden is a third-generation dairy farmer near Westby, Wisconsin, and president of the Wisconsin Farmers Union, a producer advocacy group. On August 25, he told WEAU what he’s watching for, and it wasn’t the tariff itself. “A month from now, six weeks from now, when those milk trucks start coming, and we’re hit with that probability that we won’t be selling much dairy product into Canada, just makes more of a surplus in the United States, which always drops price.”

Surplus. That’s the mechanism, and it’s the part the trade headlines keep skipping. Canada’s counter-tariffs on U.S. dairy take effect at 12:01 a.m. on September 8, 2026 — 50% on milk and cream powders, whey and milk protein concentrates, casein; 25% on cheese and curd. And the Canadian market access the U.S. is fighting to open? Smaller than the headlines suggest.

What Actually Got Signed, and What It Covers

Three things stacked up this summer, and they don’t mean what the coverage implied.

The USMCA hit its first mandatory joint review on July 1, 2026, under Article 34.7. USTR Ambassador Jamieson Greer said the U.S. “did not agree to renew the USMCA in its current form.” That reads as the deal died. It didn’t — the agreement stays fully in force, with annual reviews now running through 2036, per White & Case’s client alert dated July 1, 2026. Nothing about your milk cheque changed that day.

On July 20, three proclamations followed under Section 338 of the Tariff Act of 1930. Proclamation 11047 is the dairy one, adding 50% duties on Canadian dairy ingredients — milk and cream powders, whey, milk protein concentrate, casein, lactose. Not retail milk. Not the cheese in a grocery cooler. Inputs. Those went live August 22 after a three-day delay, once talks in Washington collapsed on August 21.

Canada’s answer, published by the Department of Finance and updated August 26, matches dollar for dollar across $27.6 billion in U.S. goods — dairy alongside steel, appliances, agricultural equipment, pulp and paper, and electronics. The dairy lines are specific: HS 0402 milk and cream powders at 50%, HS 0404 whey and whey protein concentrate at 50%, HS 3501 casein at 50%, HS 3502.20 milk albumin and whey protein concentrates at 50%, HS 3504 milk protein substances at 50%, and every named cheese category under HS 0406 at 25% — cheddar, mozzarella, brie, gouda, parmesan, provolone, havarti, Swiss, gruyère, camembert, romano. Both within and over access commitment, on every one of them.

HS codeProductSurtaxWho feels it first
0402Milk and cream powders50%Powder plants and co-op marketing arms
0404Whey and whey protein concentrate50%Cheese-plant whey streams, ingredient buyers
0406All named cheeses (cheddar, mozzarella, gouda, Swiss)25%Cheese exporters — Canada’s largest U.S. dairy line
3501 / 3502.20Casein; milk albumin, whey protein concentrates50%Ingredient processors on both sides of the line
3504Milk protein substances50%MPC and protein-blend manufacturers
Not listedSemen, embryos, livestock geneticsNoneConfirm your own HS codes with a customs broker

How Much Is the Access Fight Actually Worth to You?

Here’s the math, assumptions on the table, because the number only means something if you can check it against your own herd.

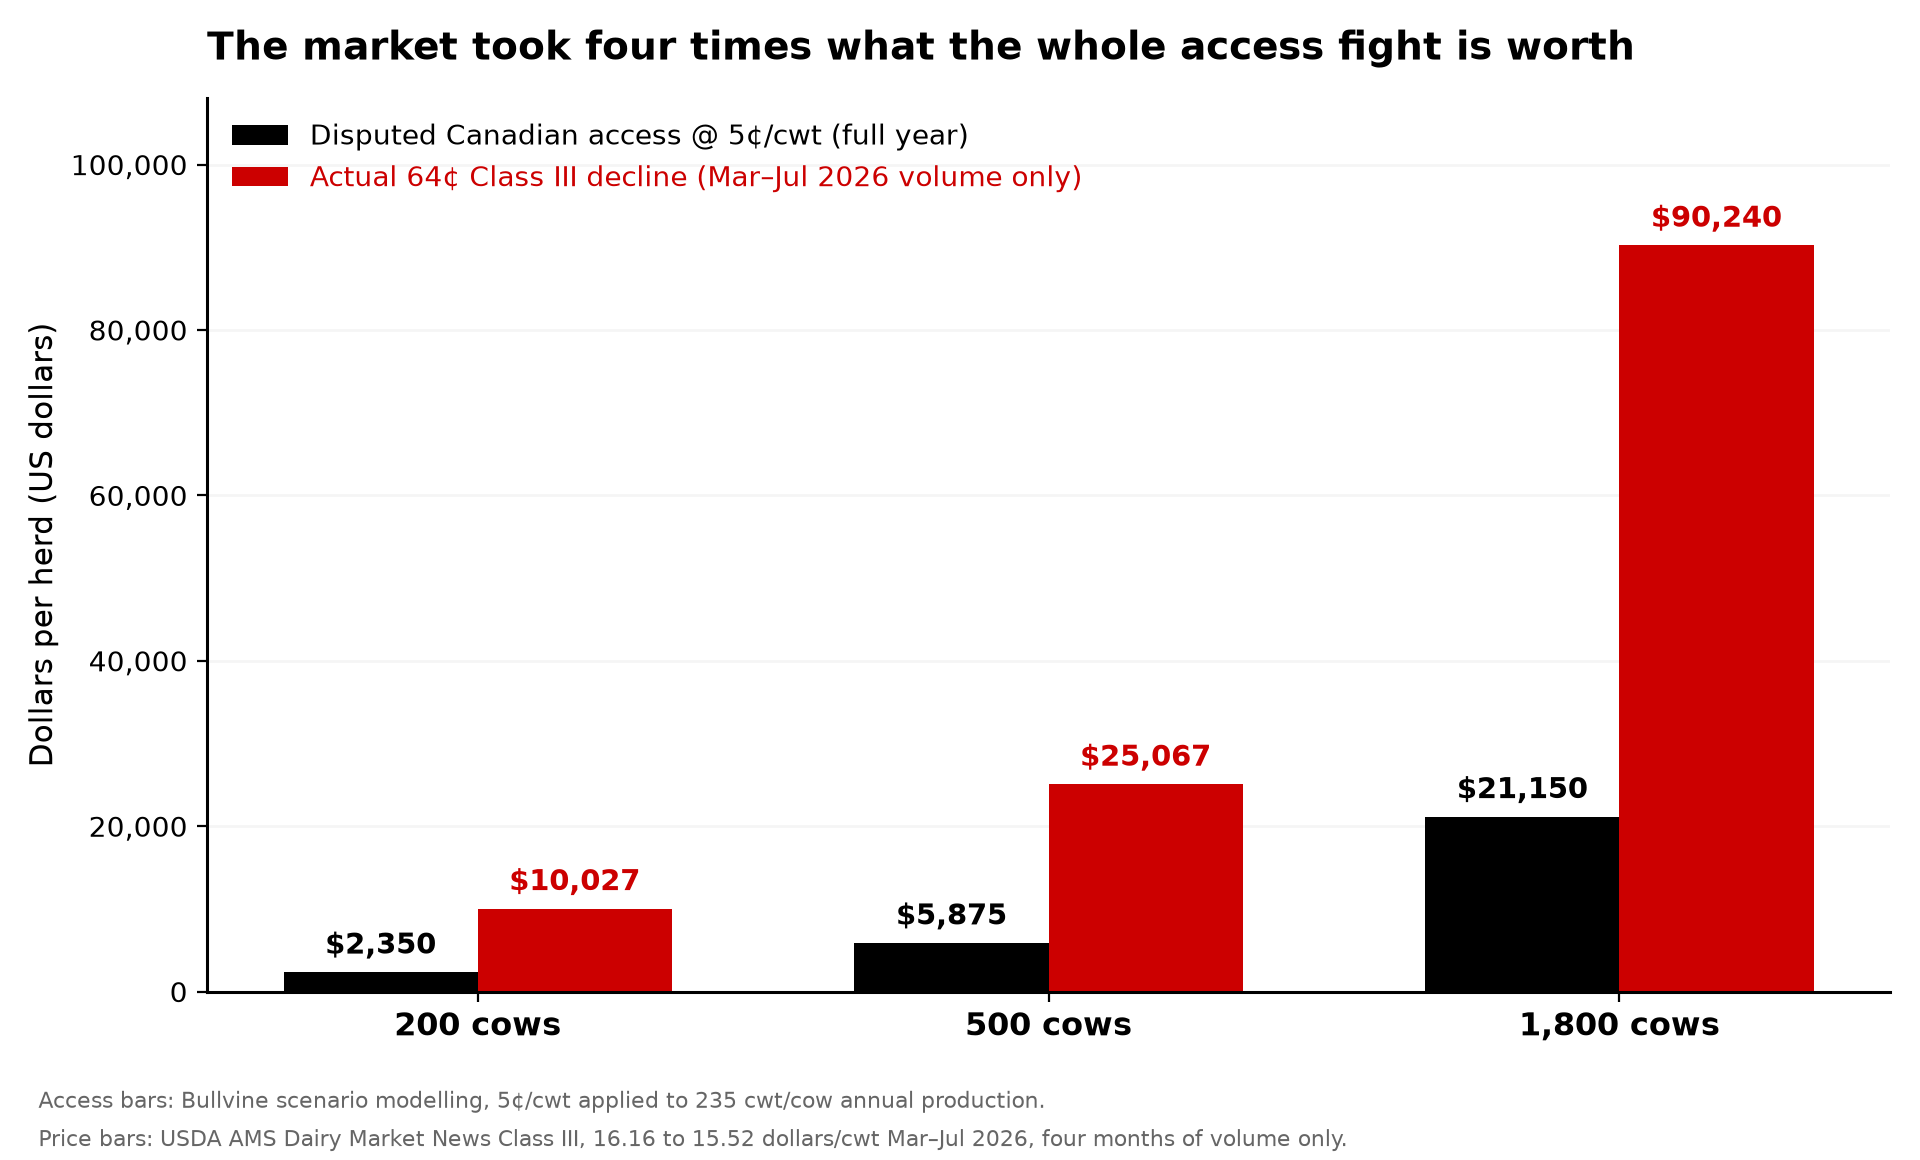
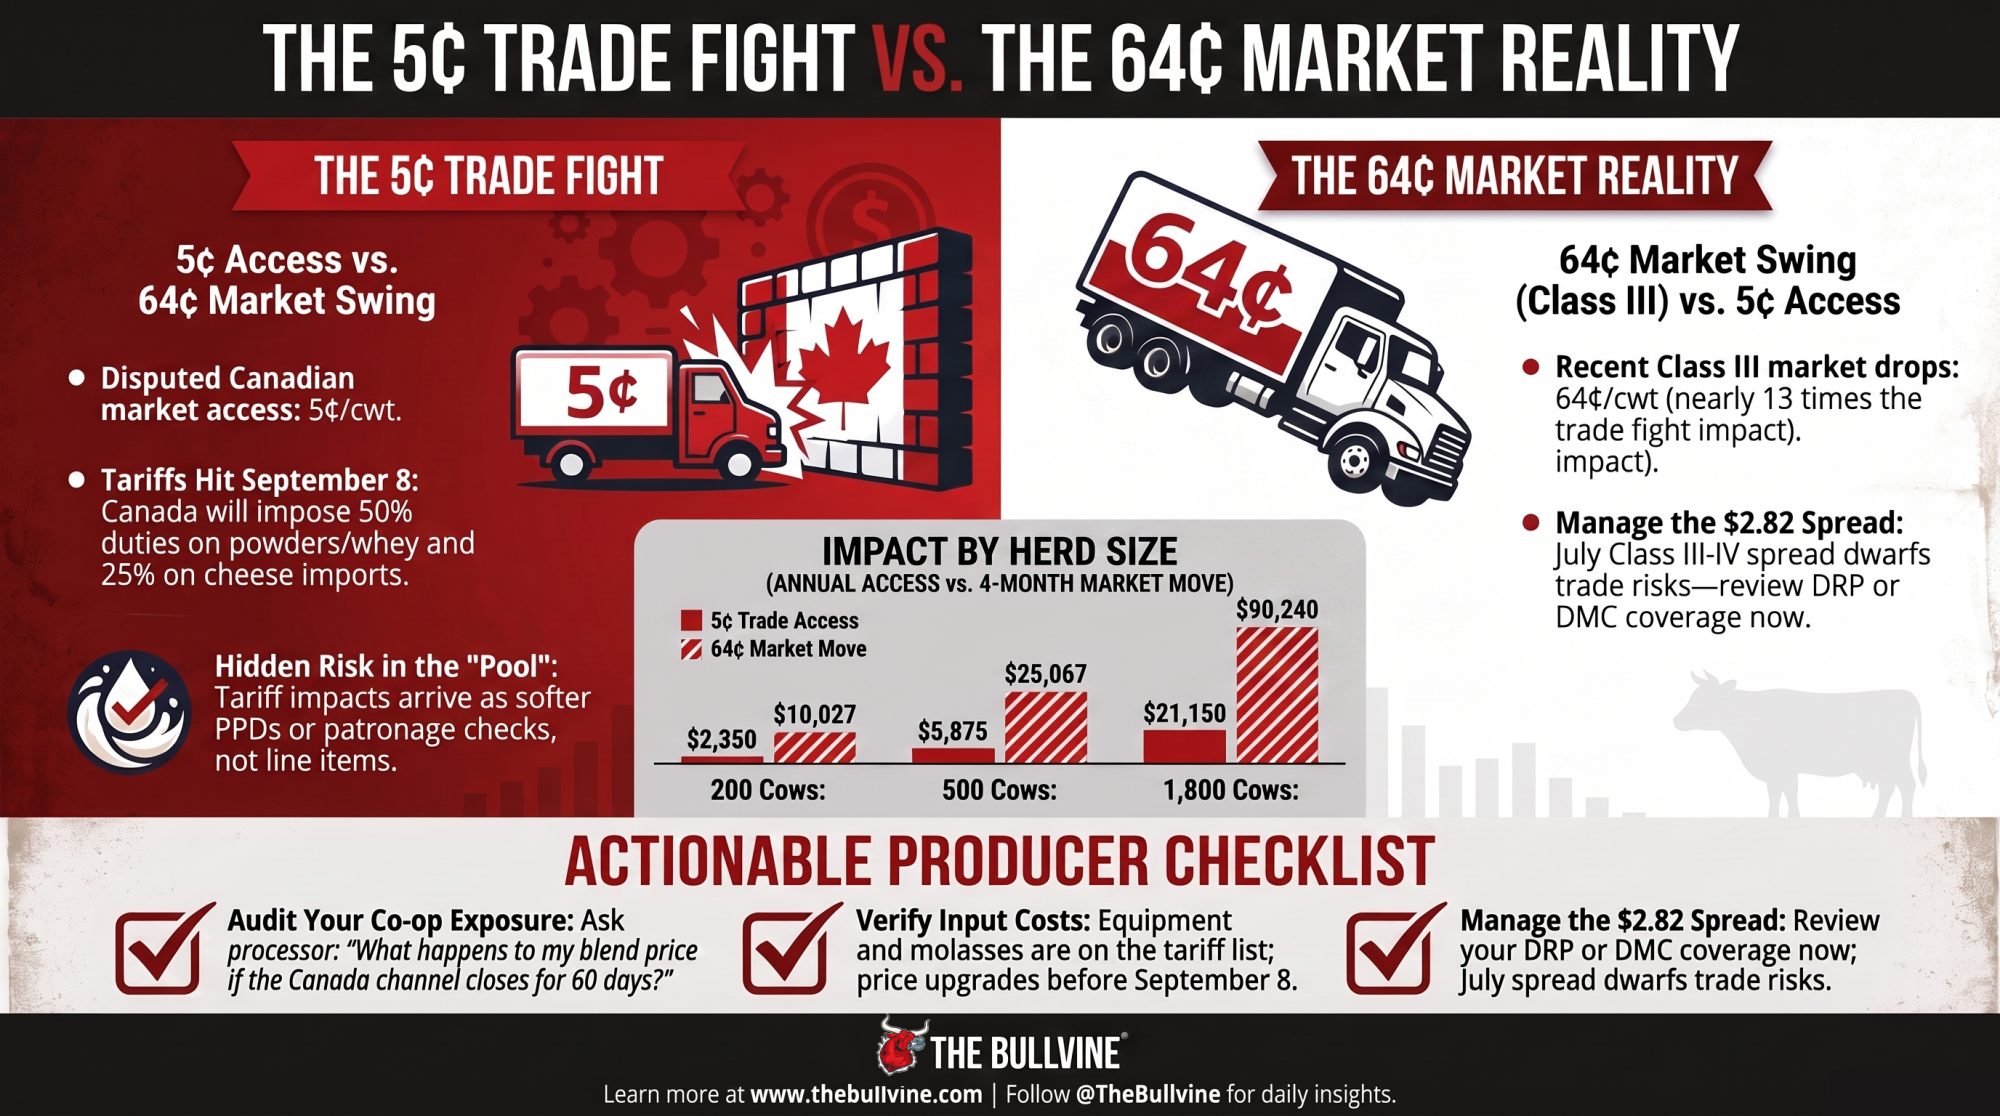
Using USDA Foreign Agricultural Service trade data, The Bullvine’s own scenario modelling puts the value of fully enforcing the disputed Canadian dairy access at roughly 5¢/cwt nationally. Model your herd at 235 cwt per cow annually — that’s our stated assumption, roughly 23,500 lbs, and you should substitute your own rolling herd average. Then set the disputed access beside what Class III actually did between March and July of this year: $16.16/cwt down to $15.52, a 64¢ drop over four months, per USDA AMS Dairy Market News.

Herd sizeAnnual productionAccess @ 5¢/cwt (year)Actual 64¢ Class III move (4 months)
200 cows47,000 cwt$2,350$10,027 on 15,667 cwt
500 cows117,500 cwt$5,875$25,067 on 39,167 cwt
1,800 cows423,000 cwt$21,150$90,240 on 141,000 cwt
Per cwt235 cwt/cow assumed$0.05$0.64 — 12.8x the access value

Access column: 5¢/cwt Bullvine scenario modelling applied to annual production at 235 cwt/cow. Price column: the actual 64¢ Class III decline applied to four months of production only — matching the window the price move covers, not annualized. Assumes even monthly production; real herds swing seasonally.

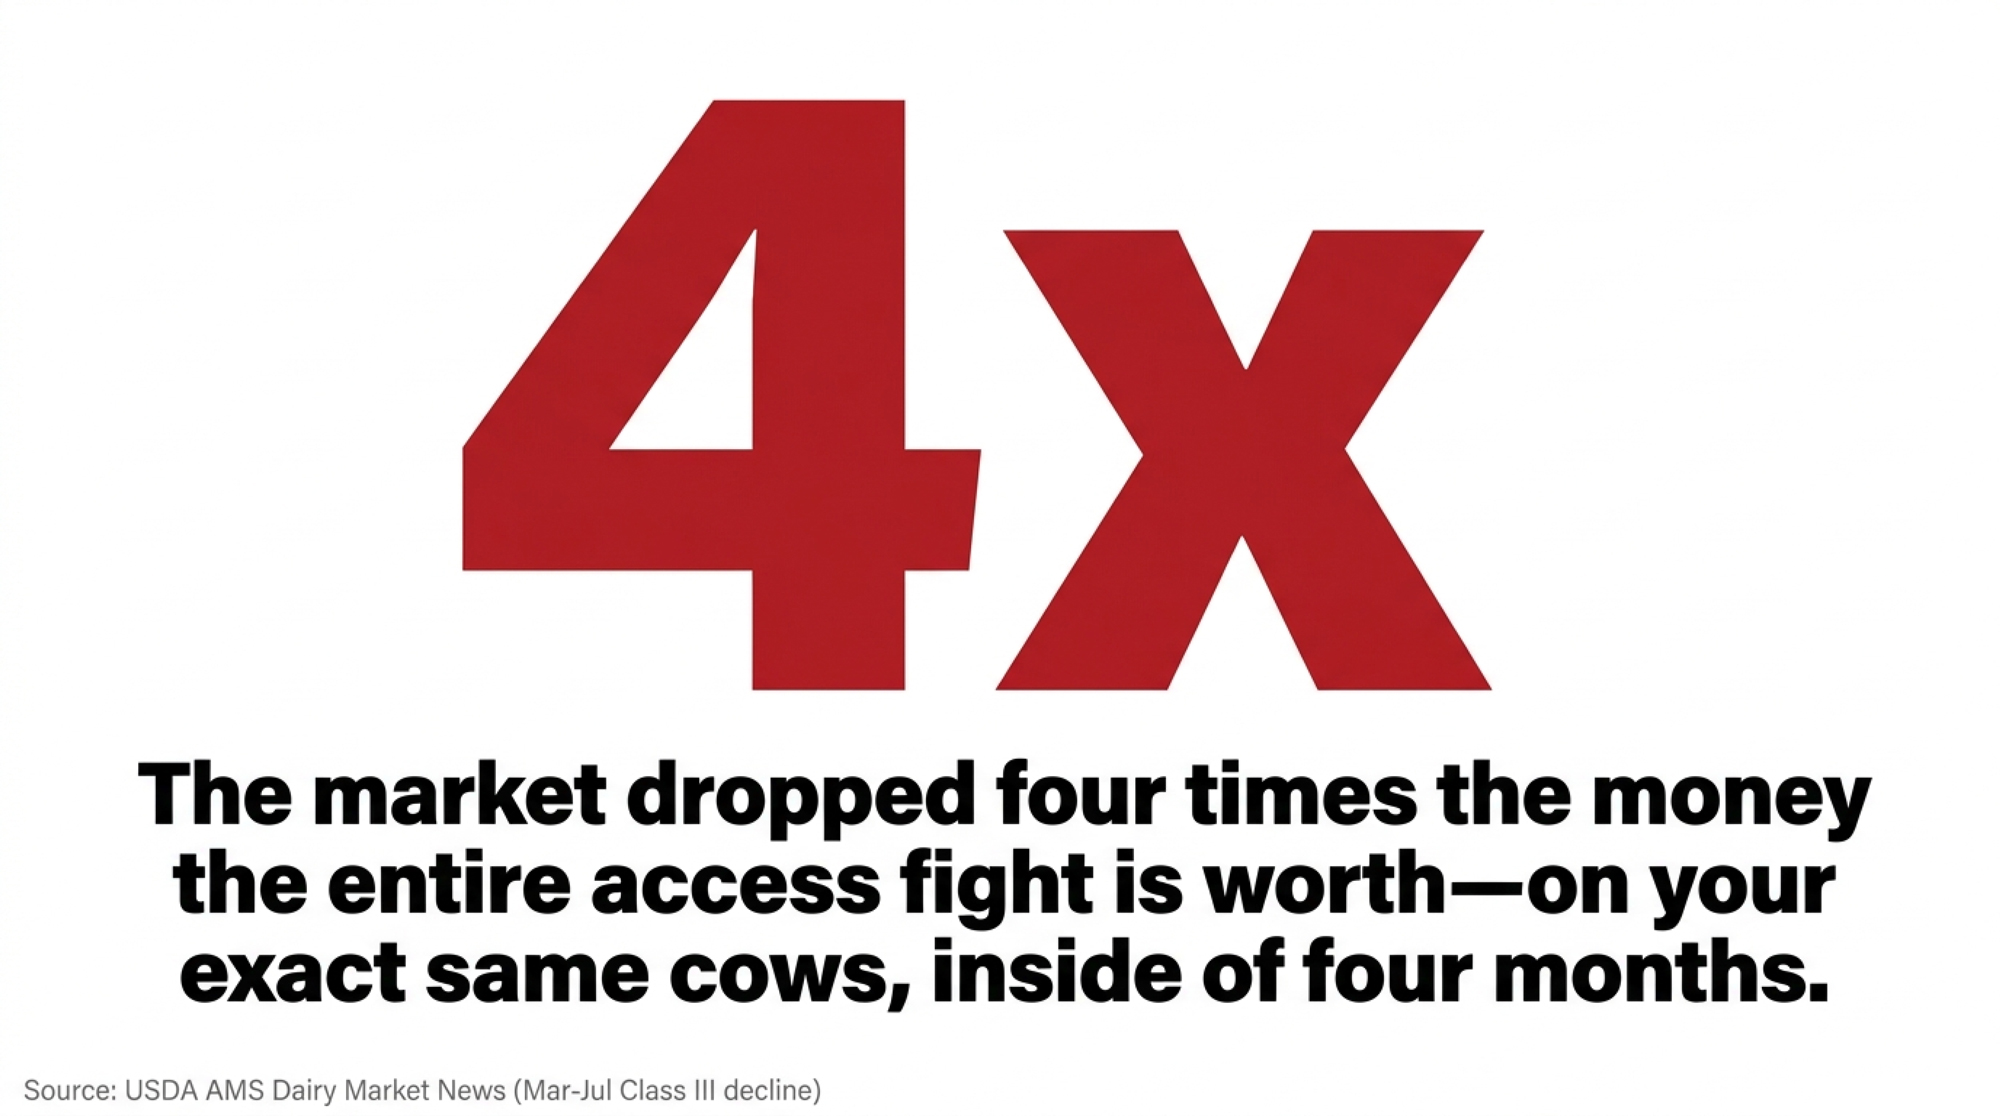
Read across any row. The market moved more than four times the money the entire access fight is worth, on the same cows, inside four months. Where does your breakeven sit right now? For most operations, the honest answer has very little to do with Canada.

That 5¢ figure is a scenario, not a published USDA number. We built it, and we’re labelling it. No government agency or land-grant university publishes a per-cwt dollar figure for unrealized USMCA dairy access, which is exactly why the number carries its label every time it appears.

One Law and One Clause Nobody’s Pricing In

Two structural facts explain why this won’t resolve the way the rhetoric implies.

The first is a statute. Bill C-282 — amending the Department of Foreign Affairs, Trade and Development Act — received Royal Assent June 26, 2025, per Parliament of Canada’s LEGISinfo record. It bars Canada’s Foreign Affairs Minister from committing to expand supply-managed dairy quotas or cut over-quota tariffs in trade negotiations. That’s not a posture a government softens under pressure. It’s a law Parliament would have to unwrite. U.S. producers waiting for Canadian negotiators to cave eventually are waiting on a law to change, not a mind.

The second is the retailer clause, and it’s the part that gets lost in the political coverage. Under Canada’s CETA agreement with the European Union, EU cheese enters through a retailer-eligible quota of roughly 16 to 17.7 million kilograms, per Global Affairs Canada’s TRQ notice. Under USMCA, U.S. cheese quota goes to processors and distributors — retailers excluded. The Globe and Mail reported July 20, 2026, that this asymmetry appears in Proclamation 11047’s own stated rationale. That gap is the actual legal complaint underneath the politics.

Access featureU.S. cheese under USMCAEU cheese under CETAWhy it matters at farm level
Eligible channelProcessors and distributors onlyRetailer-eligible quotaRetail shelf access decides whether volume moves
Quota volume6,250 t (2025) to 7,113 t by Year 19About 16 to 17.7 million kgThe EU pool dwarfs the U.S. cheese TRQ
Over-quota tariffAbout 245% MFNPreferential under CETA245% is a wall, not a price
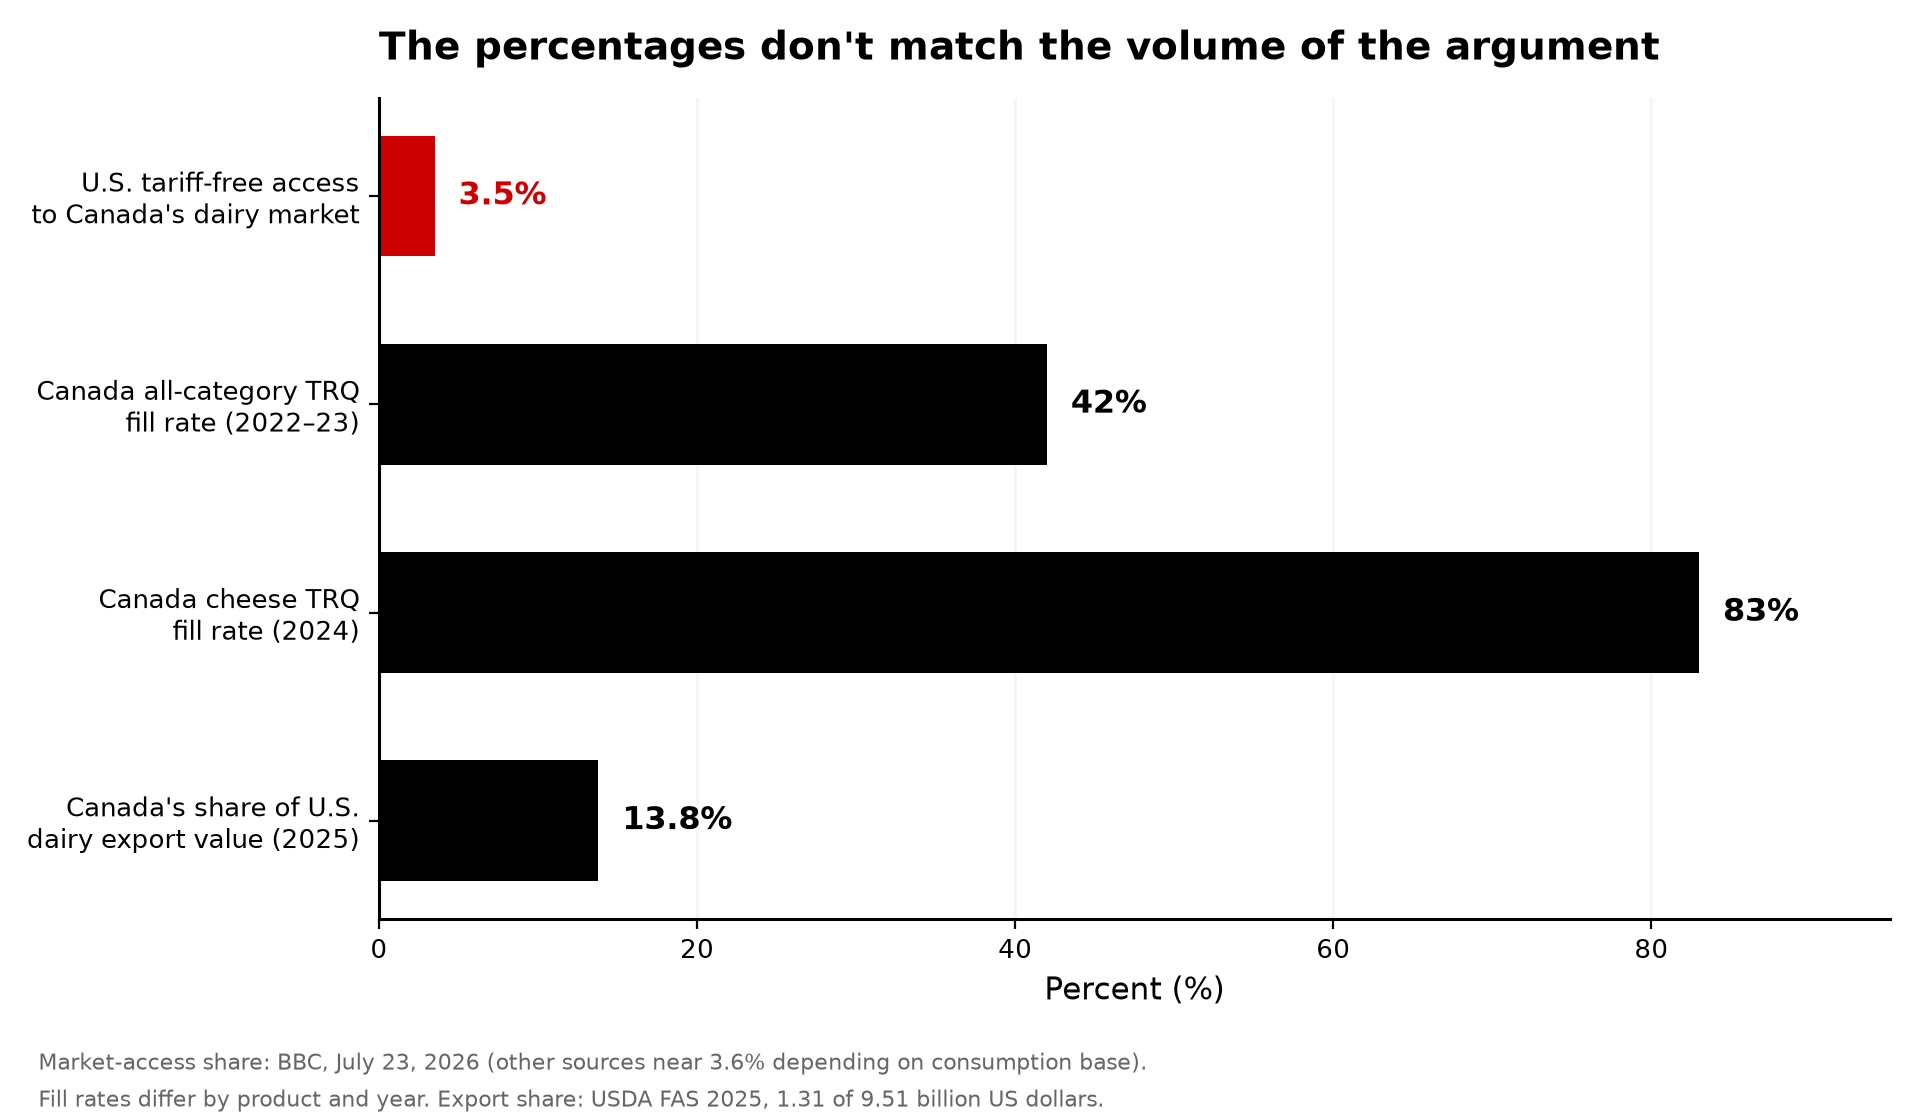
Fill performanceCheese ran 83% in 2024Not directly comparableAll-category fill near 42% in 2022–23 — ask which product
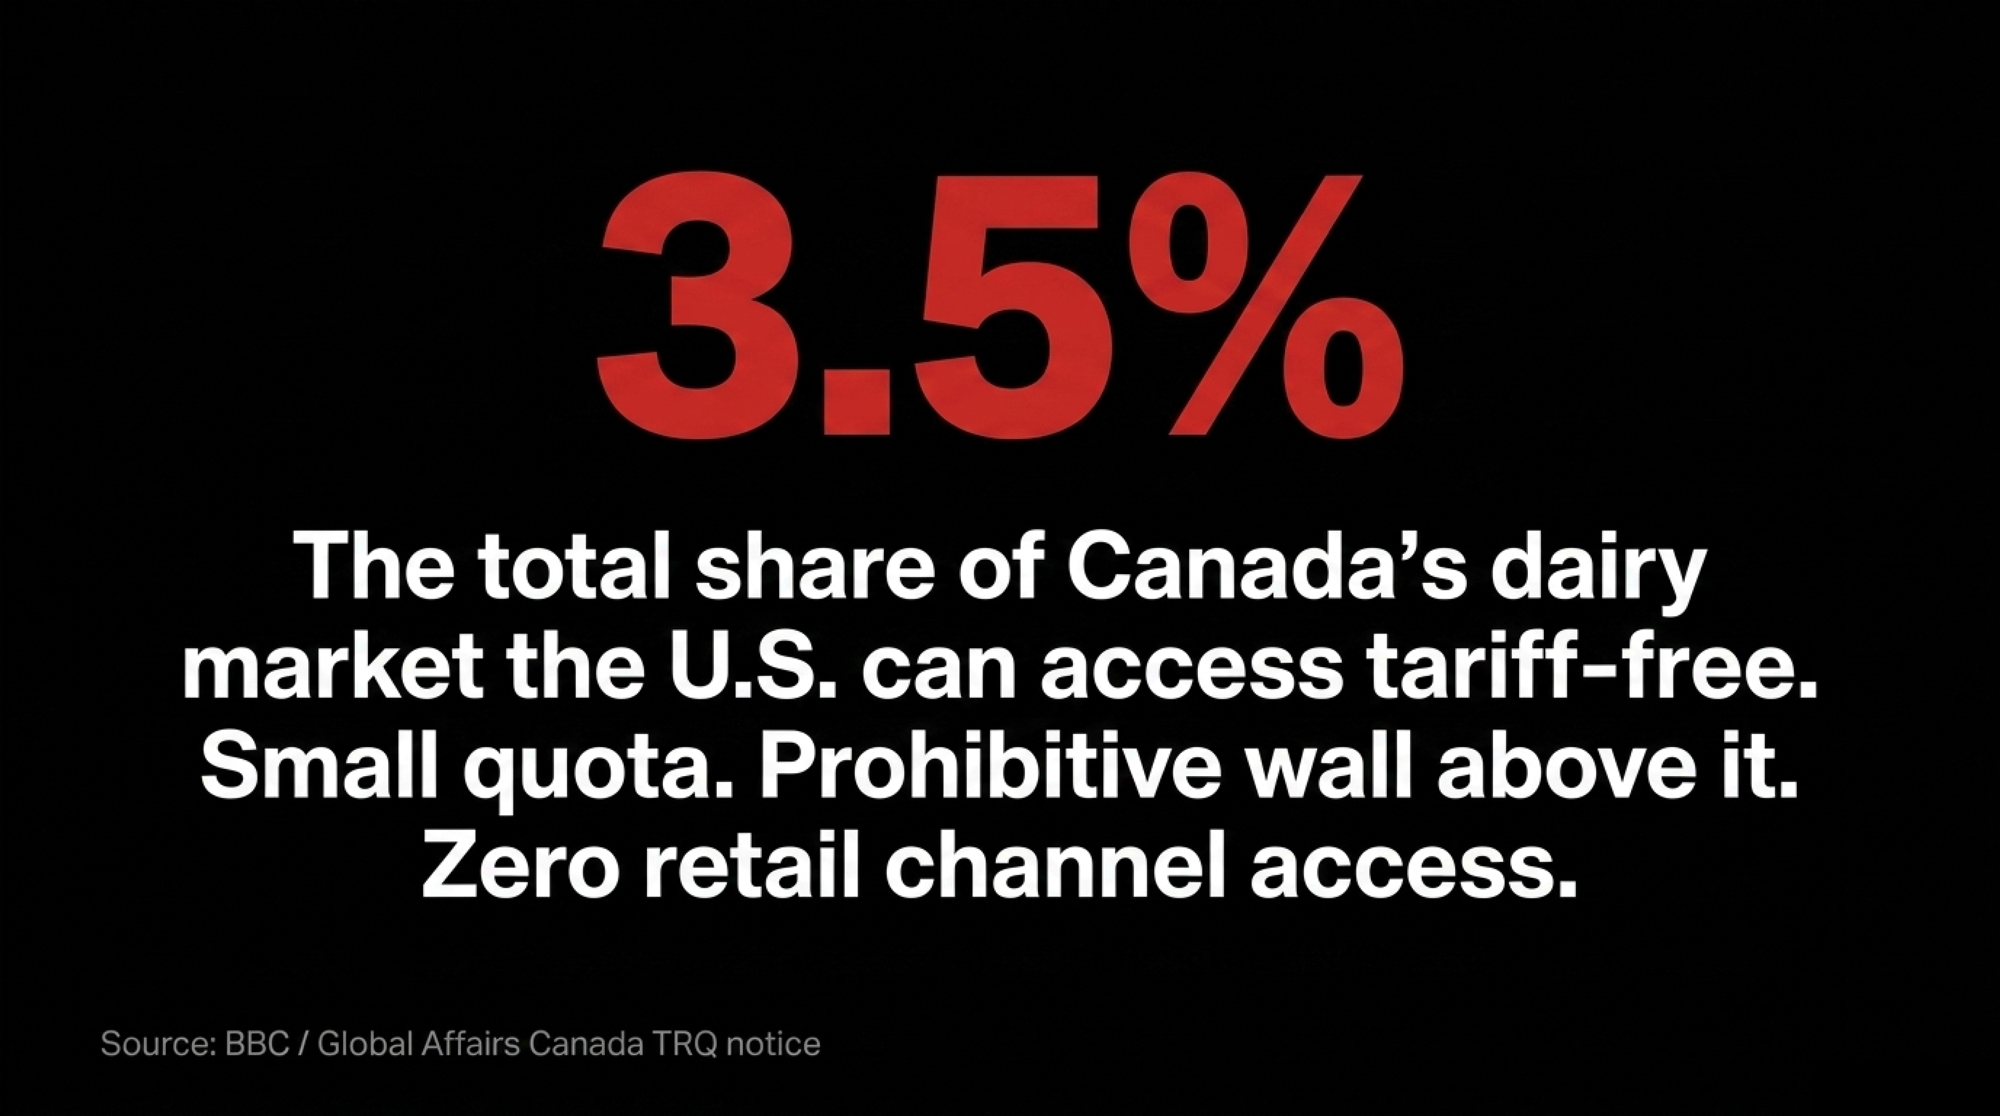
Total market accessAbout 3.5% of Canada’s marketLarger and retail-facingThe whole fight is over a sliver

Scale tells you the rest. UW-Madison Extension puts the 2025 USMCA cheese TRQ for U.S. exports at 6,250 metric tonnes, rising to 7,113 tonnes by Year 19, with an over-quota MFN rate near 245%. BBC reported July 23, 2026, that U.S. producers hold tariff-free access to about 3.5% of Canada’s market — other sources put it nearer 3.6%, depending on the consumption base used. Small quota, prohibitive wall above it, no retail channel. That’s the architecture, and it also explains why you’ll see Canadian fill rates quoted two contradictory ways: cheese ran 83% in 2024, while the all-category average sat near 42% in 2022–23. Both real. Different products.

Is Your Real Risk Even Visible in Your Milk Cheque?

Probably not, and that’s the part worth sitting with.

Most U.S. milk moves through Federal Milk Marketing Order pooling before it reaches a processor. Your cheque reflects Class I–IV utilization in your marketing order — not where the finished cheese or powder eventually sells. Export exposure lives downstream, at the plant or the co-op’s marketing arm. So your milk cheque is pooled. Your risk isn’t.

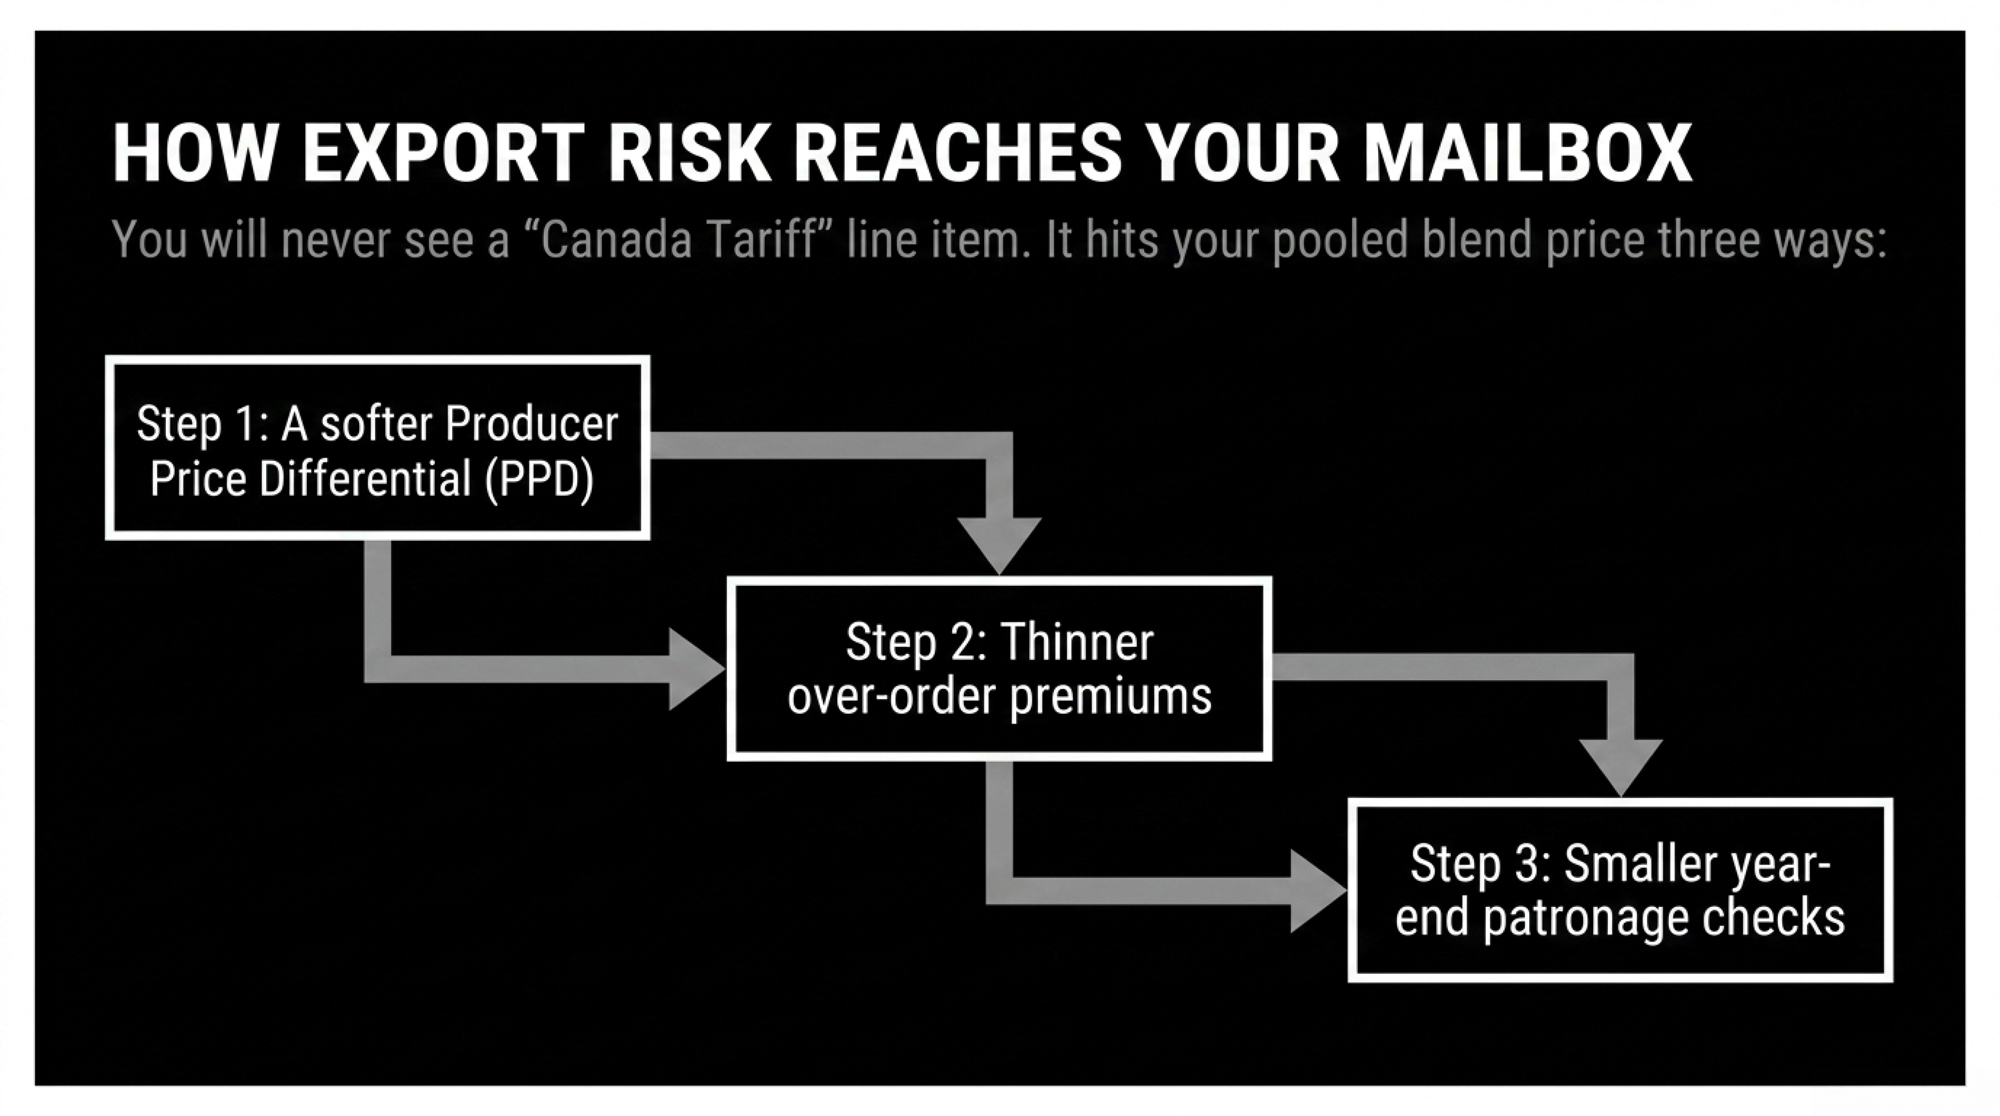
Here’s how that risk actually reaches your mailbox. You won’t see a line item that says “Canada tariff.” If your co-op takes a margin hit on powder or cheese it was moving north, that shows up in the blend — a softer Producer Price Differential, thinner over-order premiums, or a smaller patronage cheque at year-end. Same money, three degrees of separation, no label on it.

So ask your co-op or processor three things: how much of what you ship gets exported, how much of that goes to Canada, and what happens to your blend price if that channel closes for sixty days. No public dataset breaks this down at the plant level — we looked. That information sits in member communications, not government data, which means the only way to get it is to ask.

Options and Trade-Offs for Farmers

Pull the Finance Canada list and check your purchase orders—within 30 days. The document is public, free, and specific down to the tariff item. If you’re a Canadian producer buying U.S. cane molasses (HS 1703.10, 50%), polyethylene sacks and bags (HS 3923.21.90, 50%), or milk-protein inputs, it tells you exactly what changes on September 8. Costs you an hour and your purchase records. Here’s the part worth knowing: goods already in transit to Canada on September 8 are exempt, so what matters isn’t when you ordered — it’s whether the truck crosses before the clock runs out.

Quantify your Canada exposure before you react. Canada took $1.31 billion in U.S. dairy exports in 2025 out of $9.51 billion total, per USDA FAS — roughly 14%, second behind Mexico at $2.58 billion on the same dataset. Agriculture and Agri-Food Canada figures reported by the Western Producer on May 4, 2026 put butterfat and cheese at approximately CA$500 million of the CA$1.06 billion Canada recorded. So this concentrates in cheese and butterfat channels rather than spreading evenly across the industry. The catch is the pooling problem above — your own exposure isn’t visible in your own cheque.

The Class III–IV spread ran $2.82/cwt in July 2026, which is the real argument for reviewing your DRP or DMC coverage. That volatility already dwarfs anything this dispute realistically moves. It’s also the argument against buying coverage in a panic — a conversation with your risk advisor beats a reaction to a headline. Where this path fails: coverage priced off a news cycle tends to cost more than it protects. And the squeeze runs both directions on a farm, which is the part Von Ruden put plainly: “It’s a double edged sword that farmers deal with all the time, knowing that our price is lower, but going to the grocery store, buying milk, cheese, butter, ice cream, and having to pay more for it than we did two months ago.”

Agricultural equipment is on Canada’s list, so if you’ve got a parlour upgrade or a mixer order pending, price it against September 8 before you sign. That’s the tighter clock of the two cross-border paths. Genetics look clearer — semen, embryos, and livestock genetics don’t appear anywhere in Canada’s surtax list, and Proclamation 11047 covers dairy ingredient lines rather than breeding stock. But get your customs broker to confirm your specific HS codes instead of assuming the exemption covers your product.

Key Takeaways

For U.S. producers — export exposure and risk

  • If you don’t know your co-op’s Canada-export share, that’s a phone call this week, not a headline to react to.
  • If your co-op moves powder or cheese north, ask specifically what a sixty-day closure does to your blend price — the hit arrives as a softer PPD or a thinner patronage cheque, never as a tariff line item.
  • If your annual cwt × 5¢ comes to less than one Class III swing on your own herd, the access fight isn’t where your margin is going. Look somewhere else.
  • If you haven’t looked at DRP or DMC since spring, the $2.82/cwt Class III–IV spread in July is the reason to — not the tariff.

For Canadian producers — inputs and equipment

  • If you buy any U.S. inputs, check your next 60 days of purchase orders against the Finance Canada list before September 8.
  • If an order is already moving, find out whether it crosses before September 8 — goods in transit that day are exempt, so the shipping date, not the order date, is what counts.
  • If you’ve got a parlour upgrade or mixer order pending, price it against the September 8 date before you sign. Agricultural equipment is on the list.
  • If you’re financing quota in Ontario or Quebec at the capped CA$24,000/kg BF, this dispute isn’t what moves that number — provincial cap policy and pooled revenue are.

For both sides of the line

  • If someone quotes you a single Canadian quota fill rate, ask which product category and which year before you act. Cheese ran 83% in 2024; the all-category average was near 42% in 2022–23.
  • If you ship genetics either direction, get your customs broker to confirm your HS codes rather than assuming the exemption holds for your specific product.

Structural decline arguments make for good op-eds and bad forward contracts. The C.D. Howe Institute — which advocates market liberalization in its published policy work, so read it as a position rather than neutral data — argued in April 2026 that Canada’s supply management will eventually disappear on economic grounds. No source attaches a date to that. The next USMCA joint review is 2027. That’s the only clock in this story with an actual number on it.

Von Ruden is watching milk trucks, not press conferences. That’s the right instinct, and it points to the two numbers worth chasing this week — neither of them a tariff rate. What share of your co-op’s volume actually goes to Canada, and where does your rolling herd breakeven sit today? Stop trading on trade-war headlines and get both. We’re running the full per-cwt model by herd size and province, with assumption tables visible, in next week’s Bullvine Weekly — that’s where the barn math lives.

THE BULLVINE BARN MATH TOOL

Custom Herd Exposure Calculator

See what the 5¢/cwt Canadian market access fight is worth on your herd vs. your actual Class III price exposure.

cows
lbs/yr
$/cwt
$/cwt
Annual Canadian Access Value (@ $0.05/cwt)
$5,875
On 117,500 total annual cwt
4-Month Market Move (@ $0.64/cwt)
$25,067
On 39,167 cwt (4-mo window)
⚡
The Bottom Line: Your 4-month Class III market volatility is 4.3x larger than what the entire 12-month cross-border trade dispute moves on your cows.

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.

Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.

NewsSubscribe
First
Last
Consent

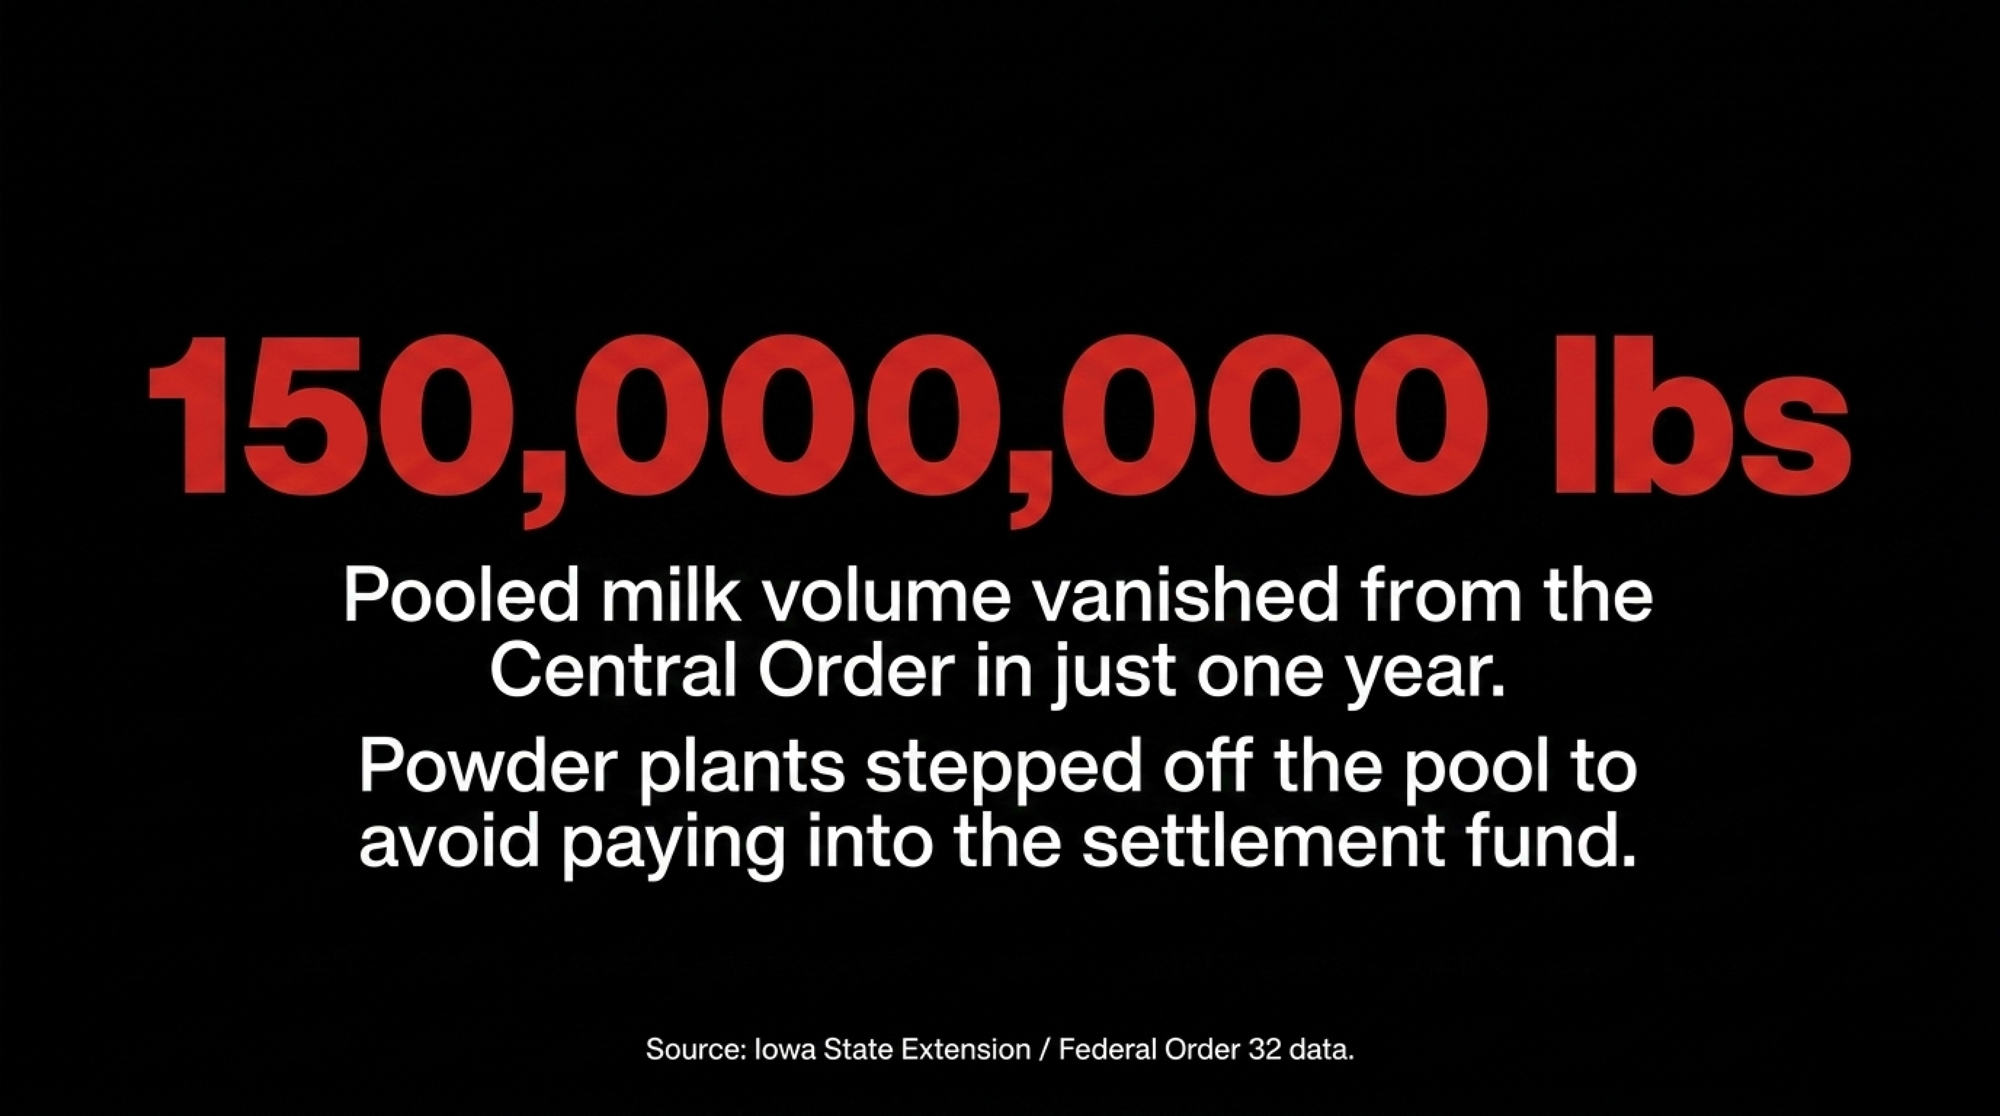
150 Million Pounds Left the Pool. Your PPD Paid for It.

Central Order pooled milk fell from 1.50 billion pounds to 1.35 billion in a year. That’s not a market move. That’s handlers stepping off the pool, and your producer price differential wearing it.

Executive Summary:

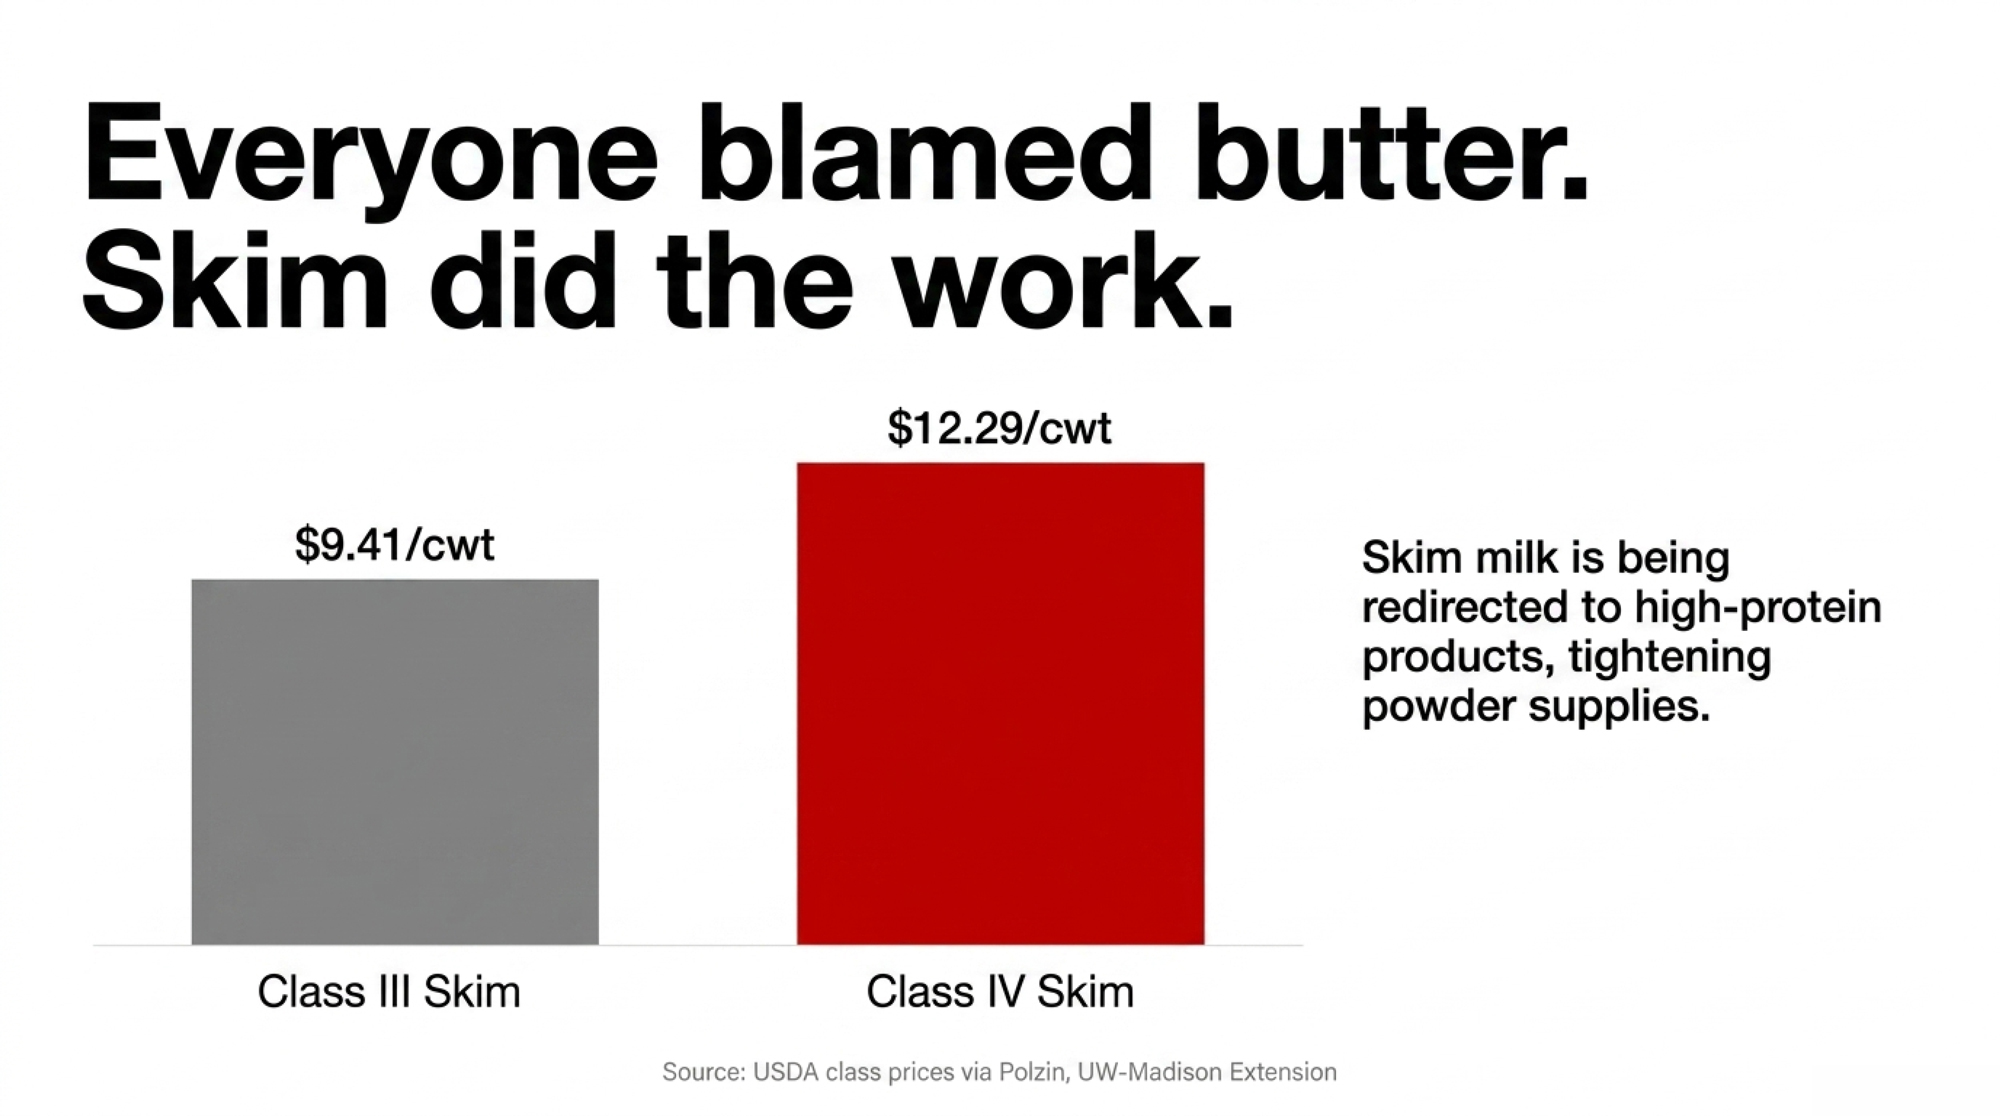
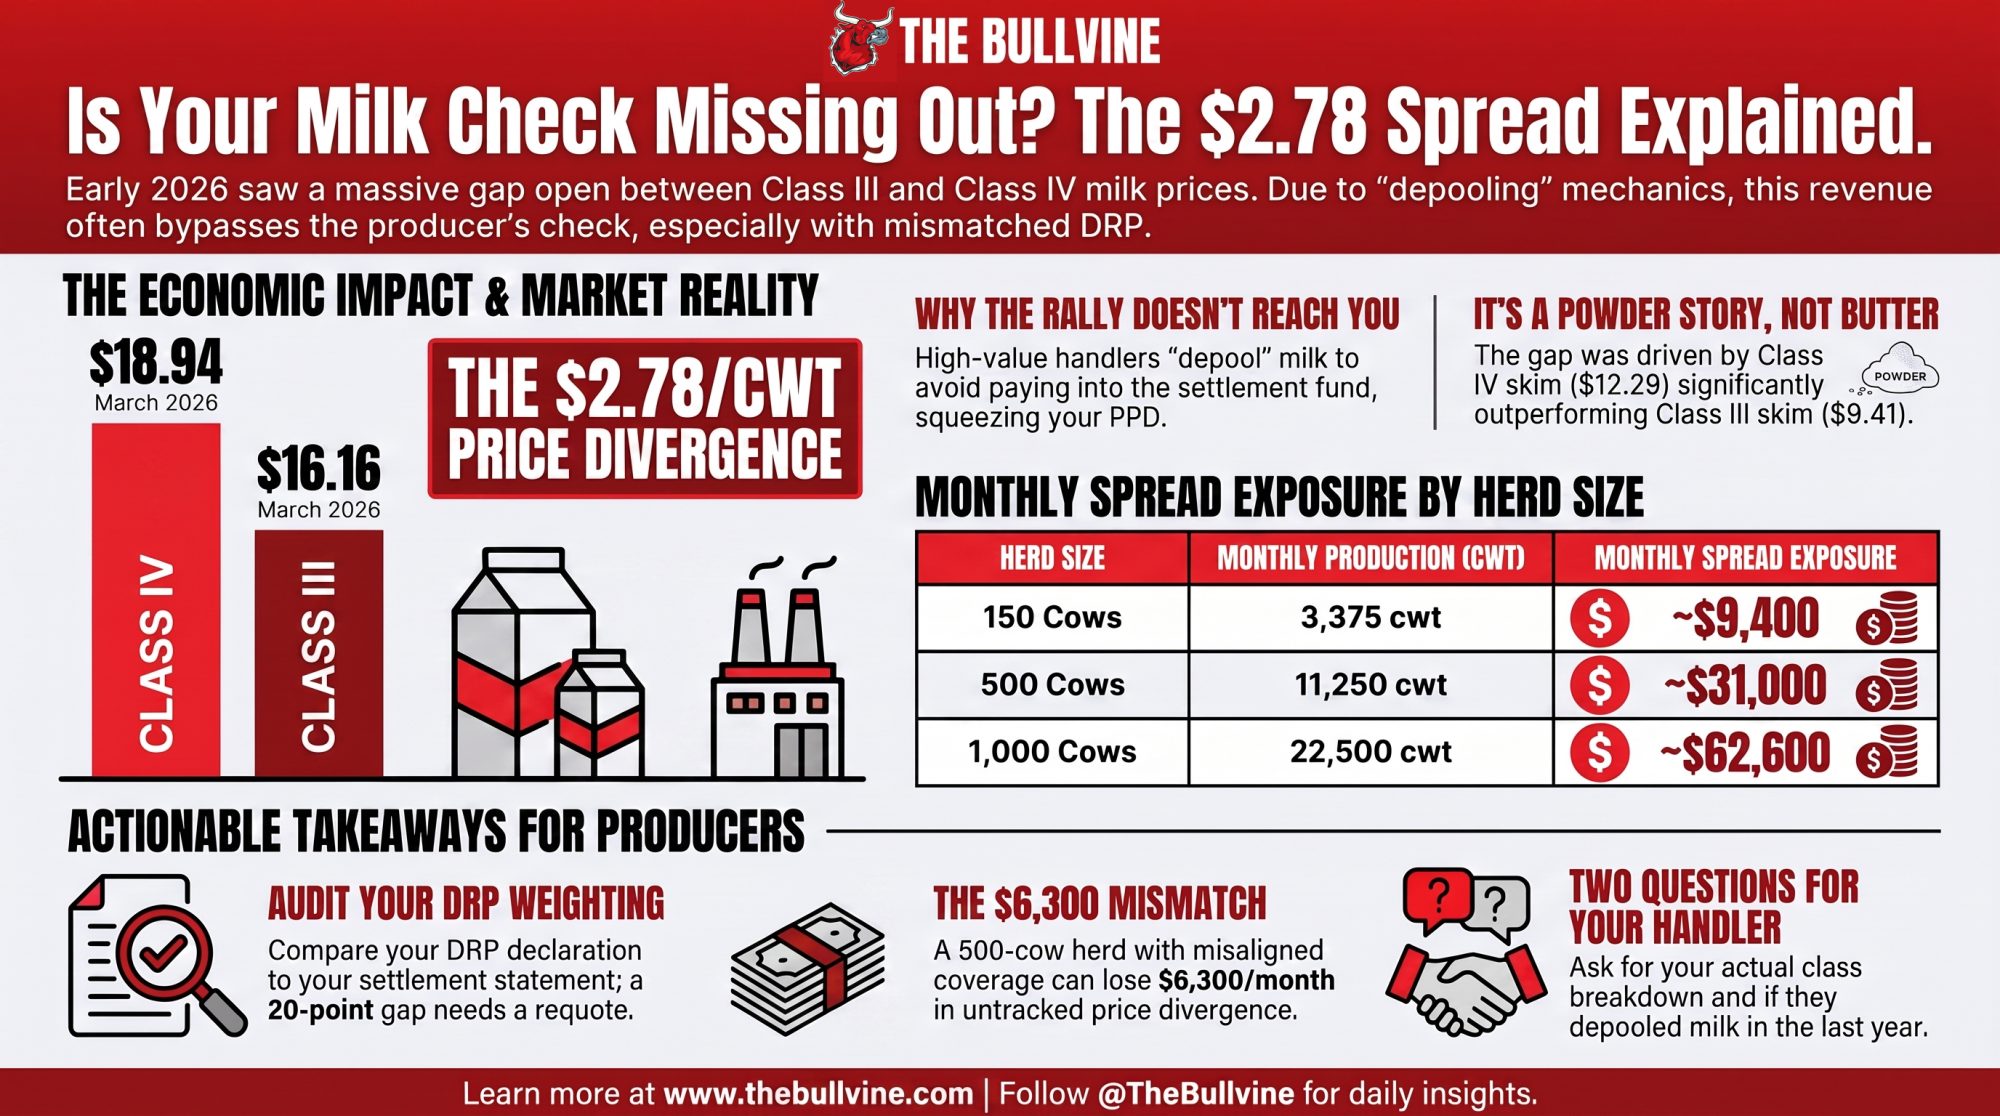
  • The gap. Class III settled at $16.16/cwt in March 2026 while Class IV hit $18.94, a $2.78/cwt spread worth roughly $31,000 a month on 500 cows and about $9,400 on 150. UW-Madison Extension’s Leonard Polzin traced the divergence to nonfat dry milk rather than butter: $12.29/cwt Class IV skim against $9.41 Class III skim.
  • The mechanism. When Class IV runs that far above a federal order’s uniform price, butter and powder plants step off the pool rather than pay into the producer settlement fund. That revenue never reaches the uniform blend, so the producer price differential riding on top of your component cheque gets squeezed, or goes negative.
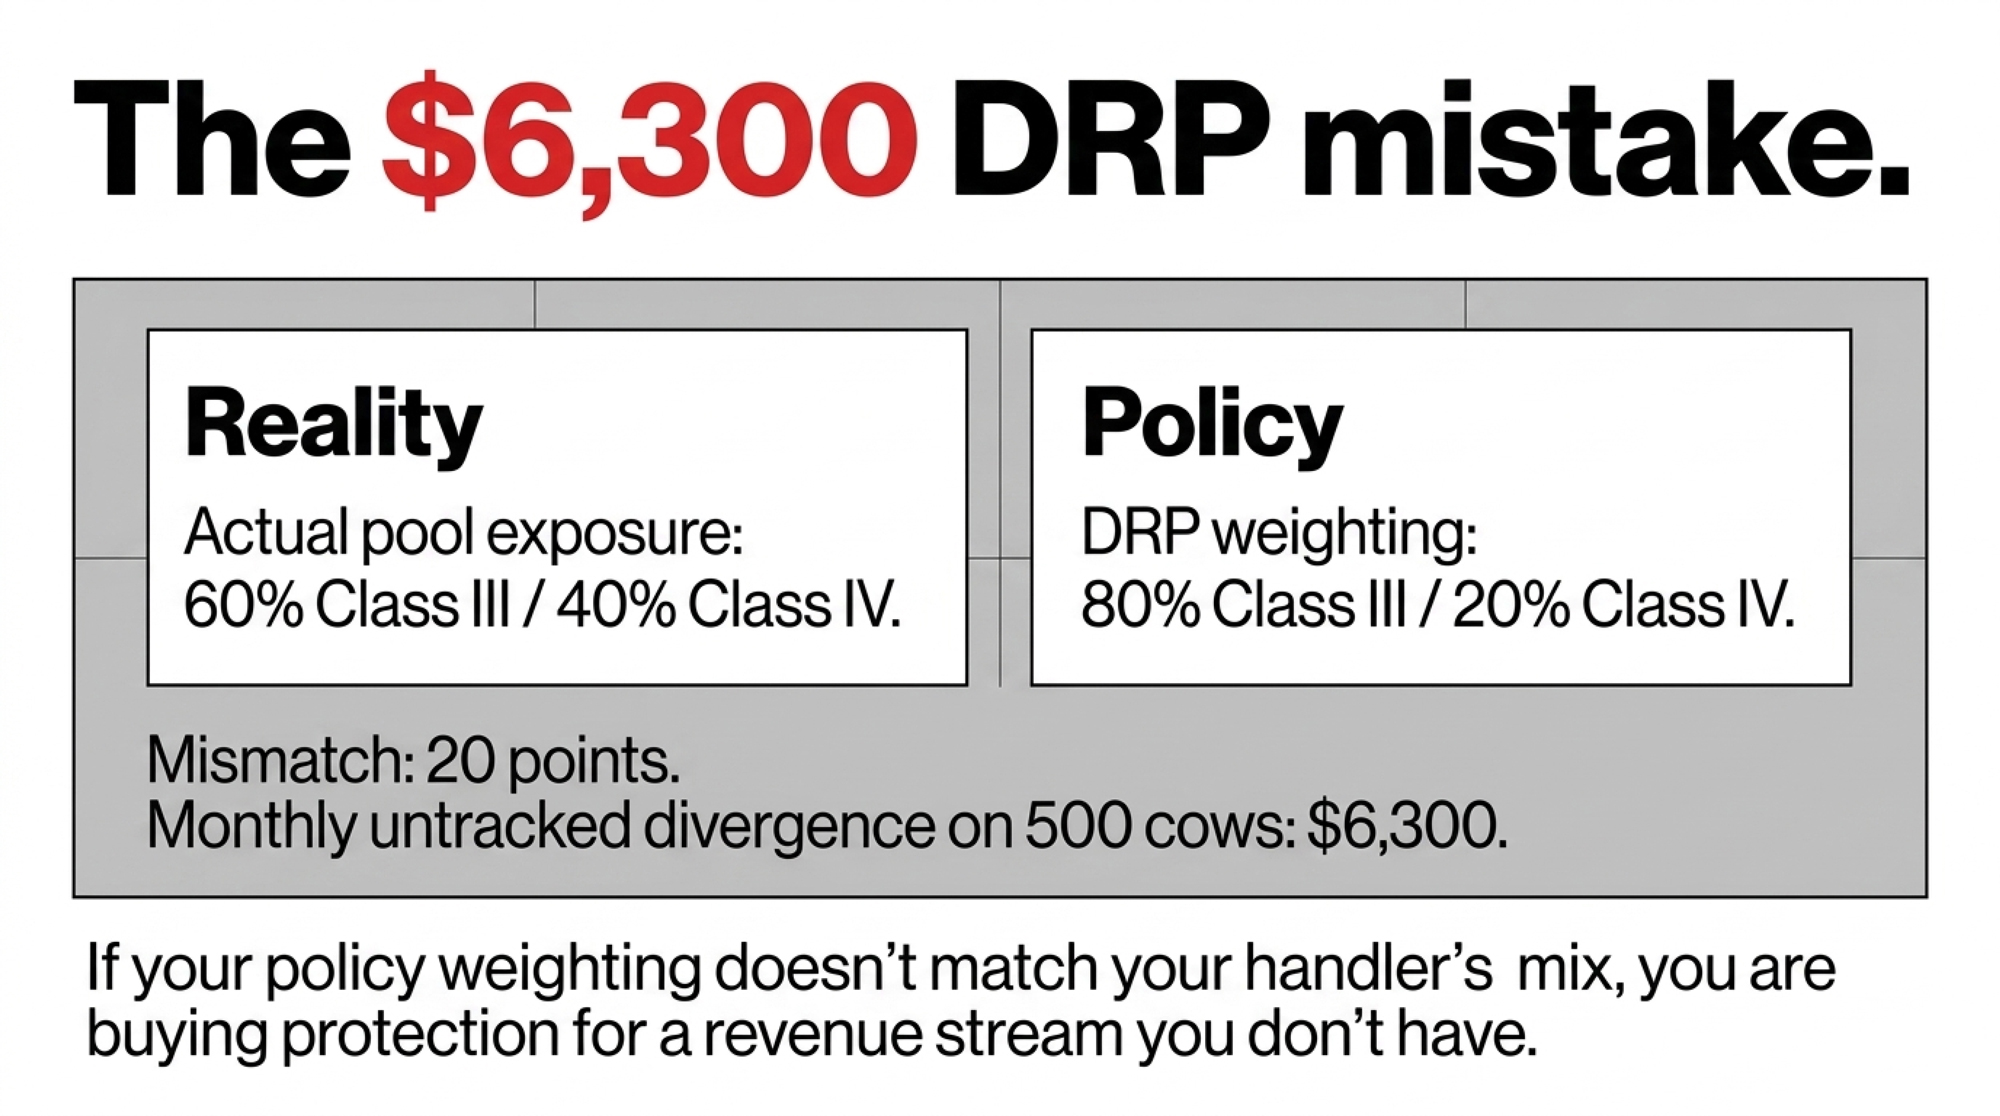
  • The fix. A 500-cow herd on a 60/40 cheese-powder pool carrying an 80/20 Class III DRP election shows roughly $6,300 a month of class divergence its policy isn’t tracking. Fifteen minutes with your settlement statement and your DRP declaration side by side tells you whether you’re one of them.
Class III Class IV spread

Analysis as of Aug. 26, 2026.

Class III milk settled at $16.16/cwt in March 2026 while Class IV hit $18.94, a $2.78/cwt spread worth roughly $31,000 a month on a 500-cow herd. Two operations with the same cows, the same ration, and the same diesel bill landed on opposite sides of it. Neither did anything to earn the difference.

March 2026Class IIIClass IVGap
Announced price$16.16/cwt$18.94/cwt$2.78/cwt
Skim milk price$9.41/cwt$12.29/cwt$2.88/cwt
Priced offCheddar + dry wheyButter + NFDM—

Source: USDA class prices via Polzin, UW-Madison Extension

Ship into a Wisconsin cheese plant, and the formula put you on the other side of it. The driver isn’t the one the shorthand suggests.

Everyone Assumed Butter. The Skim Side Was Doing the Work.

Leonard Polzin, Dairy Markets and Policy Outreach Specialist at the University of Wisconsin–Madison Division of Extension, worked through the Federal Milk Marketing Order formulas to find where the gap came from. Class IV is the butter-and-powder class, so the reflex is to blame butter.

His analysis points to nonfat dry milk instead, the powder left after water comes out of skim, which sets the nonfat solids value in the Class IV formula. That $2.88/cwt skim gap in the table above is the whole story in one line.

Polzin named the structural reason too, and that’s the part with staying power: skim milk is getting redirected toward ultrafiltration and high-protein products, tightening what actually reaches the dryers. Processing-mix shifts don’t reverse inside a quarter.

By early May, Iowa State University Extension was tracking a Class IV/Class III futures gap of roughly $5/cwt, the widest that difference has ever been. This isn’t a one-month oddity.

Why a Class IV Rally Never Reaches a Cheese Cheque

Polzin states plainly that this NFDM-driven Class IV strength does not flow directly into the pay price for Wisconsin cheese-route producers. The pooling mechanics are why.

Under a federal order, Class I fluid milk must always stay pooled. Manufacturing milk — Class II, III, and IV — can be kept out, and handlers do exactly that when a class price runs above the order’s uniform price. Butter and powder plants pull their milk off the pool rather than pay the difference into the producer settlement fund. Cheese plants can do the same when the arithmetic favors them; this isn’t a one-way mechanism.

The practical effect for an Upper Midwest (Order 30) shipper is narrower than “you missed the rally.” You’re paid Class III component values plus a producer price differential. When high-value Class IV milk leaves the pool, that revenue never enters the blend at all, so the PPD sitting on top of your component cheque gets squeezed, or goes negative. There was no Class IV upside to share. It exited before the sharing happened.

The clearest documented example of that flight comes from a separate order. Iowa State Extension reported that pooled milk in the Central Order (Federal Order 32) fell to about 1.35 billion pounds in March 2026, down from more than 1.50 billion a year earlier, with Class III utilization at 48.2% and Class IV withering to just 12.0%. Handlers voting with their feet rather than subsidizing the pool, in the same month as that $2.78 spread.

Order 32 is not Order 30, and the Wisconsin numbers aren’t in that dataset. But the incentive is written into the federal order structure itself, not into any one marketing area: any handler in any order can keep manufacturing milk off the pool when the class price beats the uniform price. Order 30 runs the lowest Class I utilization of any federal order, which means its blend leans harder on manufacturing milk than most, and a cheese-route producer there is paid off exactly the same component-plus-PPD arithmetic. Treat the Central Order figures as the visible case, not as Wisconsin’s ledger.

The Same Formula, Two Different Coasts

That Q1 divergence looked different depending on where you shipped. Corey Geiger, dairy economist at CoBank, told Brownfield Ag News in January 2026 that “if you look at the Class III markets here in the U.S., we see a rebounding of the Class III much faster… however, west of the Rockies, Class IV, butter and non-fat dry milk, and other powders is really down.” He noted futures had projected $19 Class IV against a $13–14 reality, “a lot of stress west of the Rockies right now.”

One formula, opposite outcomes. In January, Western butter-powder shippers watched a forecast collapse while Class III recovered. By March, the skim rally had flipped it. Class IV ran nearly three dollars clear of Class III, and this time Upper Midwest cheese shippers were the ones locked out. Late summer moved it again, which is where the current numbers come in.

Contract structure matters here too. A co-op member and an independent shipper on a direct supply agreement face the same federal formula but very different visibility into pooling decisions. One has a board vote and a member statement, the other has whatever the contract requires the buyer to disclose. Worth knowing which one you are before you call your handler.

A note for readers north of the border: this is a Federal Milk Marketing Order mechanic. Ontario and other supply-managed producers price through a provincial board, so the Class III/IV split has no direct analog on a Canadian cheque. The transferable lesson is narrower. Know which product classes your processor actually serves before assuming a commodity rally reaches you.

Running the Numbers

Class-spread exposure — illustrative scenarios, March 2026 formula prices

InputValue
Class IV, March 2026$18.94/cwt
Class III, March 2026$16.16/cwt
Spread$2.78/cwt
Production assumption75 lbs/cow/day (swap in your rolling average)

Scale it to your herd:

Herd sizeMonthly cwt (30 days)Spread exposure
150 cows3,375≈ $9,400/month
300 cows6,750≈ $18,800/month
500 cows11,250≈ $31,000/month
1,000 cows22,500≈ $62,600/month

Production swings move it too. At 85 lbs/cow/day, a 500-cow herd shows 12,750 cwt and roughly $35,400; at 65 lbs, 9,750 cwt and about $27,100. A 31-day month adds about $1,000.

What this math is not: profit or loss. It’s the difference in the formula price two operations settle against, before component premiums, hauling deductions, and handler blend adjustments. Your actual cheque sits downstream of all three.

Why “Class IV Is Weak” Only Tells Half the Story

Class III and Class IV aren’t market prices. They’re formula outputs. USDA calculates Class III from National Dairy Products Sales Report cheddar and dry whey prices, and Class IV from NDPSR butter and NFDM prices. Four commodities, two classes, no cow anywhere in the arithmetic.

So Class IV runs on two engines: butter on the fat side, NFDM on the skim side. They don’t have to move together.

Watch the late-August prints, and you can see them pulling apart in real time. Cheddar blocks sat at $1.5275/lb through Aug. 25. Butter closed at $1.4300 on Aug. 19, recovered to $1.4800 by Aug. 25, and its Aug. 17–21 weekly average of $1.4625 still ran well under year-ago levels. NDM climbed to $1.8100 on Aug. 19 and held there through Aug. 25 before easing 2.5 cents to $1.7750 on Aug. 26. September Class III futures were trading at $16.45 on the morning of Aug. 26.

Two components, same class, moving on their own clocks.

USDA’s August 2026 Livestock, Dairy and Poultry Outlook cut the 2026 butter forecast 4.5 cents to $1.645/lb while trimming NDM just 1.0 cent, to $1.605/lb. The August WASDE lowered the 2026 all-milk forecast to $19.85/cwt, raised Class III, and lowered Class IV. The divergence is written into USDA’s own numbers.

One detail runs counter to the tidy oversupply story. USDA NASS Cold Storage, released Aug. 24, 2026, put butter stocks down 3% from the prior month and down 3% year-over-year. Falling stocks aren’t what oversupply looks like.

Worth a caution: Polzin’s analysis covers the first quarter. The August prints suggest his mechanism is still operating, but that extension is an inference from the data, not a claim he made.

Anyone budgeting expansion against the annual number rather than the monthly spread should read our breakdown of how the $19.85 all-milk forecast reshapes expansion math alongside this.

How Much Does the Wrong DRP Weighting Cost?

Dairy Revenue Protection lets you elect a Class Pricing option with a declared Class III/Class IV weighting, or a Component Pricing option built on your own butterfat and protein tests. When that weighting doesn’t match where your milk settles, you’re buying protection against a revenue stream you don’t have.

Work it through on the verified March spread. A 500-cow herd shipping 11,250 cwt a month, on a handler running 60% cheese and 40% butter/powder, carrying a DRP election weighted 80% Class III:

MetricActual Pool ExposureDRP Policy WeightingStatus
Class III share60%80%Over-weighted
Class IV share40%20%Under-weighted by 20 pts
March 2026 spread$2.78/cwt——
Monthly volume (500 cows)11,250 cwt——
Untracked divergence——≈$6,300/month
Requote trigger threshold——>20-point gap
  • Actual pool exposure: 60% Class III / 40% Class IV
  • Policy weighting: 80% Class III / 20% Class IV
  • Mismatch, measured on the Class IV side: 20 percentage points
  • March 2026 spread: $2.78/cwt
  • Untracked divergence: 11,250 cwt × $2.78 × 20% = roughly $6,300/month

That’s a modeled figure built on a real spread and a stated weighting gap, not a forecast and not a loss. It’s the portion of the class divergence your policy isn’t tracking, measured one way. Weight both sides of the mismatch and you’d get a different number. The spread has narrowed since March, so pull the current one off your own settlement statements rather than borrowing this arithmetic wholesale.

RMA data cited in Bullvine reporting from October 2025 put DRP coverage at roughly 35% of U.S. milk production, above 50% in the High Plains. Coverage rates tell you how many operations bought a policy. They say nothing about whether the weighting matches the pool, which is why it’s worth understanding how DRP quarters and DMC tiers actually work before the next sales window.

Is Your Milk Actually Where You Think It Is?

Most producers can name their co-op. Fewer can state the class breakdown of what that co-op does with their milk in a given month, and that breakdown is what a DRP election should be built on.

Handlers shift plant mix. They also make month-to-month pooling decisions you’ll never be consulted on. When either changes, your correct weighting shifts with it, and that change won’t show up in your mailbox or your premium.

The 30/90/365-Day Playbook for Class-Exposed Herds

30 Days

Step 1 — Compare two documents. Action: Pull your most recent settlement statement and find the class utilization. Pull your current DRP declaration and find the weighting factor. Put them side by side. Trigger: A gap of more than 20 points means request a requote before the next quarterly window. Failure mode: Checking is free. Changing coverage means buying at current premiums, so know your number before you call the agent.

Step 2 — Test the spread against your debt coverage. Action: Take the per-cwt spread from your last three settlement statements, multiply by monthly cwt, and set it beside your term-debt obligation. This is a variance check, not a true ratio. It tells you how much class movement your debt service can absorb. Trigger: UW-Madison Extension’s repayment-capacity guidance treats a debt coverage ratio above 1.75 as strong and below 1.25 as a weakness. If class variance alone could push you under 1.25 in a bad quarter, this is a liquidity question, not paperwork. Failure mode:Variance isn’t cash flow. Run the real ratio with your lender or CPA before acting.

Step 3 — Confirm DMC enrollment. Action: Verify your status. The 2026 window closed Feb. 26, 2026 (USDA FSA), so there’s nothing left to buy, but there’s something to know. Trigger: If you assumed you were enrolled and can’t confirm it, make that call this week. Failure mode: None. Five-minute check, no downside.

Step 4 — Re-run your fall fuel line. Action: Reprice harvest, hauling, and manure fuel at current rates. U.S. national average retail diesel ran $5.652/gal the week of Aug. 24, up 52.2% from $3.713 a year earlier (EIA weekly series). Trigger: Any budget built on published forecast guidance needs revisiting. Failure mode: This lands during silage season, ahead of the cheque that covers it. Working-capital timing, not a planning error.

90 Days

Step 5 — Price Component against Class. Action: Have your agent quote both options using twelve months of your component data. Trigger: Fat and protein tests above breed average generally favor Component Pricing. Failure mode:It ties coverage to your own tests, so a component slump hits your cheque and your indemnity at the same time. That’s concentration, not diversification.

Step 6 — Ask your handler two questions. Action: Not the co-op name. The actual class breakdown of where your milk goes, and whether they depooled any months in the last year. Trigger: If your handler added or converted capacity, or depooled in a month when the spread was wide, treat your existing weighting as stale. Failure mode: Expect persistence to be required. Handlers don’t volunteer pooling decisions, and an independent supply contract may not obligate them to.

365 Days

Step 7 — Track the ultrafiltration signal. Action: Watch whether NDM holds its premium to cheddar blocks or the gap closes. Opportunity signal: If the skim redirection Polzin identified holds and your handler sits on the powder side, the exposure that hurt one quarter can favor you in another, but only if your coverage is weighted to capture it. Failure mode: Structural shifts are slow and easy to over-read from a single quarter’s prints. NDM gave back 2.5 cents on Aug. 26 alone.

Step 8 — Decide: manage the exposure, or accept it. Action: Some operations can’t change handlers. Name your category and plan accordingly. Trade-off: If the relationship is fixed, your levers are input cost and coverage weighting, not class mix. You gain stability. You give up the ability to chase the stronger class. Failure mode: Drifting without deciding, carrying a mismatched policy while telling yourself you’d switch handlers if it got bad enough.

For the full-year version of this arithmetic, our earlier analysis of what a three-dollar spread does across twelve monthsruns the same mechanics out to an annual figure.

Key Takeaways

  • The Class IV rally that ran $2.78/cwt above Class III in March didn’t reach cheese-route herds because butter and powder plants step off the pool rather than pay into the producer settlement fund. In the Central Order, pooled milk fell from 1.50 billion pounds to 1.35 billion in a year, and Class IV utilization dropped to 12.0%.
  • Class IV runs on two engines, not one. NFDM drove the March gap, with the Class IV skim price at $12.29/cwt against $9.41 for Class III, while butter sat weak. If your risk coverage treats Class IV as a single number, it’s tracking half your exposure.
  • Pull your settlement statement and DRP declaration, and compare class utilization to the weighting factor. A 500-cow herd on a 60/40 cheese-powder pool carrying an 80/20 Class III election shows roughly $6,300 a month of divergence its policy isn’t tracking. Request a requote before the next quarterly window if the gap runs past 20 points.
  • Ask your handler two things: the actual class breakdown of where your milk goes, and whether they depooled any month in the last year. Neither answer shows up in your mailbox, and an independent supply contract may not require them to volunteer it.

What This Means for Your Operation

The uncomfortable part isn’t the spread. It’s that two operations with identical management can finish a quarter tens of thousands of dollars apart on arithmetic neither one participates in, and on pooling decisions made in an office neither one visits.

The only lever you control is whether the policy you’re paying for matches the milk you actually ship. So pull the paperwork. What does your DRP declaration say your class split is, and what did last month’s settlement statement say it actually was?

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.

Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.

NewsSubscribe
First
Last
Consent
Send this to a friend