Archive for USDA milk production

USDA’s 24-State September Milk Gain: Five States Supplied 65.6%

August’s DMC margin fell 18.9%. The milk kept coming anyway. Here’s the Bullvine math on where it’s growing, and what to test before you add cows.

Key Takeaways

  • Wisconsin, Kansas, Texas, New York and Idaho supplied 324 million pounds, or 65.6% of the net 24-state increase, by Bullvine’s calculation. Declines in Arizona, Utah, Illinois and New Mexico cut 28 million.
  • Using revised July figures, the larger herd more than accounted for July’s reconstructed increase, while lower yield offset part of it. In September, higher yield contributed about one-third.
  • August’s $9.34 DMC margin is $2.18 below a year earlier, but it’s milk price minus formula feed cost. It skips labor, debt and depreciation, so it can’t tell you whether expansion pays.
While those five states added milk, the latest margin data point the other way. In August, the most recent month covered by the margin data used here, U.S. production rose 2.4% from a year earlier, according to USDA’s October 22 Milk Production report, while the Dairy Margin Coverage margin fell 18.9%, by Bullvine’s calculation from USDA’s October 16 Livestock, Dairy, and Poultry Outlook. That comparison describes national conditions. The return on another cow depends on your milk terms and the costs she adds.

Defining the Margin Squeeze: Behind the $9.34 DMC Trigger

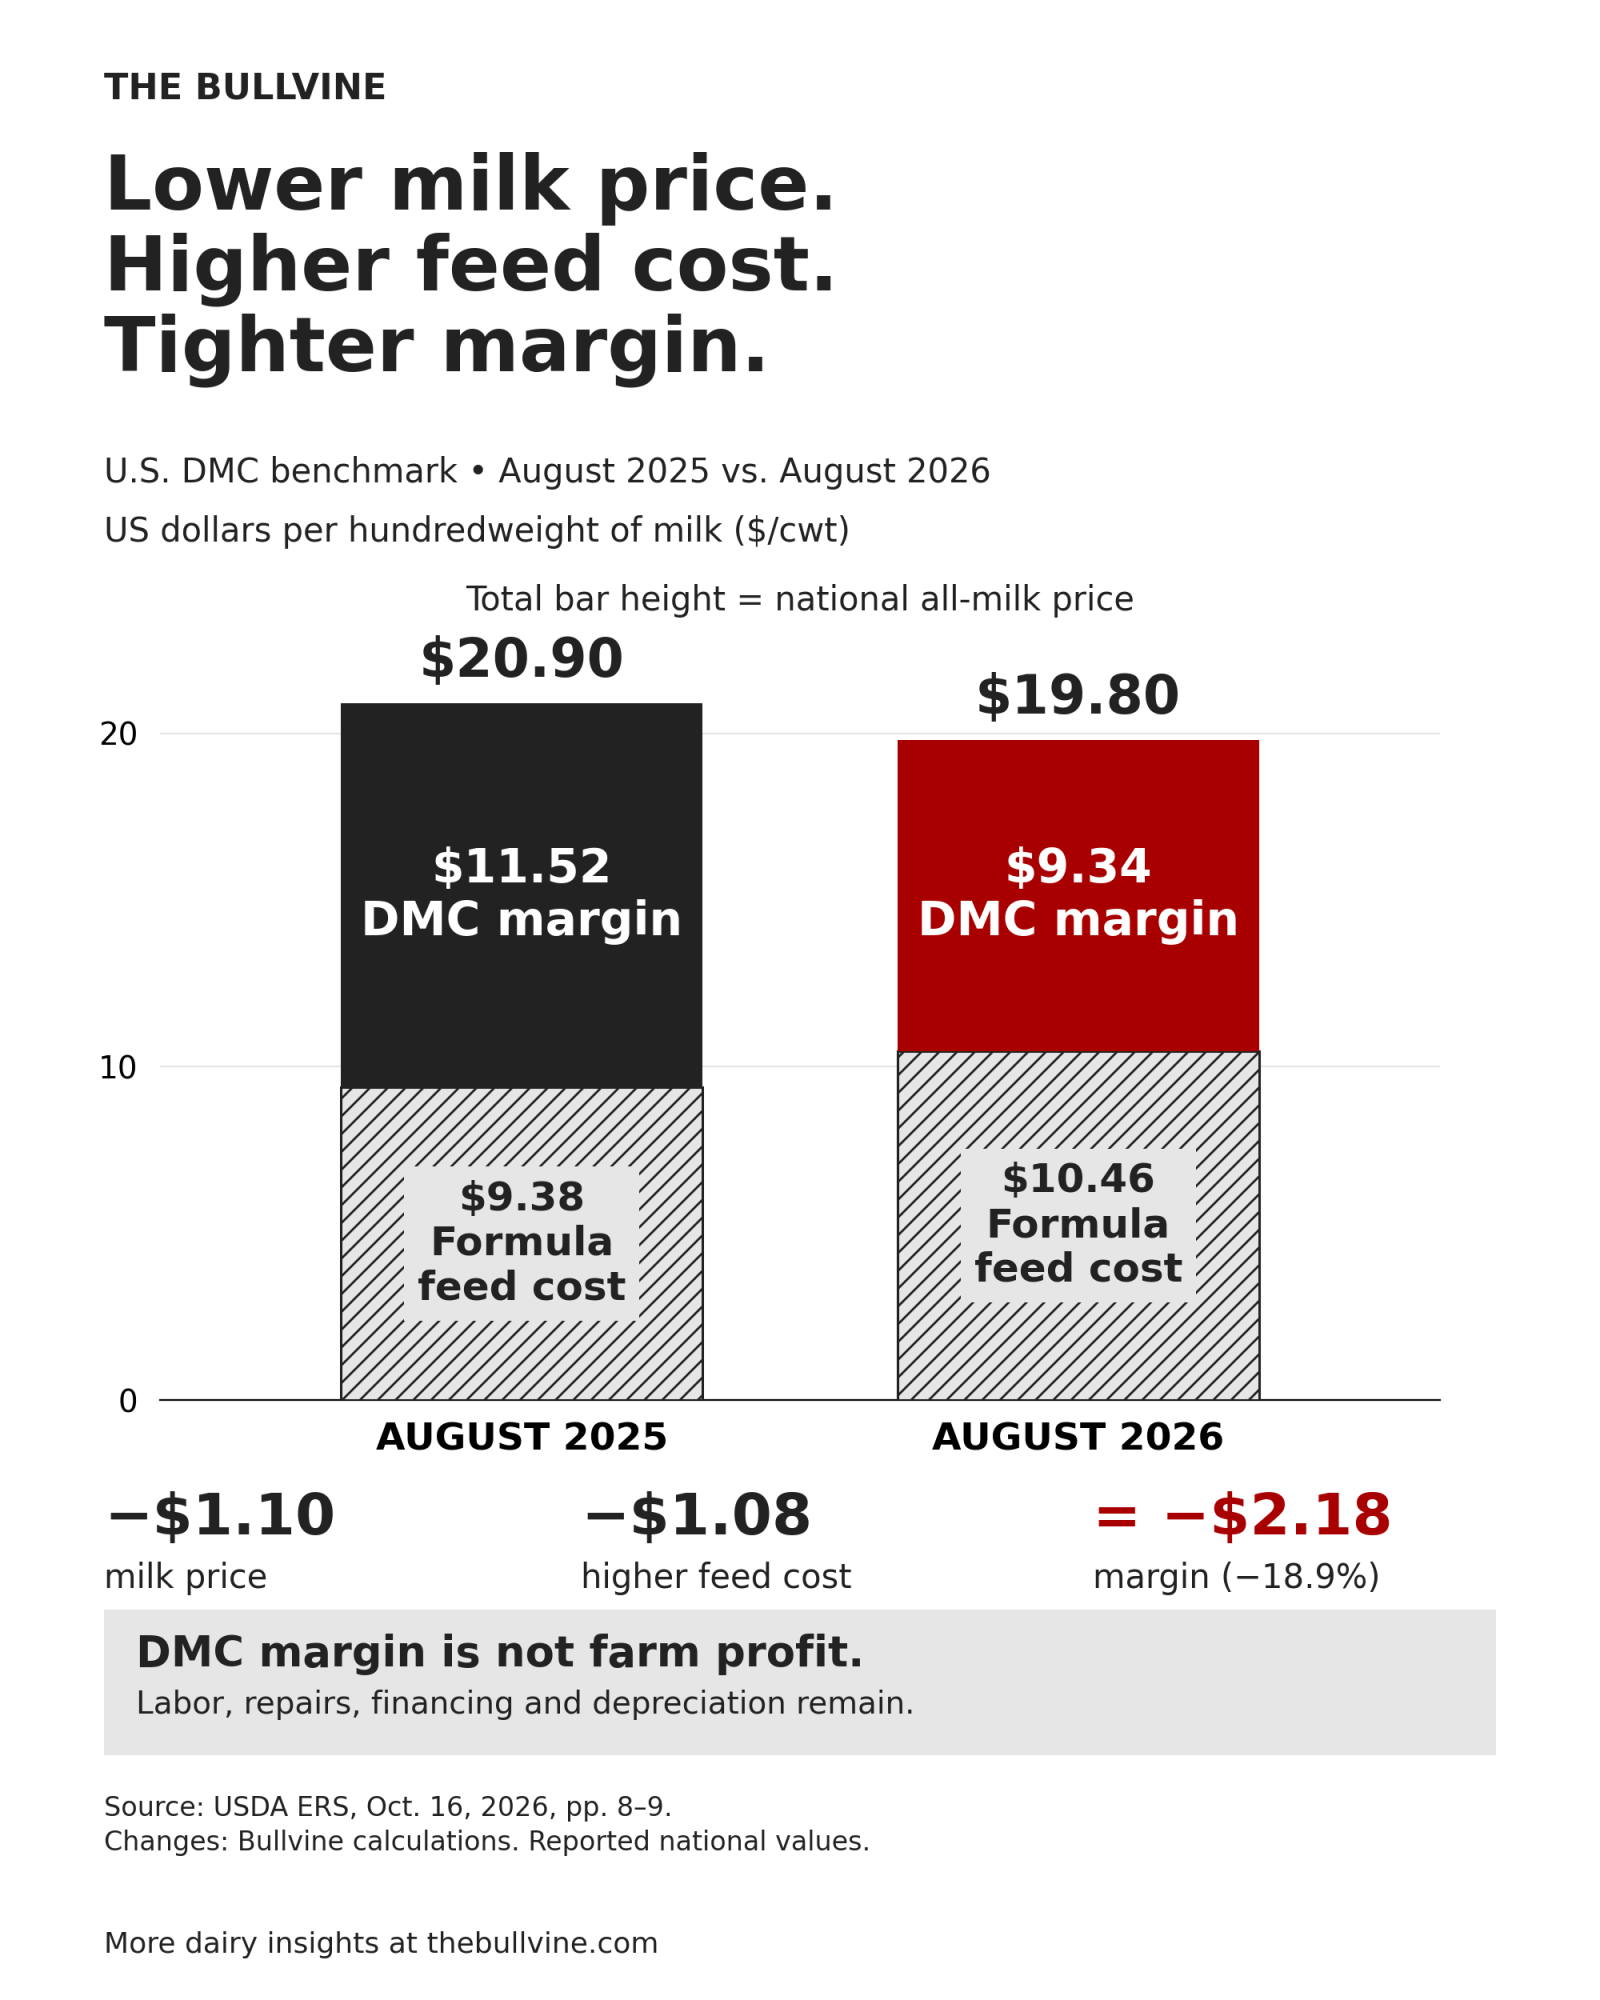
USDA’s August DMC margin was $9.34 per hundredweight, down from $11.52 in August 2025. That’s a $2.18 decline, or 18.9%, calculated by Bullvine from figures on pages 8–9 of the ERS outlook. Both sides moved against the margin: the all-milk price fell $1.10, while formula feed costs increased $1.08. August’s $9.34 margin triggered payments for participating operations with $9.50 coverage.
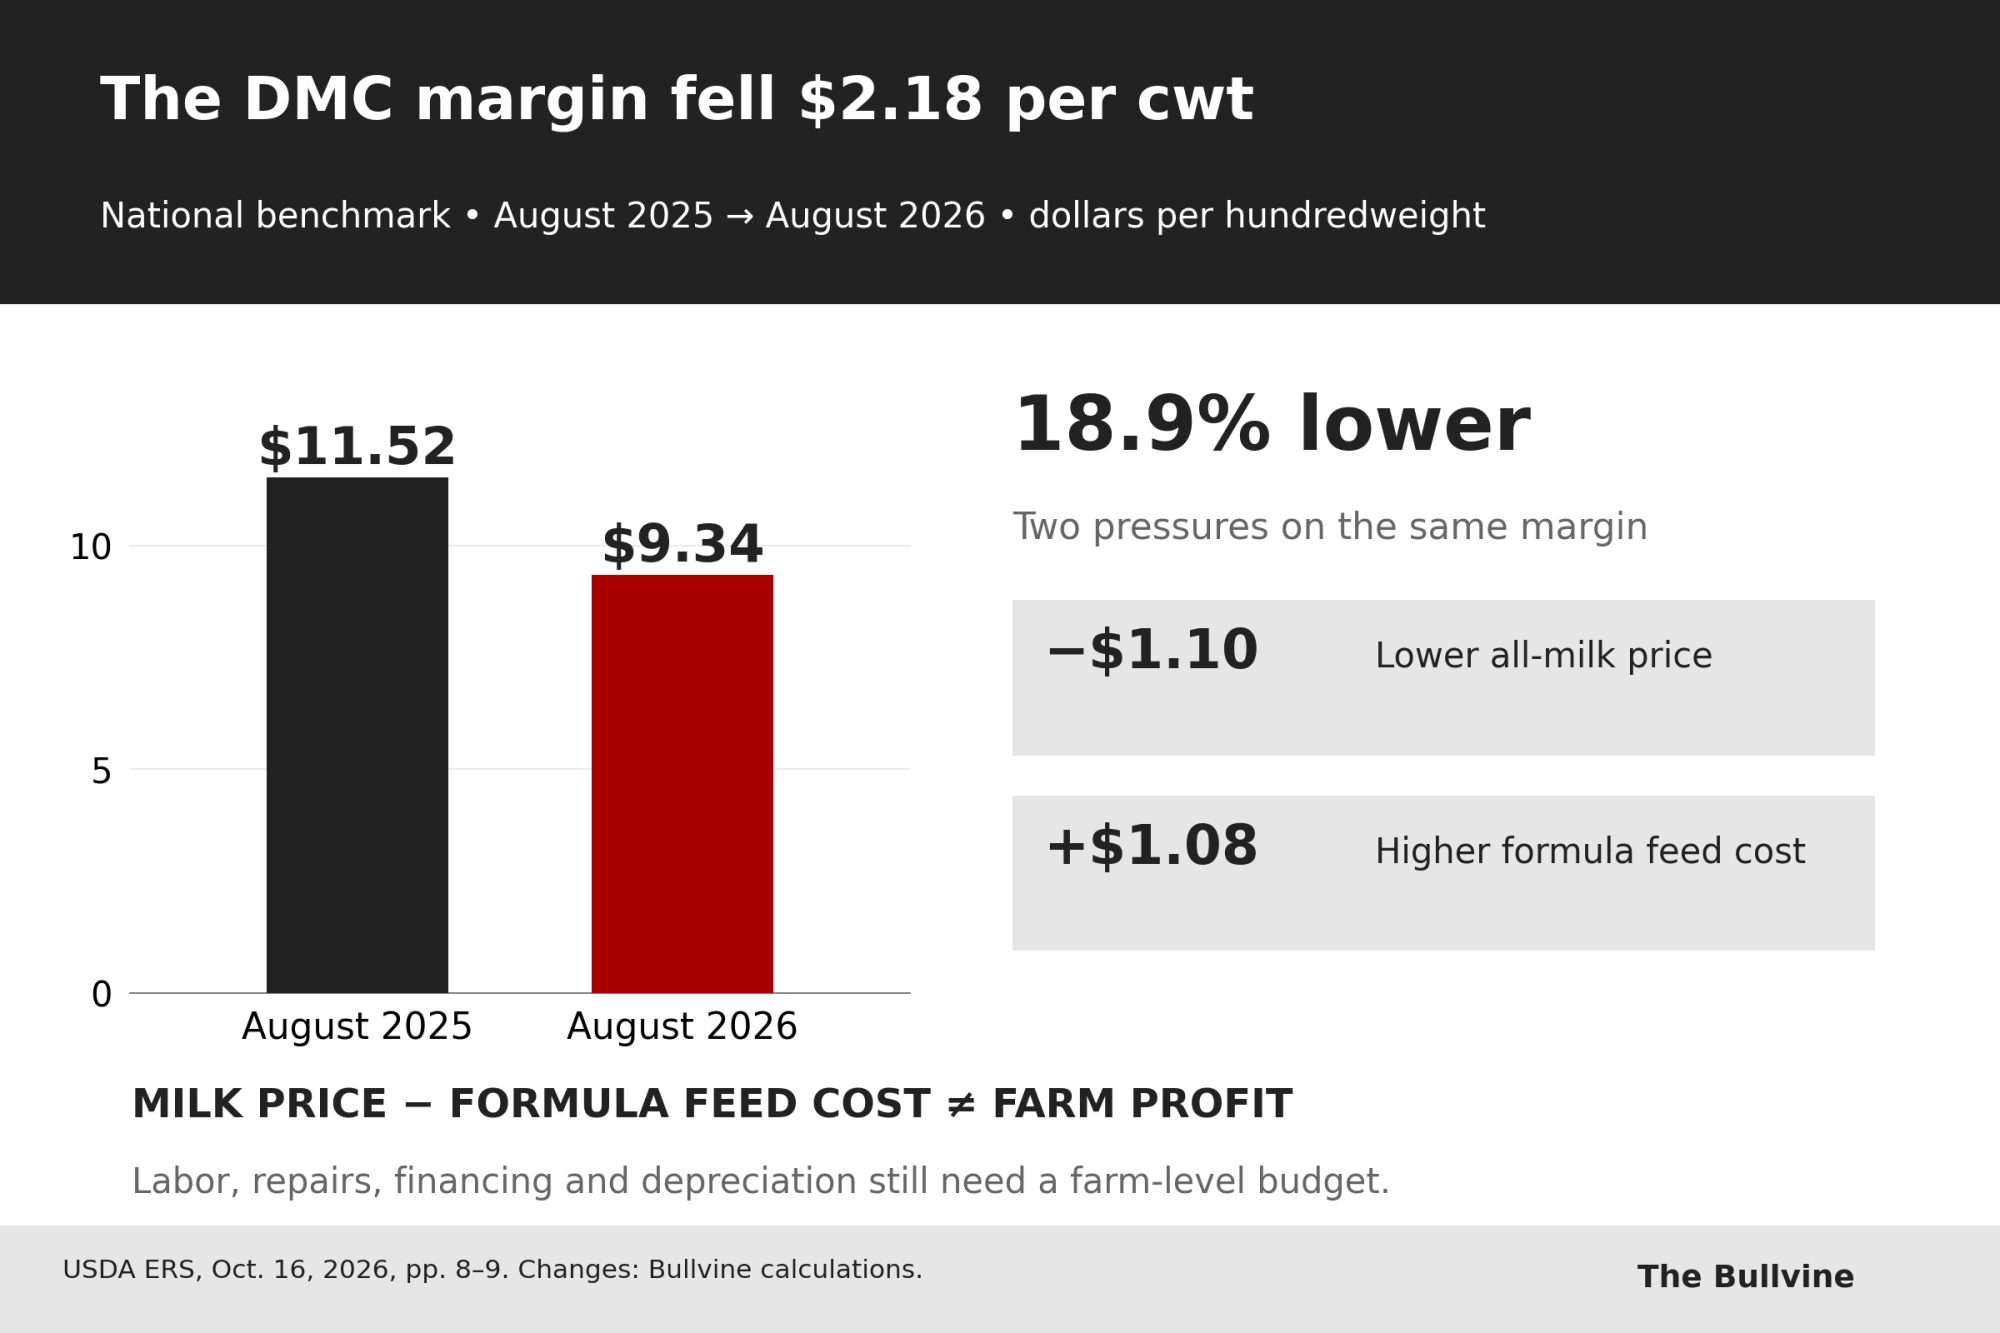
National measureAugust 2025August 2026Change
All-milk price$20.90/cwt$19.80/cwt−$1.10
DMC formula feed cost$9.38/cwt$10.46/cwt+$1.08
DMC milk-feed margin$11.52/cwt$9.34/cwt−$2.18
Milk production, October report vintage19.560 billion lb20.039 billion lb+2.4%

Sources: USDA ERS’s October 16 outlook, pages 8–9, and USDA NASS’s October 22 Milk Production report, page 2. Changes and percentage comparisons are Bullvine calculations.

DMC measures the difference between the national all-milk price and standardized feed costs. It does not deduct the farm’s entire labor bill, repairs, financing costs, depreciation or the economic cost of owned resources. Nor does it add calf receipts, cull-cow income or risk-management payments. A $9.34 DMC margin is therefore neither $9.34 of profit nor proof of a loss. August is the latest margin month; September’s production estimate is a separate, newer observation, so neither a September DMC result nor a farm-level loss is established here.

Even the all-milk price isn’t the amount deposited into every producer’s account. NASS defines it as a gross price before deductions including hauling, promotion and cooperative dues, with premiums and discounts included. Your realized milk price and actual ration cost are the starting points for your budget, not the national spread.

Where the pounds came from

USDA’s October 22 report put September national milk production at 19.443 billion pounds, up 2.6% from September 2025. The often-quoted 2.7% belongs to the separate 24-state series, which reached 18.724 billion pounds. National July–September production totaled a preliminary 59.529 billion pounds, up 2.3%.

Bullvine ranked the September state changes by additional pounds, not percentage growth. Wisconsin supplied the largest increase, even though Kansas posted the faster percentage gain. Together, the five leading states contributed almost two-thirds of the 24-state net increase.
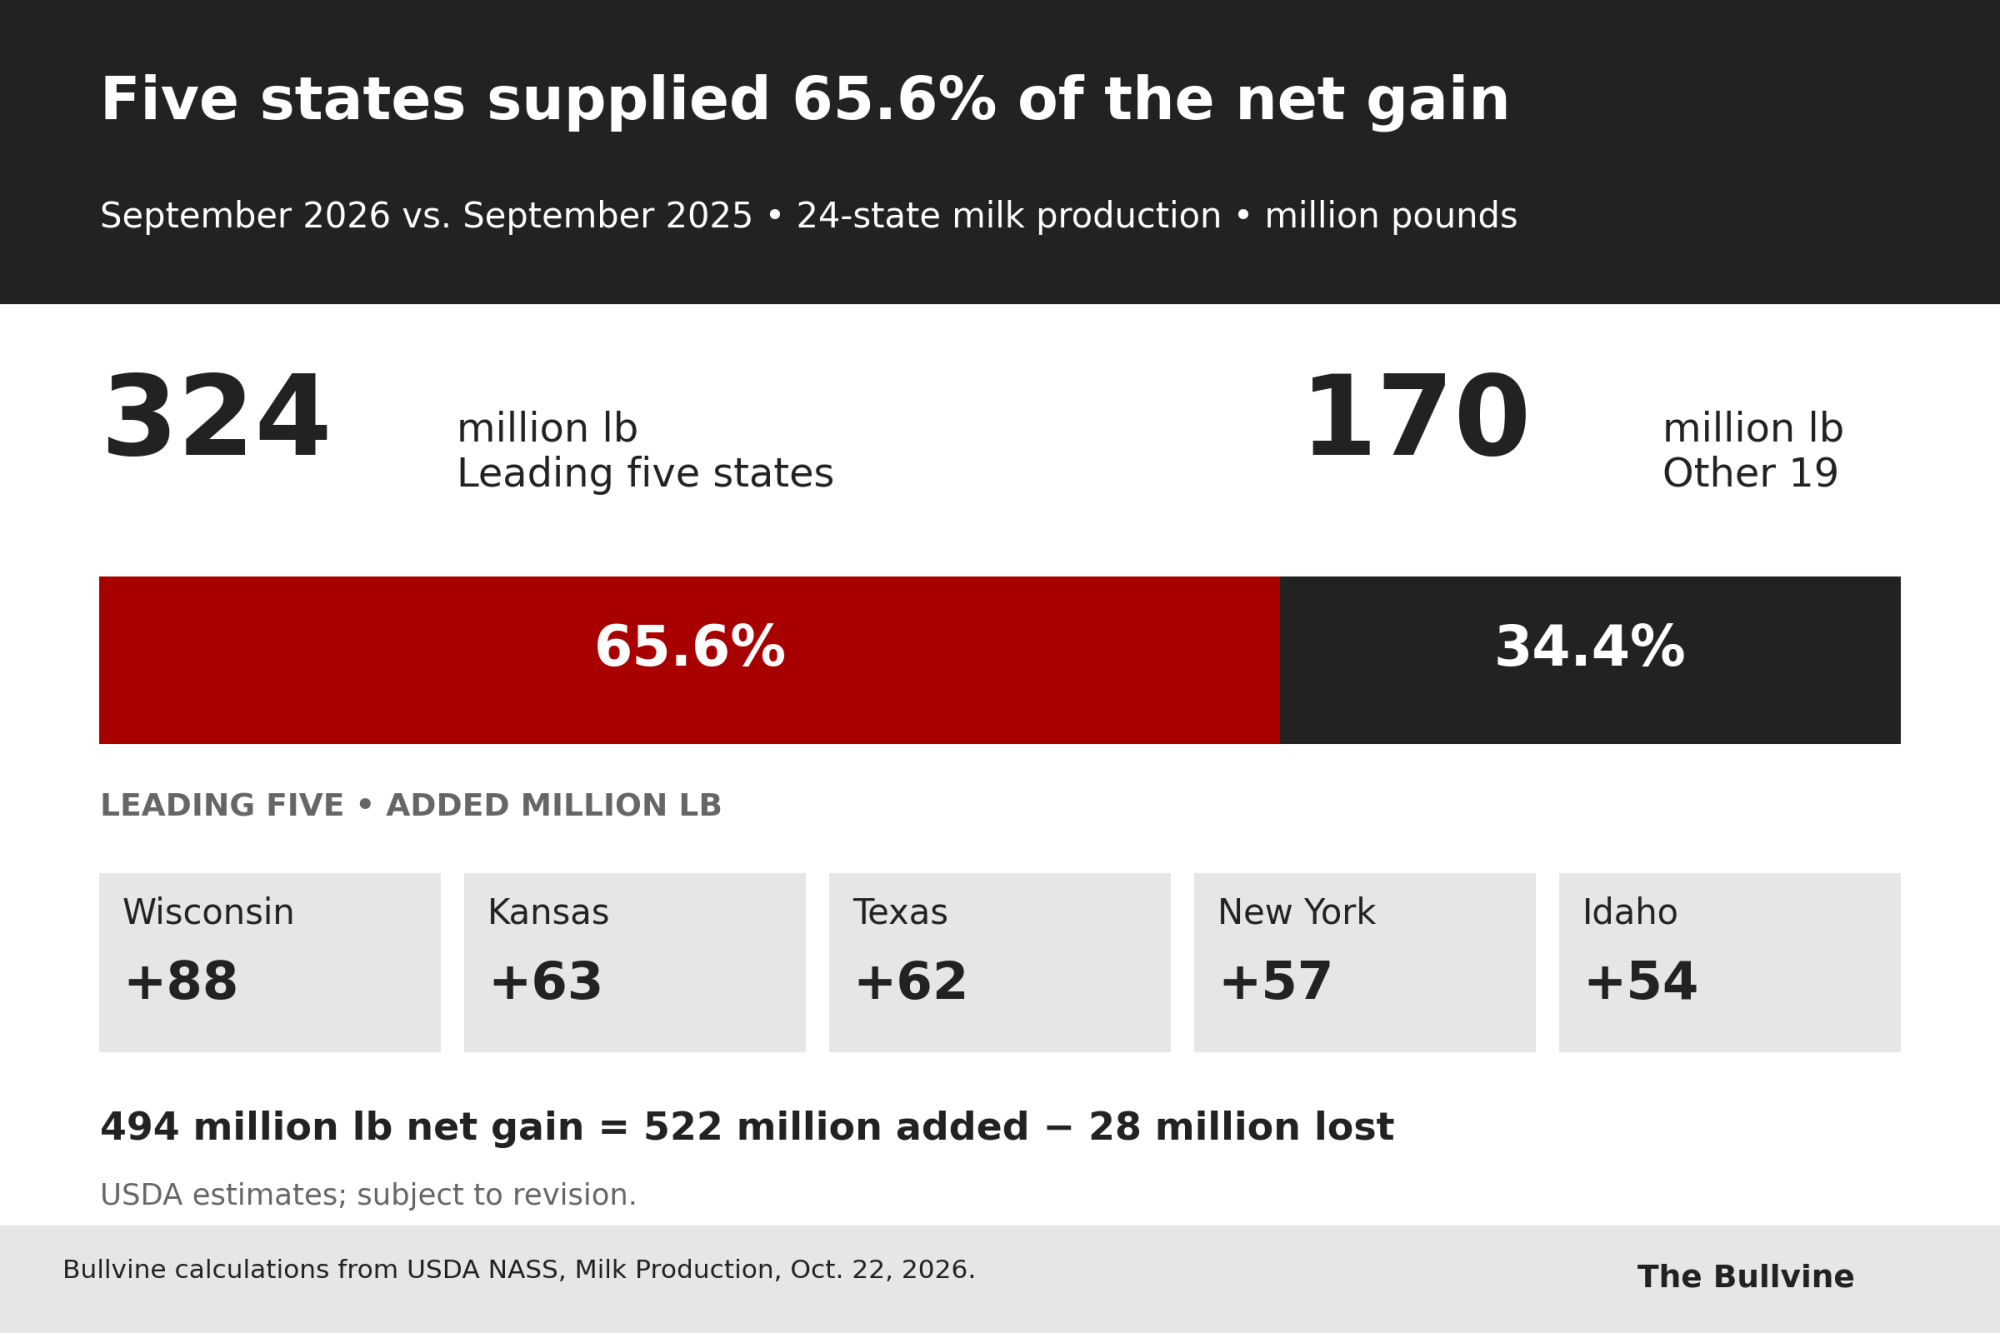
State or groupSeptember 2025, million lbSeptember 2026, million lbAdded million lbShare of net 24-state growth
Wisconsin2,6942,7828817.8%
Kansas4294926312.8%
Texas1,5001,5626212.6%
New York1,3601,4175711.5%
Idaho1,5411,5955410.9%
Leading five7,5247,84832465.6%
Remaining 19 states10,70610,87617034.4%
24-state total18,23018,724494100.0%

Bullvine calculations from USDA NASS’s September state table, October 22 release.

Growth varied widely across states. California added only 1 million pounds, while Arizona, Utah, Illinois and New Mexico declined. Across all growing states, additions totaled 522 million pounds; declines elsewhere removed 28 million, leaving the 494-million-pound net gain. A state total also doesn’t tell us how many individual farms expanded.

September’s estimates remain revisable. The same report raised August’s 24-state production by 132 million pounds from the previous preliminary estimate. Use the release date when citing these estimates; subsequent reports can revise them.

More cows did more work

Nationally, USDA reported 9.743 million milk cows in September, up 169,000 from a year earlier, and 1,996 pounds per cow, up 18 pounds. Those are approximately 1.8% more cows and 0.9% more milk per cow. The cow count includes dry cows and excludes heifers that haven’t freshened; it is not a count of dairy operations.

By Bullvine’s calculation, the larger herd accounted for about 65.6% of September’s reconstructed increase and higher milk per cow for about 33.8%. Yes, that’s the same 65.6% as the five-state share. It’s two separate calculations that happen to match, not one number counted twice. These figures can’t tell us whether those cows went into new stalls, filled existing facilities or stayed in production longer. The full calculation is in the appendix.

Yield vs. Herd Size: The July-to-September Shift

Bullvine’s July analysis put cows at about 93% of July’s year-over-year gain, based on USDA’s August 21 first estimate. The October 22 report revised July production down 98 million pounds, to 20.047 billion. On the revised figures, more cows accounted for more than July’s entire increase, because milk per cow slipped 2 pounds.

By September, the picture had shifted. Milk per cow rose 18 pounds from a year earlier and supplied about a third of the gain. Cows still did most of the work, but two months isn’t a trend, and these figures don’t say why yield moved. 

Kansas shows the processing link

Kansas offers a documented link between added milk and a plant that’s actually operating, not just announced. Hilmar’s March 17, 2025, release confirmed cheese production at Dodge City, identified more than $600 million in capital investment and thanked Southwest Kansas dairy families for their investment to supply the plant with milk.

But Hilmar’s release doesn’t disclose September 2026 milk intake, utilization or supplier returns. Kansas’s added 63 million pounds fit with an operating plant and earlier supply investment; the documents don’t establish how much of the state’s increase Hilmar caused.

The decision changes once facilities are operating. Keeping an existing cow producing requires a different budget from buying replacements and building another barn. USDA’s national DMC result can’t answer either budget on its own.

Demand isn’t one milk bucket

ERS reported January–August export growth of 27.4% on a milk-fat milk-equivalent basis, but 3.3% on a skim-solids basis. Domestic use grew 0.5% and 2.2%, respectively. Fat and skim-solids equivalents are separate measures and cannot be added together as raw-milk volume. These January–August changes provide demand context, but they do not establish how much of September’s additional milk went to exports.

USDA’s price expectations also differed by product stream. Its October outlook lowered the 2026 annual Class III forecast to $15.80 per cwt while raising Class IV to $18.90. Those are forecasts, not realized farm returns, but their divergence is another reason not to assume every additional hundredweight faces the same economics.

Don’t make calves prove too much

Budget warning: keep calf money out of the milk math. Neither NASS’s production tables nor ERS’s DMC measure establishes that beef-cross calf revenue caused the larger national milk herd. The national expansion figures don’t establish that calves are financing expansion. Evaluate nonmilk receipts separately before deciding whether they cushion your weaker milk returns.

Use net additional calf contribution, not the sale price of the highest-priced calf. Deduct the associated breeding and calf costs, account for saleable calves actually produced, preserve the required replacement pipeline and subtract the value of the dairy calf displaced. Keep cull-cow receipts separate: ERS reports cull cow prices have fallen sharply from mid-year highs, so use your own expected sale receipts. And don’t add cattle revenue twice if the whole-farm budget already contains it.

What this means for your operation
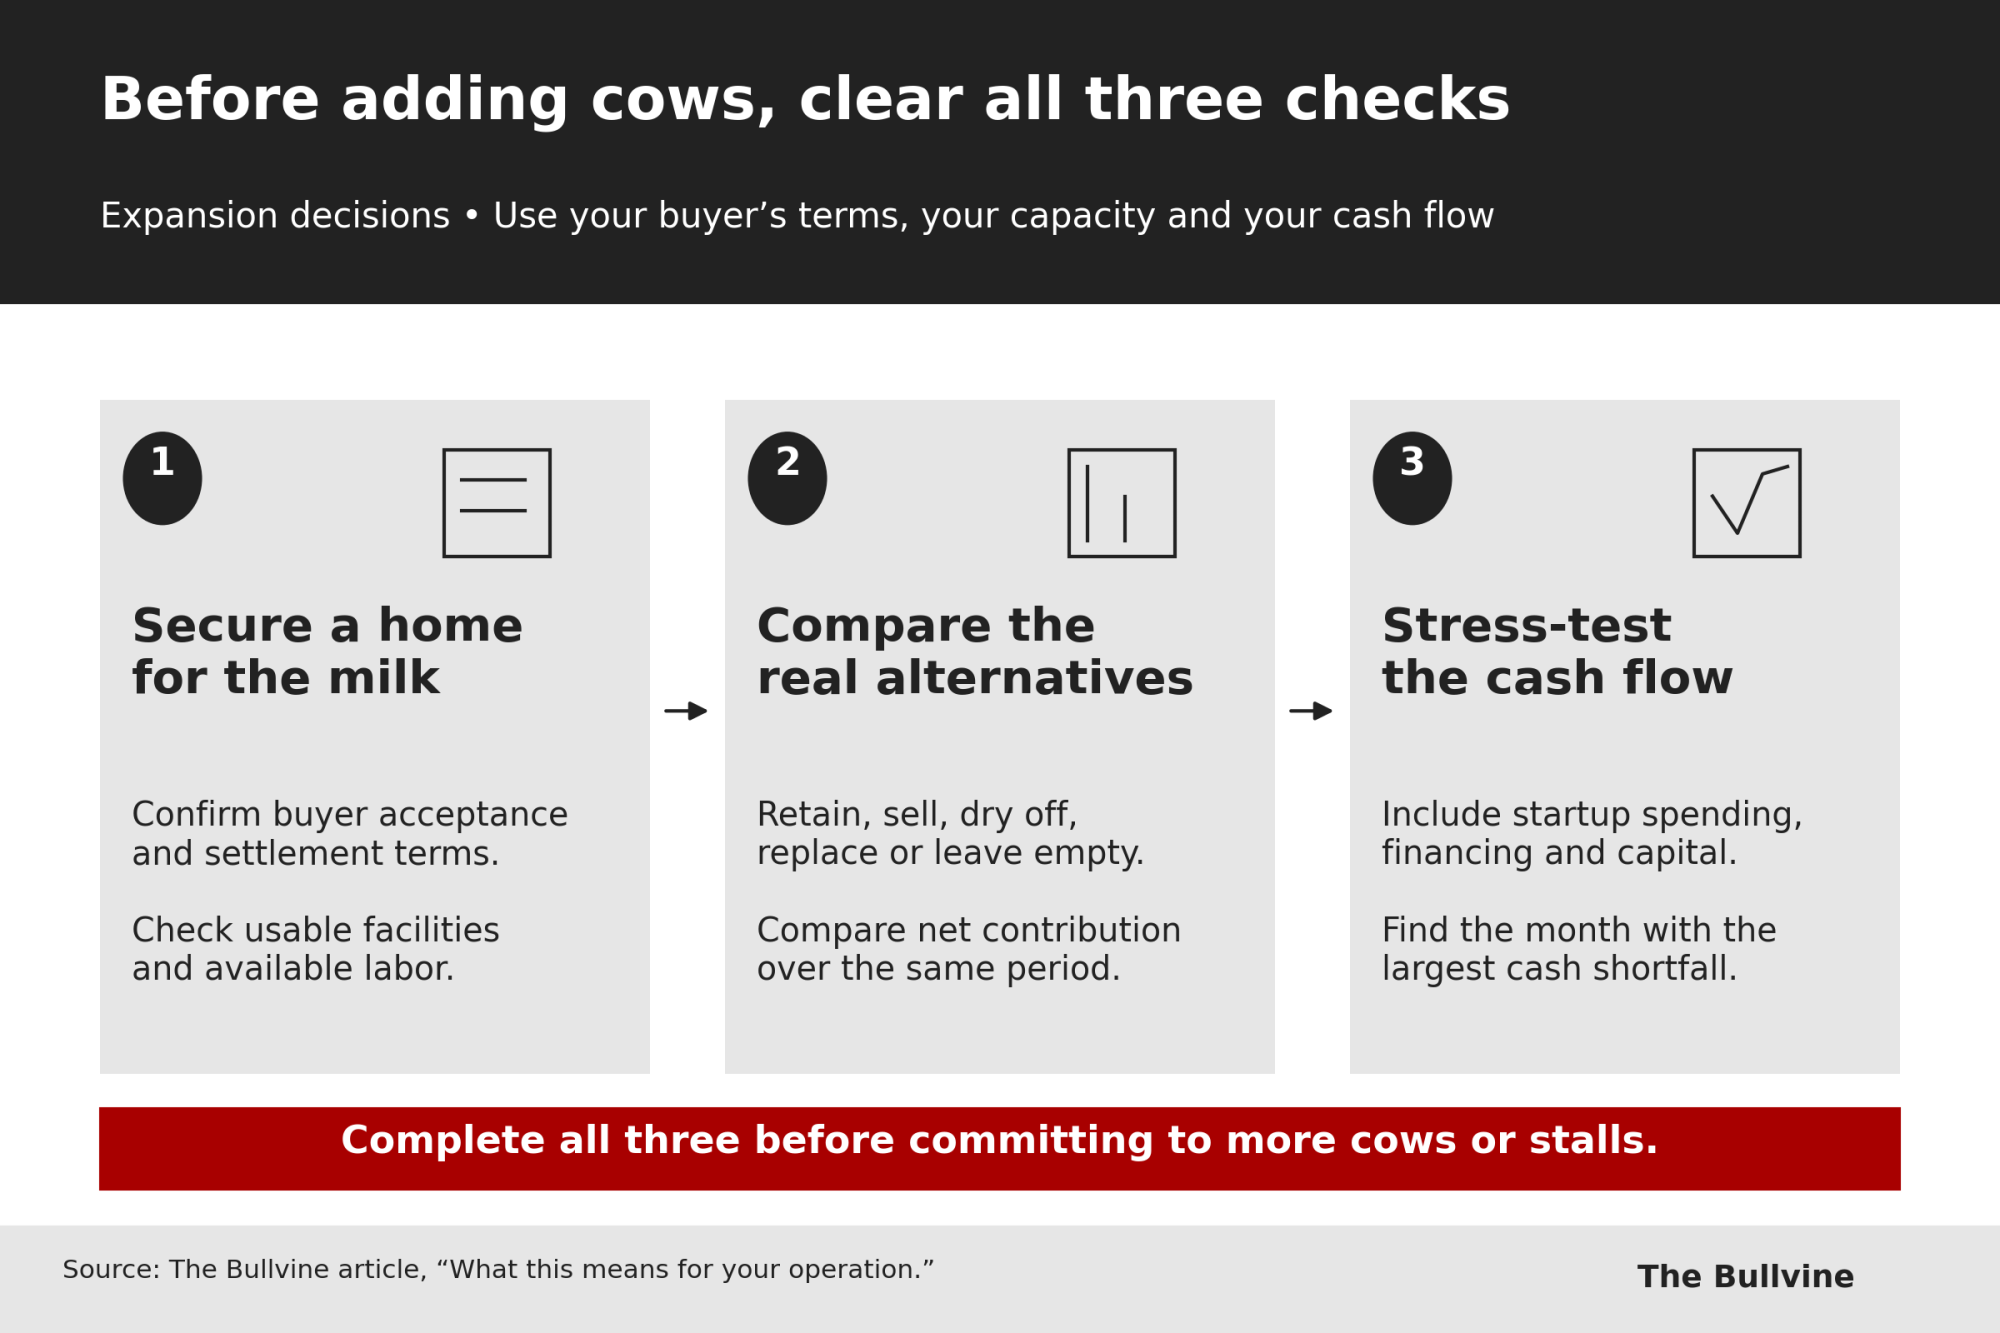
Before committing to additional cows or stalls, run three separate tests through the expansion budget.

  • Compare retention with the alternatives. Set the expected net contribution of keeping a cow against selling her, replacing her or leaving the stall empty, over the same period and including replacement costs and timing. Go ahead only if keeping her comes out ahead.
  • Confirm milk acceptance and usable capacity. Check your settlement terms and whether your buyer will take the added volume. Then confirm your facilities and labor can handle it without spending you haven’t budgeted.
  • Test startup and downside cash needs. Include added labor, replacements, financing and capital, and record net calf and cull receipts separately from milk. Identify the month with the largest cash shortfall. The Bullvine’s Dairy Profit Projector projects 12-month whole-herd margin and breakeven milk price from your own herd, milk and ration inputs. Run it first with cull and calf revenue set to zero, then add your expected receipts. Use the projector as an initial operating-margin screen. Build startup spending, loan payments and capital requirements in a separate monthly cash-flow schedule, checking that costs already included in the operating estimate are not counted twice.
Budget questionSupplied evidence or interpretationLimit / practical use
Does a $9.34 DMC margin mean $9.34 of profit?No. DMC subtracts standardized feed costs from the national all-milk price, not all farm expenses. It also excludes calf receipts, cull-cow income and risk-management payments.The figure triggered payments at $9.50 coverage for participating operations; it establishes neither farm profit nor farm loss.
Can August’s margin establish September’s economics?No. August is the latest margin month in the supplied material; September production is a separate, newer observation.Pair August economics with August production. A September DMC result is not established here.
What should be tested before adding cows?Bullvine interpretation: compare retaining, selling, drying off, replacing or leaving a stall empty over the same period. Confirm buyer acceptance, settlement terms, usable facilities and labor.Compare each option’s additional receipts, costs and timing; national production growth cannot decide the farm budget.
How should calf receipts and expansion cash needs be handled?Bullvine interpretation: record net additional calf and cull receipts separately; include startup spending, financing and capital in monthly cash flow.Avoid assuming calf revenue caused national herd growth or counting cattle receipts and costs twice.

DMC deadline: December 18, 2026. Review your eligible production, coverage options, premiums and existing election with your FSA office before December 18. If you already hold a multiyear election, complete the annual requirements needed to maintain coverage. (USDA FSA, September 30)

For the next monthly budget update, keep August economics paired with August production until the corresponding September margin evidence is available. Then replace the national benchmark with your own milk settlements and costs. Don’t turn a national payment trigger into your farm’s expansion breakeven.

USDA’s figures establish expanding production, a larger herd and a weaker August milk-feed margin. They don’t establish that expansion is universally profitable, or that it’s irrational. Before signing for the next group of replacements, ask the question the national figures can’t answer: at the price and volume your buyer will actually accept, does that group cover its additional costs and required return without an unsupported calf-revenue assumption?

September production findingEvidenceWhat it means
Five states supplied most of the net increaseWisconsin, Kansas, Texas, New York and Idaho added 324 million lb. Bullvine calculation: 324 ÷ 494 × 100 = 65.6% of net 24-state growth.Share of additional pounds—not share of total production or number of expanding farms.
Declining states offset some growthArizona, Utah, Illinois and New Mexico lost a combined 28 million lb. Bullvine calculation: 522 million lb in gross additions − 28 million lb in declines = 494 million lb net growth.Gross additions overstate the increase available across the 24-state market.
National and 24-state growth rates differSeptember national production: 19.443 billion lb, up 2.6% year over year. The 24-state series: 18.724 billion lb, up 2.7%.Keep the geography attached to the growth rate.
More cows supplied most of the reconstructed national increaseSeptember cow numbers rose 169,000; yield rose 18 lb per cow. Bullvine’s decomposition assigns roughly two-thirds to herd size and one-third to yield.The reconstructed gain is 509.656 million lb versus the published 501 million lb; the −8.656 million lb residual remains unassigned. These figures do not explain why farms added or retained cows.

Appendix: Data Reconciliation

How Bullvine calculated this

  • Production split: monthly production equals milk cows multiplied by milk per cow, using USDA’s national figures from the October 22 release for every month shown.
  • Cow contribution: change in cow numbers × prior-year milk per cow.
  • Yield contribution: prior-year cow numbers × change in milk per cow.
  • Interaction: change in cow numbers × change in milk per cow.
  • Units: USDA publishes cows in thousands; they’re converted to head before multiplying, and results are in million pounds.
  • Rounding: The published cow, yield and production figures do not reconcile exactly when multiplied.USDA notes that figures may not add because of rounding. Bullvine shows the residual without assigning it to either contribution.
  • State shares: each state’s added pounds divided by the 494-million-pound net 24-state increase.Subtotals are summed from the state rows. Because some states declined, gross additions (522 million pounds) exceed the net gain.
  • Margin change: August 2025 and August 2026 DMC values from the ERS October outlook chart; the dollar and percentage changes are Bullvine calculations.

September 2026 vs. September 2025, national
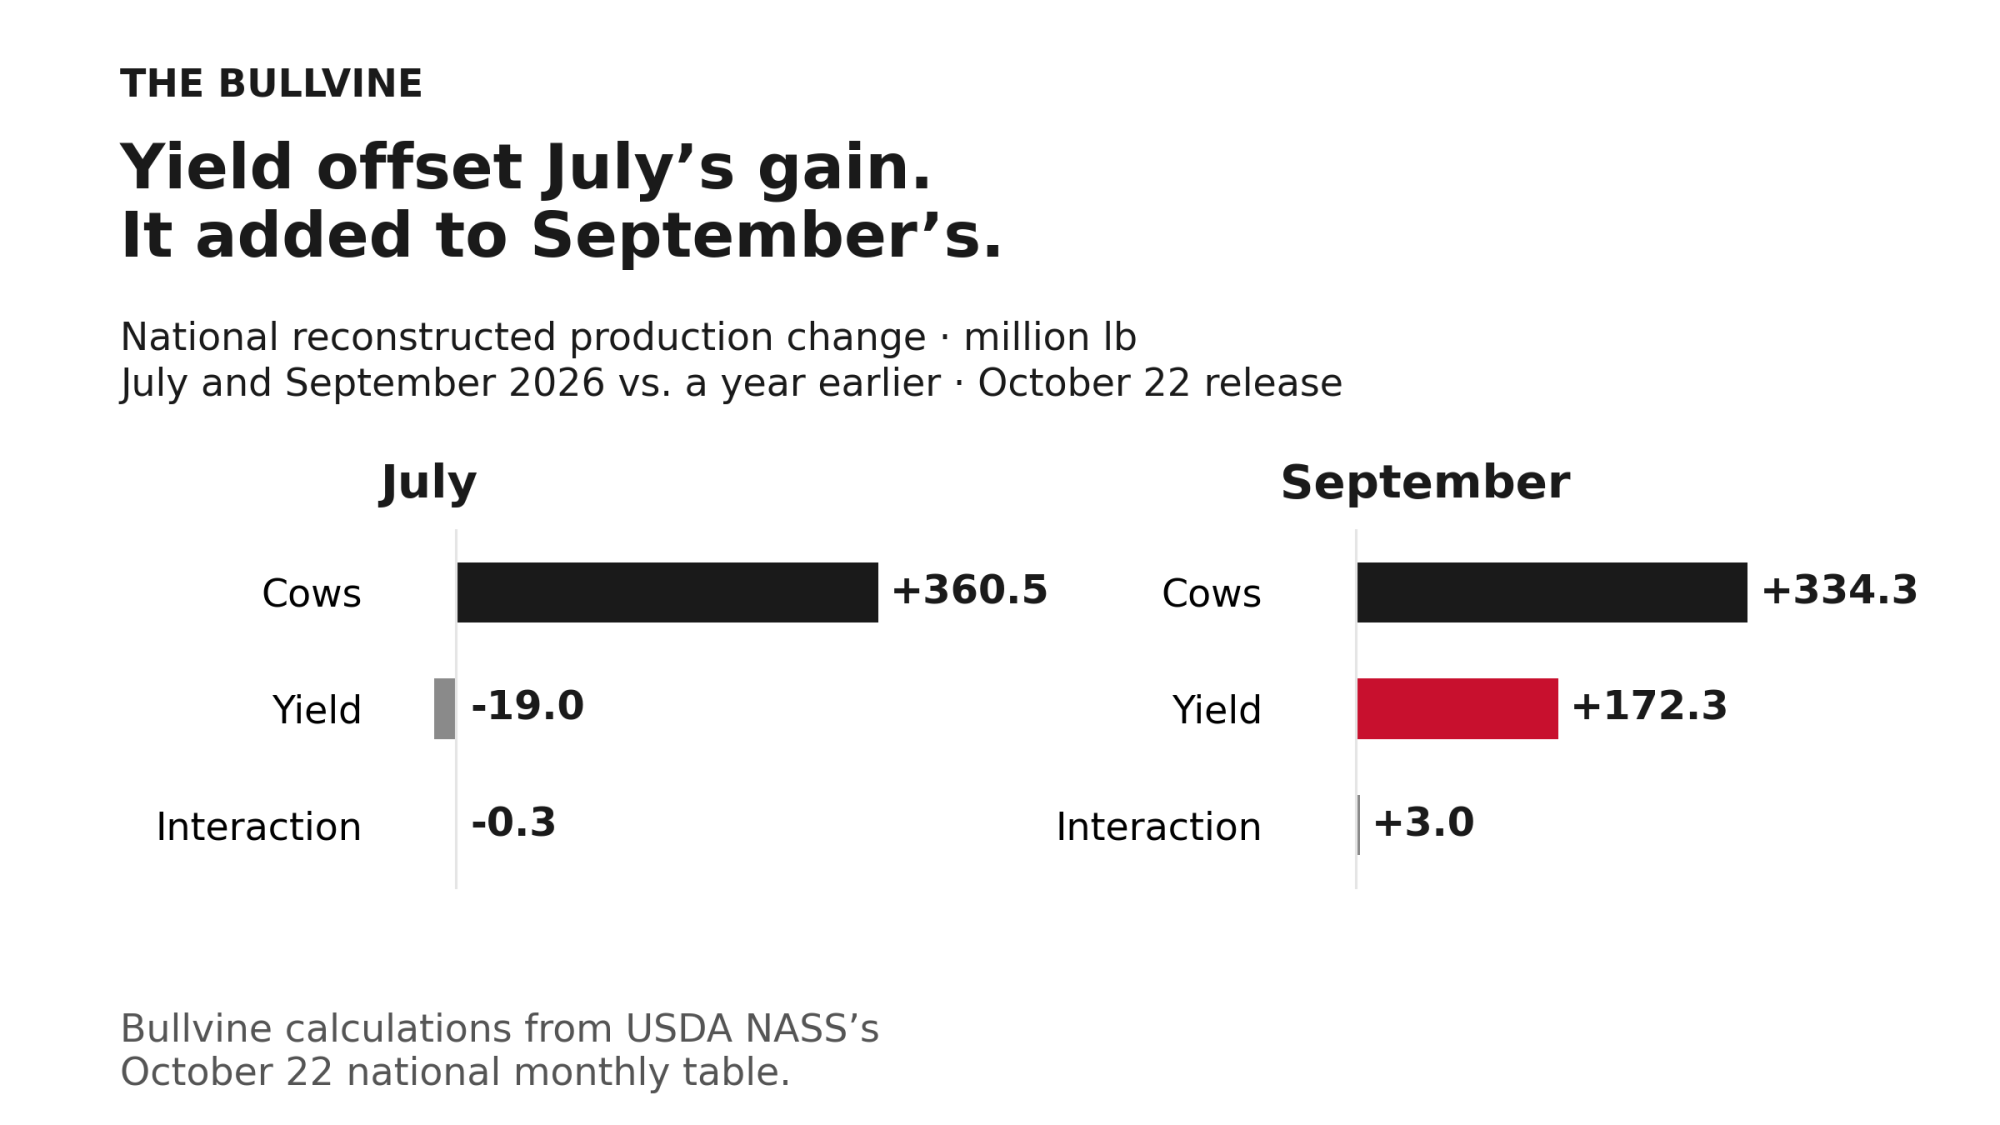
Yield contributed −19.0 million lb in July and +172.3 million lb in September; cow contributions were +360.5 and +334.3.
TermInputsM lb
Cow term169,000 × 1,978 lb334.282
Yield term9,574,000 × 18 lb172.332
Interaction169,000 × 18 lb3.042
RebuiltSum of three509.656
Published19,443 − 18,942501.000
ResidualPublished − rebuilt−8.656

July vs. September, national (October 22 release)

TermJul 2026Sep 2026
Cows YoY+174,000+169,000
Milk/cow YoY−2 lb+18 lb
Cow term+360.5M+334.3M
Yield term−19.0M+172.3M
Interaction−0.3M+3.0M
Published+341.0M (+1.7%)+501.0M (+2.6%)
Residual−0.2M−8.7M

Bullvine calculations, not USDA attribution. Figures in million pounds. Both months come from USDA’s October 22 national monthly table.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.

NewsSubscribe
First
Last
Consent

Dairy Markets on A Knife’s Edge: Spring 2025’s Make-Or-Break Moment for Producers

Dairy markets plunge as milk floods markets. Can producers adapt to heifer shortage and avian flu impacts?

EXECUTIVE SUMMARY: U.S. dairy markets face intense pressure as milk production surges (+1% YOY to 17.73M lbs in February) while prices plummet: butter (-4¢), cheese blocks (-9¢), and barrels (-14¢) hit multi-month lows. Despite historic heifer shortages, herds expanded to 9.405M head, driven by lower cull rates. Component production booms—cream output up 12.7M lbs YOY, milk protein +3.1%—but processors struggle with oversupply. Regional disparities sharpen due to avian influenza (California down 3.8%) and growth in Texas/Idaho. Futures indicate painful near-term margins (Class III .95/cwt), but export opportunities and feed cost savings (10.1% YOY) offer lifelines. Producers must prioritize cost control, component optimization, and strategic culling to survive the squeeze.

KEY TAKEAWAYS

  • Herd Expansion Defies Logic: 9.405M cows (+62k YOY) despite heifer shortage, driven by low cull rates.
  • Component Wars: Butterfat surges (+12.7M lbs cream) dominate, but protein growth (+3.1%) lags behind demand.
  • Regional Crisis: California production plummets (-3.8% YOY) from avian flu, while Texas/Idaho thrive.
  • Futures Forecast Pain: Class III futures at $17.95/cwt threaten margins; Q4 rebound potential hinges on exports.
  • Strategic Solutions: Lock in sub-$4.70 corn, target 3.5% butterfat herds, and consider culling low-performing cows.
dairy market trends 2025, USDA milk production, avian influenza dairy impact, dairy component pricing, Class III futures forecast

The whey market’s 5¢ rally to 50¢/lb this week fooled nobody who’s read a milk check lately. USDA’s Dairy Market News confirms what every producer knows – demand remains “lackluster” with inventories ballooning. This dead-cat bounce comes as:

  • Butter crashes 4¢ to $2.3025/lb
  • Cheese blocks nosedive 9¢ to $1.6025
  • Barrels implode 14¢ to $1.55 – an 11-month low[3]

“Buyers play hardball below 50¢,” says our Chicago floor contact. “With milk flows increasing, this whey rally has expiration date written all over it.”

MILK FLOODGATES OPEN AS HERD EXPANSION DEFIES LOGIC

USDA’s March shocker: 9.405 million head in February – highest since May 2023. How?

HERD GROWTH DESPITE HEIFER ARMAGEDDON

MetricFeb 2025Change YOY
Total Dairy Cows9.405M+62k
Heifers 500lb+3.914M-7% (1978 low)
Cull Rate (Jan-Feb)89k below historic avg

Producers are playing musical barns – 15k cows added in February alone. The result? 17.73M lbs February output (+1% YOY leap-adjusted) – biggest jump since 2023.

COMPONENT WARS: FAT’S WINNING, PROTEIN’S FUTURE UNCERTAIN

The real money’s in what’s IN your milk:

FEBRUARY COMPONENT SURGE

ComponentProduction IncreaseEquivalent Product
Butterfat+12.7M lbs cream15.5M lbs butter
Protein+3.1% YOY620k lbs cheese
Nonfat Solids+2.3% YOY9.2M lbs NFDM

“Processors are fat-hungry,” notes USDA economist Dr. Mark Svennson. “That $2.30 butter price? Still 18% above 5-year average. The fat premium’s alive.”

COAST-TO-COAST CRISIS: BIRD FLU DECIMATES WESTERN HERDS

Avian influenza isn’t just a poultry problem anymore:

STATE-LEVEL MILK PRODUCTION

RegionYOY ChangeKey Factor
California-3.8%62% herds infected
Texas+4.1%New mega-facilities
Pacific NW-2.9%Historic basis discounts
Upper Midwest+1.3%Component focus

“California’s looking at 5% production drop by June if culling continues,” warns Western United Dairies’ Janelle Hasser.

FUTURES FORECAST: PAIN BEFORE GAIN?

USDA’s revised projections paint a grim near-term picture:

2025 PRICE PROJECTIONS

MetricMarch EstimateChange vs FebProfit Threshold
All-Milk Price$21.60/cwt-$1.00$22.00+
Class III$17.95/cwt-$1.15$19.50
Class IV$18.80/cwt-$0.90$20.00
Feed Cost Savings10.1% YOYCorn $4.85/buSoymeal $395/ton

“Q4 could see $19.75 Class III,” says CME analyst Luke Torrison. “But getting from here to there will bankrupt marginal operators.”

THE BULLVINE BOTTOM LINE: ADAPT OR EXIT

  1. Cost Crunch Calculus: Lock in sub-$4.70 corn now – USDA sees 2025 feed savings offsetting 14% of milk price decline.
  2. Component Premium Play: 3.5% BF herds now capturing $0.47/cwt premium over 3.0% herds.
  3. Exit Strategy Window: Beef prices at $1.92/lb make culling profitable – 12% ROI on heifer-replacement deferral.

As one Wisconsin producer told us: “I’m feeding more haylage, culling 5% low-end cows, and praying Class IV finds its legs by June. If not? The auctioneer’s getting my Rolodex.”

LEARN MORE

  1. DAIRY MARKET WARNING: How The Egg Price Collapse Reveals Your Farm’s Hidden Vulnerabilities
    Analyzes parallels between the egg market collapse and dairy’s consumer price resistance risks, offering strategies to mitigate volatility.
  2. CME Dairy Market Analysis: Trade War Drama Sends Cheese Prices Plunging to 11-Month Lows
    Examines the impact of U.S. tariffs and international trade tensions on cheese and butter markets, with actionable producer recommendations.
  3. CME Dairy Market Report: March 17, 2025: Cheese and Butter Prices Fall Amid Seasonal Supply Increases
    Provides granular analysis of the latest CME price declines, bird flu disruptions, and plant-based competition shaping dairy’s Q2 outlook.

Join the Revolution!

Join over 30,000 successful dairy professionals who rely on Bullvine Daily for their competitive edge. Delivered directly to your inbox each week, our exclusive industry insights help you make smarter decisions while saving precious hours every week. Never miss critical updates on milk production trends, breakthrough technologies, and profit-boosting strategies that top producers are already implementing. Subscribe now to transform your dairy operation’s efficiency and profitability—your future success is just one click away.

NewsSubscribe
First
Last
Consent

CME Dairy Market Report February 19, 2025: Butter Soars, Cheese Stumbles

Butter prices surged 3.00¢/lb today on tightening inventories and strong global demand, while cheddar blocks fell 2.25¢/lb amid Mexico’s proposed 25% retaliatory tariffs. USDA’s revised milk production forecast (-0.3B lbs) and New Zealand’s export competition signal transformative shifts, with Class III futures dropping to $19.15/cwt on cheese market pressures

Summary:

The CME dairy market on February 19, 2025, painted a mixed picture, with butter prices surging 3.00¢ to $2.4400/lb on strong export demand and tight inventories, while cheese markets retreated. Cheddar blocks fell 2.25¢ to $1.8975/lb, and barrels dropped 0.75¢ to $1.8075/lb, reflecting weak trading activity and uncertainty surrounding potential Mexican tariffs. Nonfat Dry Milk and Dry Whey both declined 1.00¢ to $1.2700/lb and $0.5450/lb respectively, due to subdued global demand. The USDA revised its 2025 milk production forecast downward to 227.9 billion pounds, with an all-milk price projection of $23.05/cwt. Class III futures for March settled at $19.15/cwt, down 2.4% week-over-week, mirroring cheese market weakness. Feed costs showed some relief with corn futures dropping to $4.8675/bu, though soybean meal edged up to $294.80/ton. Market sentiment remains cautiously optimistic for butter but bearish for cheese, with traders closely monitoring export developments and feed cost volatility.

Key Takeaways:

  • Butter prices jumped 3.00¢ to $2.4400/lb, driven by strong export demand and tight inventories.
  • Cheese markets declined: blocks fell 2.25¢ to $1.8975/lb, barrels dropped 0.75¢ to $1.8075/lb.
  • Potential 20-25% Mexican tariffs on U.S. cheese exports are creating market uncertainty.
  • USDA lowered its 2025 milk production forecast to 227.9 billion pounds.
  • All-milk price projection for 2025 stands at $23.05/cwt, up 2.7% year-over-year.
  • Class III futures (March) settled at $19.15/cwt, down 2.4% week-over-week.
  • Feed costs showed mixed signals: corn futures dropped to $4.8675/bu, while soybean meal rose to $294.80/ton.
  • Global competition intensifies with EU-Japan and New Zealand-Vietnam trade deals threatening U.S. exports.
  • Traders recommend hedging 50% of Q2 corn needs below $4.90/bu.
  • Market sentiment: cautiously optimistic for butter, bearish for cheese due to trade risks.
butter prices, cheese market, USDA milk production, Mexican tariffs, global dairy competition

“Butter Prices Jump 3.00¢ on Export Surge; Cheese Markets Stumble Amid Mexican Tariff Uncertainty”

Key Price Changes & Market Trends 

ProductClosing PriceChange from Yesterday
Cheese (Blocks)$1.8975/lb-2.25¢
Cheese (Barrels)$1.8075/lb-0.75¢
Butter$2.4400/lb+3.00¢
Nonfat Dry Milk$1.2700/lb-1.00¢
Dry Whey$0.5450/lb-1.00¢

Commentary:
Butter led gains with a 3.00¢/lb surge fueled by tightening domestic inventories and robust foodservice demand, despite a 7% YoY increase in U.S. butter stocks7. Cheese markets declined sharply, with blocks dropping 2.25¢/lb and barrels 0.75¢/lb, reflecting stalled export momentum as Mexico threatens 20-25% tariffs on $950M in annual U.S. cheese exports. Nonfat Dry Milk (NDM) and Dry Whey fell 1.00¢/lb each amid weak global demand, particularly in Southeast Asia where New Zealand’s whey prices undercut U.S. offers.

Volume and Trading Activity 

  • Butter: 18 trades executed with active bids/offers at $2.4400/lb, signaling commercial hedging ahead of Q1 inventory reports.
  • Cheese: Zero trades for blocks/barrels—the first inactive session since November 2024—as buyers await clarity on Mexico’s retaliatory measures.
  • NDM: 2 trades at $1.2700/lb, aligning with USDA’s revised 2025 skim-solids export forecast of 49.1B lbs(-0.4B lbs).

Global Context 

  • CAFTA-DR Impact: U.S. dairy exports to Central America hit $441M in 2025 (up 1,117% since 2006), but Nicaragua’s $42k/shipment port fees and El Salvador’s 72-day approval delays hinder growth.
  • EU Competition: EU-Japan trade deals threaten $1.3B in U.S. cheese exports by 2030, while New Zealand secured 45% tariff cuts in Vietnam.
  • Canada’s Grade A Standards: U.S. exporters face hurdles meeting Canada’s “substantially equivalent” certification for fluid milk, risking $450M in annual sales.

Forecasts and Analysis 

  • USDA Revisions: The 2025 milk production forecast has been lowered to 227.9B lbs (-0.3 B lbs), and all milk prices are projected at $23.05/cwt (+2.7% YoY).
  • Class III/IV Futures:
    • Class III (MAR) fell to $19.15/cwt (-2.4 % WoW) on cheese weakness.
    • Class IV (MAR) held at $19.15/cwt, supported by Butter’s rally7.
  • Feed Costs: Corn (MAR) dropped to $4.8675/bu (-3.0% WoW), but soybean meal edged to $294.80/ton, pressuring margins.

Market Sentiment 

  • Trader Insight: “Butter’s rally is sustainable through Q2, but cheese needs tariff relief to rebound,” noted a CME floor broker.
  • Analyst View: Corey Geiger (CoBank) emphasized, “Mexico buys 25% of U.S. dairy exports—losing this market would crater farmgate prices”.
  • Overall: Cautious optimism for butter, bearish cheese sentiment on trade risks.

Closing Summary & Recommendations 

Summary: Butter’s rally (+3.00¢) contrasted with cheese’s tariff-driven slump, while feed cost volatility persists.

Action Items:

  1. Export Diversification: Leverage CAFTA-DR’s $527M export potential by targeting Guatemala’s bakery sector (NDM) and Honduras’ artisanal cheese demand.
  2. Risk Management: Hedge 50% of Q2 corn needs below $4.90/bu using DEC futures at $4.7575/bu.
  3. Compliance Prep: Audit facilities for Canada’s Grade A equivalence to avoid $1.2B in retaliatory tariffs.

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

U.S. Milk Production Dips in December 2024: What It Means for Dairy Farmers

U.S. dairy production dipped slightly in December 2024, but what does this mean for farmers? From regional challenges to efficiency gains, the latest USDA report reveals a complex picture. Discover how the industry is adapting and what strategies could shape the future of American dairy farming.

Summary:

The USDA’s December 2024 report shows a tiny drop of 0.5% in U.S. milk production, with California having a big drop of 6.8%, while other states went up by 1.0%. This might make milk prices go up, which is good for farmers. Even though 9,000 cows were removed from herds between November and December, cows on average still produce 2,020 pounds of milk. Milk prices for 2025 vary; for example, Cheddar cheese is expected to be cheaper. Farmers need to focus on getting more milk from each cow and plan for their local challenges, especially in California. The USDA also predicts a small increase in milk production for 2025, offering hope for the future.

Key Takeaways:

  • California’s milk production struggles contrast with the slight growth seen in other regions, indicating varied regional challenges.
  • Overall milk production decline might stabilize or increase milk prices, offering potential financial relief for dairy farmers.
  • With a marginal reduction in herd size and productivity, focus on enhancing cow efficiency becomes crucial for productivity.
  • Upcoming USDA milk production growth forecast for 2025 provides a positive outlook for potential industry recovery.
  • Diverse price forecasts for different dairy products necessitate strategic adaptations to navigate future market trends.
USDA Milk Production, dairy output decrease, cow productivity, California dairy farmers, milk production growth

The latest USDA Milk Production report for December 2024 reveals significant insights for U.S. dairy farmers. It indicates a slight drop in U.S. dairy output, a trend that could have implications for the industry.  

Report Highlights: 

  • December 2024 milk production down 0.5% from last year
  • California production down 6.8%, rest of U.S. up 1.0%
  • 9,000 fewer cows in the national herd from November to December
  • Cows in 24 major states averaged 2,020 pounds of milk in December

Milk Production: The Big Picture 

StateMilk Production (billion lbs)Change from Previous YearAvg. Milk per Cow (lbs)
California2.99-6.8%Not Available
Wisconsin2.69-0.5%2,125
Texas1.42-3.86%Not Available
Michigan1.02-0.3%2,345
ColoradoNot AvailableNot Available2,190

U.S. milk production in December 2024 decreased marginally by 0.5% compared to the previous year. This slight drop could stabilize or even elevate milk prices, benefiting farmers’ financial health. 

California, usually a top milk-producing state, is still experiencing challenges. Its production dropped 6.8% from last year. But there’s a bright spot: the rest of the country saw a slight increase of 1.0%. This indicates that while some areas are improving, others face challenging times. 

Michigan’s cows are the top performers, averaging 2,290 pounds of milk each. Colorado comes in second at 2,190 pounds per cow. Despite its challenges, California still produces the most milk overall at 2.99 billion pounds, followed by Wisconsin with 2.59 billion pounds and Texas with 1.42 billion pounds. 

Herd Size and Cow Productivity 

The report shows some interesting changes in herd management: 

  • Farmers removed 9,000 cows from their herds between November and December 2024.
  • The 24 central dairy states had 8.91 million cows total, which is 17,000 more than last year
  • Each cow produced an average of 2,020 pounds of milk in December, eleven pounds less than last year

These numbers tell us that while there are slightly more cows than last year, farmers recently cut back their herds. Even though each cow is producing a little less milk, some farms are still finding ways to be more efficient.  Farmers’ resilience in managing herd size adjustments is a testament to their adaptability in challenging conditions. This adaptability is a key strength of the industry and a source of inspiration for others.

What This Means for the Market 

This report brings both good and bad news for dairy farmers: 

  1. Prices May Remain Stable: Due to a slight decrease in milk production, prices are expected to remain steady or experience slight fluctuations due to this decrease.
  2. Different Regions, Different Stories: Farmers outside California might have room to grow, while California farmers still face challenges.
  3. Focus on Cow Efficiency: Since adding more cows is challenging, Farmers should explore ways to maximize milk production from each cow in their herds.
  4. California Needs Help: California dairy farmers might need new strategies or support to get back on track.

The USDA predicts a 0.8% growth in total milk production in 2025 compared to 2024. This forecast suggests a gradual improvement in U.S. milk production, offering a ray of hope for dairy farmers. 

Milk and Dairy Product Prices 

The USDA has updated its price forecasts for 2025: 

  • Cheddar cheese: $1.800 per pound (down 9.5 cents)
  • Nonfat dry milk: $1.300 per pound (up 4.0 cents)
  • Dry whey: $0.595 per pound (up 7.5 cents)
  • Butter: $2.685 per pound (down 7.0 cents)

Due to these changes, the 2025 Class III milk price forecast is slightly lower. However, strong demand in the U.S. and less dairy in storage might help keep prices up. 

Key Recommendations for Action 

  • Get more from each cow: Since it’s hard to add cows, try to increase how much milk each cow produces.
  • Adapt to your area: Use strategies that work for your local conditions and market.
  • Keep an eye on prices: Stay updated on USDA price forecasts to help plan your milk sales.
  • Think about specialty products: Consider making specialty or high-protein dairy products to tap into growing markets.

The Bottom Line

The December 2024 Milk Production report shows that U.S. dairy farmers are resilient and can handle challenges. They deal with different production levels in various areas and managing herd sizes. However, there’s still a chance for growth and improving efficiency. As the industry changes, farmers should focus on making the most of their resources, understanding their local markets, and finding ways to grow slowly and steadily. To succeed, farmers can try new ways to boost milk from each cow, keep up with consumer preferences, learn about new farming tech, and stay informed about global markets. By doing these, American dairy farmers can tackle challenges and seize future opportunities by being innovative and adaptable.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Dairy Market Shake-Up: Understanding the Unexpected Milk Production Increase

Delve into the surprising uptick in US milk output. How does it impact dairy farmers? Uncover insights and challenges in the latest market analysis.

Summary:

In this week’s US Dairy Market Report, the USDA’s findings indicate a modest rebound in national milk production, ending a year-long decline with a 0.1% increase in September and revised August figures showing a 0.4% rise. The national dairy herd remains stable at 9.328 million head, with milk yield per cow up 0.5%, enhancing the milk’s manufacturing value. Regionally, Texas and Idaho show strong growth, exhibiting a 4.9% and 1.8% increase, respectively, while the H5N1 outbreak impacts California and Wisconsin, experiencing a 0.5% decline. Cheese prices have dipped due to easing milk supplies, yet demand maintains tight inventories, whereas butter supplies are increasing, contrasting with the cheese stock trends. Meanwhile, dry whey remains stable, and favorable weather boosts corn and soybean harvests, which are vital for dairy feed, despite ongoing price volatility. Readers are encouraged to delve into these findings further and share their insights.

Key Takeaways:

  • Milk production in the U.S. surprised by increasing 0.1% year over year in September, with the August figure revised to a 0.4% gain.
  • The national dairy herd remained stable from the previous month but is down by 38,000 head compared to last year.
  • Regional disparities exist, with California’s production steady, Wisconsin witnessing a decline, and Texas showing robust growth.
  • Cheese production remains high, yet inventories continue to shrink, indicating strong domestic and international demand.
  • Butter inventories have grown, reflecting strong production fueled by high butterfat levels, but market movement has slowed.
  • In the Nonfat Dry Milk sector, modest price movements contrast with significant trading activity; California restrictions pose challenges.
  • Whey markets stabilize with steady prices, driven by strong demand for higher protein products, keeping supplies balanced.
  • Favorable weather supports an ahead-of-schedule harvest for corn and soybeans, contributing to positive feed supply prospects.
US Dairy Market Report, USDA milk production, national dairy herd, milk yield per cow, Texas Idaho dairy growth, cheese prices decline, butter supplies increase, dry whey stability, corn soybean harvests, dairy feed prices volatility

What just happened? Dairy market analysts are abuzz after the USDA’s unexpected Milk Production report revealed a surprising upswing, reversing expectations with a notable turnaround. The report showed 0.1% year-over-year growth in September, supported by a revised 0.4% increase for August, suggesting a potential shift in U.S. dairy farmers‘ fortunes. But is this a sign of prolonged recovery or just a temporary peak before another dip?  Let’s see if this could mean closing the chapter on falling milk production or if more twists are ahead in the churn. 

MonTueWedThurFriCurrent Avg.Prior Week Avg.Weekly Volume
Butter2.73002.67752.65502.65002.69502.68152.641015
Cheddar Block1.92001.89001.92001.92001.90001.91001.92205
Cheddar Barrel1.98001.91001.90751.87501.87001.90851.93709
NDM Grade A1.38751.36001.36001.36001.37501.36851.359032
Dry Whey0.60250.60250.60250.60500.60500.60350.597013

Unexpected Revival: USDA Report Highlights Growth in Milk Production as Farmers Regain Momentum

The USDA’s latest Milk Production report reveals a slight uptick in year-over-year milk production, marking a 0.1% increase for September. In a surprising turn, August figures were amended from a loss to a 0.4% increase, shifting the narrative on recent production trends. The national dairy herd remains stable at 9.328 million head, although it is 38,000 head smaller than last year’s. 

The 0.5% rise in milk yield per cow is a crucial contributor to these figures. This increase boosts current production and opens up potential growth avenues for the future. Milk component levels have also grown, enhancing milk’s overall manufacturing value. These adjustments and enhancements underline significant trends in dairy production efficiency and potential growth avenues.

Regional Dynamics: Navigating Challenges and Seizing Opportunities in Dairy Production

The recent Mixed Regional Performance in milk production reveals statistical variance and underlying challenges and opportunities within key dairy states. California’s output remained unchanged compared to last year, but the impact of the H5N1 outbreak, a highly pathogenic avian influenza, casts a shadow on the future. This unforeseen factor threatens to disrupt production further in the coming months, potentially destabilizing the state’s substantial contribution to national totals. 

Wisconsin, on the other hand, saw a 0.5% decline in production. This downturn in the Upper Midwest underscores ongoing struggles with herd health and other operational challenges. However, Idaho, Texas, and New York provide a silver lining. Idaho’s production rise of 1.8%, coupled with Texas’s impressive 4.9% increase and New York’s modest 1.2% gain, suggest that regional dynamics are nuanced but pivotal in offsetting losses elsewhere. 

The varied performances highlight a delicate balancing act in the overall market. Gains in states like Texas and New York are vital, offering resilience against declines in other regions. These disparities also influence supply allocations, with areas of growth possibly playing a more significant role in fulfilling demand, especially during the upcoming holiday season. Regional differences could dictate milk pricing, availability, and export potential, urging farmers and industry professionals to remain agile and informed.

The Cheddar Conundrum: Navigating the Cascade of Surplus and Pricing Challenges in a Complex Market

The increased milk supplies have put downward pressure on cheese prices, a shift vividly illustrated by the decline in cheddar prices at the CME. When milk is more readily available, dairy processors can ramp up production, leading to an abundance of cheese, particularly cheddar, in the market. This supply spike and steady export demand make for a tricky balancing act. In the short term, an oversupply, as seen with the swelling cheese inventories despite robust demand, inevitably leads to price declines. 

Historically, muted activity in the cheese market often coincides with a narrow block-barrel spread, typically around the historical average of 3¢. This spread measures the price difference between cheddar blocks and barrels at the CME, reflecting supply-demand dynamics. When milk supplies increase and processors pivot towards higher cheese production, the resulting surplus prompts limited buy-and-hold strategies among traders—this week reflected such cautious market behavior, with only a handful of trading loads moving. Consequently, the cheddar market expressed its turmoil through price contractions, particularly in barrels, which saw more pronounced dips. These developments highlight the industry’s intricate dance with supply and pricing, demanding strategic foresight from all stakeholders involved.

Divergent Paths: Navigating the Contrasting Trends in Cheese and Butter Inventories

Cheese and butter inventories are heading in opposite directions, with cheese stocks consistently declining while butter inventories continue to grow. This divergence can be attributed to several key factors influencing each market differently. 

On one hand, cheese inventories have been shrinking for the seventh consecutive month, as evidenced by the USDA’s Cold Storage report. The robust demand for cheese, both domestically and internationally, particularly in strong export markets, is likely driving this trend. This solid demand helps offset any potential surplus, keeping inventory levels in check despite production running higher than in previous years. 

Conversely, butter inventories have grown year over year, underscoring a different set of dynamics. One significant factor fueling this increase is the high butterfat content in milk, which boosts butter production. Manufacturers struggle to match production with market demand, leading to increased stockpiles. This mismatch has been evident in the price fluctuations over the past month. 

While cheese stocks dwindle due to persistent consumer and export demand, butter inventories build as production outpaces market movement. These contrasting trends highlight dairy producers’ unique challenges and opportunities in balancing output with evolving market conditions.

Balancing Act: Navigating the Nonfat Dry Milk and Whey Market Dynamics Amidst Production Challenges

The nonfat dry milk (NDM) and whey markets are navigating their unique challenges and dynamics in the ever-complex dairy product landscape. This week, the NDM market saw a modest decrease, surrendering half a cent to close at $1.375/lb. Despite this minor dip, the trade was notably active, with 32 loads exchanging hands. While milk production gains some ground, California-specific restrictions, such as water usage regulations and environmental policies, might continue overshadowing NDM production capabilities. This bottleneck could persist, affecting supply and potentially influencing prices. 

Mexican buyers are a dynamic player in these movements. They still show significant activity in the NDM market, and their ongoing demand is crucial. Their demand could serve as a stabilizing force even amidst production uncertainties. Their consistent demand helps maintain a certain level of market activity and influences price stability in the NDM market. 

Meanwhile, the whey market is entangled in a dual scenario. On the one hand, the increased cheese production flows a substantial whey stream into the market. On the other hand, high demand for whey-derived protein products restricts the amount of raw whey available for drying. These counterbalancing factors have kept dry whey prices steady, ending the week at a comfortable 60.5¢ per pound, with a slight increase of just a quarter of a cent from the previous week. With 13 loads transacted at the CME, the market displays an equilibrium that reflects inherent supply and demand tensions.

Corn and Soybean Harvests: The Unsung Heroes of the Dairy Supply Chain

The backdrop of the current dairy market unfolds amidst a captivating agricultural landscape. As we delve deeper, the corn and soybean harvests emerge as pivotal players. This season, timely weather patterns have granted farmers a head start, leading to harvest figures that exceed historical averages. The USDA’s Crop Progress report sheds light on these developments, with 65% of corn and 81% of soybeans already being harvested, compared to their respective five-year averages of 52% and 67%. 

These bumper harvests are not just numbers on a page; they substantially impact feed supplies for dairy farms. An abundant harvest typically translates to more accessible and affordable feed options, which impacts production costs and can influence milk output across the country. This ripple effect is vital for dairy producers as they navigate market challenges. 

However, the landscape has its complexities. As corn futures take an upward turn, with the MAR25 corn contract reaching $4.35/bu., the financial calculus for feed procurement becomes more intricate. Meanwhile, the softening of soybean meal futures, settling at $310.20/ton for the JAN25 contract, offers a counterbalance, presenting a mixed bag of opportunities and challenges for dairy farmers keenly watching their bottom lines.

The Bottom Line

The USDA’s latest report unexpectedly reports a surge in September milk production, signaling a shift from the previous trend of declining output. This growth is coupled with regional variances, where some states, like Idaho and Texas, experience significant increases while others, such as Wisconsin, face reductions. The complexity of markets is evident, with cheese prices declining due to increased milk supply while butter inventories rise, reflecting divergent industry paths. 

These trends present both opportunities and challenges for dairy farmers. An increased milk supply could impact prices and revenue, but it also offers the prospect of increased production volume. Meanwhile, region-specific conditions and global market demands must be navigated strategically. 

As we witness these shifts, it’s crucial to contemplate how your dairy operations might adapt or take advantage of these emerging trends. What strategies could optimize production under these circumstances? Feel free to share your thoughts or engage with the community below. 

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent
Send this to a friend