Archive for milk supply contracts

Chobani’s Rome Plant Needs Up to 2 Million Pounds of Milk a Day for Phase 1. Who Carries the Expansion Risk?

IDFA’s count of planned dairy processing investment has passed $15 billion. The Bullvine found no public document committing any of it to a supplying farm.
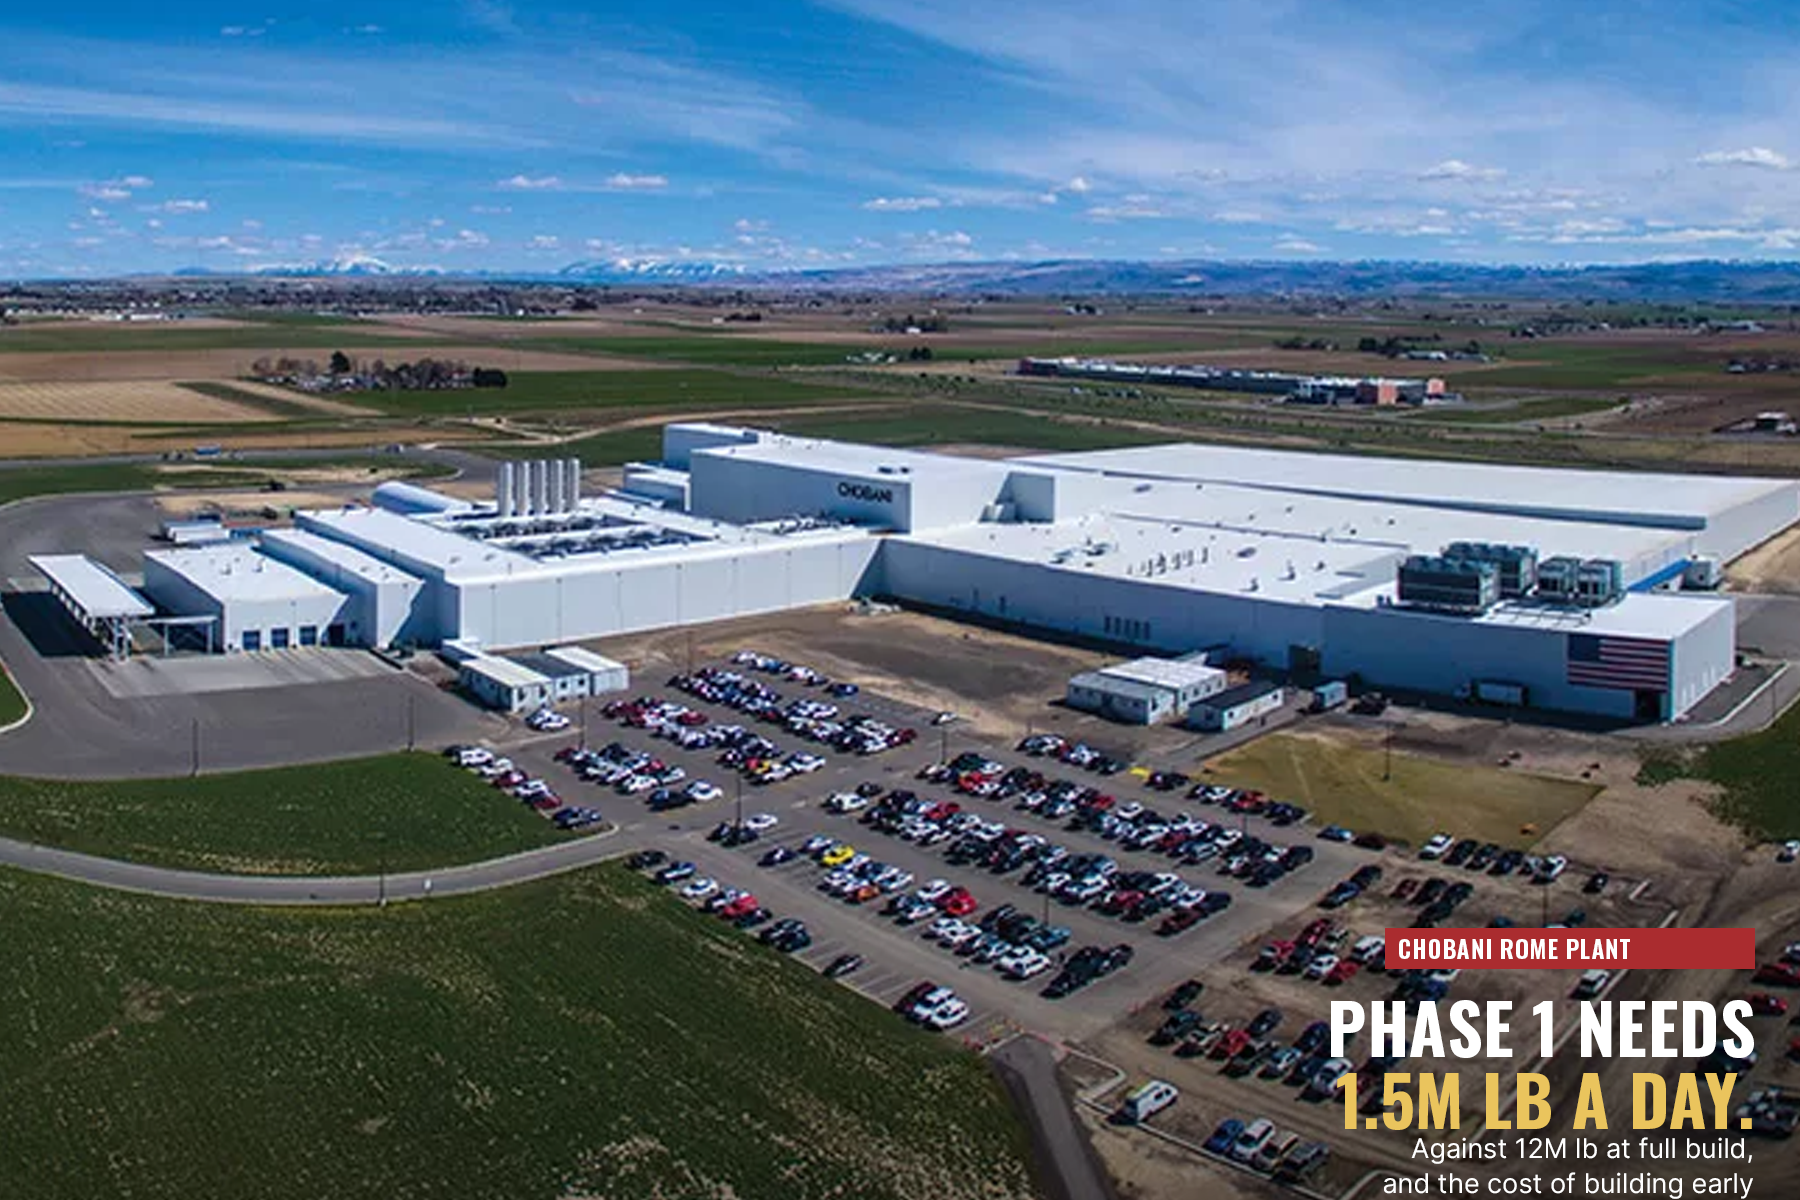
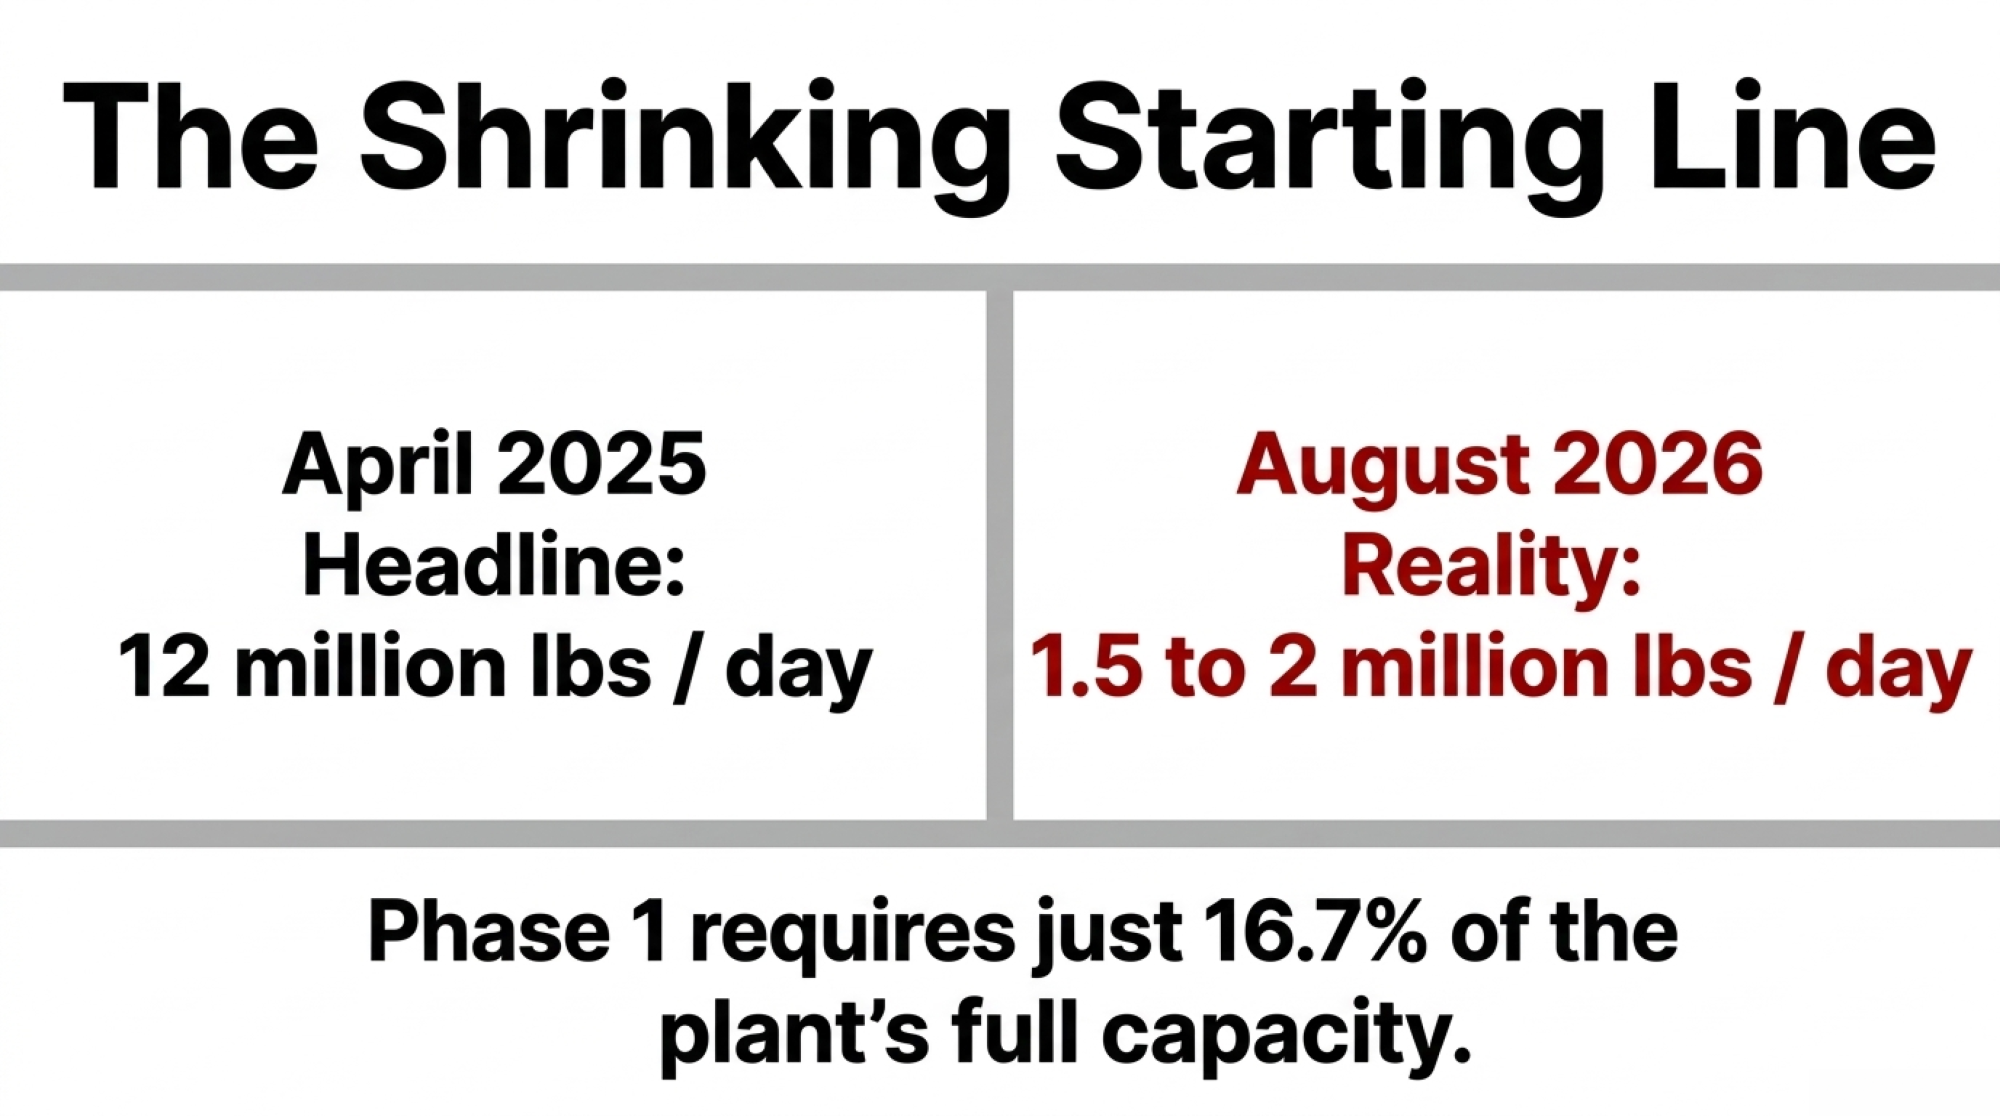
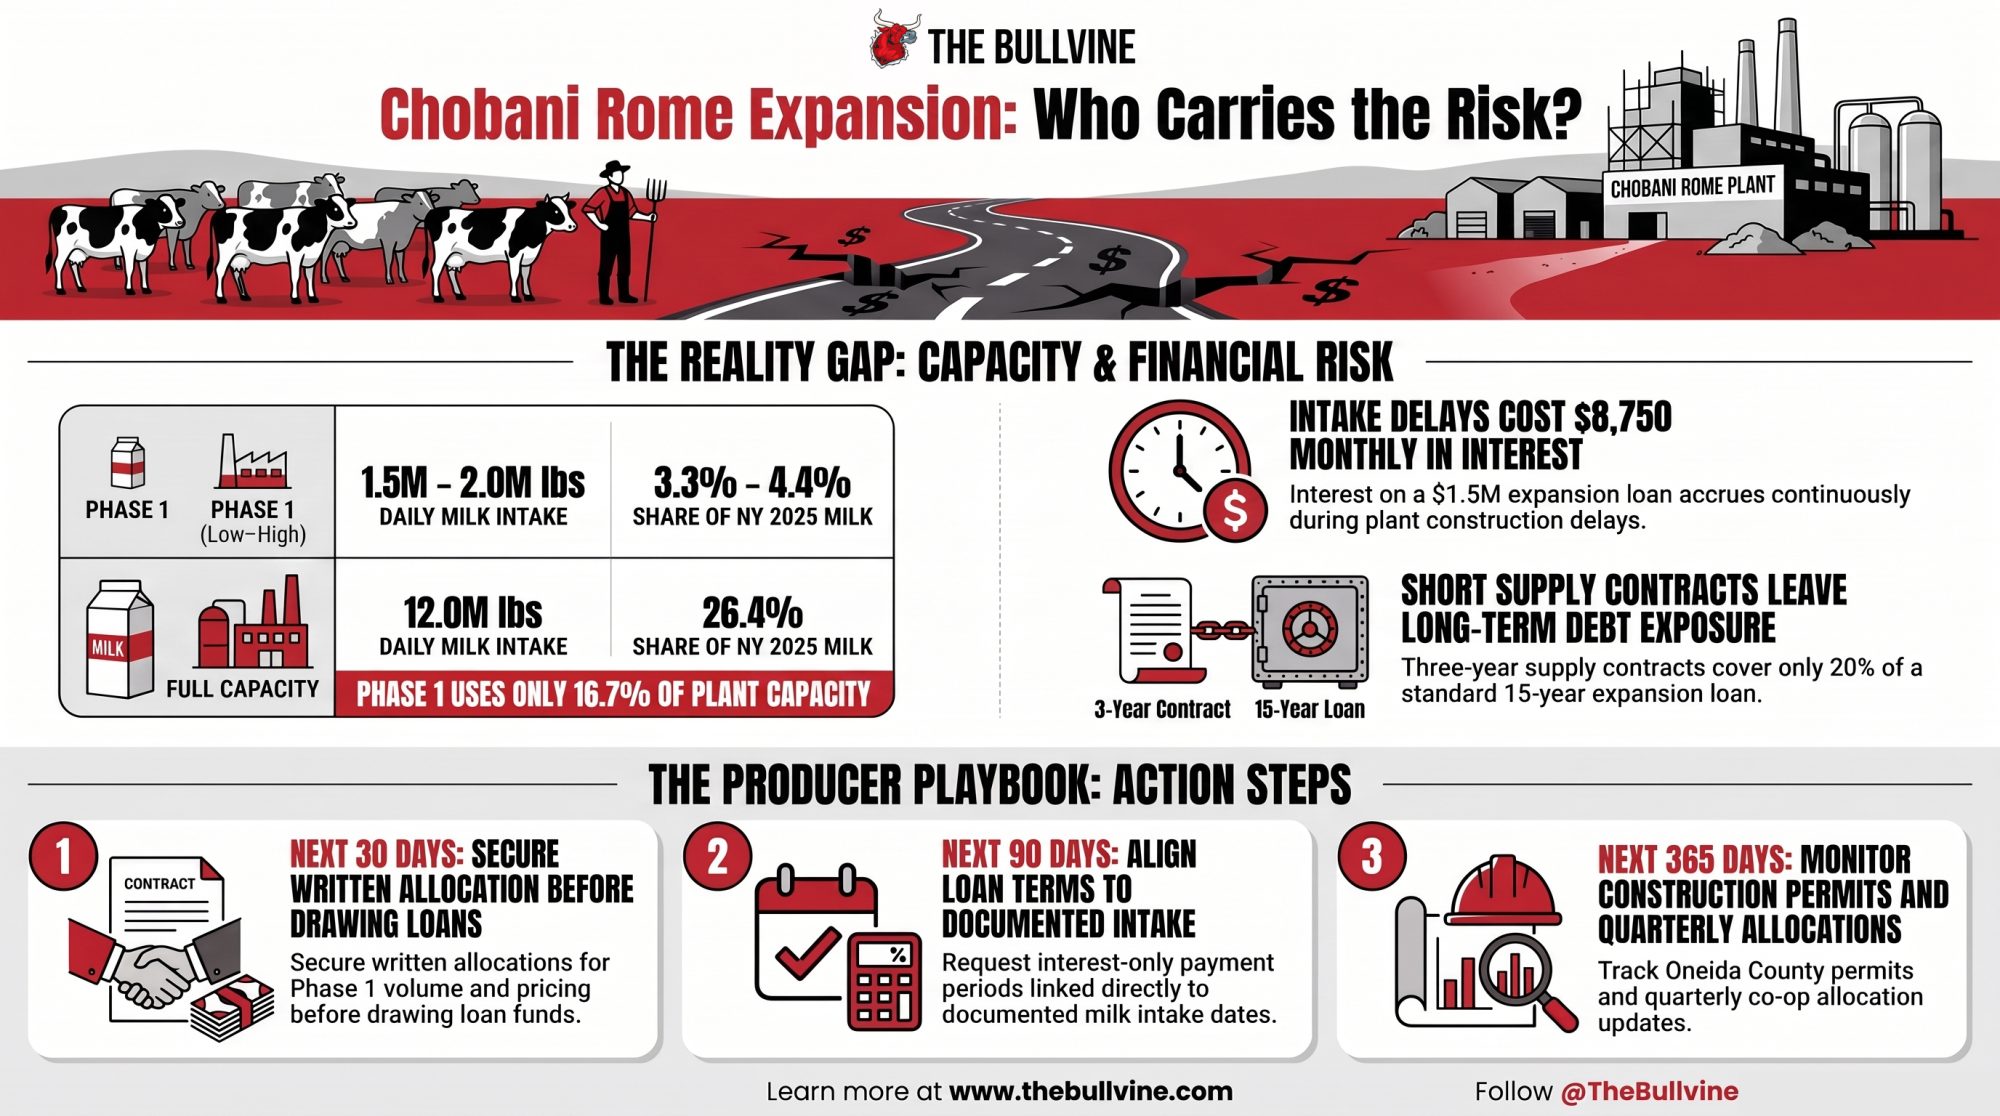
New York herds eyeing Chobani’s Rome plant are caught between two numbers. When New York announced the project in April 2025, the headline figure was 12 million pounds of milk a day at full capacity. Sixteen months later, Chobani’s chief impact officer, Nishant Roy, gave the Rome Sentinel a much smaller starting number: Phase 1 will require about 1.5 to 2 million pounds a day. Even at the top of that range, Phase 1 is 16.7% of the plant’s full milk capacity.
For New York herds, that gap is the Chobani Rome milk supply story. DairyHerd’s October 1 report, which interviewed IDFA president and CEO Michael Dykes, counts $14.4 billion across 77 projects in 21 states. Bullvine hasn’t seen the project list behind that count. The capital commitments are public. Any supply commitments to farms would sit in separate documents, and Bullvine found none published.

What did New York commit Chobani to?

The April 22, 2025 release describes a $1.2 billion, 1.4-million-square-foot plant “capable of producing over one-billion pounds” of dairy products a year, with “more than 1,000 jobs.” Ulukaya said Rome would have Chobani “partnering with hard working people across the heartland of New York.” State Agriculture Commissioner Richard A. Ball called it “tremendous news for our state and for our dairy farmers, who will be supplying milk to this state-of-the-art processing facility.”

The public money is tied to infrastructure and jobs:

  • Excelsior Jobs Program: up to $73 million in performance-based tax credits from Empire State Development, tied to more than 1,000 jobs (Governor’s Office, April 22, 2025).
  • FAST NY: $32.6 million to Oneida County for infrastructure at the Griffiss Triangle Site, announced by Governor Hochul on August 19, 2025, with Roy in the room (Governor’s Office transcript).

Neither award sets a price formula, base allocation, hauling terms, procurement radius, contract length or intake date for a supplying farm.

Chobani held a ceremonial groundbreaking in April 2025. Food Processing reported on August 13, 2026 that the company had planned to start full construction in 2026. The Sentinel now reports a construction start between spring 2027 and summer 2028 (Food Processing).

How much milk does Chobani Rome need at startup?

The phasing isn’t new. At the April 2025 announcement, Chobani president and COO Kevin Burns described the project as “phase one,” adding, “We’re building a campus, really,” according to WXXI. What’s new is a number. Roy told the Sentinel that Phase 1 brings four to six of a planned 28 production lines online, with about 300 to 450 hires, and Phase 2 adds seven to 10 lines. Oneida County officials now put total jobs closer to 1,800, WKTV reported on August 12, 2026.

The Sentinel reported that Roy said Chobani is engaged with more than 400 local dairy farms and co-ops, and has worked with farmers and co-ops since before the 2025 announcement. “Engaged” can mean conversations, prospect lists or co-op planning, and co-ops in that count may represent some of the same farms.

New York produced 16.568 billion pounds of milk in 2025 from 642,000 cows averaging 25,807 pounds each, according to USDA NASS’s annual summary, released April 30, 2026.

Rome capacity measureDaily milkAnnualizedShare of NY 2025 productionNY-average cow equivalent
Phase 1, low1.5 million lb547.5 million lb3.3%~21,200 cows
Phase 1, high2.0 million lb730 million lb4.4%~28,300 cows
Full capacity12 million lb4.38 billion lb26.4%~169,700 cows

Bullvine calculation using the NY Governor’s Office release (April 22, 2025), Roy’s Phase 1 range as reported by the Rome Sentinel (August 11, 2026), and USDA NASS 2025 New York data (April 30, 2026).

Chobani already buys more than 1 billion pounds of New York milk a year, according to Oneida County’s April 21, 2025 release. Phase 1’s annual demand, at the high end, equals at most 73% of that. No public source says how much of Phase 1 will be new demand rather than milk now going to Chobani’s existing plants, and that’s the first question your co-op should be able to answer.

The plant’s scale and schedule have both moved since April 2025, and our earlier math didn’t hold up even against the original announcement. Checked against the announced figures and the new Phase 1 range, four previous Bullvine estimates need correcting:

  • April 24, 2025. We put the plant at roughly 100,000 cows, with completion in late 2026.
  • June 16, 2025. We equated 12 million pounds a day with about 1,200 high-producing cows, understating it by more than 168,000 cows.
  • October 19, 2025. We listed a Chobani Rome premium of $0.75 to $1.25/cwt for 3.3%-plus protein. We have found no published Chobani document that sets a premium for a plant that hasn’t operated.
  • November 21, 2025. We said 40 mid-size farms or three to four mega-dairies could supply it. At New York’s 2025 yield, 40 farms would need about 4,240 cows each.

Pennsylvania gets Chobani milk demand first

Chobani’s second $1.2 billion bet starts sooner. Governor Josh Shapiro’s office announced on August 31, 2026 that Chobani’s plant at 7356 Industrial Boulevard in Upper Macungie Township will, at full scale, source more than 3 billion pounds of Pennsylvania milk a year. That’s about 30% of the state’s current production, with production expected to begin in 2027 (reported by the Morning Call). Three billion pounds averages about 8.2 million pounds a day (Bullvine, September 3, 2026).

PennLive reported a mid-summer 2027 start after $270 million in upgrades (PennLive, September 25, 2026). Pennsylvania is also offering $127 million in loans and grants to farmers who expand to meet the demand.

For a New York herd, the order matters. Pennsylvania’s full-scale daily volume is more than four times Rome’s Phase 1 high, and it’s due to start a year or more earlier. Whether Chobani supplies Upper Macungie from Pennsylvania farms only, or New York co-op milk crosses the line, isn’t in any public document. That’s the second question for your co-op.

When will Chobani Rome start taking milk?

Chobani’s 15 months has been reported two ways. WKTV reported on August 12, 2026 that operations are set to begin 15 months after construction starts, with the whole project finished by 2030. Syracuse.com reported on August 19 that Roy said the three-phase project would take 15 months to complete. On WKTV’s reading, first milk arrives between mid-2028 and late 2029 (Bullvine calculation from the Sentinel’s construction window).

Oneida County Executive Anthony Picente gave an earlier date. He said he looked forward to “the upwards of 450 jobs that phase one of the Rome plant will bring to Oneida County in early 2028,” according to the Oneida Dispatch on September 7, 2026. Chobani hasn’t published a date that settles it.

The Sentinel reported that Chobani moved the start while juggling new market demand and Mohawk Valley winters. Roy also said, “we are also not abandoning our commitment to Rome. We’re coming,” as quoted by Food Processing.

Who carries the risk while Rome phases in?

On the MILK Business Podcast, as reported by Lucas Fuess of Rabobank, a major dairy lender, described the standoff. Co-ops and processors won’t spend, “in some cases, $1 billion on a new plant” without security in milk supply growth, he said, and farmers need “security in someone coming to pick up their milk every day.”
Dykes said profitability has to exist “at the farm level and the processing level.” He also acknowledged that a farmer being able to switch milk buyers is “not necessarily the case today.”

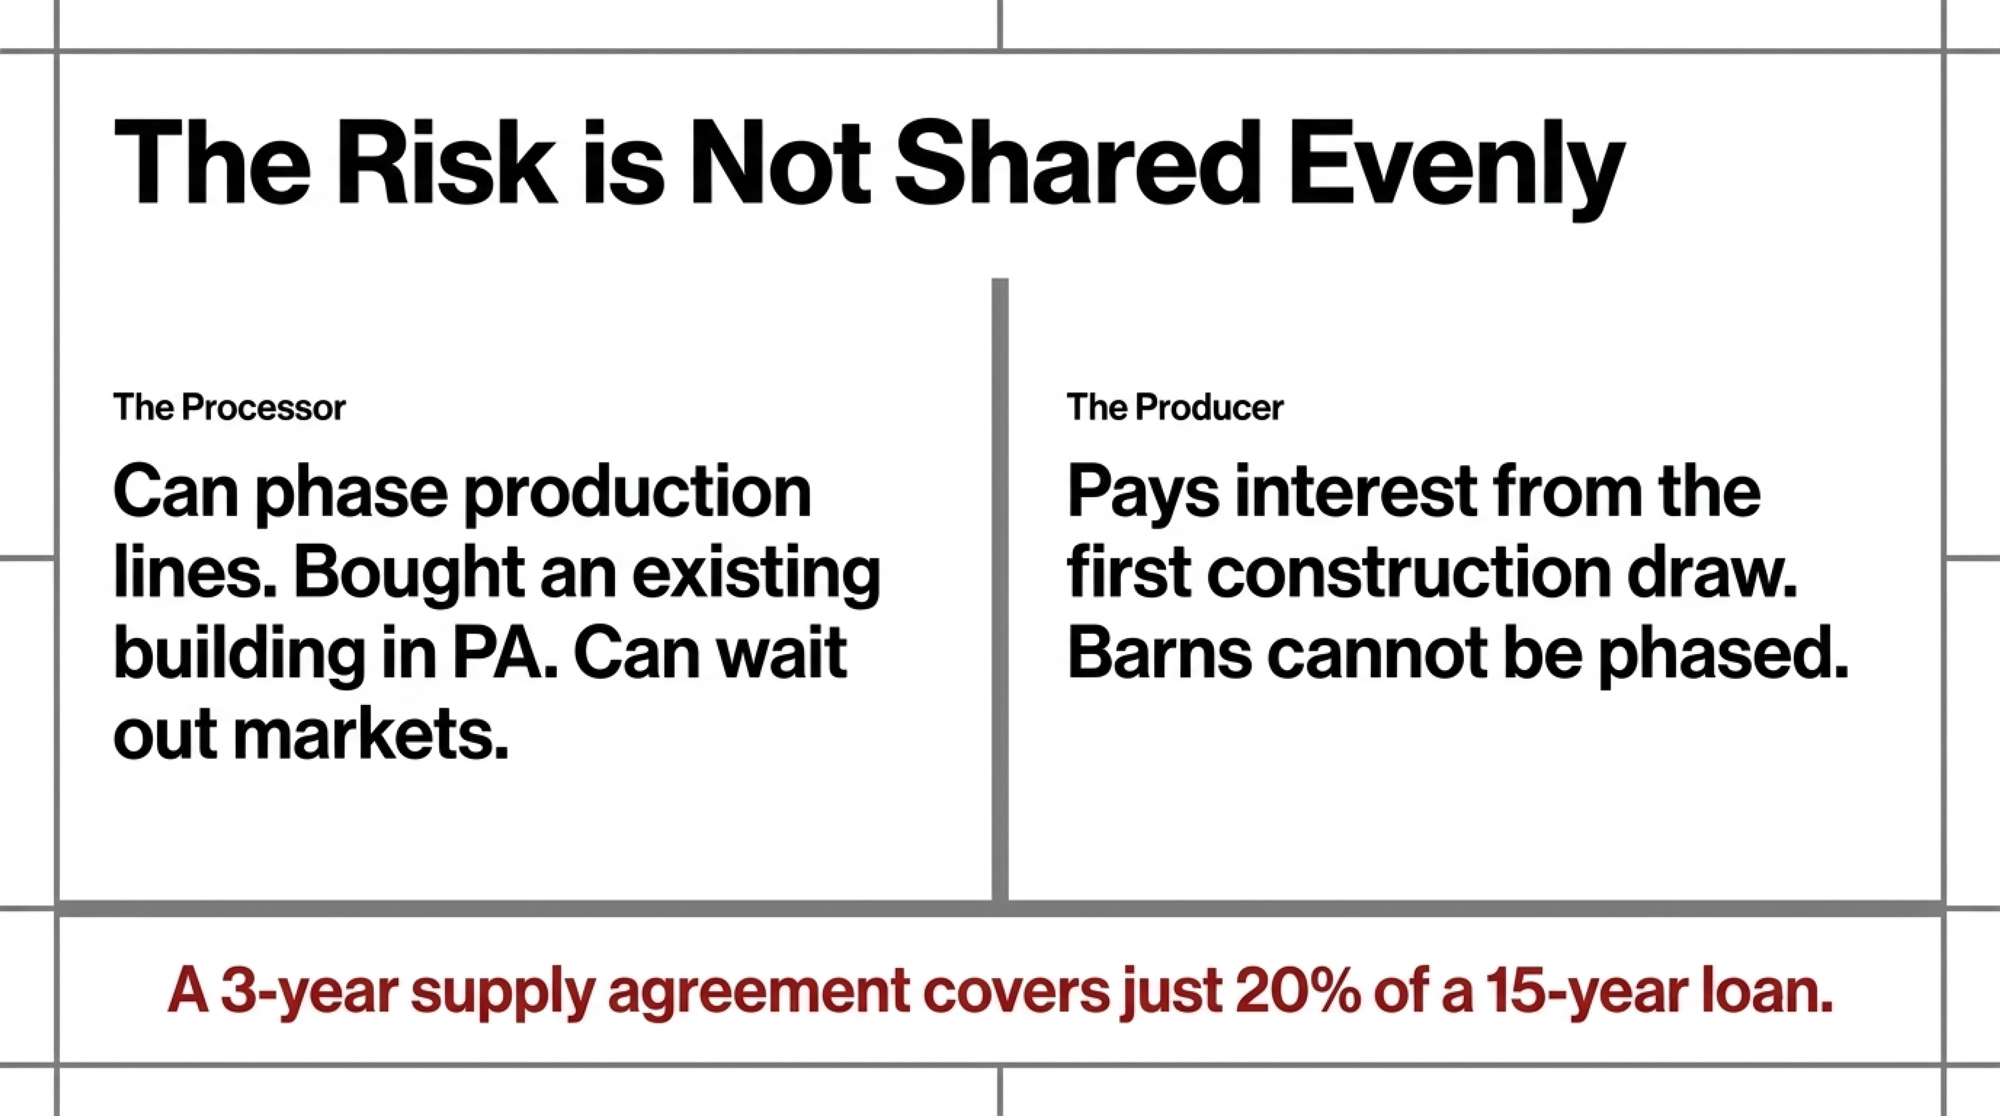
In our analysis, the risk isn’t shared evenly. Chobani can phase lines in, and in Pennsylvania it’s bought an existing building that starts producing sooner. A producer who builds a barn pays interest from the first construction draw, whether Rome takes milk in mid-2028 or late 2029.

Running the Numbers: Building ahead of a phased plant

Published evidence

  • New York 2025 yield: 25,807 lb/cow (USDA NASS, April 30, 2026, state average).
  • Capital: “maybe $25,000 a cow, depending on land prices,” from Dykes describing a whole new dairy.
  • Construction-start window: spring 2027 to summer 2028, about 16 months (Rome Sentinel, August 11, 2026).
  • 2027 U.S. all-milk price forecast: $19.80/cwt (USDA ERS, Livestock, Dairy, and Poultry Outlook, September 2026).

Stated assumptions

  • A 400-cow New York herd adds 100 cows, shipping 25,807 cwt more a year.
  • Capital per added cow: $25,000 high (Dykes’s whole-dairy figure), $20,000 central, $15,000 low. An addition on an existing site likely costs less, so the takeaways use the low case.
  • Loan: 7% interest (illustrative, not a quoted rate), 15-year amortization with annual payments (factor 0.109795).
  • Supply contract: three years, starting the same year as the loan.

Bullvine calculation (USD)
 LowCentralHigh
Expansion capital$1,500,000$2,000,000$2,500,000
Annual principal and interest$164,692$219,589$274,487
Debt service per added cwt$6.38$8.51$10.64
Debt service as share of $19.80 all-milk32%43%54%
Interest carry per month of delay$8,750$11,667$14,583
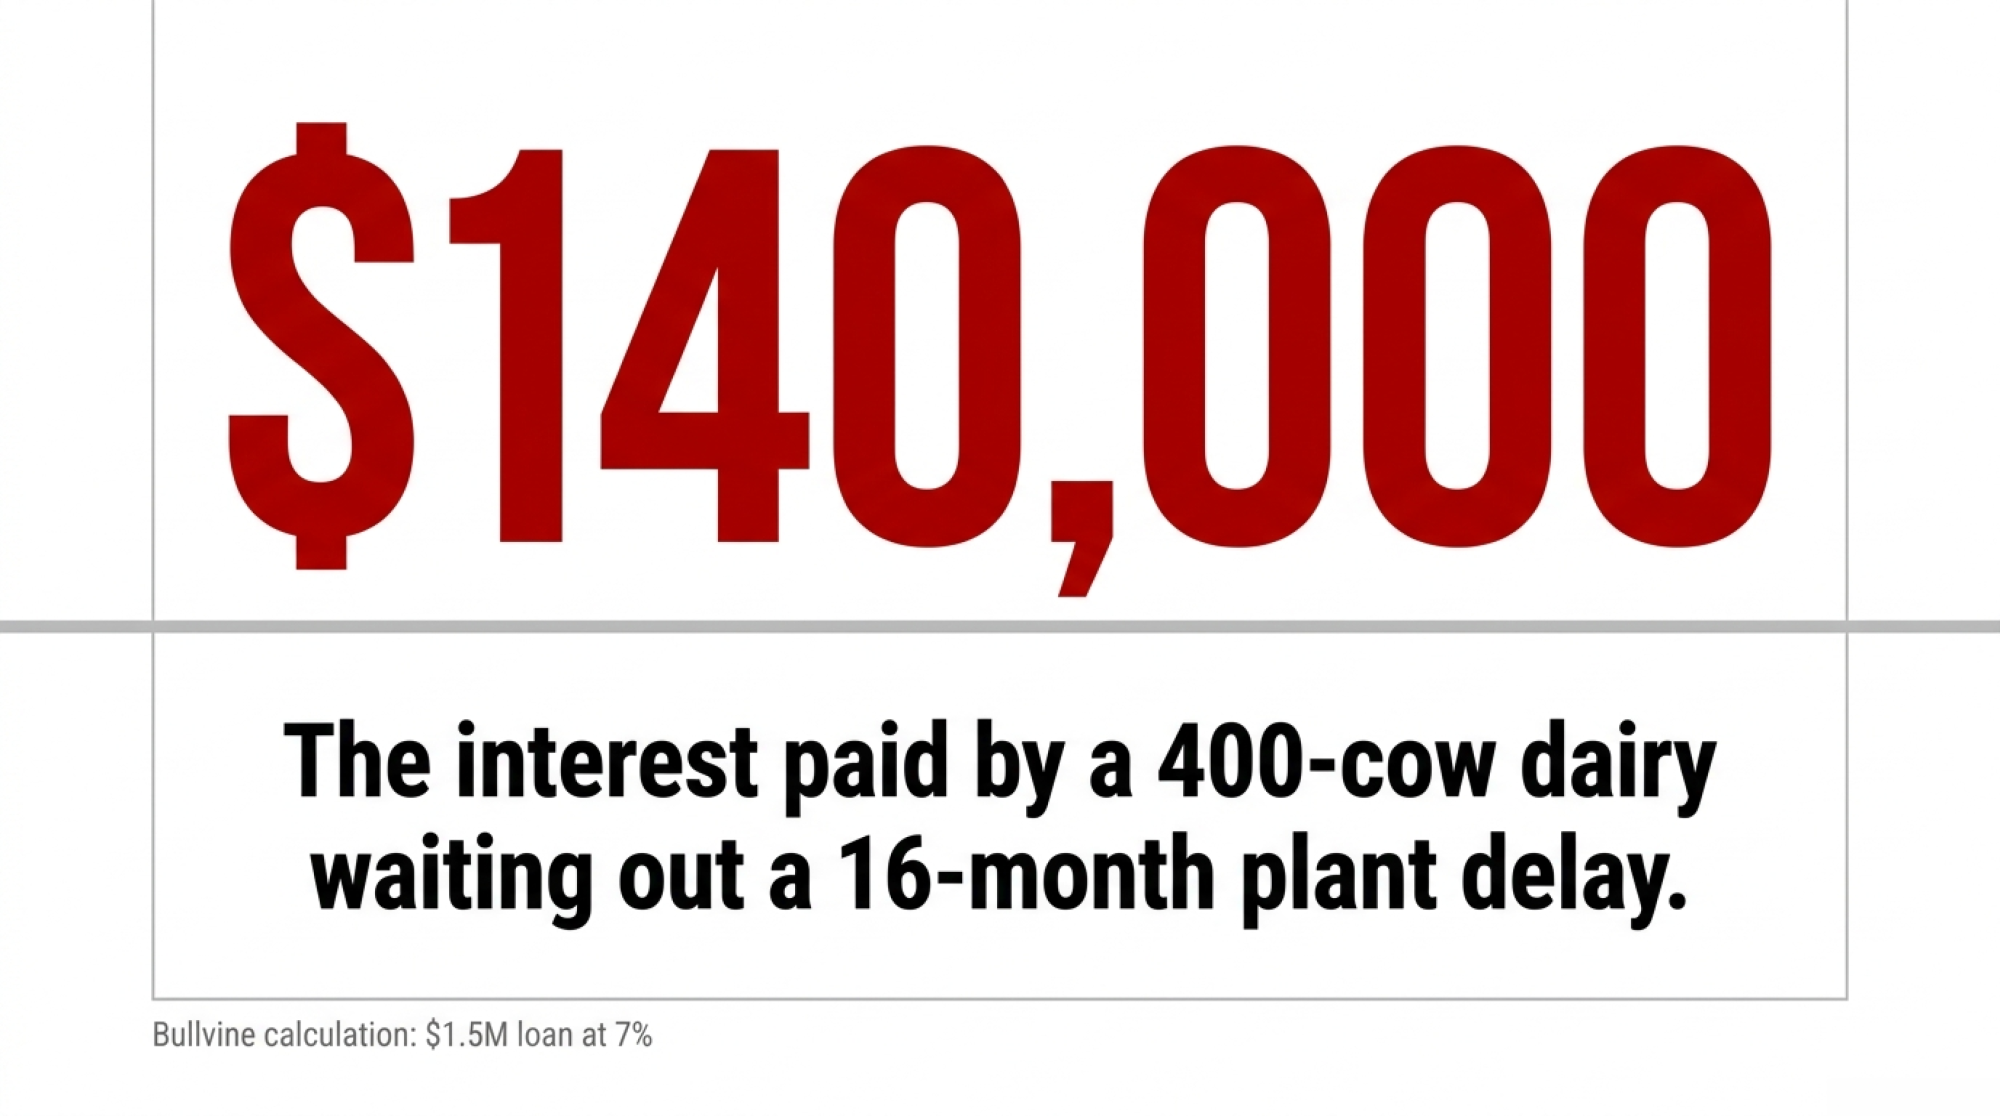
Interest carry across a 16-month slip$140,000$186,667$233,333
Remaining payments after a 3-year contract ends (principal + interest)$1.98 million$2.64 million$3.29 million

On our low case, a producer who has drawn $1.5 million at 7% pays $8,750 a month in interest while waiting for the plant to take milk.

The principal still owed after three years is about $1.31 million on the low case. The table row is larger because it adds 12 years of interest to that balance.

On the low case:

  • A 16-month slip, the spread between Chobani’s earliest and latest construction starts, costs $140,000 in interest.
  • Debt service alone takes $6.38 of every $19.80 the added milk is forecast to earn in 2027, before feed, labour or heifers.
  • Each $1.00/cwt over-base discount on the added milk costs $25,807 a year, or 9.4% to 15.7% of the annual loan payment across the three cases.
  • A three-year agreement covers 20% of a 15-year loan.

Methodology note. Delay carry is interest-only on the full drawn balance. With monthly payments, the low case runs $161,790 a year and leaves $1.94 million in payments after the contract ends. The $19.80 forecast is a U.S. average; New York pay prices differ. The herd is a model, not a named farm’s books. For how a rally-year budget hides this exposure, see the $5.39/cwt debt trap in 2026 expansion budgets.

What does $15 billion tell New York producers?

The count grows as the window widens:

DateCountScope
October 2, 2025more than $11 billion50+ projects, 19 states, 2025 to early 2028
October 1, 2026$14.4 billion77 projects, 21 states
Accessed October 5, 2026more than $15 billion2025–2030

IDFA, which represents dairy processors, split its October 2025 total by product: cheese $3.20 billion, milk and cream $2.97 billion, yogurt and cultured $2.81 billion. USDA ERS forecasts 238.6 billion pounds of U.S. milk for 2027.

That’s what the counts tell a New York producer: where processors are putting capital. They don’t report contracted farm pounds, so none of them tells you whether any of it is committed to your milk.

What does my co-op milk check actually show?

Under 7 CFR §1001.73(e), a Northeast handler paying producers must give each one a statement showing the minimum rate owed, any different rate actually paid, each deduction and the net payment. The rule carves out producers whose milk was received from a cooperative association acting as a handler under §1000.9(a) or (c). Under §1001.73(b), the handler pays the cooperative for that milk, and §1001.73 doesn’t set what the member’s own pay statement must show.

If your milk moves through a co-op, a Chobani premium paid to the co-op could arrive blended into your pay price, without its own line. That’s a visibility gap, and the rule alone says nothing about whether anything is withheld. You can’t confirm from the statement that Rome milk is worth more to you, so ask.
The Rome playbook: 30, 90 and 365 days

The same written questions apply to any producer being courted by a new plant, in New York, Pennsylvania or elsewhere.

Next 30 days: Get the supply answer in writing

The Action: Ask your co-op field rep or buyer for, in writing, Phase 1 committed pounds, which co-ops hold them, intake date, contract term, how over-base milk is priced, and whether your milk could be routed to Upper Macungie instead.

The Requirement: One email and 12 months of pay statements to compare against.

The Red Flag: You can’t get a written volume allocation for your added milk before your lender’s first construction draw. On the model above, every month between that draw and first intake costs $8,750 per $1.5 million borrowed at 7%.

The Backfire: Budgeting on Roy’s reported engagement with more than 400 farms and co-ops. Budget on pounds and dates in writing.

Next 90 days: Tie the loan to the contract

The Action: Ask your lender about an interest-only period tied to a documented intake date, or stage the build so cows arrive with the contract.

The Requirement: The written answer from step one, a cash-flow budget at your current net price and a lender meeting.

The Trigger: Your offered contract runs shorter than your loan. On the model, a three-year deal covers 20% of a 15-year note.

The Backfire: Staging raises per-cow cost or delays the herd past the intake date. Price both paths before choosing.
Next 365 days: Watch for the signal that changes the bargain

The Signal: A confirmed construction start, through a contractor award, building permit or Chobani announcement, would narrow the window in the model from 16 months to a date. That’s the point where co-ops have a reason to compete for added milk.

The Action: Track Oneida County and City of Rome planning records, watch Upper Macungie’s 2027 ramp, and ask your co-op each quarter whether your Phase 1 allocation has changed.

The Watch Item: Whether any offer prices protein specifically. Rome is a yogurt and cultured-products plant, and no Chobani premium schedule for Rome has been published.

Chobani can wait out markets, winters and its existing sites. A producer carrying construction debt can’t. Before you sign a loan, can your co-op show you, in writing, how many pounds of your milk Rome has committed to take, and when?
Learn More

The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
NewsSubscribe
First
Last
Consent

The $333M Processor Rush: Why Rod Hissong Wins While Pool Farms Get the 30-to-1 Gap

Processor math reveals the brutal truth: If you aren’t in the direct-supply lane, you’re likely financing someone else’s expansion.

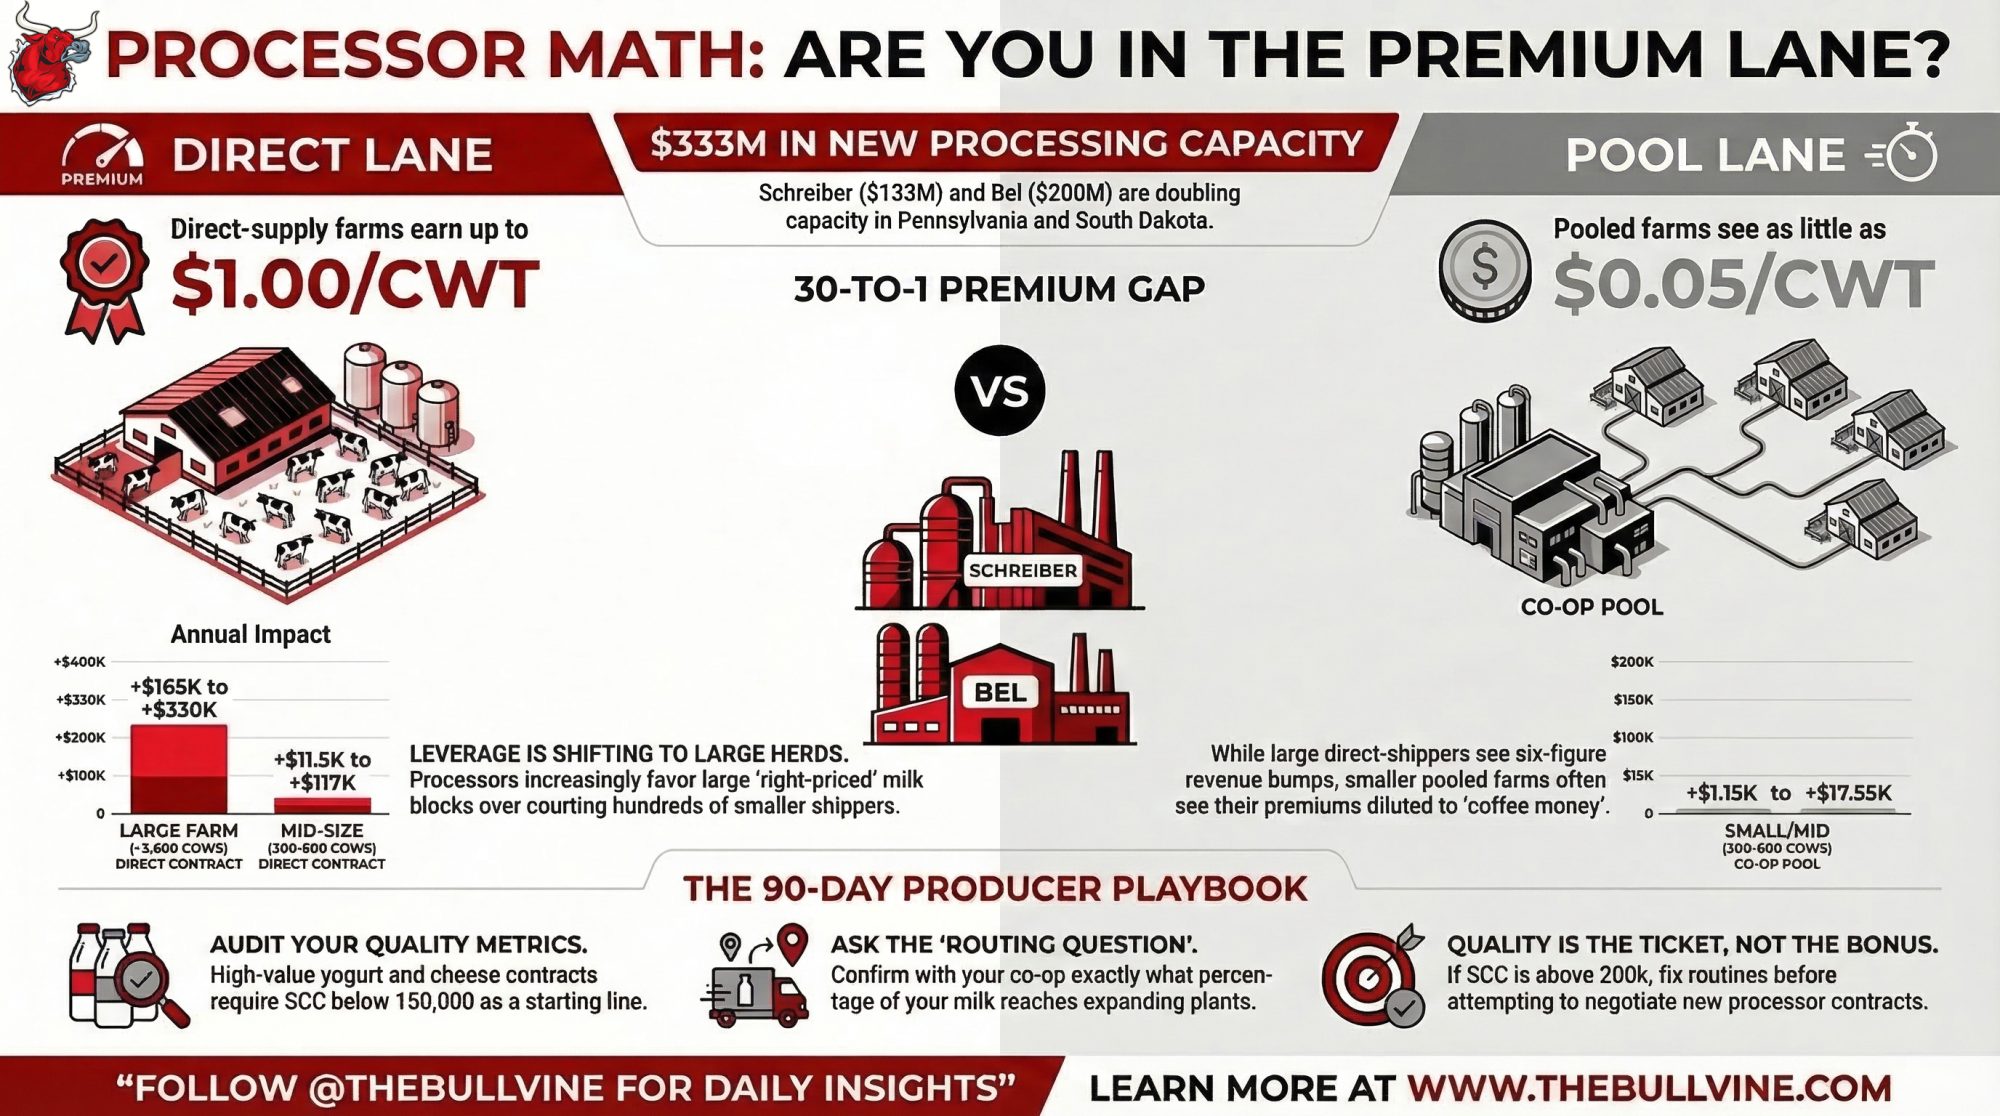
Executive Summary: $333M processor rush: Schreiber ($133M yogurt) and Bel ($200M Babybel) double capacity in PA/SD. Rod Hissong’s $5M Schreiber contract gains $165K–$330K/year. 200‑cow pool farms get $1K–$7K. 30‑to‑1 premium gap. PA’s 490 farm exits flip leverage to herds like Mercer Vu. FO30 down $5.42/cwt. Run your numbers: co‑op routing % + SCC <150K? +$0.50/cwt floor to switch lanes. Processor Math asks: where’s your share?”

dairy processing expansion

Rod Hissong ships 33 million pounds of milk a year to Schreiber Foods’ Shippensburg, Pennsylvania, plant — at least .06 million in annual revenue from that one relationship, using the Federal Order Class II minimum of .34/cwt(USDA, February 2026) as a floor. When Schreiber’s new yogurt line hits full stride, that same expansion could add $165,000–$330,000/year to his milk check, while a 200‑cow co‑op farm in the same sourcing zone might only see $1,150–$6,900 from the same announcement — depending on how premiums wash through the pool.

Two days after that Schreiber news, Bel Group broke ground on a 0 million expansion in Brookings, South Dakota, to double Babybel production from 10,000 to 20,000 tons per year and double its milk intake from American farms, primarily in South Dakota and neighboring states. Together, those two projects add 3 million in dairy processing capacity to regions where milk is already concentrating into fewer, larger herds — and where contract structure quietly decides who actually gets paid.

The Massive Premium Dilution Nobody Mentions

Press releases promise “support for local dairy.” The barn math says your contract lane and herd size decide whether you see a six‑figure bump or coffee money.

Mercer Vu Farms — Hissong’s operation in Mercersburg, PA — milks about 3,600 mature cows, farms 5,500 acres, and produces roughly 100 million pounds annually. Glenn and Mae Hissong started that herd with 7 cows in 1949; today, about one‑third of Mercer Vu’s production, around 33 million lbs/year, goes straight to Schreiber. The rest moves through Land O’Lakes.

The “average” Schreiber‑zone producer looks very different. The Center for Dairy Excellence’s 2025 survey pegs average responding herd size at 152 cows, while the USDA puts the statewide Pennsylvania average closer to 106 cows. Even using 152, that’s roughly 3.5 million lbs/year per farm — about a tenth of Mercer Vu’s Schreiber volume.

Schreiber’s 109,000 lbs/day: Same Expansion, Very Different Milk Checks

Governor Shapiro’s office says Schreiber’s Shippensburg project will add 109,000 lbs of raw milk processing per day, or about 39.8 million lbs/year, across 165 farms in 11 counties. Under realistic premium scenarios, that looks like this:

Farm ProfileAnnual Schreiber VolumePremium ScenarioAnnual Impact (barn math)
Mercer Vu (~3,600 cows, direct)~33M lbs+$0.50/cwt+$165,000 (33,000 cwt × $0.50)
+$1.00/cwt+$330,000 (33,000 cwt × $1.00)
200‑cow farm (direct, 50% to Schreiber)~2.3M lbs+$0.50/cwt+$11,500 (23,000 cwt × $0.50)
+$1.00/cwt+$23,000 (23,000 cwt × $1.00)
200‑cow farm (co‑op pool, indirect)Pooled+$0.05–$0.15/cwt (diluted)+$1,150–$3,450 (23,000 cwt × $0.05–$0.15)
+$0.10–$0.30/cwt (diluted)+$2,300–$6,900 (23,000 cwt × $0.10–$0.30)

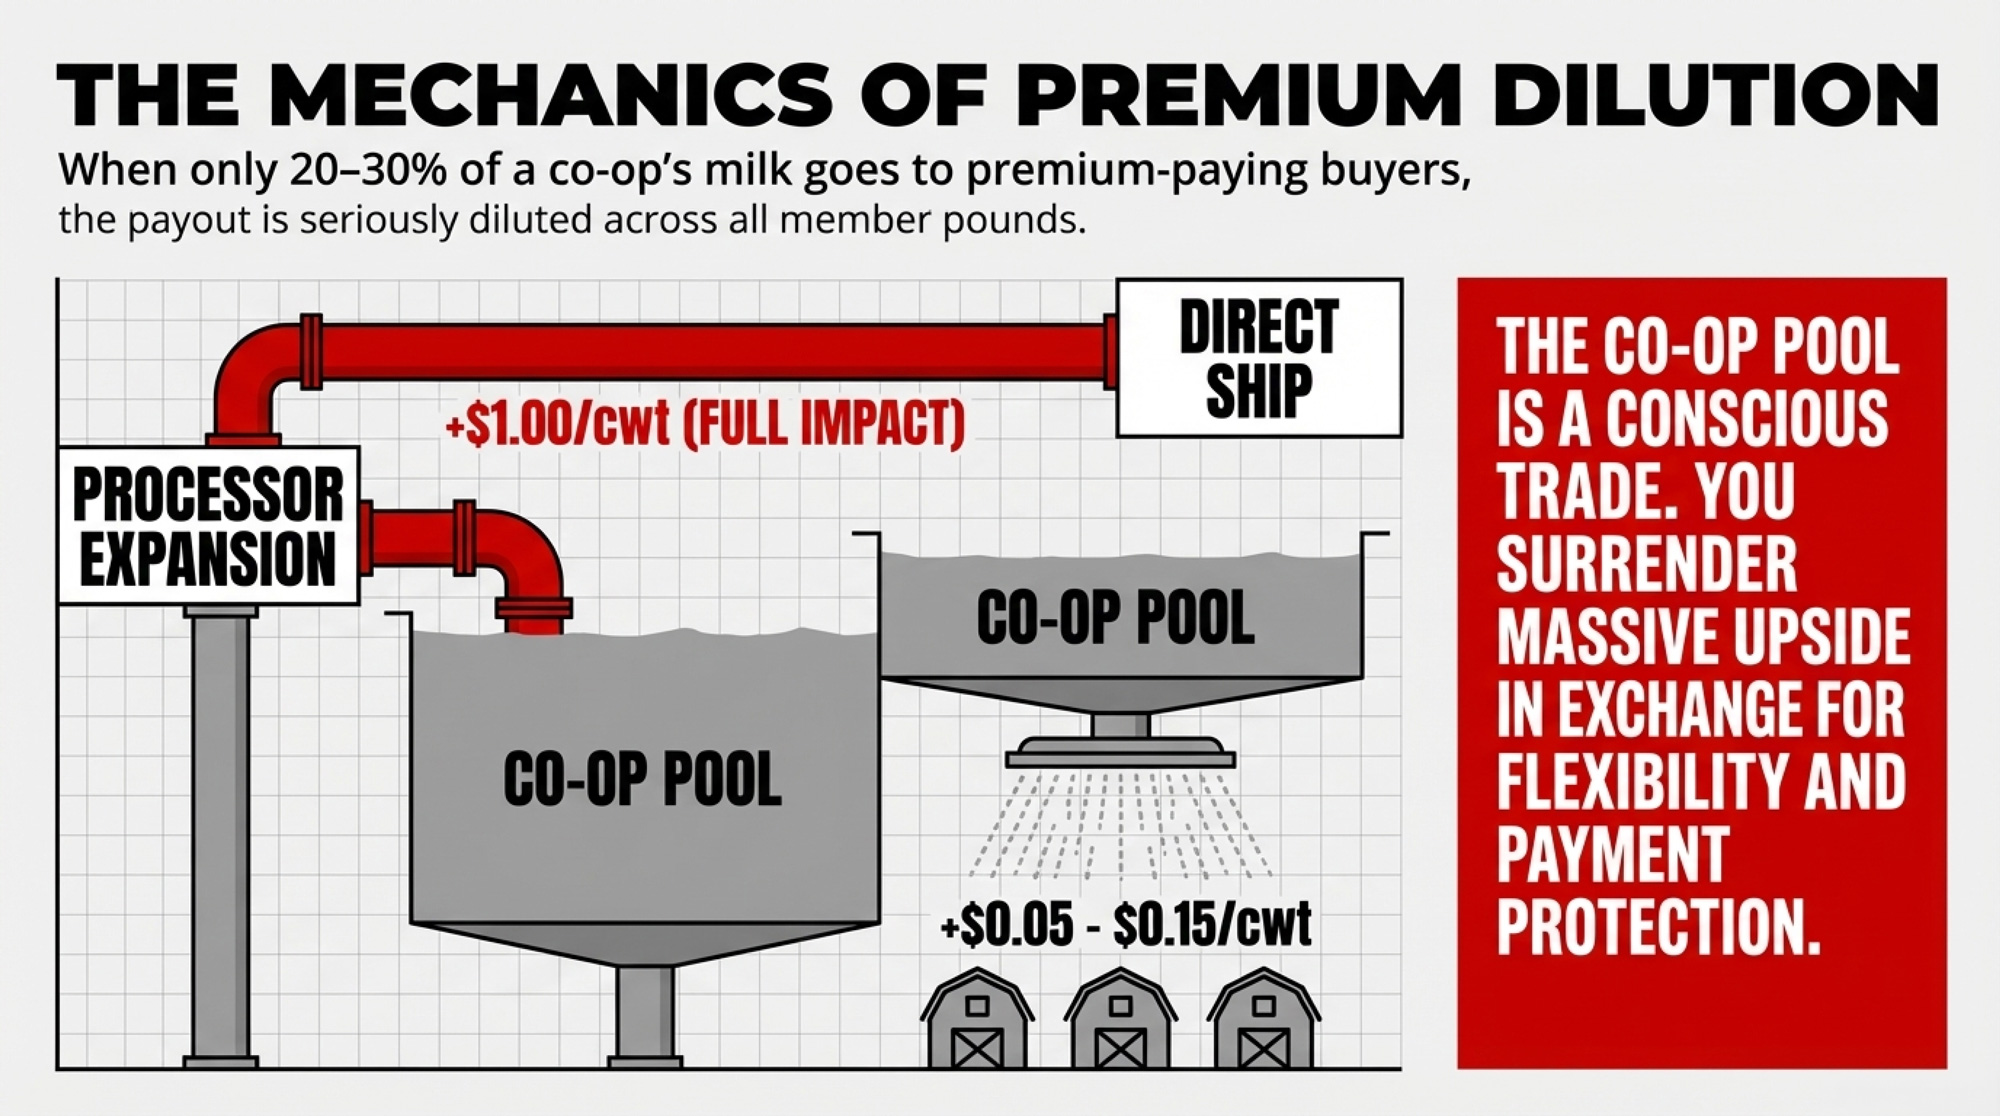
Those premium bands line up with historical $0.25–$1.00/cwt over‑order and contract premiums discussed by agricultural economist John Janzen in Progressive Dairy, and with the pooling math laid out by Mark Stephenson and Andrew Novakovic for the Center for Dairy Excellence. Their work shows that when only 20–30% of a co‑op’s milk goes to premium‑paying buyers, those premiums are “seriously diluted” across all member pounds.

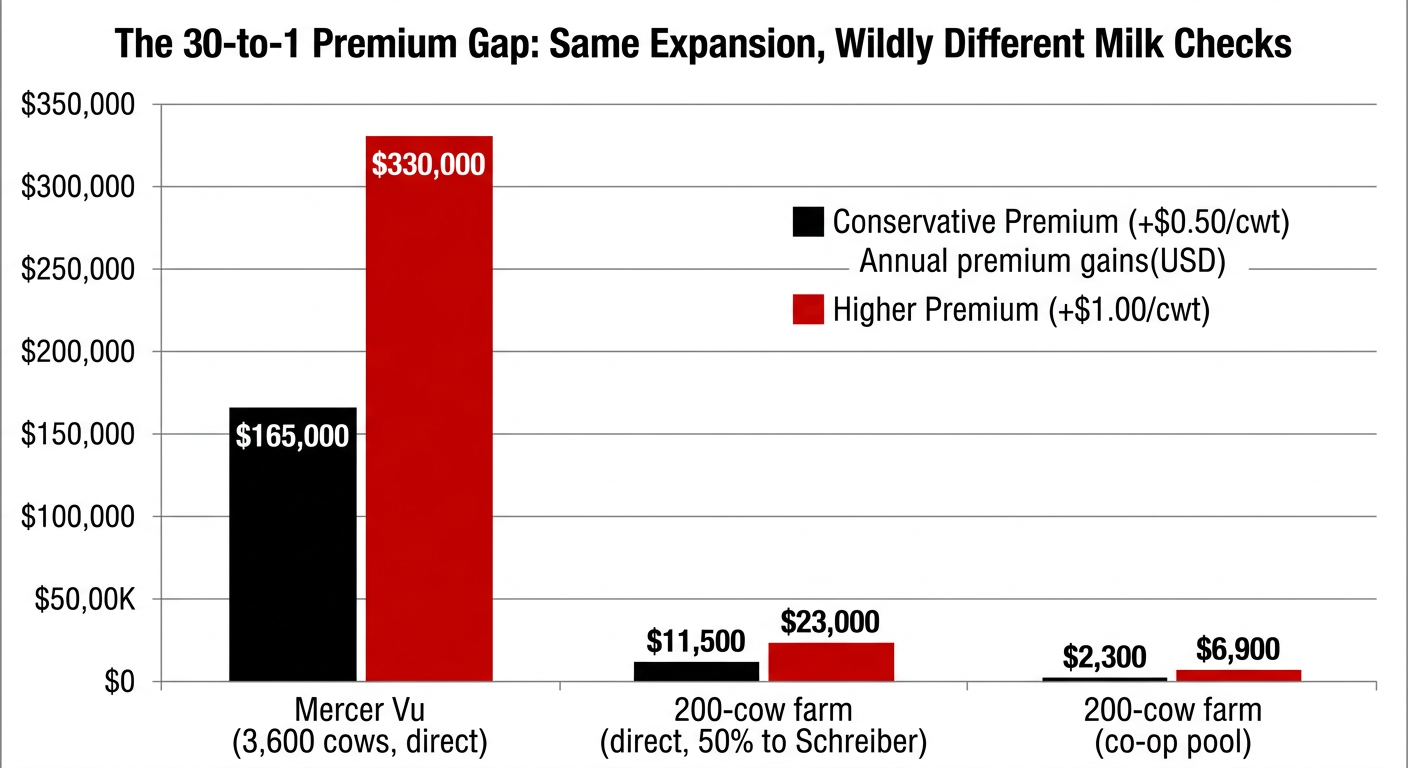
Same expansion. Same counties. A difference that can approach 30‑to‑1 between the top and bottom rows.

Farm ProfileConservative Premium (+$0.50 or +$0.10 pooled)Higher Premium (+$1.00 or +$0.30 pooled)
Mercer Vu (3,600 cows, direct)$165,000$330,000
200-cow farm (direct, 50% to Schreiber)$11,500$23,000
200-cow farm (co-op pool)$2,300$6,900

If your milk only reaches an expanding plant through a pool, you’re living in that bottom row — even if the press release name‑checks your state.

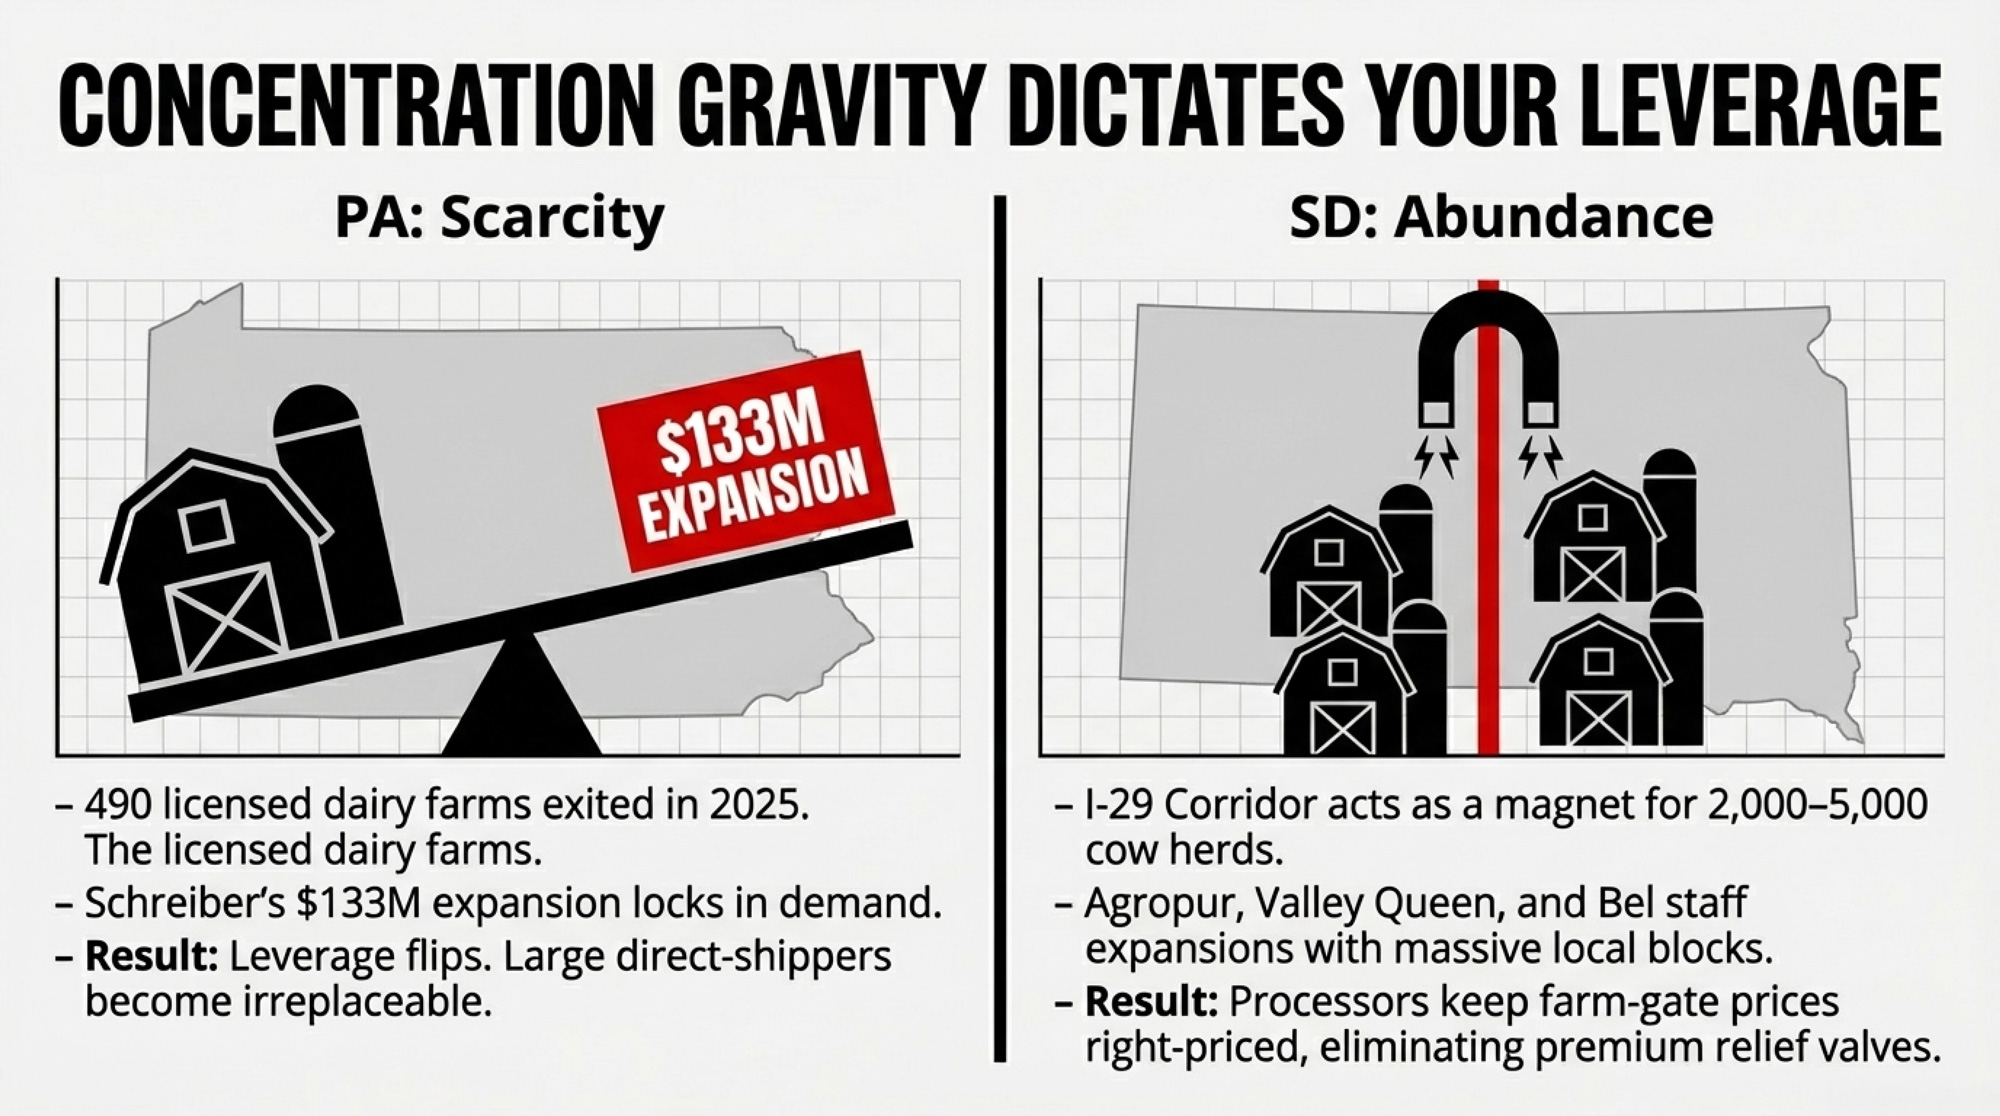
Concentration Gravity: From Shippensburg to Brookings

What’s happening in south‑central Pennsylvania is part of a broader concentration gravity: processor capital chasing large, “right‑priced” milk blocks.

On the PA side, Schreiber can pick up its extra 39.8 million lbs/year largely by deepening commitments with a handful of big direct shippers like Mercer Vu and adding a smaller number of mid‑size farms that can meet yogurt‑grade quality. Janzen’s line — “it’s much easier to sign up 10 2,000‑cow farms than 100 200‑cow farms” — is the procurement cheat code.

On the SD side, that same gravity is even stronger:

  • Valley Queen’s 2025 profile highlights 39 farms milking around 95,000 cows — about 2,400 cows per farm, all within reasonable hauling distance. 
  • South Dakota has been one of the fastest‑growing milk states in the U.S., while national herd numbers slowly shrink. 
  • Agropur (Lake Norden), Valley Queen (Milbank), and Bel (Brookings) now form a cheese/snack corridor that can staff expansions with local 2,000‑ to 5,000‑cow herds instead of courting hundreds of smaller shippers. 

Bel’s press release says Brookings currently produces 10,000 tons/year of Babybel and will double to 20,000 tons, “doubling milk sourcing from American dairy farms, primarily in South Dakota and neighboring states.” Earlier coverage around the original Brookings plant pegged its draw at about 15,000 cows; doubling production implies a similar additional draw.

The more easily Bel, Agropur, and Valley Queen can fill new vats with I‑29 corridor milk, the fewer basis‑premium “relief valves” remain for smaller herds shipping in from border states. That shows up later as weaker premiums and fewer calls when plants are short.

What Does Bel’s Expansion Really Mean for a 500‑Cow SD Herd?

South Dakota’s starting price floor is very different from Pennsylvania’s.

Federal Order 30 data show an Upper Midwest Statistical Uniform Price of $15.05/cwt in January 2026, down $5.42 from $20.47/cwt in January 2025, and among the lowest uniform prices across the FMMOs at that point. American Farm Bureau’s analysis of the June 2025 FMMO changes estimates that, in the first three months, higher allowances alone will result in about $64 million in lost revenue to the Upper Midwest pool.

A 500‑cow SD herd producing roughly 11.7 million lbs/year sits at about $1.76 million of gross milk revenue at $15.05/cwt.

Bel’s expansion doubles Babybeladd’s output to 20,000 tons and puts another $200 million into the Brookings site. Translate that into barn‑math scenarios for a 500‑cow herd:

FactorDirect ContractCo-op Pool
Premium Potential (500-cow herd, SD example)+$58,500–$117,000/year ($0.50–$1.00/cwt over FMMO)+$5,850–$17,550/year (diluted +$0.05–$0.15/cwt across all pool lbs)
Quality ThresholdSCC <150K (target <100K); strict bacteria/temp audits; failures can trigger terminationMore flexibility on month-to-month quality variance; still need to meet minimum FMMO standards
Volume Commitment3–5 year agreement typical; specified daily/monthly minimums; limited flexibility to expand/shrink without renegotiationShip what you produce; flexibility to grow/contract herd size without contract amendments
Payment ProtectionTermination risk if plant closes, finds cheaper supply, or cites quality “for cause”Federal Order payment security; pool guarantees you get paid even if processor fails
Upside CaptureYou get full premium when processor wins (e.g., +$0.50–$1.00/cwt for specialty cheese/yogurt)Premium dilution: your milk subsidizes pool members farther from premium plants

Exact over‑order numbers are contract‑specific and not public, but these ranges reflect real SD “right‑price” conversations and are consistent with historical premium levels along the corridor.

ScenarioVolume & PriceAnnual Impact (barn math)
Base case (pool only)11.7M lbs at $15.05/cwt$1.76M (117,000 cwt × $15.05)
Direct lane, +$0.50/cwt11.7M lbs at $15.55/cwt+$58,500 (117,000 cwt × $0.50)
Direct lane, +$1.00/cwt11.7M lbs at $16.05/cwt+$117,000 (117,000 cwt × $1.00)
Pool farm, diluted +$0.05–$0.15/cwt corridor lift11.7M lbs at $15.10–$15.20/cwt+$5,850–$17,550 (117,000 cwt × $0.05–$0.15)

Lynn Boadwine — who milks more than 2,000 cows near Baltic and has been a visible voice for SD dairy recruitment — summed up the processor logic bluntly: “You don’t want to have the highest price raw material for those folks, so they’re not going to move here. We’ve got to be right-priced to attract a processor.”

When a region can keep landing plants and keep farm‑gate prices “right‑priced” for processors, it’s not just growing local capacity. It’s slowly shifting where processors feel comfortable cutting bigger checks.

490 Pennsylvania Farms Gone — and Why That Flips the Leverage

Now flip back to Pennsylvania, because Hissong’s leverage sits on top of a changing supply base.

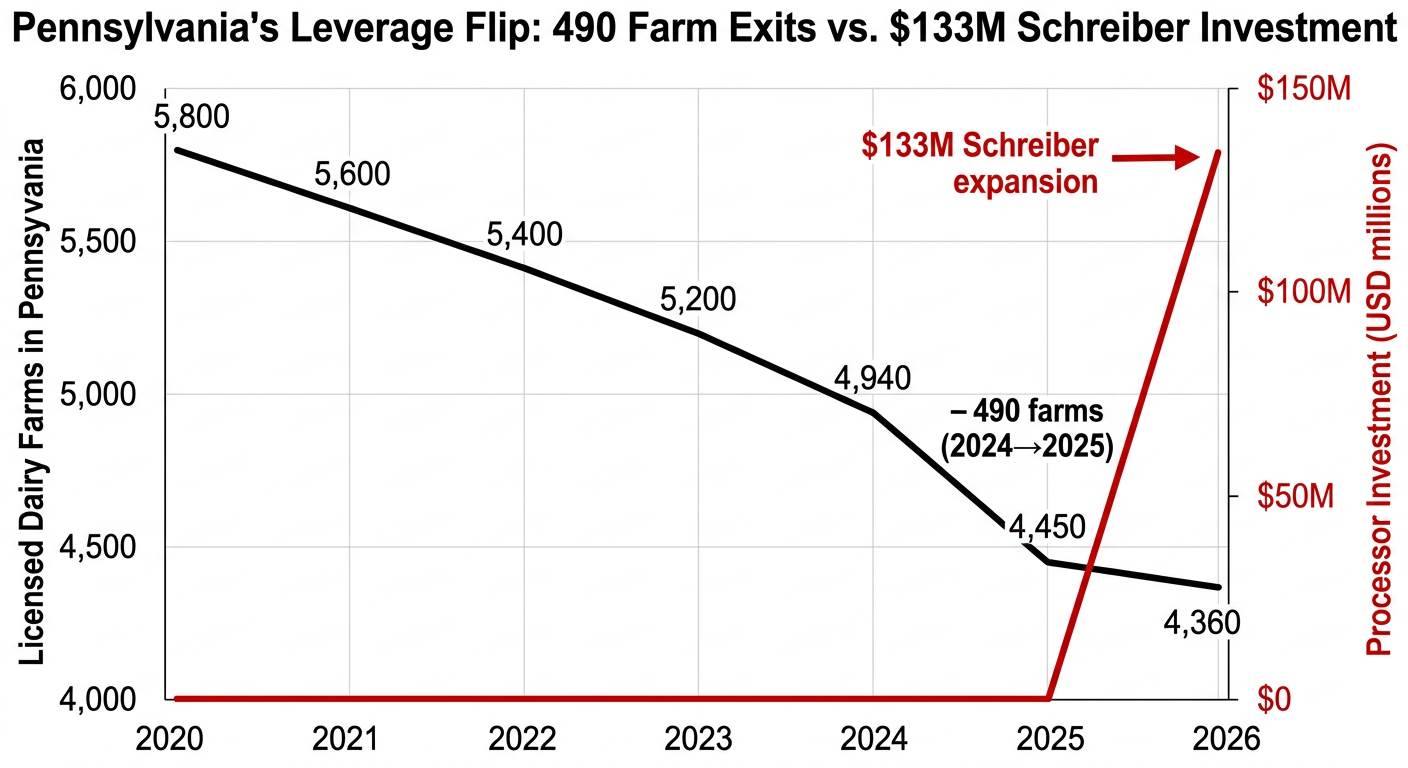
Looking at the USDA’s Milk Production report, notes that Pennsylvania lost 490 licensed dairy farms in 2025, dropping from 4,940 to 4,360 dairies — an 11.7% decline and about 41% of all U.S. dairy farm exits that year. Cow numbers fell by around 4,000 head to roughly 465,000, and state milk volume slipped 0.5% while national production rose 3.4%.

Schreiber has operated its Shippensburg plant since 2002. By locking in a $132.9 million expansion and 47 new jobs there, the company is effectively tethering more of its future yogurt strategy to south‑central PA.

Put that together:

  • Fewer herds.
  • Slightly fewer cows.
  • More processing demand backed by fresh capital.

For a large, proven direct‑ship supplier like Mercer Vu, that’s the moment the math flips. He’s no longer just one more shipper in a crowded market; he’s one of the relatively few large herds Schreiber can’t easily replace.

For a 200‑cow farm shipping into a co‑op pool, it raises the stakes on whether your co‑op is at the Schreiber table or repositioning milk into lower‑value outlets.

When Hissong said it’s “exciting and commendable for Schreiber Foods to continue investing in this plant” rather than chasing expansion “in West Texas, New York and other areas,” he was also naming the alternative: that $133 million could’ve gone somewhere else. pa

Trevor Farrell, Schreiber’s president, underlined that intent: “This expansion reinforces our long-term commitment to this area.”

Big capital decisions like this lock in procurement patterns and premium maps for years. If your region isn’t seeing those announcements — or if you’re not inside the sourcing radius — you’re playing a different premium game than your peers in PA or SD.

The 90‑Day Playbook Before the Premium Window Closes

Processors usually build their supply base 12–18 months before an expansion line hits full utilization. After that, they mostly manage what they’ve signed.

If you’re anywhere near Brookings or Shippensburg, the next 90 days matter.

If You’re a 500‑Cow SD Herd in the Pool

In the next 30 days:

  • Pull your last 12 months of DHIA records. Write down the average SCC, bacteria count, fat %, and protein %.
  • If SCC is over 200,000 or SPC/bacteria over 20,000 cfu/mL, fix that first. That kind of quality noise kills a procurement conversation before it starts.
  • Call your co‑op field rep and ask three precise questions:
    • “Do we currently supply Bel Brookings, Agropur Lake Norden, or Valley Queen Milbank?”
    • “Roughly what share of my milk routes to each?”
    • “Are there any volume commitments tied to those plants I should know about?”

By 90 days out:

  • Ask SDSU Extension or SD dairy groups for named contacts in Bel, Agropur, and Valley Queen procurement. Don’t sit back and hope they find you. 
  • Fix any bulk tank cooling problems — recorded temps above 40°F at two hours are a red flag for most audits.
  • Decide your minimum acceptable premium before you sit down. If Bel or a handler can’t clear your current blend by at least +$0.50/cwt on all lbs, your default assumption should be that staying in the pool is the safer play.

If You’re a 200‑Cow PA Farm in Schreiber’s Zone

This month:

  • Pull DHIA and tighten your own bar: for Class II yogurt, aim for SCC below 150,000, with <100,000 as the “best shot at premiums” goal.
  • If you’re at 180,000, that’s a 60–90 day barn‑level fix (dry‑cow program, milking routine, towels, prep).
  • Ask your co‑op explicitly: “Do we have a direct supply agreement with Schreiber Shippensburg? If yes, how much of that volume comes from farms my size?”

Then set your walk‑away number:

  • If your current blend is $15.05–$15.34/cwt, you probably need at least +$0.35–$0.50/cwt to justify a direct contract with tighter QA and termination clauses.
  • On 2.3M lbs, that’s about $8,050–$11,500/year. A +$0.25/cwt offer (~$5,750) may not be worth the extra risk when you can often find similar gains by tightening components and SCC inside the pool.

If You’re a 400–600‑Cow Herd Stuck in “We Should Talk.”

This week:

  • Call your actual processor contact — not the plant’s main line. If you don’t have a name and a number, that’s job one.
  • Prepare a one‑page supply proposal:
    • Average daily lbs.
    • 12‑month quality stats.
    • Hauling logistics.
    • A specific offer like: “We can deliver 8 million lbs/year on a 3‑year agreement with 6‑month mutual termination.”

Then get a contract review. Janzen’s work on milk contracts points to “market conditions,” “quality failures,” and “termination for cause” clauses that quietly shift risk to the producer. A $500 legal review on a $2M/year contract is inexpensive risk insurance.

If you don’t have at least a term sheet by fall 2026, assume this specific Bel/Schreiber expansion wave is largely spoken for. You’ll still move milk. You may not be in the first row of premium seats.

What This Means for Your Operation

  • Your contract lane matters more than your ZIP code. A 500‑cow herd inside Bel’s or Schreiber’s direct‑supply lane can see $58,500–$117,000/year from a $0.50–$1.00/cwt premium. A similar herd shipping through a pool might see $5,850–$17,550 — or nothing direct.
  • Quality is the ticket, not the bonus. For higher‑value Class II and branded cheese, <150,000 SCC is the starting line, and <100,000 is the target for serious premium conversations. If you’re above that, your first processor‑math project is fixing cows and routines, not chasing contracts.
  • The co‑op pool is a conscious trade, not a default. You give up some upside — maybe $29,000–$58,500/yearon a 500‑cow SD herd — in exchange for flexibility and regulatory payment protections. For small and mid‑size herds, that can be the smart play if you’re choosing it with eyes open.
  • Expansion somewhere shifts leverage everywhere. When corridor states like SD keep landing plants and keeping milk “right‑priced” for processors, it slowly nudges leverage away from regions that aren’t seeing those investments. That shows up later as weaker over‑order premiums and tighter contract terms.
  • 30‑day homework: Print your last 12 milk checks and DHIA summary. On one page, answer:
    • What % of your milk currently routes to a plant with announced expansion?
    • How many $/cwt above FMMO minimum are you actually getting?
    • How much of that spread is due to components/quality vs. processor premiums?

If you can’t answer those three without making a call, that’s your signal that the real story isn’t in Bel’s or Schreiber’s press release — it’s in the fine print of your own milk check.

Key Takeaways

  • If more than half your milk already ships to an expanding plant, you’re in the leverage band this article describes. Your decisions over the next 12–18 months are about terms and floors, not just having a home for your milk.
  • If all of your milk is pooled and none of it routes to an expanding plant, you’re probably subsidizing someone else’s premium. Your paths are: get into a sourcing radius, get into a different pool, or squeeze more out of components and costs where you are.
  • If you’re in that 300–500‑cow middle, you’re big enough that a good contract moves the needle, but small enough that you’re not the first call. Your edge is quality plus relationships — not waiting by the phone.

The Bottom Line

Whether you’re sitting in Franklin County or three states away, the practical question is simple: are you close enough — on paper and on quality — to be inside a processor’s premium lane, or are you quietly financing someone else’s expansion?

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.

Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
NewsSubscribe
First
Last
Consent

The Great Milk Divorce: The $383,000 IOFC Gap Splitting 500‑Cow Midwest Herds Into Upstairs and Downstairs Milk

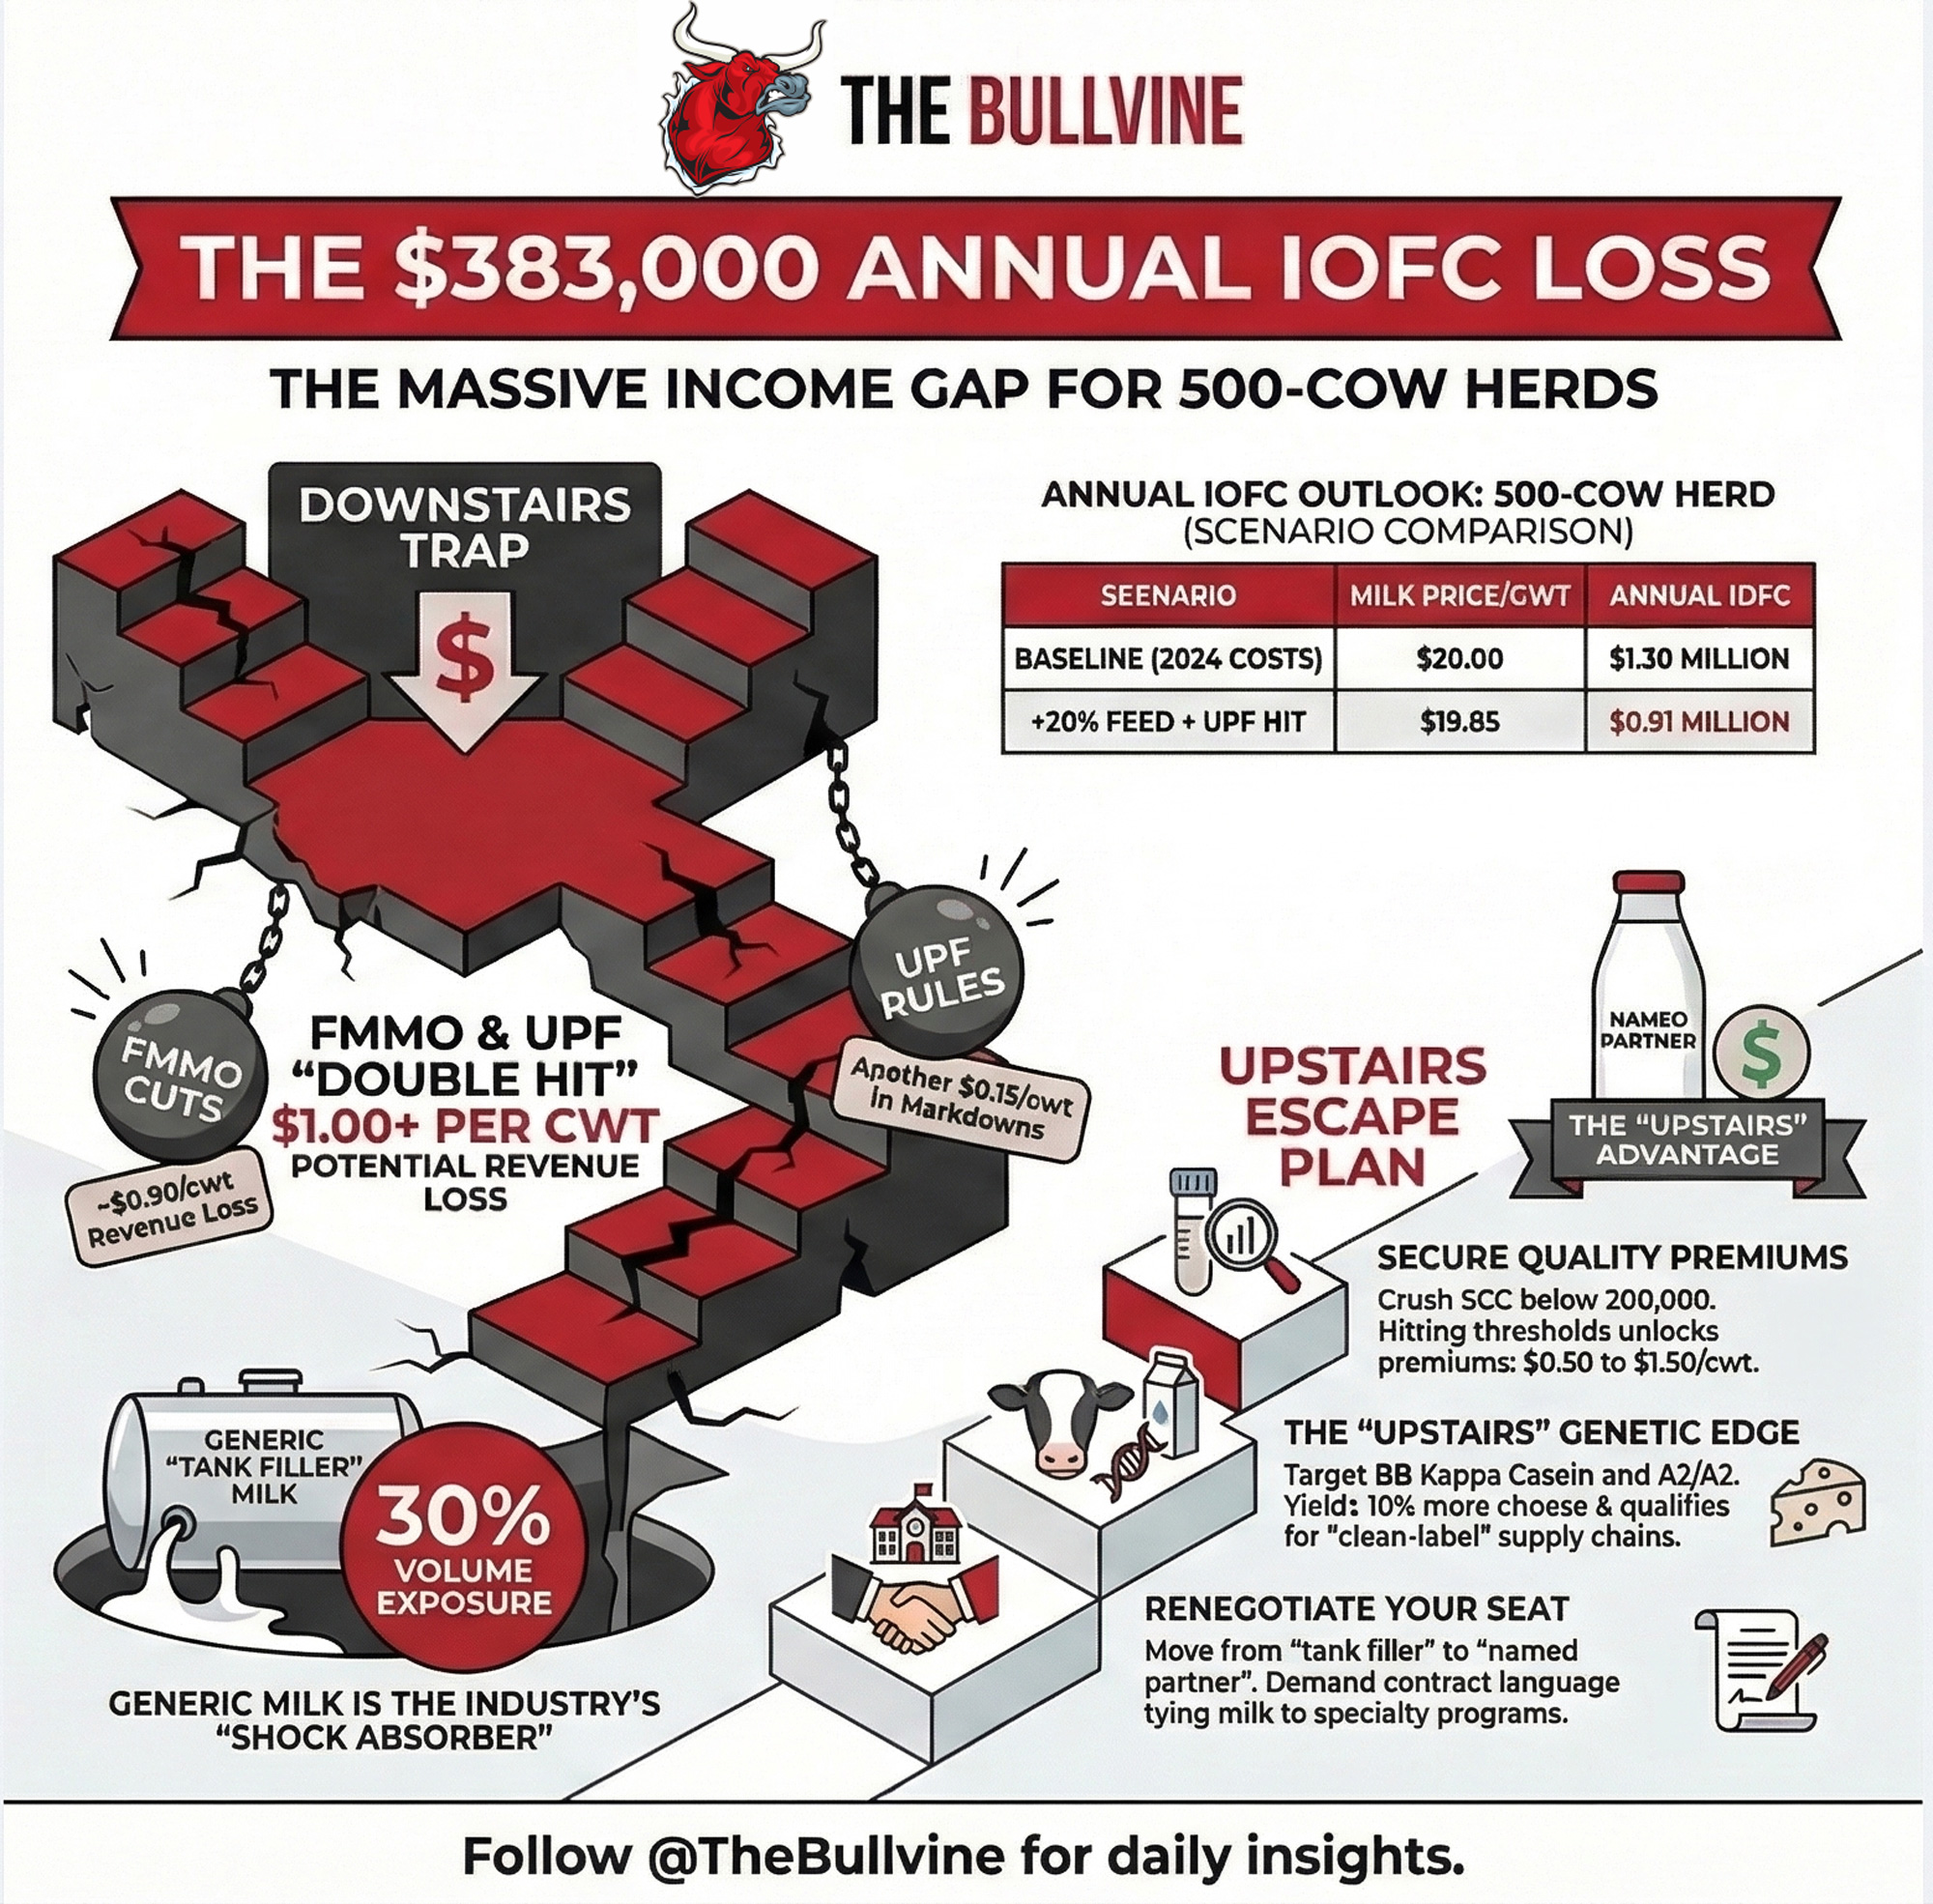
On a 500-cow Midwest dairy, FMMO and UPF rules can turn the same 425 cwt/day into either solid margins or a $383,000 IOFC hole.

Executive Summary: Federal make‑allowance changes and looming UPF rules are quietly splitting processor milk into “upstairs” and “downstairs” streams, with huge IOFC consequences for 500‑cow herds. Using Illinois FBFM data, the article shows how a 500‑cow Midwest dairy shipping 425 cwt/day can see a $383,000/year swing in income over feed as feed costs rise 10–20% and processors squeeze premiums on UPF‑exposed products. Mark, a composite based on 2024 FBFM economics, sits below full‑cost breakeven at $20 milk once the June 2025 FMMO make‑allowance cuts pull about $0.85–$0.93/cwt from his milk check. Sarah, built from the same regional benchmarks, closes that gap by driving SCC under 200,000, selecting for BB kappa casein and A2/A2, and renegotiating to tie her herd to school, hospital, and clean‑label programs. The piece walks through three IOFC scenarios, a transparent $0.15/cwt “UPF hit” calculation, and the math behind SCC and protein‑variant premiums. It then lays out a 30/90/365‑day playbook so producers can diagnose whether they’re upstairs or downstairs milk today, and what it takes to move up a tier in their buyer’s supply plan.

dairy milk quality premiums

A 500‑cow Midwest operation shipping 425 cwt a day can see about a 3,000/year swing in income over feed depending on which side of the plant its milk lands on. Two forces that have hit in the last nine months are widening that gap fast.

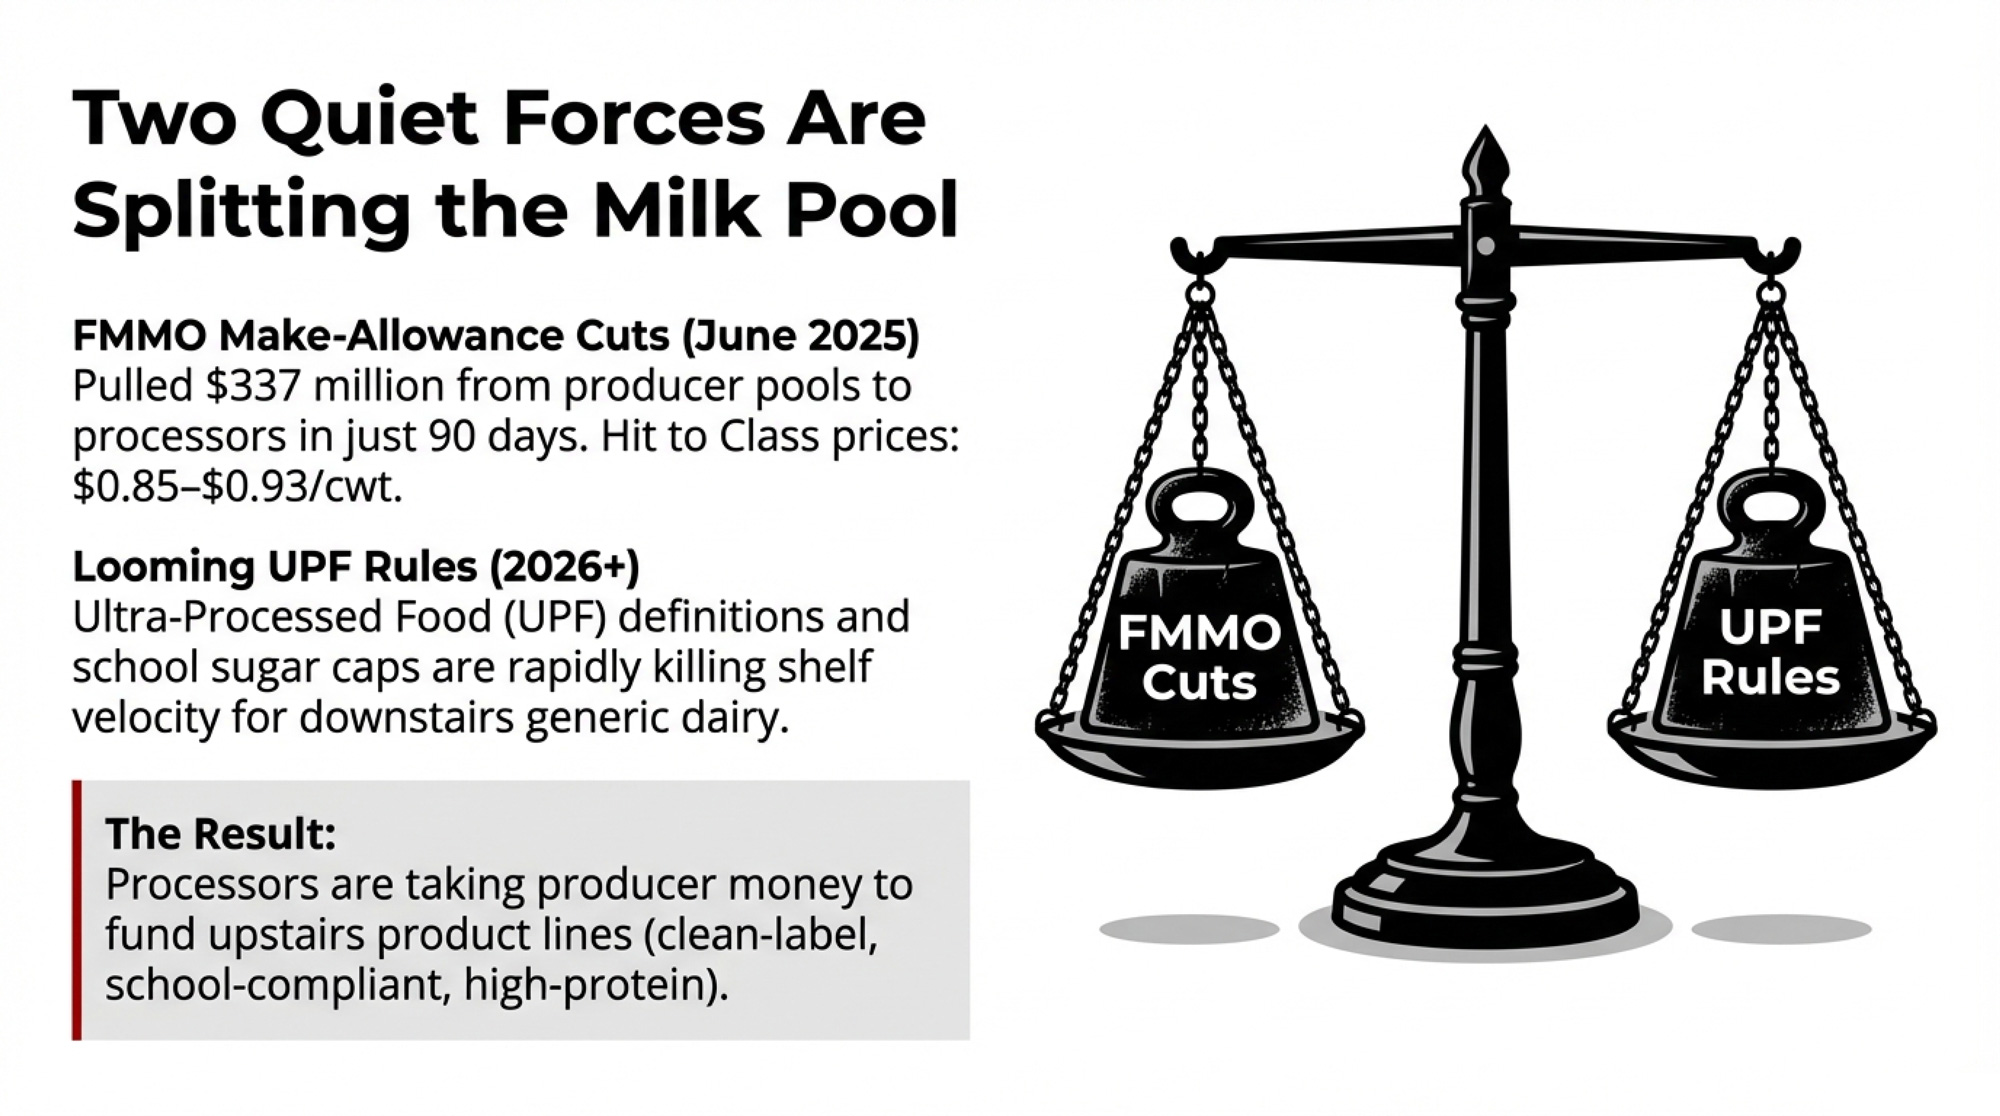
The June 2025 FMMO make‑allowance increase pulled an estimated $337 million from producer pool revenues in its first 90 days, per AFBF economist Danny Munch’s September 2025 Market Intel analysis, with Class price reductions ranging from $0.85 to $0.93/cwt. Now, a federal UPF definition — possibly arriving in 2026, based on HHS Secretary RFK Jr.’s public statements about FDA timelines — could sort every dairy plant’s product lines into “upstairs” (clean‑label, school‑compliant, high‑protein) and “downstairs” (likely to face UPF classification under proposed frameworks, with growing regulatory and market pressure on shelf velocity and margins).

Two composite operators — call them Mark and Sarah — show how that split plays out on real milk checks, benchmarked to Illinois 2024 FBFM data. They’re composites built from regional averages, not real people. But the math is real.

Mark’s Baseline: A Good Herd on the Wrong Side of the Plant

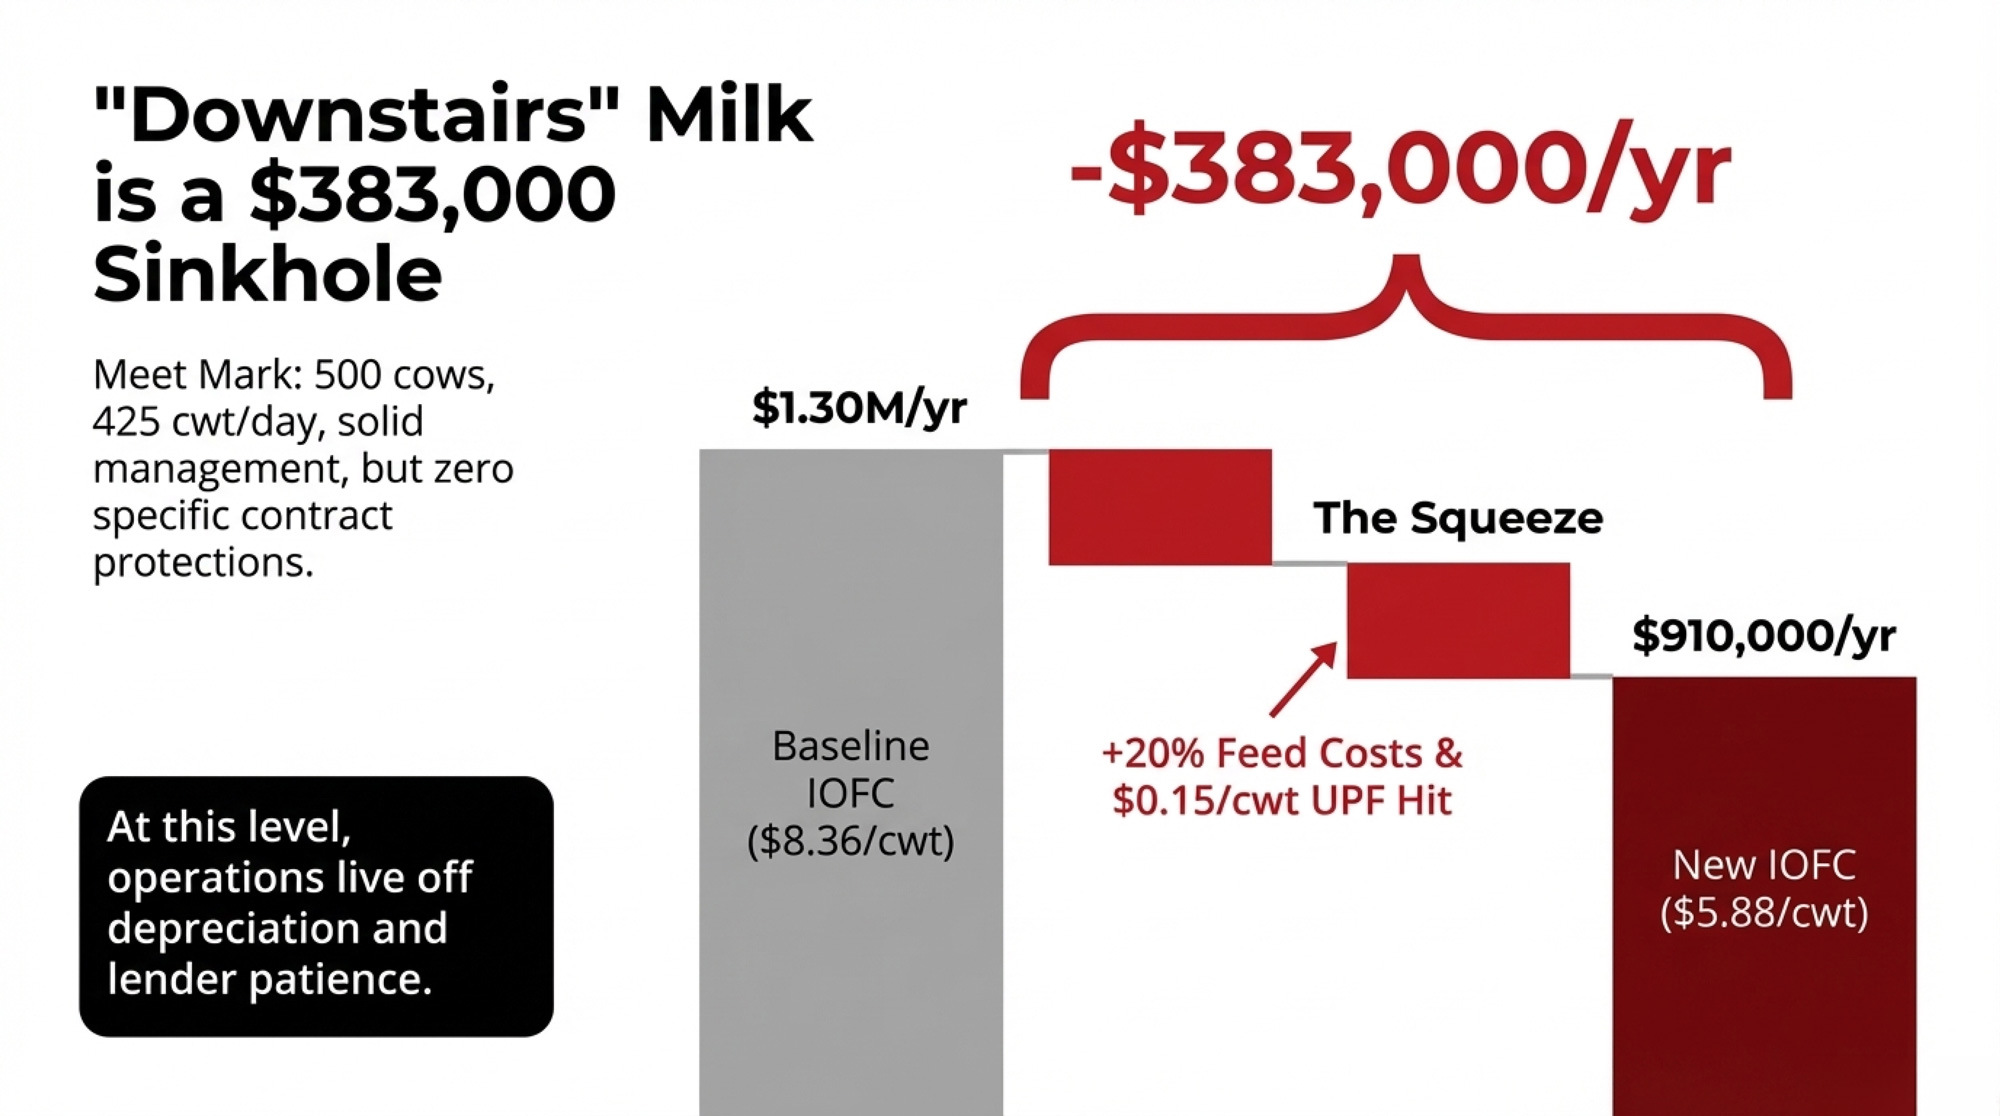
Mark runs 500 cows. Solid management. Reasonable genetics. His milk goes to a regional plant running both institutional and retail/UPF product lines.

His 2024 cost structure comes straight from the Illinois Farm Business Farm Management Association’s annual summary (farmdoc daily, December 18, 2025, Bradley Zwilling):

  • Feed cost: $11.64/cwt
  • Non‑feed costs: $11.92/cwt (a record high)
  • Total economic cost: $23.56/cwt
  • Milk production: 23,530 lbs/cow (up 549 lbs from 2023)

The actual 2024 milk price averaged $21.63/cwt — already $1.93 below total economic cost, costing Illinois producers negative $409/cow for the year. For this analysis, we model a $20.00/cwt milk price — in line with farmdoc’s 2025 projection of approximately $20.15/cwt and USDA’s outlook for further price decreases into 2026.

At $20.00 milk against $11.64 feed cost:

  • IOFC: about $8.36/cwt
  • Daily IOFC (425 cwt): ~$3,553/day
  • Annual IOFC: ~$1.30 million/year

He’s well below full‑cost breakeven. Then the ground moved.

The FMMO make allowance hit: On June 1, 2025, USDA raised allowances for butter, cheese, whey, and nonfat dry milk. Munch at AFBF estimated the hit to Class prices at $0.85–$0.93/cwt, shifting roughly $337 million from producer pools to processors in 90 days. That money went to the plant side of the ledger — funding reformulation, equipment upgrades, and premium‑grid tightening.

The UPF policy timeline is stacking up just as fast. In July 2025, HHS, FDA, and USDA issued a formal Request for Information on UPFs. USDA school meal standards now cap added sugar in flavored milk at 10 g/8 oz by the 2026–27 school year, and IDFA’s Healthy School Milk Commitment brought average added sugar in school milks down to 7.2 g/serving by July 2025.

That’s the federal picture. At the state level, California’s AB 1264 requires identification of harmful UPFs by July 1, 2026, with phased K–12 removal running through 2035. And north of the border, Canada’s mandatory front‑of‑pack nutrition labelling went live January 1, 2026, with enforcement beginning the same date.

Mark didn’t change his cows, his feeding program, or his contract. The economics around him changed plenty.

What Does a $383,000 Dairy IOFC Gap Look Like in 2026?

Most kitchen‑table talk still treats UPF as a nutrition story or a PR problem. Run the numbers, and it’s a feed and IOFC issue.

The following scenarios are not based on any specific processor’s current or announced pricing. They model what the economics could look like if UPF‑related policy changes affect feed costs and processor pricing grids over 3–5 years.

An IIED analysis of 2016–2021 agricultural support across 72 countries plus the EU, led by principal researcher Alejandro Guarín (published May 2025), found $14.5–$42.5 billion/year in support effectively subsidizing UPF ingredients — corn, soy, wheat, sugar — while penalizing fresh fruits and vegetables by about $16.3 billion/year. IIED’s modeling suggests repurposing those supports toward fruits, vegetables, and pulses would reduce production of previously subsidized commodities in OECD countries, though the exact percentage depends on how governments redesign the programs.

For this analysis, a 10–20% increase in feed costs over 3–5 years is the stress‑test range — not a forecast. But the directional pressure is real. USDA’s May 2025 Feed Outlook flagged that protein costs, soybean meal in particular, are expected to remain firm or increase even as corn softens — creating what the report described as a “barbell economy” of feed expenses. Purdue ag economist Michael Langemeier separately flagged DDG price shifts as a factor that could push livestock feed costs higher in 2026, with estimated DDG prices ranging from $145 to $155 per ton.

Three Scenarios for Mark’s 500‑Cow Herd

ScenarioFeed/cwtMilk Price/cwtIOFC/cwtDaily IOFCAnnual IOFC
Baseline (FBFM 2024 costs, projected price)$11.64$20.00$8.36$3,553~$1.30M
+10% feed$12.80$20.00$7.20$3,060~$1.12M
+20% feed + UPF hit$13.97$19.85$5.88$2,499~$0.91M

Note: The bottom scenario uses this article’s modeled assumptions — 30% of volume exposed to UPF‑side SKUs, $0.50/cwt plant markdown on that slice. These are illustrative. Your exposure depends on your buyer’s product mix and pricing grid.

The gap between baseline and the bottom row: about $383,000/year in IOFC. Same herd. Same people. Very different economics.

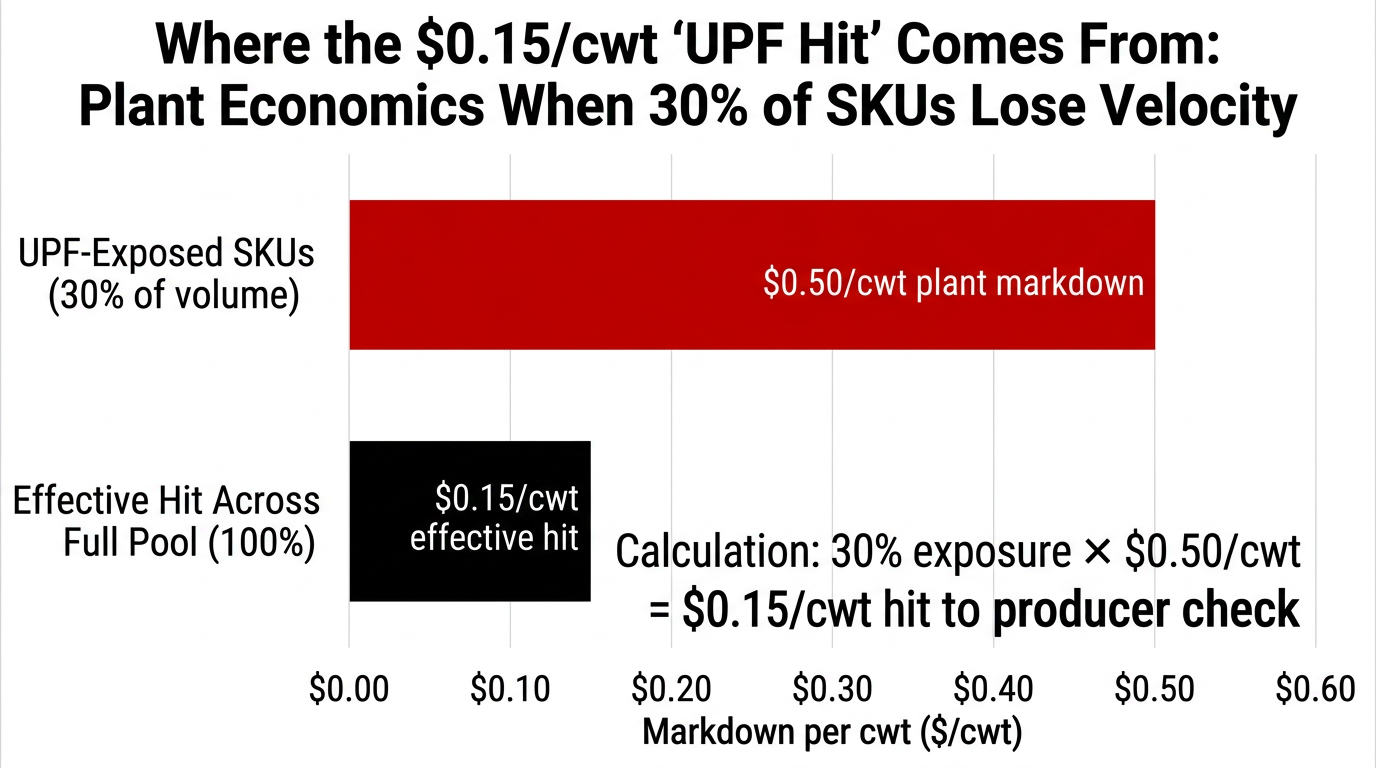
Where Does the $0.15/cwt “UPF Hit” Come From?

This isn’t on anyone’s milk statement yet. It’s a calculated risk tied to what happens when the plant’s downstairs side starts losing shelf velocity.

When Chile’s mandatory warning labels and marketing restrictions took effect, purchases of “high‑in” beverages — primarily sugary drinks — fell 23.7% over 18 months (Taillie et al., PLOS Medicine, February 2020). Canada’s black‑and‑white warning symbols for high‑sugar, high‑sodium, and high‑saturated‑fat products went live in January 2026, with immediate enforcement. FDA’s proposed front‑of‑pack labels could follow.

Plants won’t eat reformulation and marketing costs on slow‑moving UPF‑flagged SKUs forever. They’ll pass more of that pressure back through the pool — lower premiums, tighter quality grids, higher marketing deductions.

If 30% of Mark’s volume feeds UPF‑exposed SKUs and the plant shaves $0.50/cwt on that slice, the effective hit across his whole pool is 0.30 × $0.50 = $0.15/cwt. New effective price: $20.00 − $0.15 = $19.85/cwt.

IOFC in the $5.88–$6.10/cwt range, while non‑feed costs sit near $11.92/cwt, is where operations start living off depreciation, open lines of credit, and lender patience.

How Are Dairy Processors Sorting Upstairs From Downstairs Milk?

The Wisconsin Cheese Makers Association, representing more than 850 companies and cooperatives across 44 states, laid this out directly in their September 22, 2025 position statement: “In practice, a cup of fortified yogurt or a protein‑packed slice of cheese could be treated as nutritionally suspect, because it required pasteurization, culture development, or added rennet to create.” NMPF filed formal comments on October 23, 2025, warning that how UPFs are ultimately defined “could affect how [dairy] products can be marketed, and whether or not they will be included in federally funded programs such as SNAP, WIC or school meals programs.” IDFA urged the FDA not to rush a definition that lumps all processing together.

That’s the public positioning. The private math is sharper.

Upstairs products — school milk meeting sugar caps, clean‑label yogurts, high‑protein UF, A2‑certified brands, hard and specialty cheeses — are politically and contractually protected. Products more likely to face UPF classification— heavily sweetened yogurts, flavored snack cups, sugary retail-flavored milks, and private‑label processed cheese — are facing growing regulatory and market pressure.

Plants now have more manufacturing margin from the make‑allowance bump to fund that upstairs transition. They’ll pay more for milk feeding the upstairs lines — and spend less to keep the downstairs pool happy.

Where plant capacity is tight, and every tanker matters, that shift hasn’t landed yet. Generic volume still has negotiating power. But plants investing in upstairs products are getting pickier about which herds earn those seats — and building the kind of buyer relationships that survive the next downturn.

Mark’s milk goes to both places. His contract doesn’t specify which.

Sarah’s Turn: What Moving Upstairs Actually Takes

Sarah farms in the same region. Similar size. She looked at the same FMMO and UPF calendar and saw a 24‑month repositioning window, not a label headache.

She asked her processor one question: When you pitch school milk or hospital yogurt, is our herd one of the names in the deck? The honest answer — good volume, but not the herd they highlight in RFPs — told her everything.

So she made three moves.

Move 1: Crush SCC and Bacteria Counts

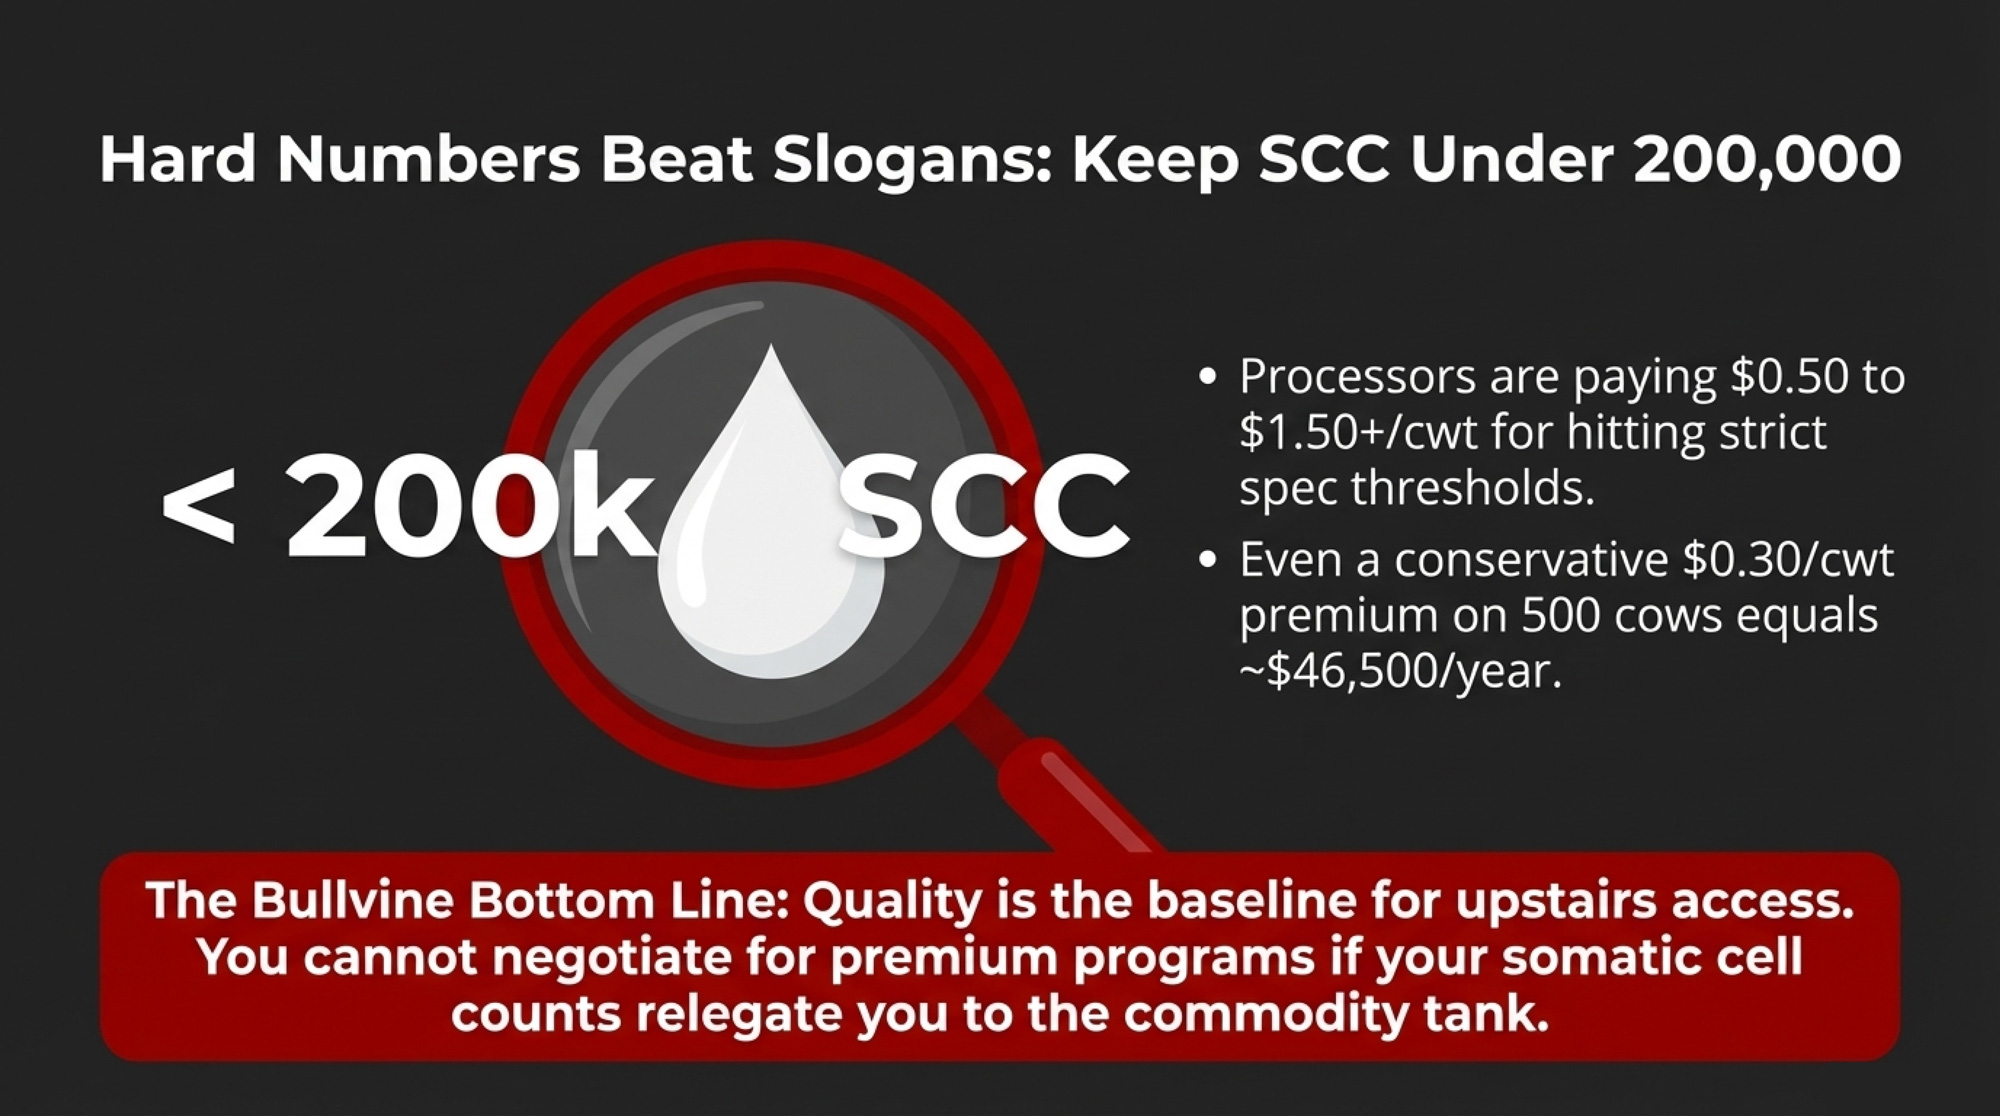
Pulling herd SCC from the mid‑300k band under 200,000 unlocks consistent quality premiums. The Bullvine’s own reporting on processor expansion found that farms hitting spec thresholds are seeing premiums ranging from $0.50 to over $1.50/cwt, and an 85‑cow Pennsylvania operation captured $0.75/cwt through relatively simple bypass protein and consistent feed push‑ups. Even at a conservative $0.30/cwt SCC premium on 500 cows shipping 425 cwt/day, that’s 425 × $0.30 = $127.50/day, roughly $46,500/year. That’s before the extra pounds and lower treatment costs.

Move 2: Get Specific on Protein Variants

Sarah’s genetics team didn’t just target “more solids.” They targeted which solids matter for products that survive UPF scrutiny.

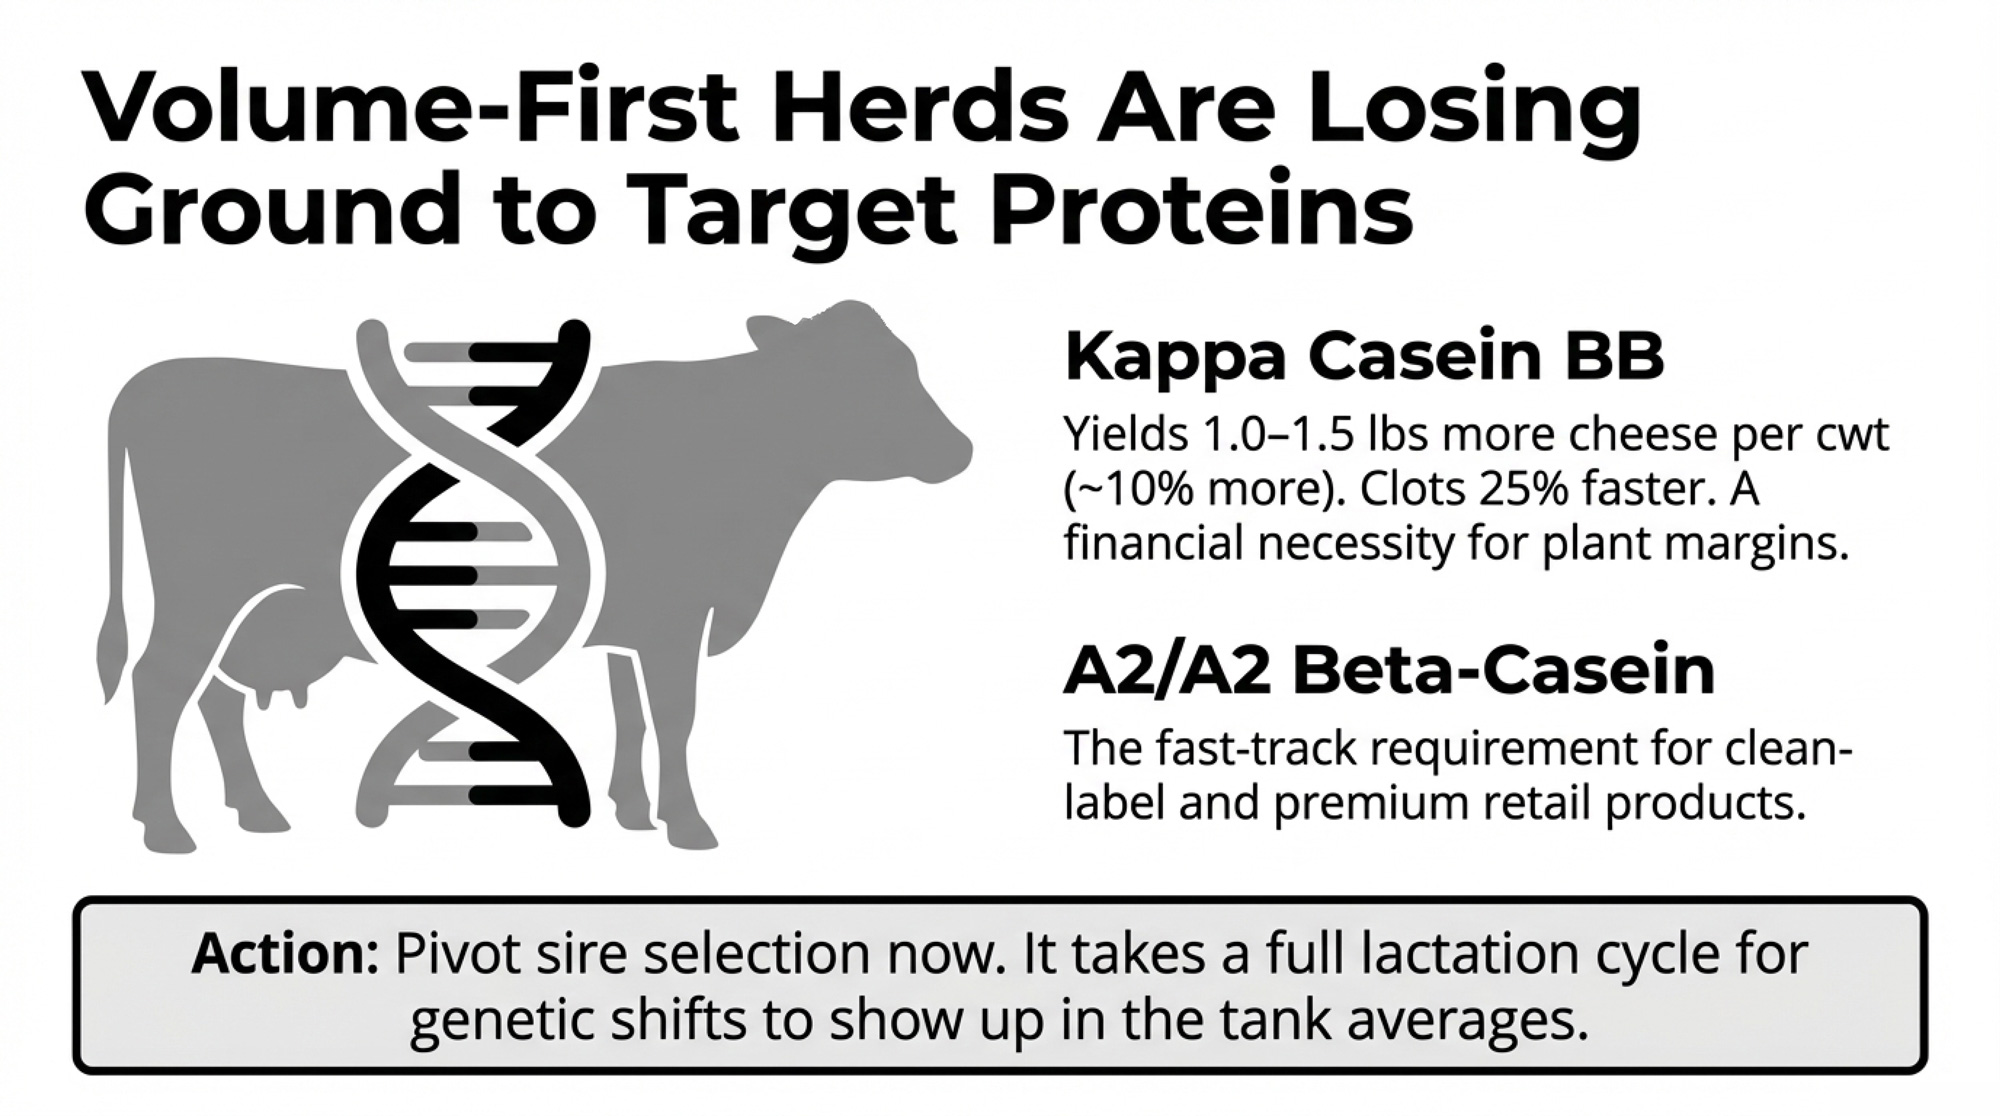
Kappa Casein BB: Cheese from BB cows clots around 25% faster, produces curd roughly twice as firm, and yields about 1.0–1.5 lbs more cheese per cwt — roughly 10% more — than AA cows. For a cheese plant, that’s not a nice‑to‑have. That’s money. Lactanet data (CDN document #586, August 2022) show BB is the dominant genotype in Jerseys (82.2%) and Brown Swiss (61.5%), but in Holsteins, it’s just 37.6% — meaning active selection toward BB and AB sires matters most where most milk is produced.

A2/A2 Beta‑Casein: Lonnie Holthaus at Milkhaus Dairy in Fennimore, Wisconsin, has selectively bred his Holsteins for A2/A2 — more than half the herd now produces only A2 protein milk, with products available through local grocery stores and direct‑to‑consumer channels. UW–Madison Extension notes the Holstein breed “is quickly moving to be an A2A2 only breed,” with a survey of five A.I. studs turning up over 800 A2A2 Holstein bulls — by far the most common beta‑casein combination now offered.

Lactanet’s published breeding guidance spells out the path: producers can increase BB frequency by “selecting for BB or AB sires,” and increase A2 frequency by “preferred use of A2A2 or A1A2 sires.” It’s not a complicated selection — it just has to be intentional.

New U.S. plant capacity backs the same direction. IDFA reported in October 2025 that processors have committed more than $11 billion in new and expanded manufacturing capacity across 19 states — over 50 individual building projects between 2025 and early 2028. A significant share of the capacity is for cheese and whey, positioned for what MarkNtel projects as a global whey protein market growing from .5 billion (2023) to .2 billion by 2030. UW–Madison Extension dairy economist Leonard Polzin noted that fat and protein components keep climbing “every single year” — and the new processing infrastructure is built to reward exactly that. Volume‑first herds are losing ground.

Sarah pivoted sire selection toward BB kappa casein and A2/A2 alongside health, solids, and longevity. Not a one‑month fix — it took a lactation cycle to start showing up in tank averages.

Move 3: Renegotiate Her Seat in the Supply Plan

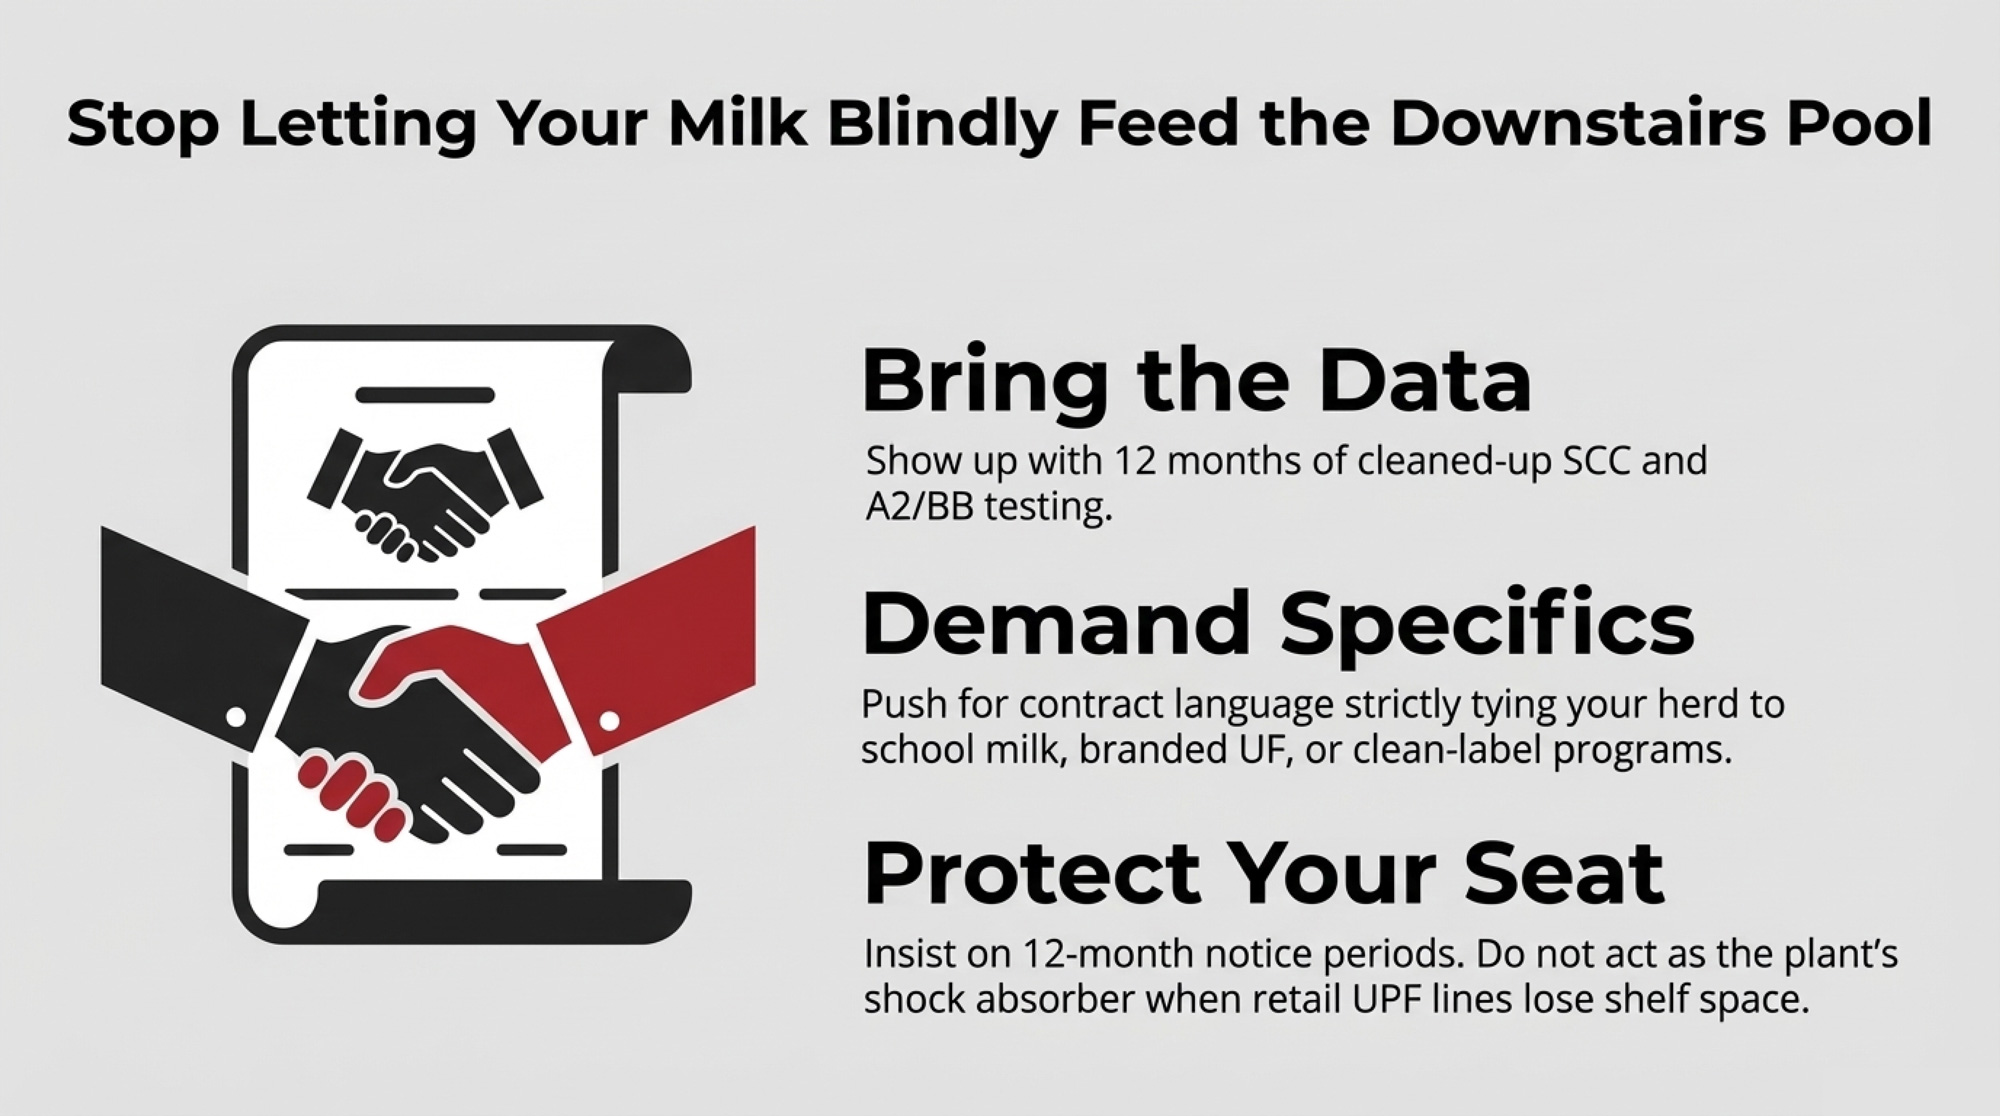
Instead of asking for a better average price, she brought 12 months of cleaned‑up SCC, strong components, and documented A2/BB testing to the table. She pushed for program language tying her herd to specific products and 12‑month notice periods, so she wasn’t locked in if the plant doubled down on UPF‑heavy retail.

Two years from now, both herds could still be shipping 425 cwt/day. The difference sits on the milk check. Sarah carries a stable stack of quality and program premiums — consistent with The Bullvine’s reporting on processor expansion, which documented premiums of $0.50 to over $1.50/cwt for farms meeting spec thresholds, with top‑tier programs potentially reaching higher for herds that qualify on components, protein variants, and SCC simultaneously.

MetricMark (Downstairs)Sarah (Upstairs)Gap Impact
Herd Size500 cows500 cowsIdentical
Daily Volume425 cwt/day425 cwt/dayIdentical
SCC Average320,000185,000−42% SCC
Kappa Casein / A2 StatusNot testedBB & A2/A2 selectedActive selection
Processor Contract TypeGeneric pool volumeNamed in school/hospital RFPsProtected seat
Quality/Program Premiums$0.10/cwt$0.80/cwt+$0.70/cwt
Feed Cost/cwt$13.97$13.97Identical
Milk Price Received$19.85/cwt (base − UPF hit)$20.80/cwt (base + premiums)+$0.95/cwt
IOFC/cwt$5.88$6.83+$0.95/cwt
Annual IOFC~$912,000~$1,059,000—
Annual IOFC Difference——+$147,000/year

Mark is still letting his milk feed the downstairs pool.

Can You Move Off the Downstairs Staircase in 24 Months?

Federal UPF definitions, front‑of‑pack labels, and school standards all have dates attached. Here’s what to do with that calendar.

In the Next 30 Days

  • Pull the last 3–6 months of milk statements. What’s your average SCC? Where are protein and butterfat sitting? How much per cwt is the base vs. quality vs. program premiums?
  • Print your milk supply agreement. What’s the notice period? Does it mention specific programs — school milk, branded UF, clean‑label — or are you just generic pool volume?
  • Ask your field rep one blunt question: “When you pitch our plant’s school and clean‑label contracts, is our herd one you mention by name — or are we just filling tanks?”
  • Check your herd’s kappa casein and A2/A2 status. Individual tests run about $40/head through labs like UC Davis VGL; the full Milk Protein Panel (A2 + kappa casein + beta‑lactoglobulin) runs $93/head (UC Davis VGL pricing, October 2023). On 500 cows, that’s $20,000–$46,500 — significant upfront, but budget it against the $46,500/year SCC premium recovery alone. If you’re already running broader panels, Zoetis CLARIFIDE Plus costs roughly $43/head, including health and wellness traits.

Red flag: No quality or program premiums on your statement, no program language in your contract, and your buyer can’t link your herd to anything strategic? You’re deep in the downstairs story right now.

Green flag: Your buyer names your herd specifically in RFP submissions, your contract ties to at least one program, and you’ve got 12+ months of SCC under 200K on record? You’re upstairs. Protect that seat — keep specs high, contract language specific, and your testing documentation current.

In the Next 90 Days: Pick Your Branch

  1. Upgrade into the A‑pool where you are. Targets: SCC consistently <200,000, protein >3.15%, start genomic testing for kappa casein BB and A2/A2. You gain leverage with your current buyer, but you’ll spend more upfront on vet work, cow comfort, nutrition, and testing.
  2. Scout a processor switch. Map processors within a realistic hauling radius that are building school, hospital, “no UPF,” A2, or specialty cheese contracts. You gain alignment with a buyer who values upstairs milk. You take on hauling changes, relationship risk, and the chance that if the new buyer’s program changes specs mid‑contract, you’re rebuilding from scratch in a market where your old plant already filled your slot.
  3. Renegotiate your seat at the table. Push for a program language that ties your herd to products that must survive UPF rules. Aim for 12‑month notice periods. You keep the relationship you know, but it may be a harder conversation if your buyer isn’t under immediate pressure yet.

Opportunity signal: If your buyer is already talking about school sugar caps, UPF definitions, or “real food” wins with institutions, they’re feeling the heat. That’s when A‑team milk becomes more valuable inside their business than it looks on your statement.

Over the Next 365 Days

Build a 6–12 month run with SCC under 200,000 and documented component and protein‑variant testing. Lean hard into sires that bring BB kappa casein, A2/A2, solids, and longevity. After that, go back to your buyer with a simple ask: “Here’s our updated quality and component record. Which of your school, hospital, or clean‑label programs could we qualify for, and what premiums go with them?”

What This Means for Your Operation

  • If your IOFC is under about $7/cwt and quality/program premiums are thin on your statement, you’re in the zone this $383,000 gap describes. Run your own numbers — swap in your feed cost, your milk price, and your best guess at how much of your buyer’s volume feeds UPF‑exposed products.
  • If your buyer can name specific products and contracts your herd supports, you’re already upstairs. Don’t assume that the seat is permanent — keep your specs high and your contract language specific.
  • If your contract doesn’t mention notice periods or programs, assume you’re the shock absorber, not the protected volume. That doesn’t mean panic. It means read the fine print and decide if that’s where you want to sit in your buyer’s supply plan.
  • If you don’t know your herd’s kappa-casein or A2 status, you can’t negotiate for traits you haven’t tested for. At $40–$93/head, that’s cheap insurance relative to the premium it could unlock.

Signals to Watch

  • FDA UPF definition timeline: If a federal definition arrives in 2026, processor contract language could start shifting within 90 days of publication. We’ll be tracking processor responses and contract grid changes as they surface — this is the story to watch for the next 18 months.
  • California’s AB 1264 identification deadline (July 1, 2026): The first real test of which products get flagged and which don’t. What happens in California school districts will signal how other states and federal programs respond.
  • Your buyer’s institutional wins: Track whether your processor is growing school milk and hospital contracts. If those are growing, your leverage is growing too.

Key Takeaways

  • If your IOFC on a 500‑cow herd is drifting under ~$7/cwt, today’s FBFM‑style costs and a small UPF‑driven markdown can easily add up to a $383,000/year gap between you and a neighbour on the upstairs side of the plant.
  • The fastest upgrades into that upstairs pool are hard numbers, not slogans: SCC consistently under 200,000, protein north of ~3.15%, and a clear plan to move your herd’s genetics toward BB kappa casein and A2/A2 for cheese, school, and clean‑label programs.
  • Your most important 30‑day check isn’t on a spreadsheet; it’s one question for your field rep: “When you pitch school and clean‑label contracts, is our herd one you mention by name—or are we just filling tanks?”
  • If your contract doesn’t spell out program links and at least a 12‑month notice period, assume you’re in the cut‑first volume, not the protected pool—and build a 365‑day plan to either upgrade in place, switch buyers, or renegotiate your seat.

The Bottom Line

In the next 30 days, do one thing: calculate your real IOFC — not from memory, from your actual milk statements and feed records. Break down how much of your check is base price vs premiums. Then ask your buyer in plain language: Is our herd part of the milk you rely on for your safest contracts, or are we in the pool you can cut first?

What’s your real IOFC this month — and does your buyer know your milk by name, or just by tank number?

Complete references and supporting documentation are available upon request by contacting the editorial team at editor@thebullvine.com.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.

Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
NewsSubscribe
First
Last
Consent
Send this to a friend