Archive for Environmental Regulations

The $128,320 Additive Bill: Why the First Dairy Carbon Credit Wasn’t Bovaer

$128,320 a year on 1,000 cows, and 35 cents a cow a day you don’t get back. The first U.S. dairy methane credit ever sold came off a different product entirely — and the difference is the contract.
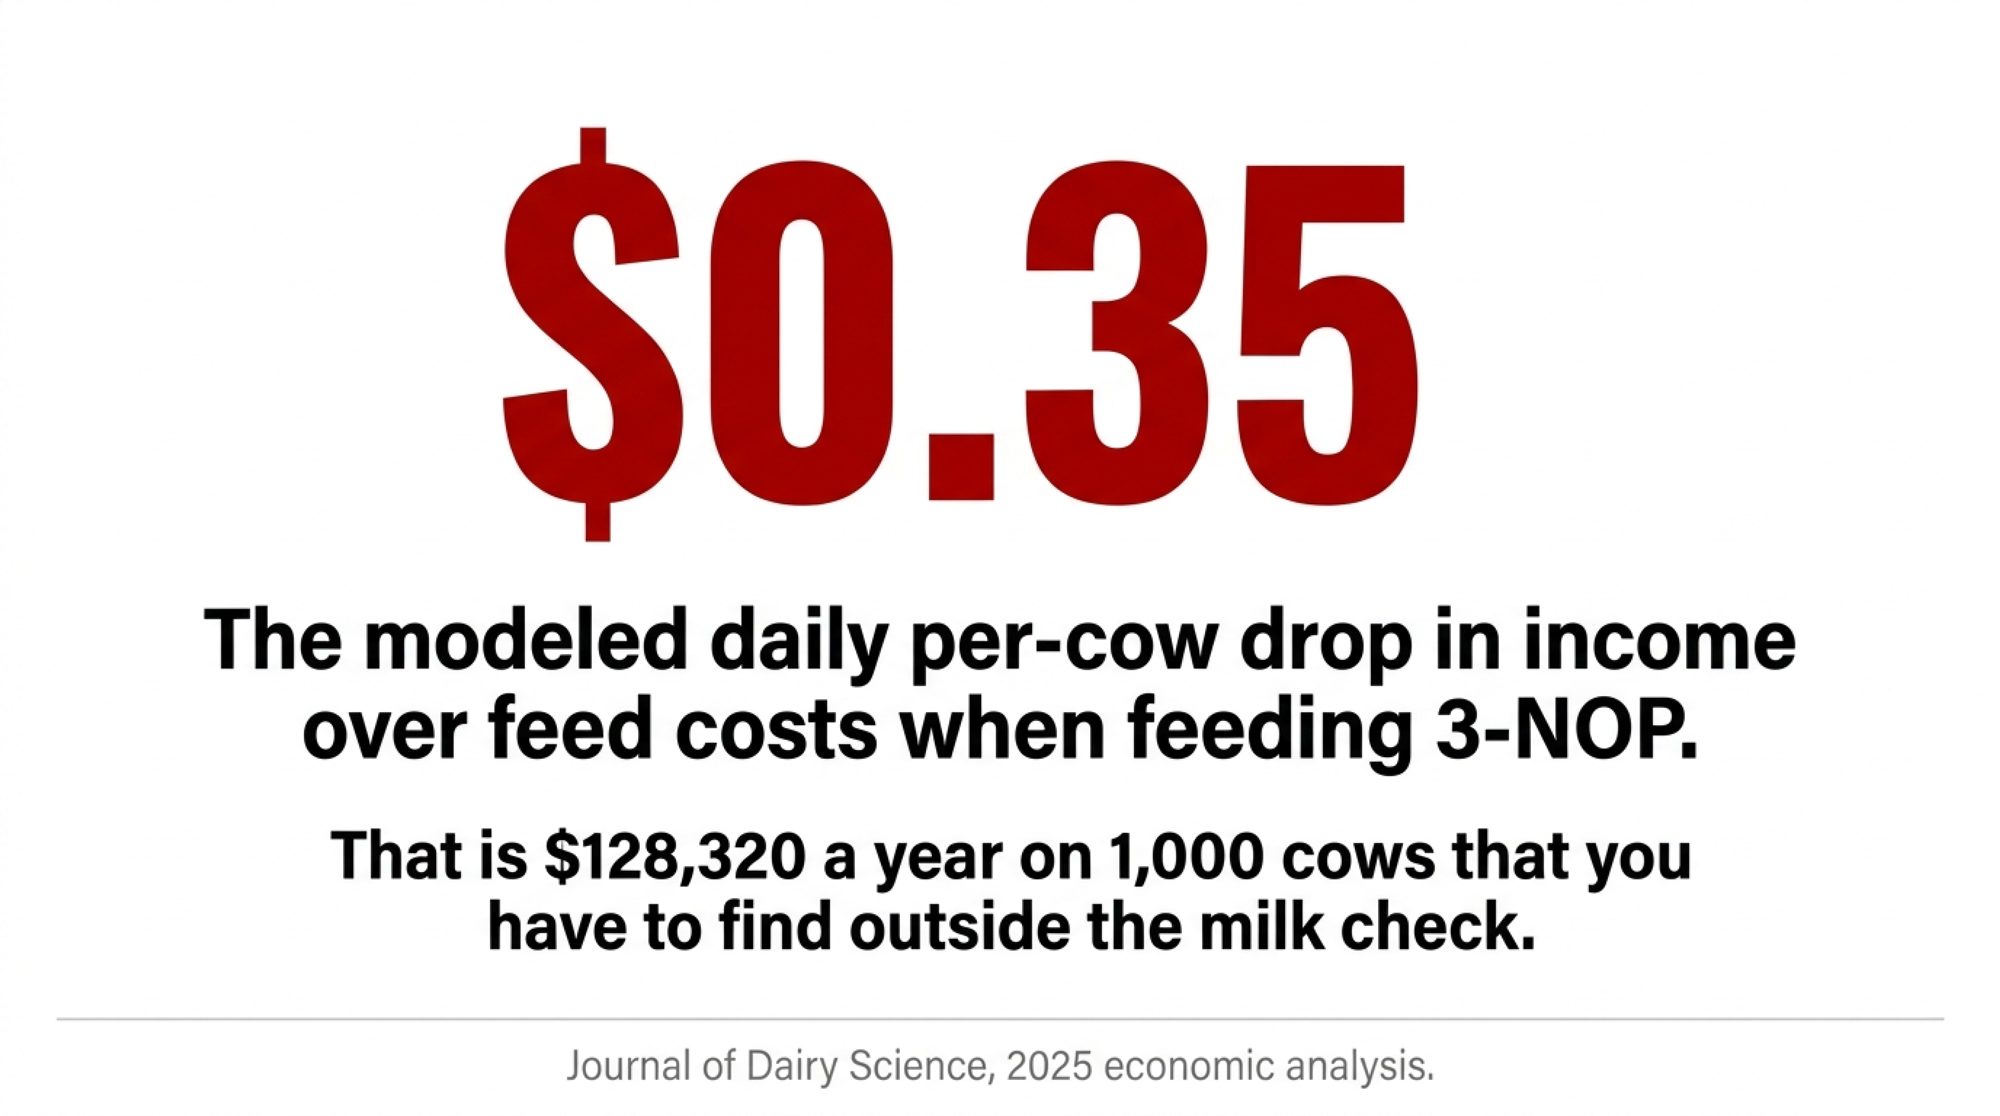
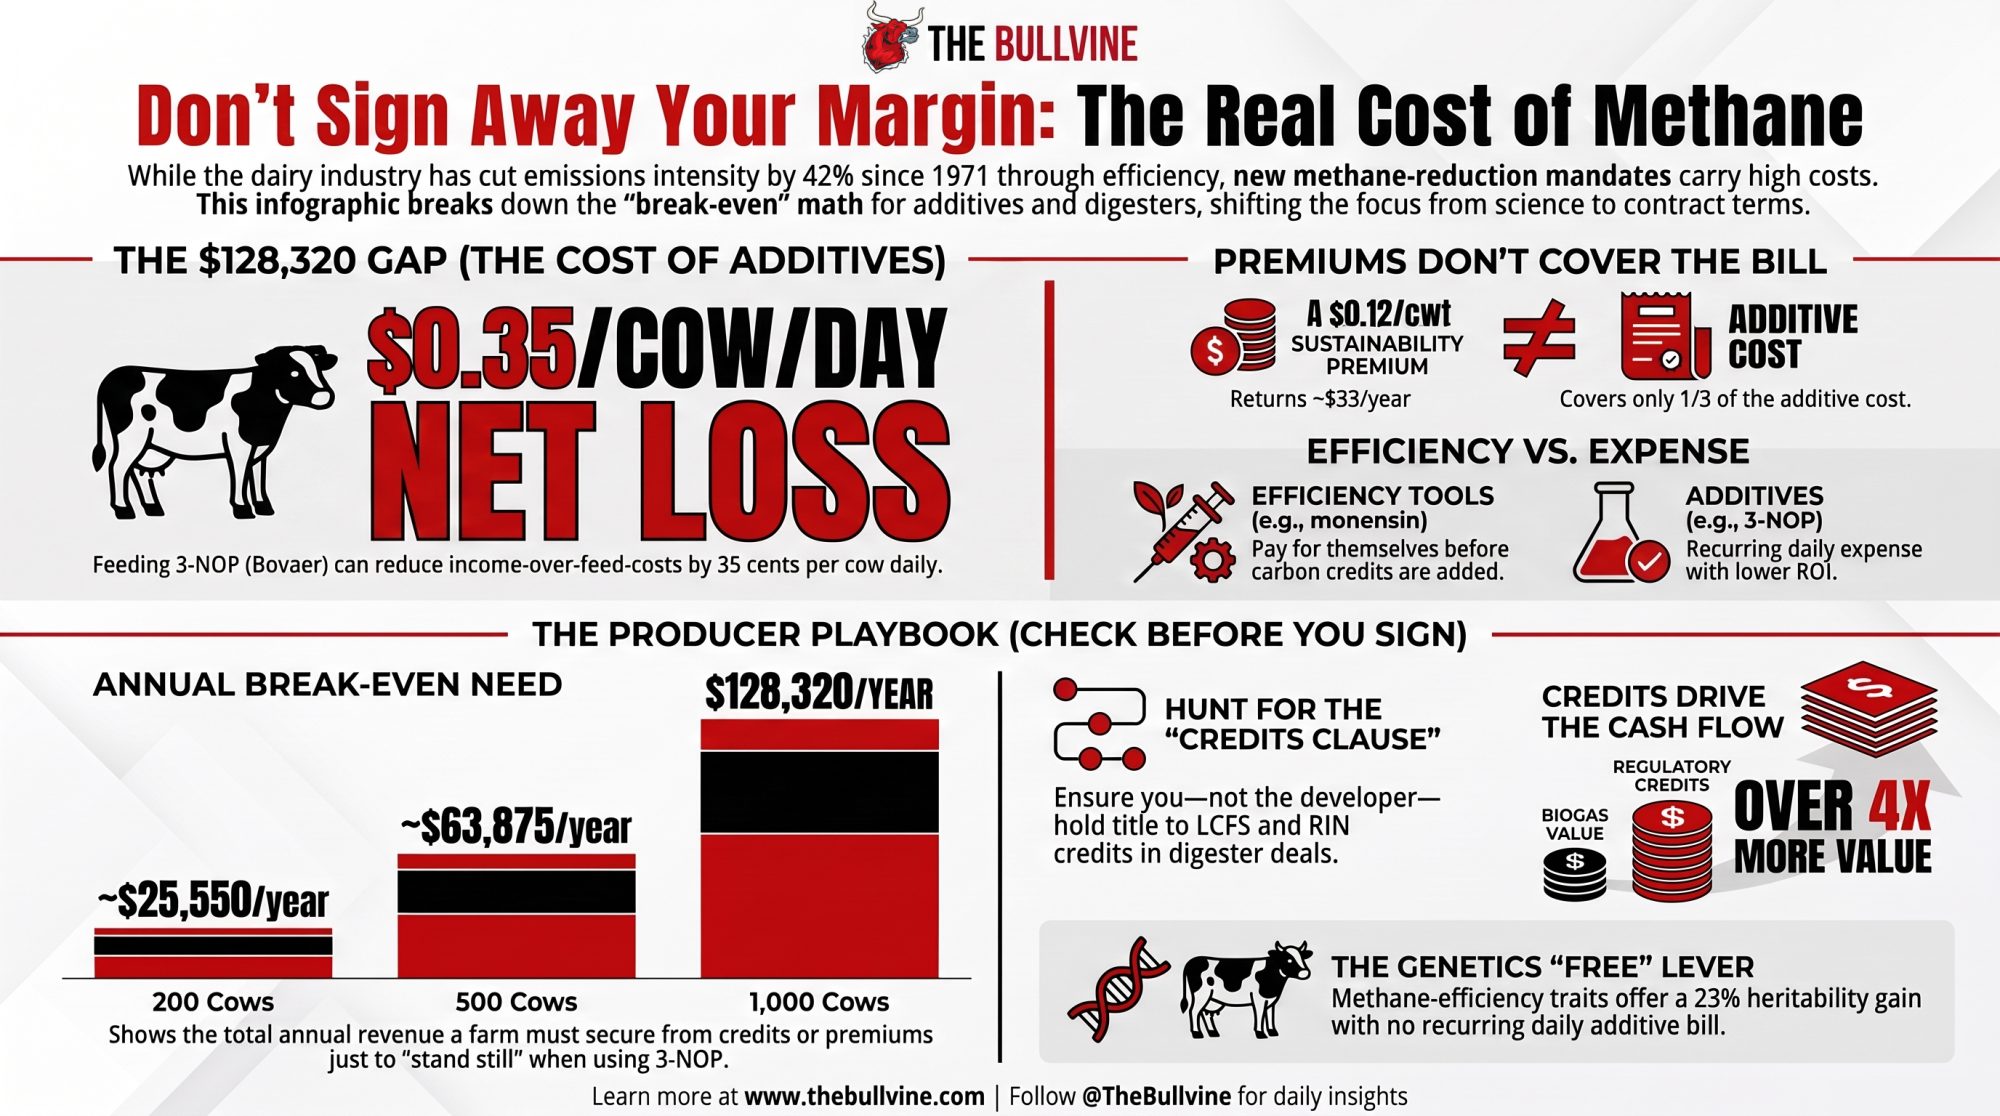
Start with the number that belongs on every whiteboard in every barn office. A 2025 economic analysis in the Journal of Dairy Science modeled a 1,000-cow dairy feeding 3-nitrooxypropanol, the methane additive sold as Bovaer and made by DSM-Firmenich. Feeding it cut income over feed costs by roughly $0.35 per cow per day, which on that herd works out to about $128,320 a year the farm has to find somewhere other than the milk check . That’s not a worst case. That’s the modeled outcome.
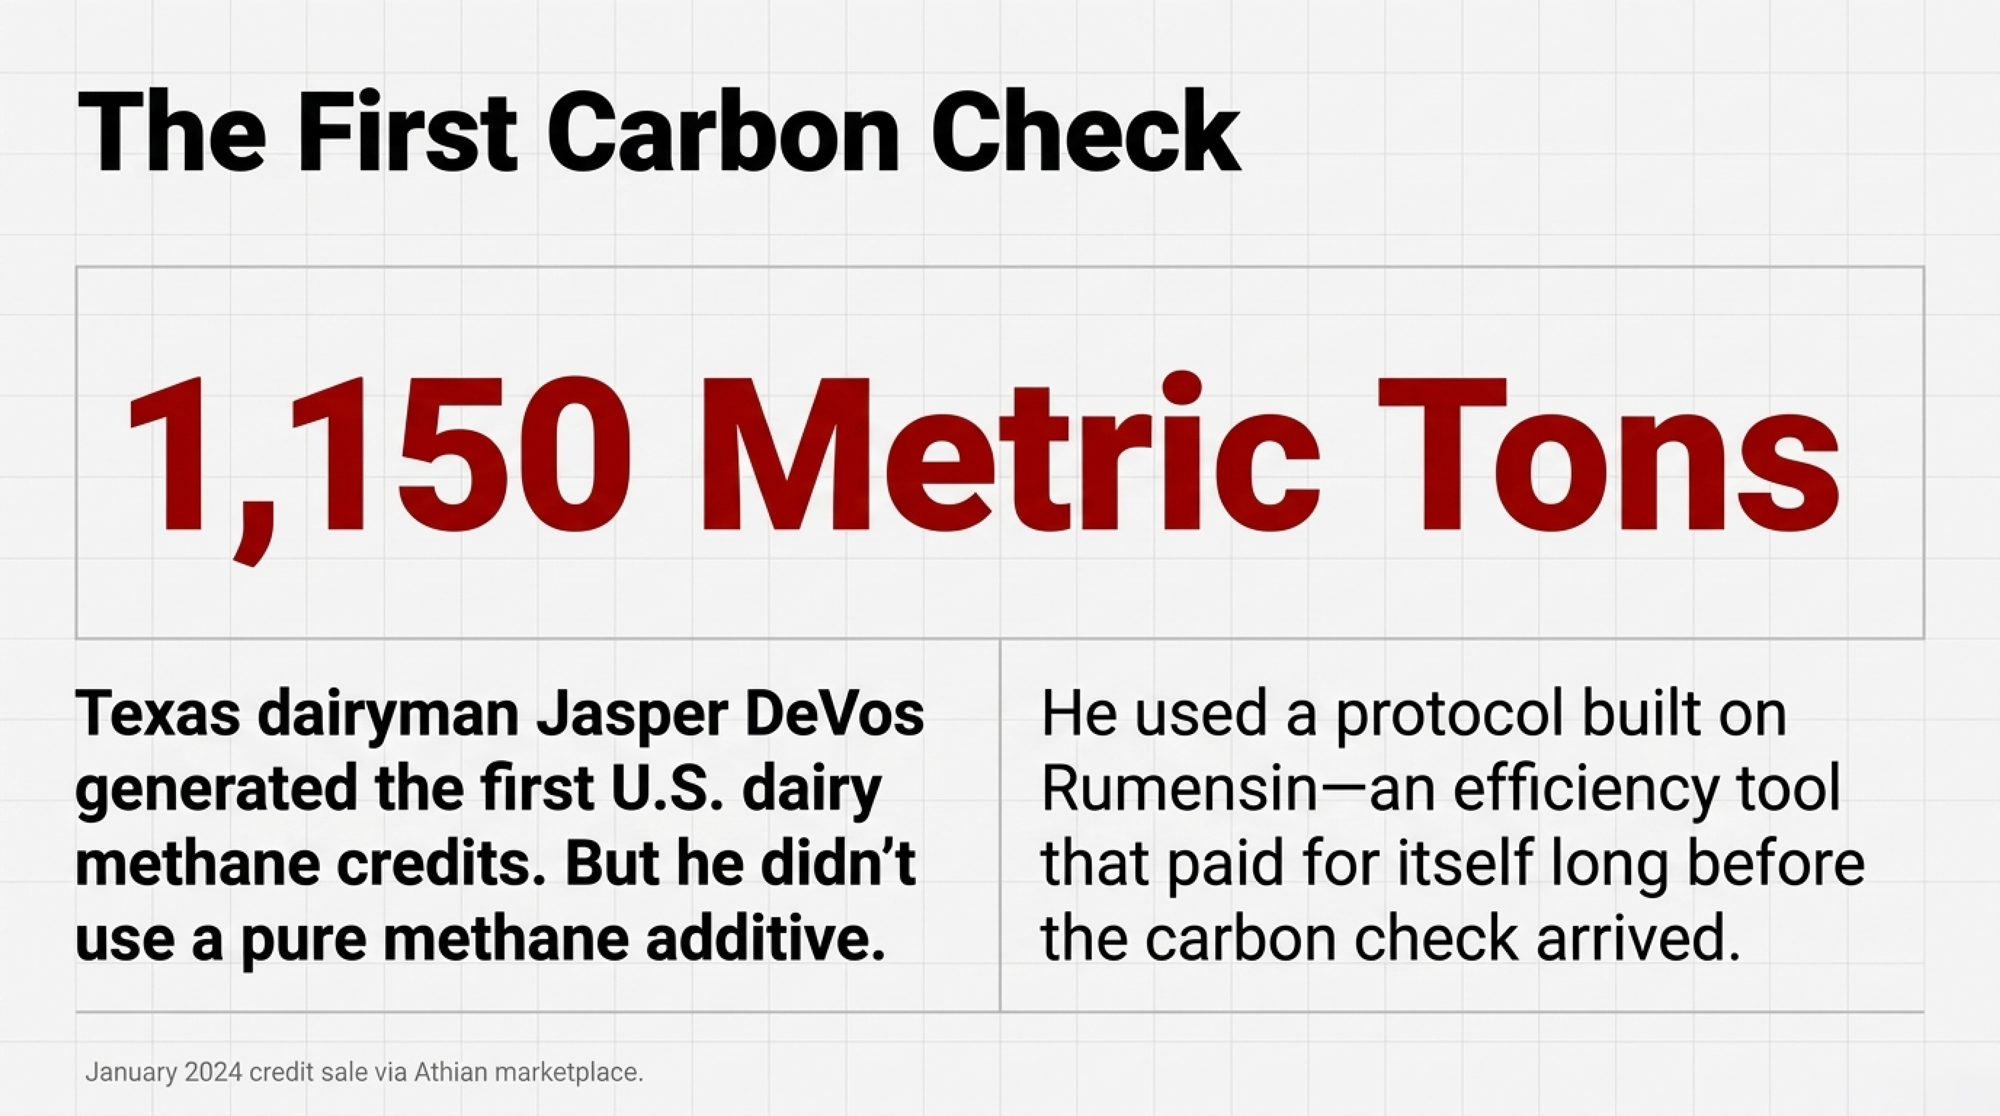
Now set it beside what happened the first time an American dairy farmer got paid for methane. In January 2024, Texas dairyman Jasper DeVos generated nearly 1,150 metric tons of verified carbon credits, the first sale of its kind in the U.S. livestock market, purchased by Dairy Farmers of America through a marketplace called Athian . Here’s the detail most coverage flattened: DeVos used Athian’s first accepted protocol, built on Rumensin, Elanco’s monensin product, FDA-approved to improve milk production efficiency and cut roughly half a metric ton of CO₂e per cow per year, depending on the herd’s animals and management .

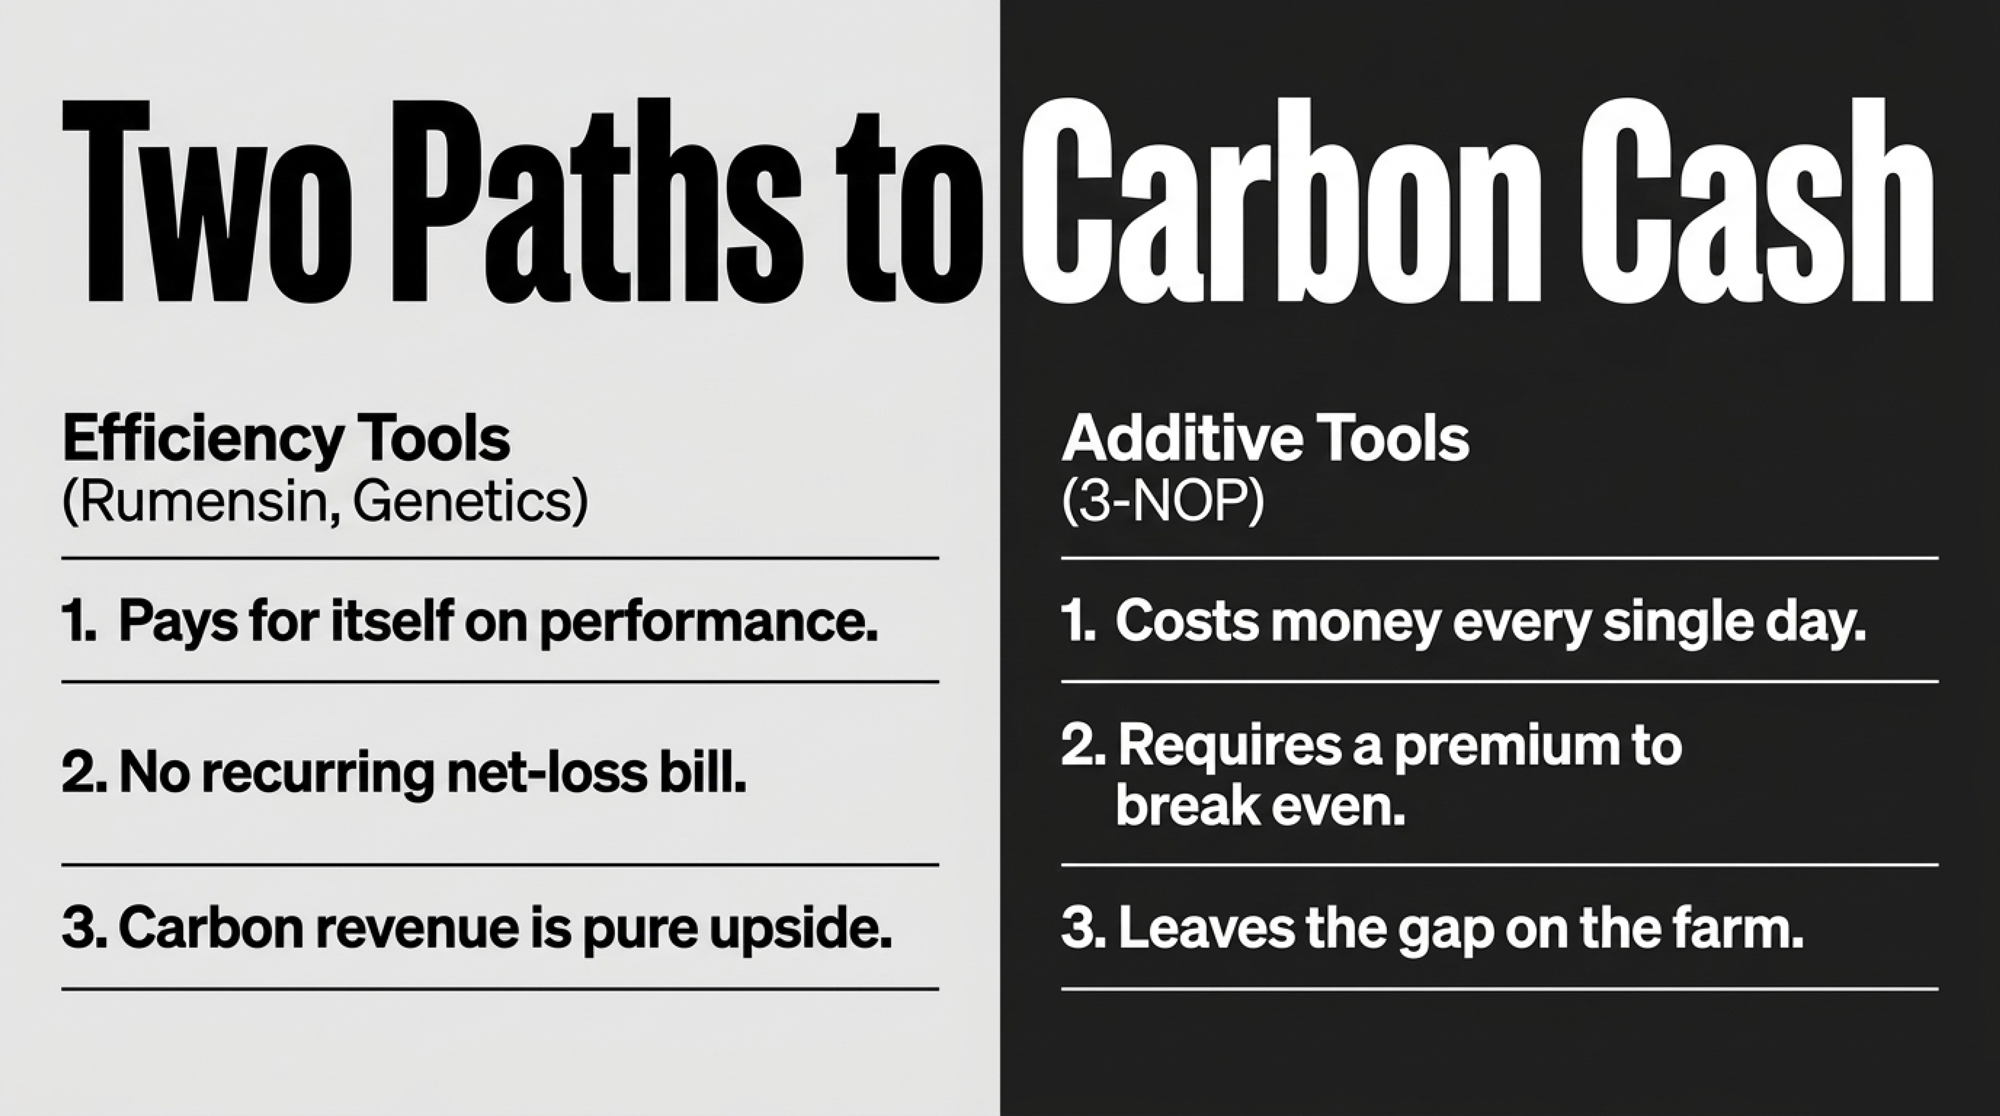
Read those two paragraphs together and you’ve got the hinge of dairy’s next twenty years. The first farmer paid for methane reduction used a tool that improves feed efficiency — it was already earning its keep before the carbon check showed up. The tool the whole industry is now being pitched costs money every day and doesn’t. So the question was never whether you can cut methane. It’s who pays when the cut doesn’t pay for itself, and that’s a contract question headed for your desk.
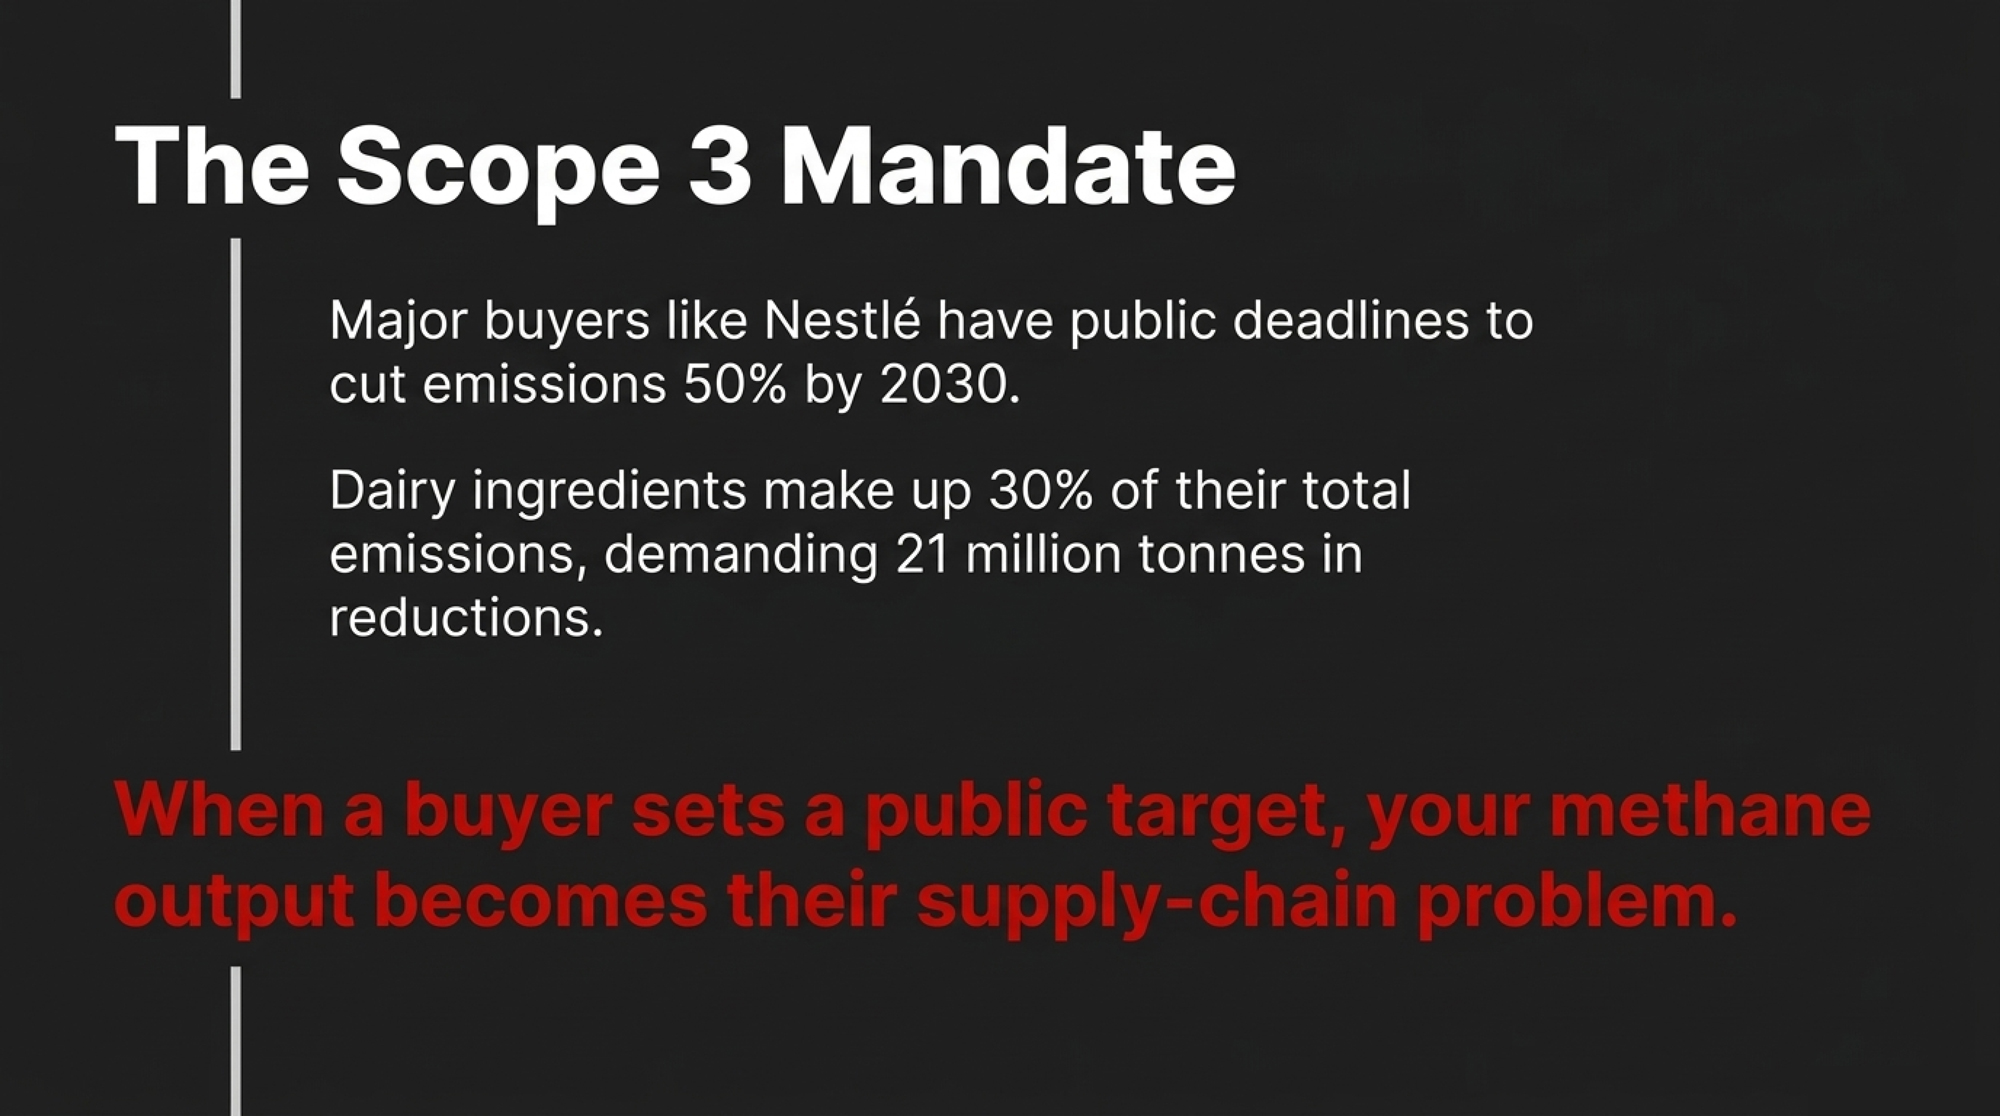
Why now, in 2026? Because the buyers at the other end of your milk have public deadlines. Nestlé, one of the largest dairy purchasers on the planet, has committed to cutting greenhouse gas emissions 50% by 2030 against a 2018 baseline and reaching net zero by 2050, with roughly 95% of its footprint sitting in Scope 3 . Dairy and livestock ingredients are its single largest Scope 3 source at about 30% of total emissions, and its roadmap targets 21 million tonnes of reductions from that category by 2030 . When a buyer that size sets a public target that depends on farm-level methane cuts, the cost of achieving those cuts becomes a supply-chain question. Producers are part of that chain.

The win nobody outside the barn talks about
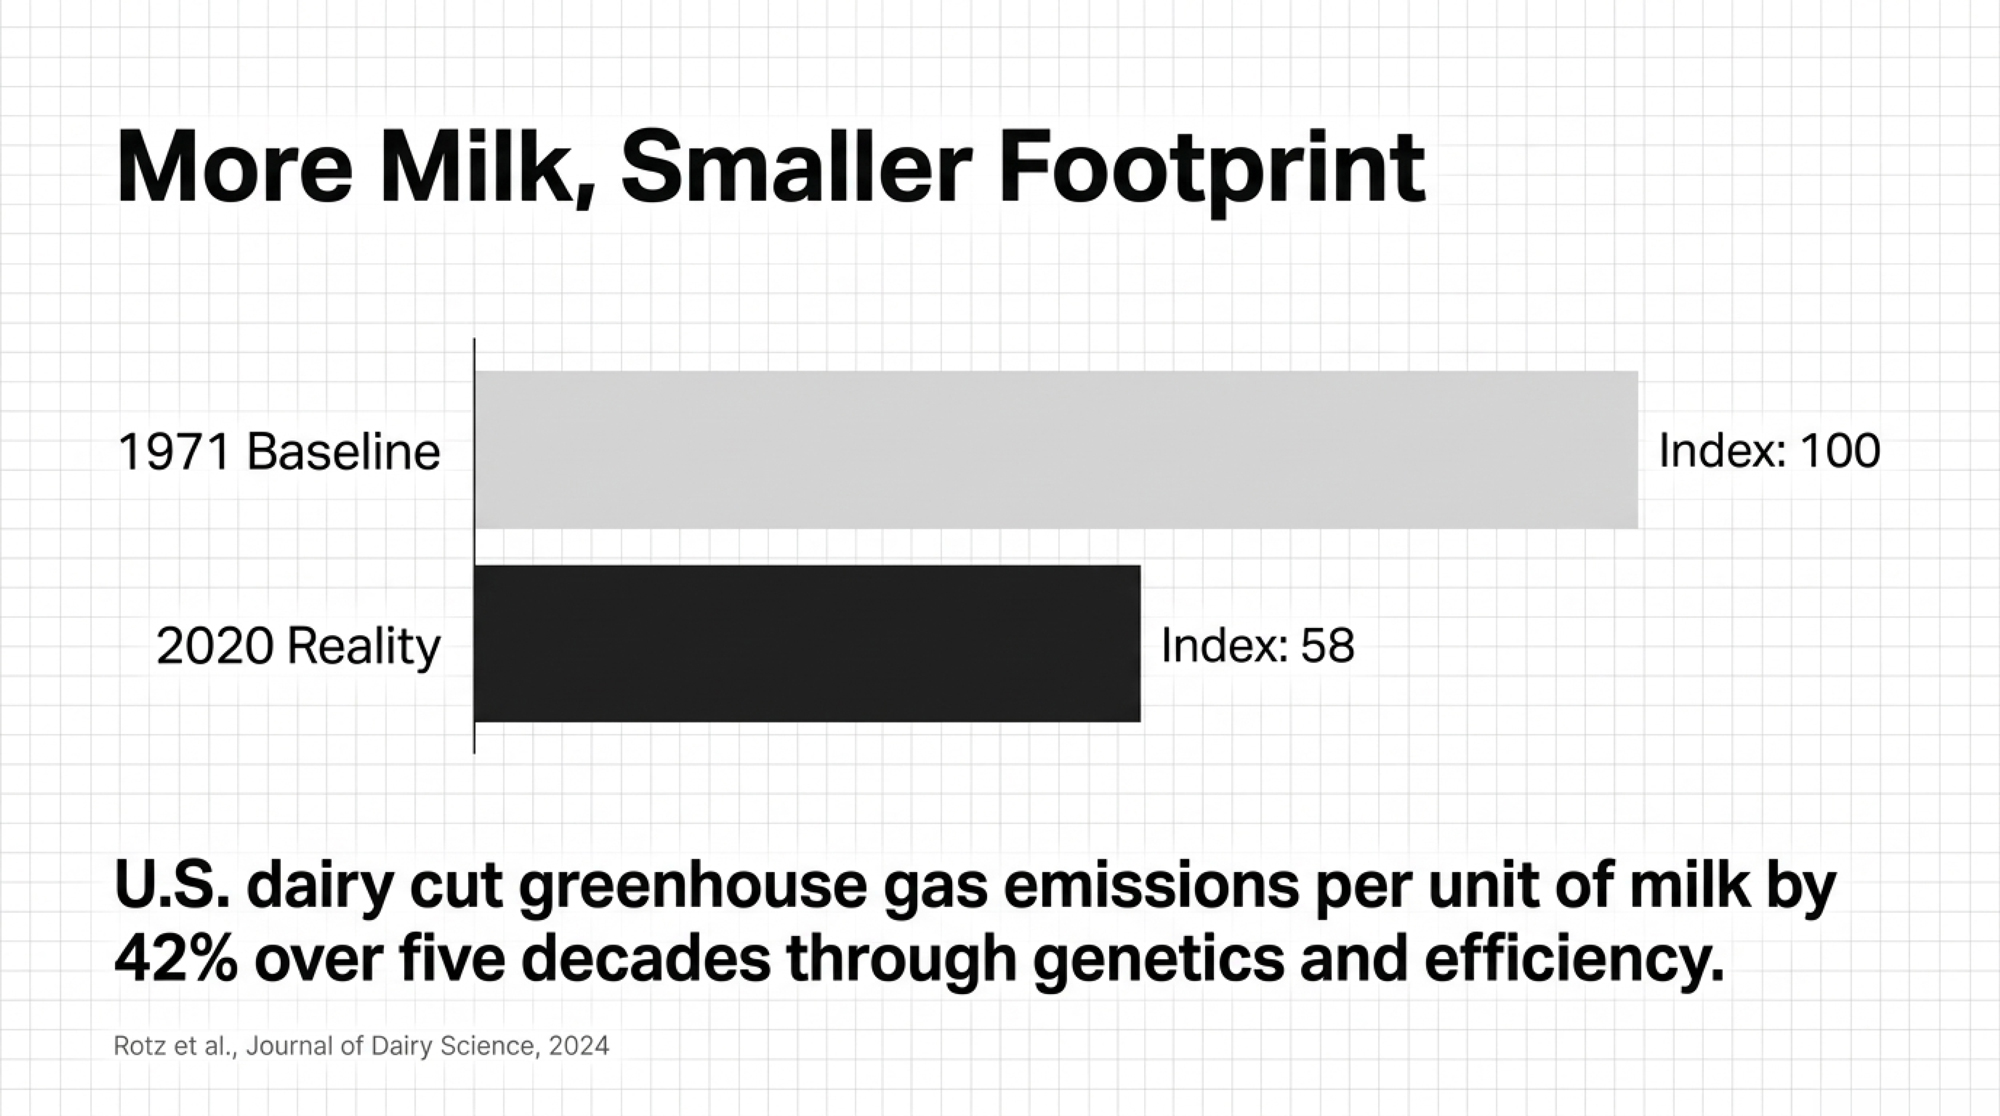
Here’s the part that should make you stand up straighter. Between 1971 and 2020, U.S. dairy farms cut greenhouse gas emissions per unit of milk by 42% while milking about 20% fewer cows and producing roughly twice the milk. That isn’t a marketing line. It’s peer-reviewed work from Rotz and colleagues in the Journal of Dairy Science, 2024 .

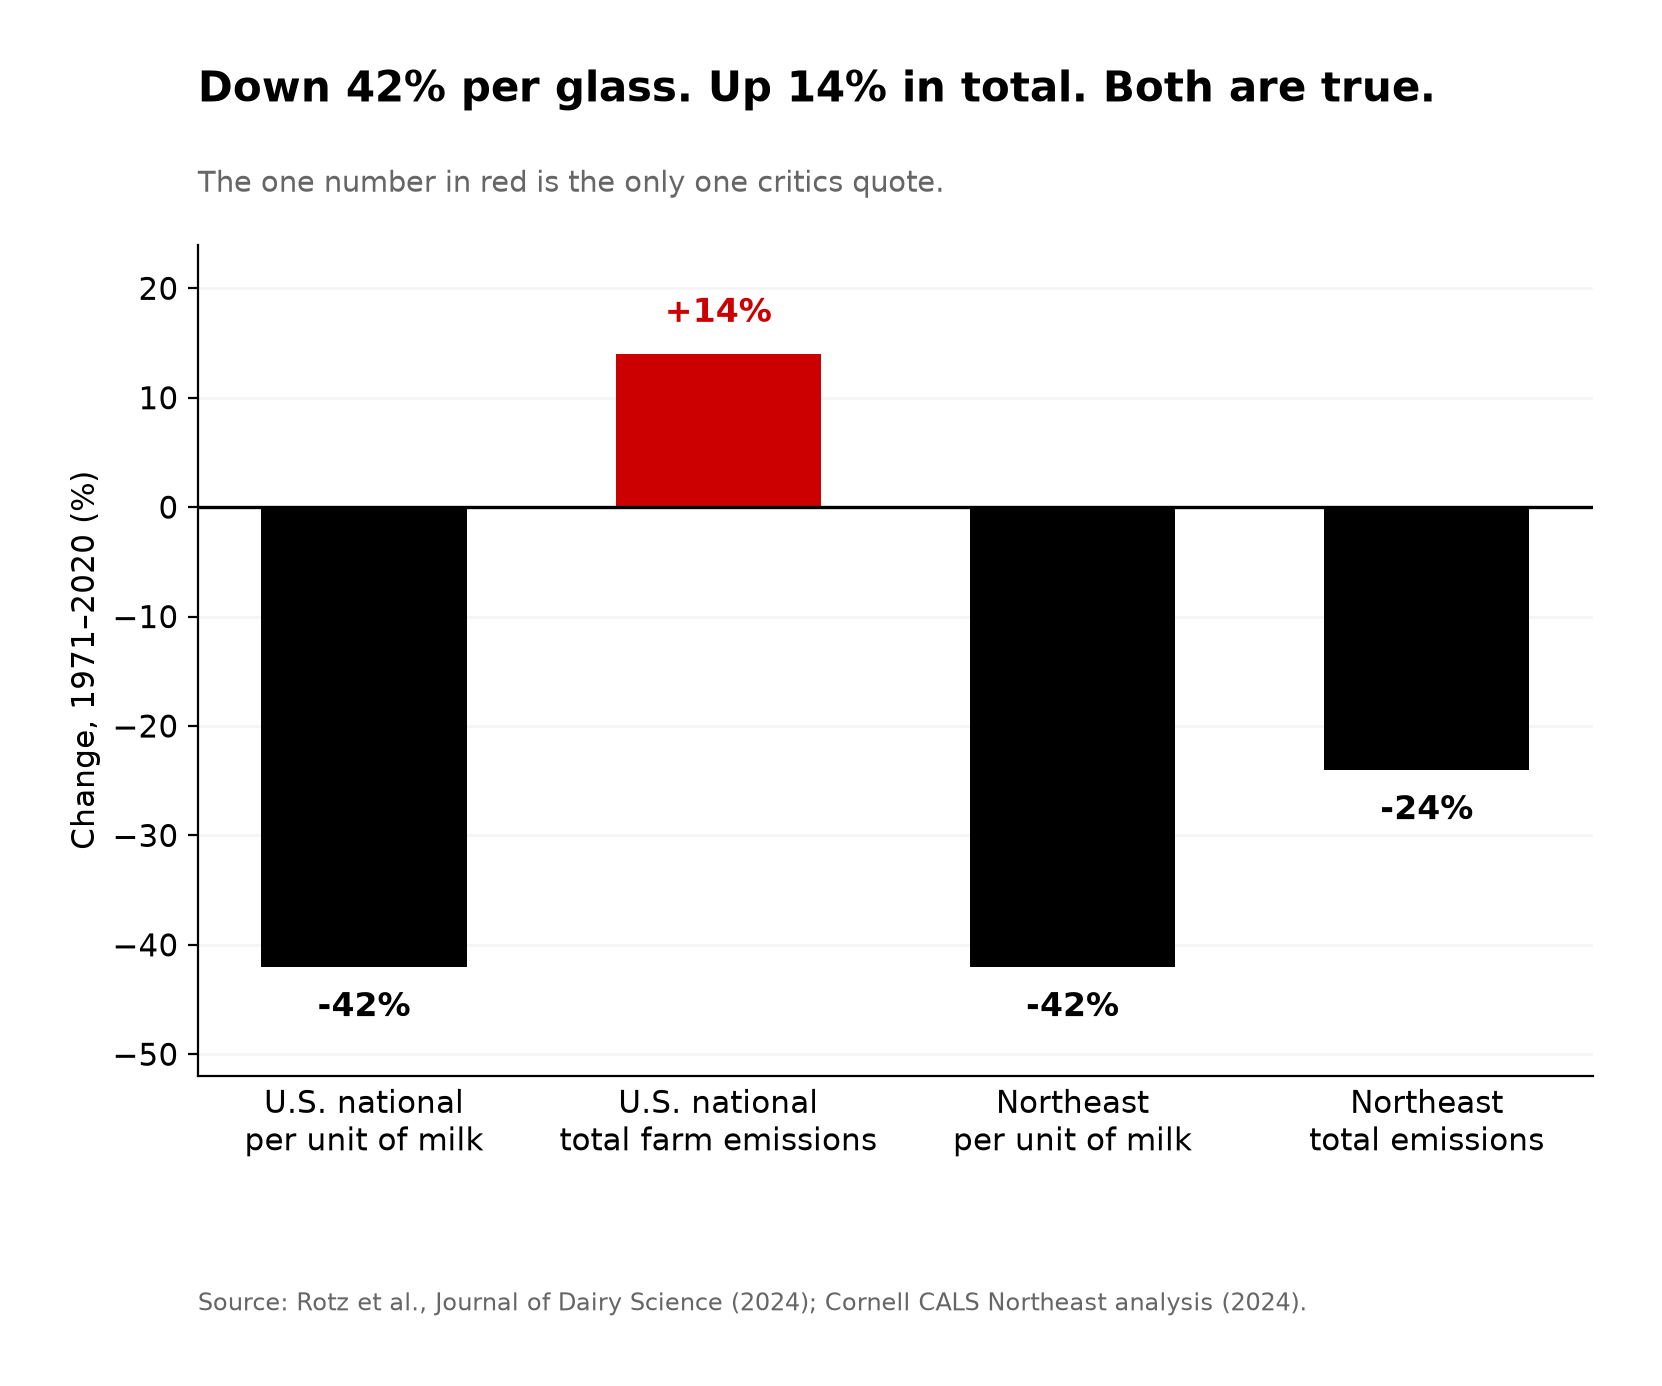
The rest of that study holds up just as well: fossil energy use per unit of milk down 54%, water-use intensity down 28%, and modeled nitrogen and phosphorus runoff per unit of milk down between 27% and 51%. Cornell’s Northeast analysis lands in the same place, with milk carbon intensity down 42% across the same span and absolute emissions in that region down 24% .

So why does your kid come home from school saying cows are bad for the planet? Because the public conversation never got the memo. Two research teams, one national and one regional, landed within a point of each other on intensity.
Why “per glass” and “in total” are both true

This is the line that won’t fit on a bumper sticker. Total emissions from all U.S. dairy farms still rose about 14% across those five decades, because total production climbed and a good share of it moved west into dry regions that lean hard on irrigation. Per glass, way down. In total, up. Both real.

Why does that matter to you? Because a critic reaches for the 14% and a checkoff ad reaches for the 42%, and if you can’t hold both in one breath you sound like you’re hiding something. You’re not. The footprint of each glass fell while the country drank more of it, which is productivity, not a cover-up. The Northeast figure is your best friend in that argument: in that region, absolute emissions came down 24% while intensity fell 42%. Regional stories differ, and saying so out loud is what makes you credible.

What drove the per-glass gains wasn’t a trick, and it wasn’t hormones. USDA’s Economic Research Service reported in February 2026 that the share of milk sales from farms using bovine somatotropin fell from 35% in 2000 to 2% by 2021 . The progress came from genetics, nutrition, reproduction, and management. More milk out of every cow, every acre, every gallon of diesel, and it paid for itself on the way. That’s exactly what DeVos’s credit was built on: Rumensin improves production efficiency, and the methane reduction rode along with it. The old deal, with a carbon check stapled on. The next round breaks it.
What does feeding 3-NOP actually cost you?

The science isn’t the problem. A meta-analysis in the Journal of Dairy Science found 3-NOP reduced methane production, yield, and intensity by 30.9% to 32.7% at an average dose of 70.5 mg/kg of dry matter . Van Gastelen and colleagues followed Holstein-Friesians over a full lactation and reported 21% lower daily methane, 20% lower methane yield, and 27% lower methane intensity, with a positive effect on production characteristics — Journal of Dairy Science, volume 107, 2024. It works.

The economics are the problem, and two different numbers get confused here. Bovaer’s price has been reported in trade coverage at roughly $0.30–$0.40 per cow per day, or about $93–$105 per cow per year on a lactating-cow basis . Separately, the 2025 JDS analysis found a net income-over-feed-cost decline of about $0.35 per cow per day, driven substantially by reduced feed intake and milk yield in the trials modeled . Similar-looking figures, different metrics. The second one matters because it’s what lands on your bottom line after the production response.

Read that twice before you sign anything. You’re not simply buying a feed additive — you’re absorbing a modeled production effect. Trial results vary, and some studies report no significant yield penalty, which is precisely why you run the number against your own herd instead of against a brochure.

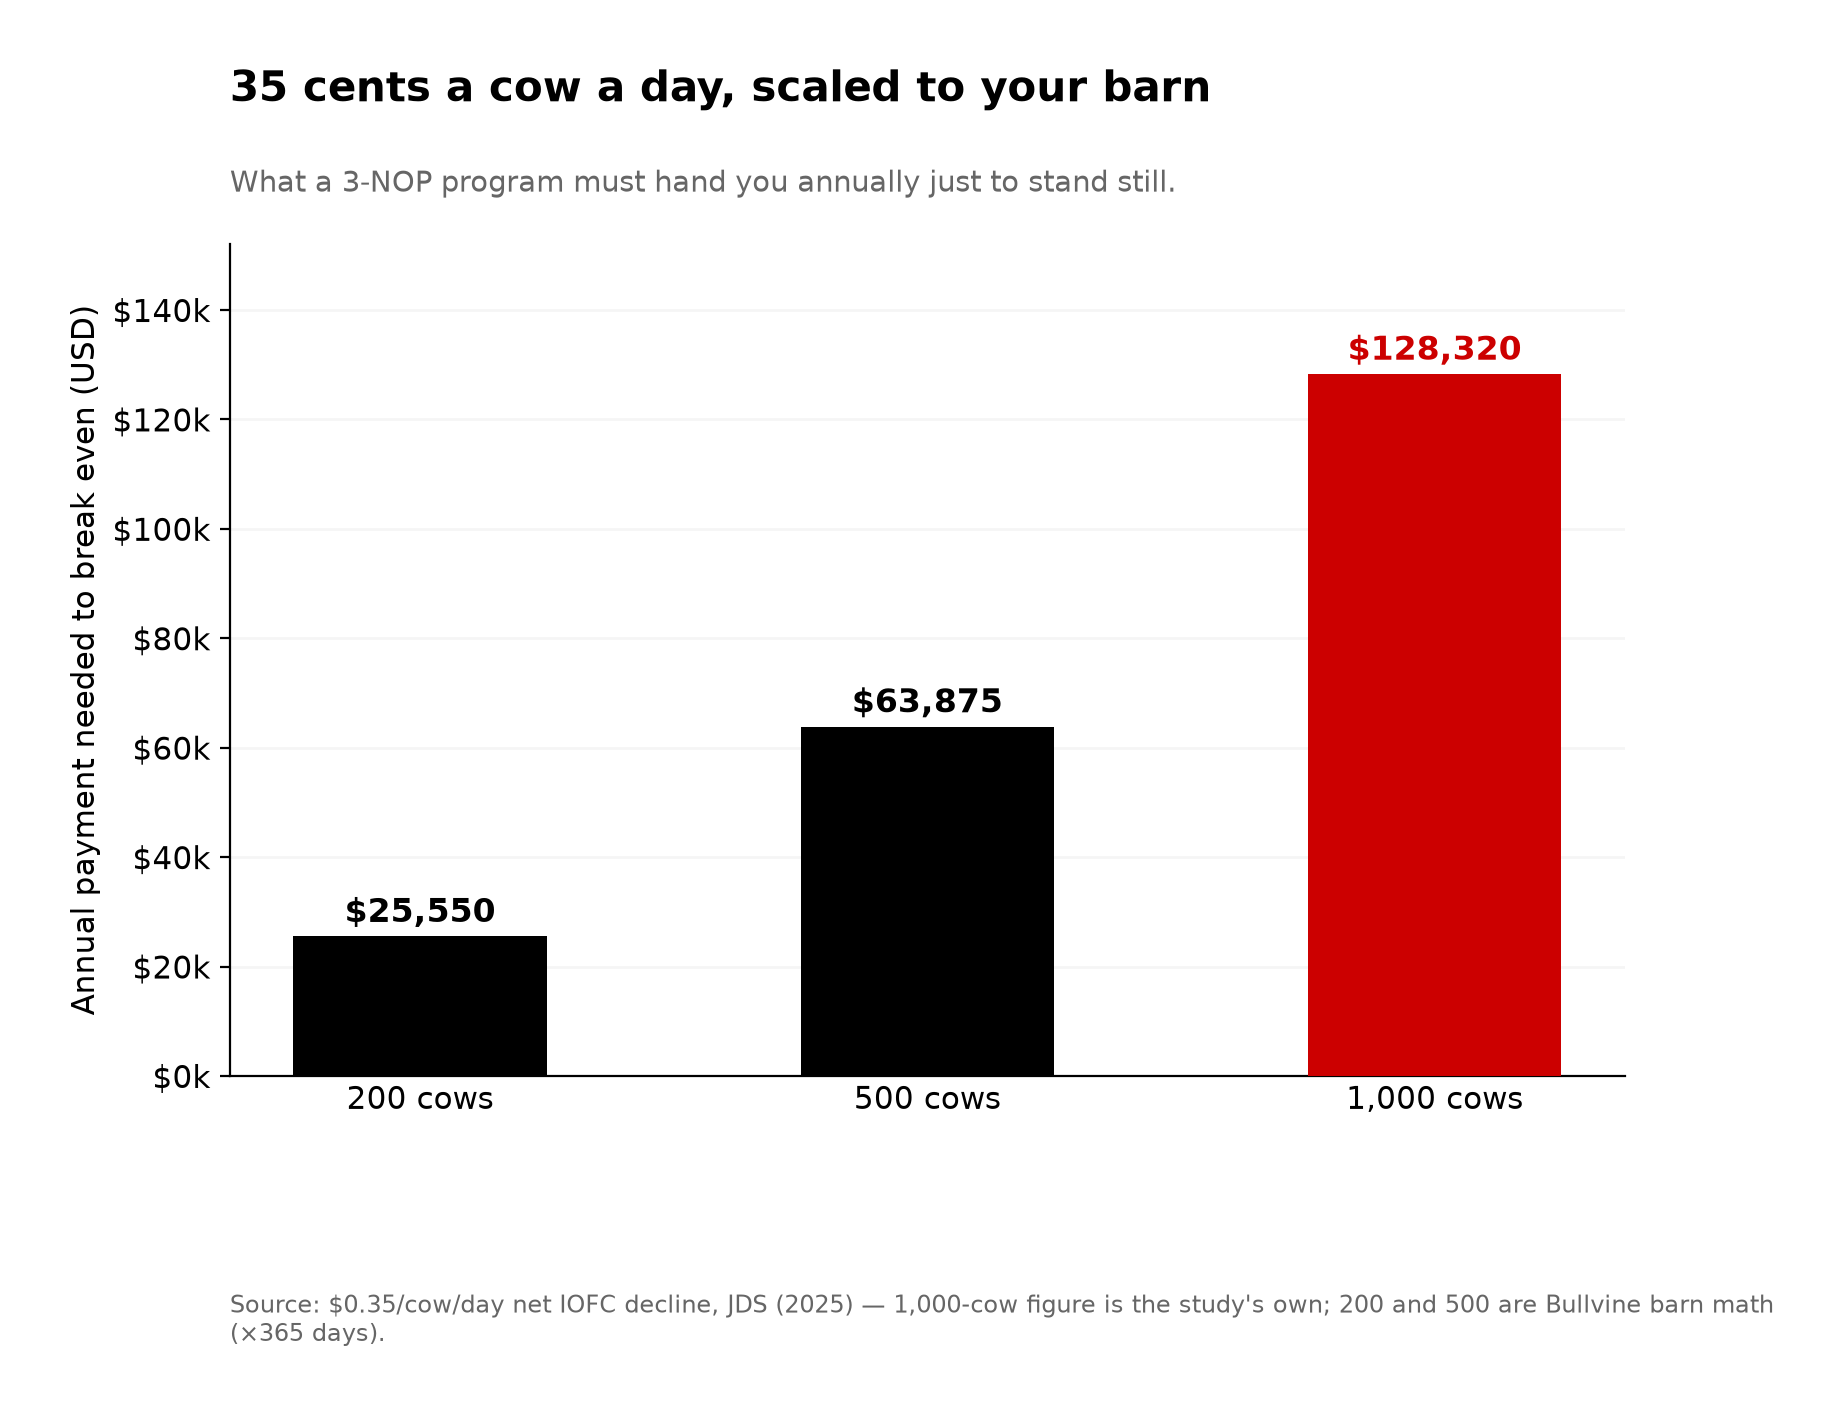
So run it. At the published $0.35 per cow per day net decline, here’s what your operation needs handed to it annually to stand still, applying that figure across herd scale:
Herd sizeBreak-even need at $0.35/cow/day
200 cows~$25,550/yr
500 cows~$63,875/yr
1,000 cows~$128,320/yr

Table note: the 1,000-cow figure is the JDS-modeled annual shortfall, the study’s own number. The 200- and 500-cow rows are Bullvine’s barn math, scaling the published $0.35/cow/day across 365 days, giving $25,550 and $63,875. A straight-line 1,000-cow calculation returns $127,750, fractionally under the study’s $128,320; that difference is in the model, not a typo.

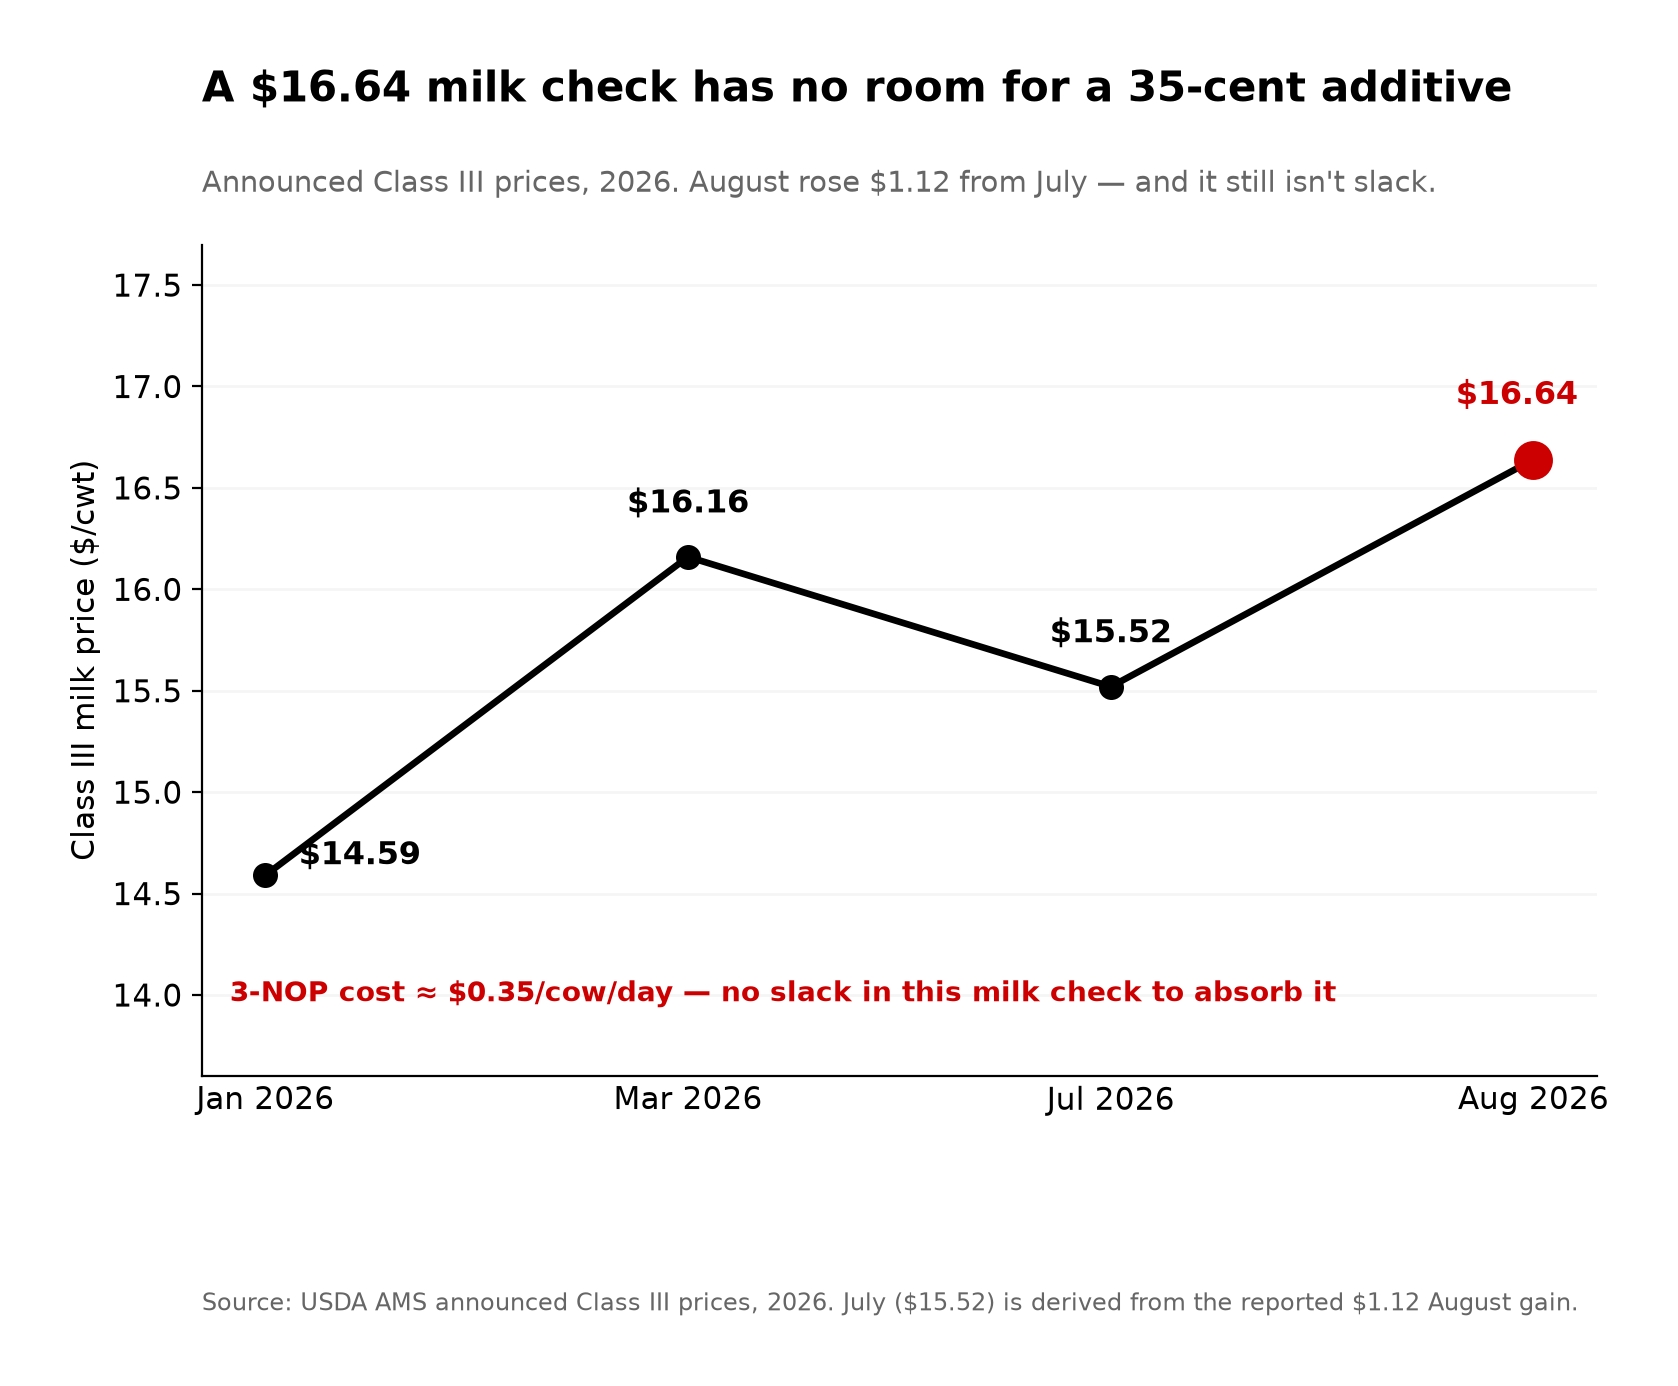
That money comes from a credit, a premium, or a buyer’s check. It isn’t coming from more milk in the tank. USDA AMS put the announced August 2026 Class III price at $16.64/cwt, up $1.12 from July , and Class III opened this year at $14.59 in January before working up through $16.16 in March . There’s no slack in that milk check to quietly absorb 35 cents a cow a day.
On the premium side, the arithmetic is thinner than the pitch. A $0.12/cwt sustainability premium on a 75-lb cow returns only about $33 per cow per year, and Elanco has publicly projected carbon-market returns around $20 per cow per year on top of that — which against a $93–$105 additive bill still leaves a gap of roughly $40–$73 per cow . We’ve walked that contract math clause by clause in the $73-a-cow gap hiding in your 2027 Bovaer contract.

Line itemPer cow / yearPer 1,000-cow herdSource
Bovaer additive cost−$93 to −$105−$93,000 to −$105,000Trade-reported price, $0.30–$0.40/cow/day
$0.12/cwt sustainability premium (75-lb cow)+$33+$33,000Bullvine barn math
Elanco projected carbon-market return+$20+$20,000Elanco public projection
Net gap left on the farm−$40 to −$73−$40,000 to −$73,000Bullvine calculation
Modeled net IOFC decline (separate metric)−$128−$128,320JDS 2025 economic analysis

Who actually keeps the carbon money?

The money is large. It just mostly isn’t yours.

Start with what a digester costs to build, because the regulator publishes its own arithmetic. CARB sets out the cost formulas it uses for dairy manure digesters in Appendix F of its Short-Lived Climate Pollutant Reduction Strategy, and the ICCT’s 2023 California renewable natural gas outlook applied them: capital expense scaling with herd size, operations and maintenance at 6% of capital, pipeline at $200,000 a mile, biogas upgrading at $8 per MCF, and a $2 million interconnection fee on a single-farm project against $5.5 million on a centralized one, plus $250,000 a truck where the gas has to move by road. theicct

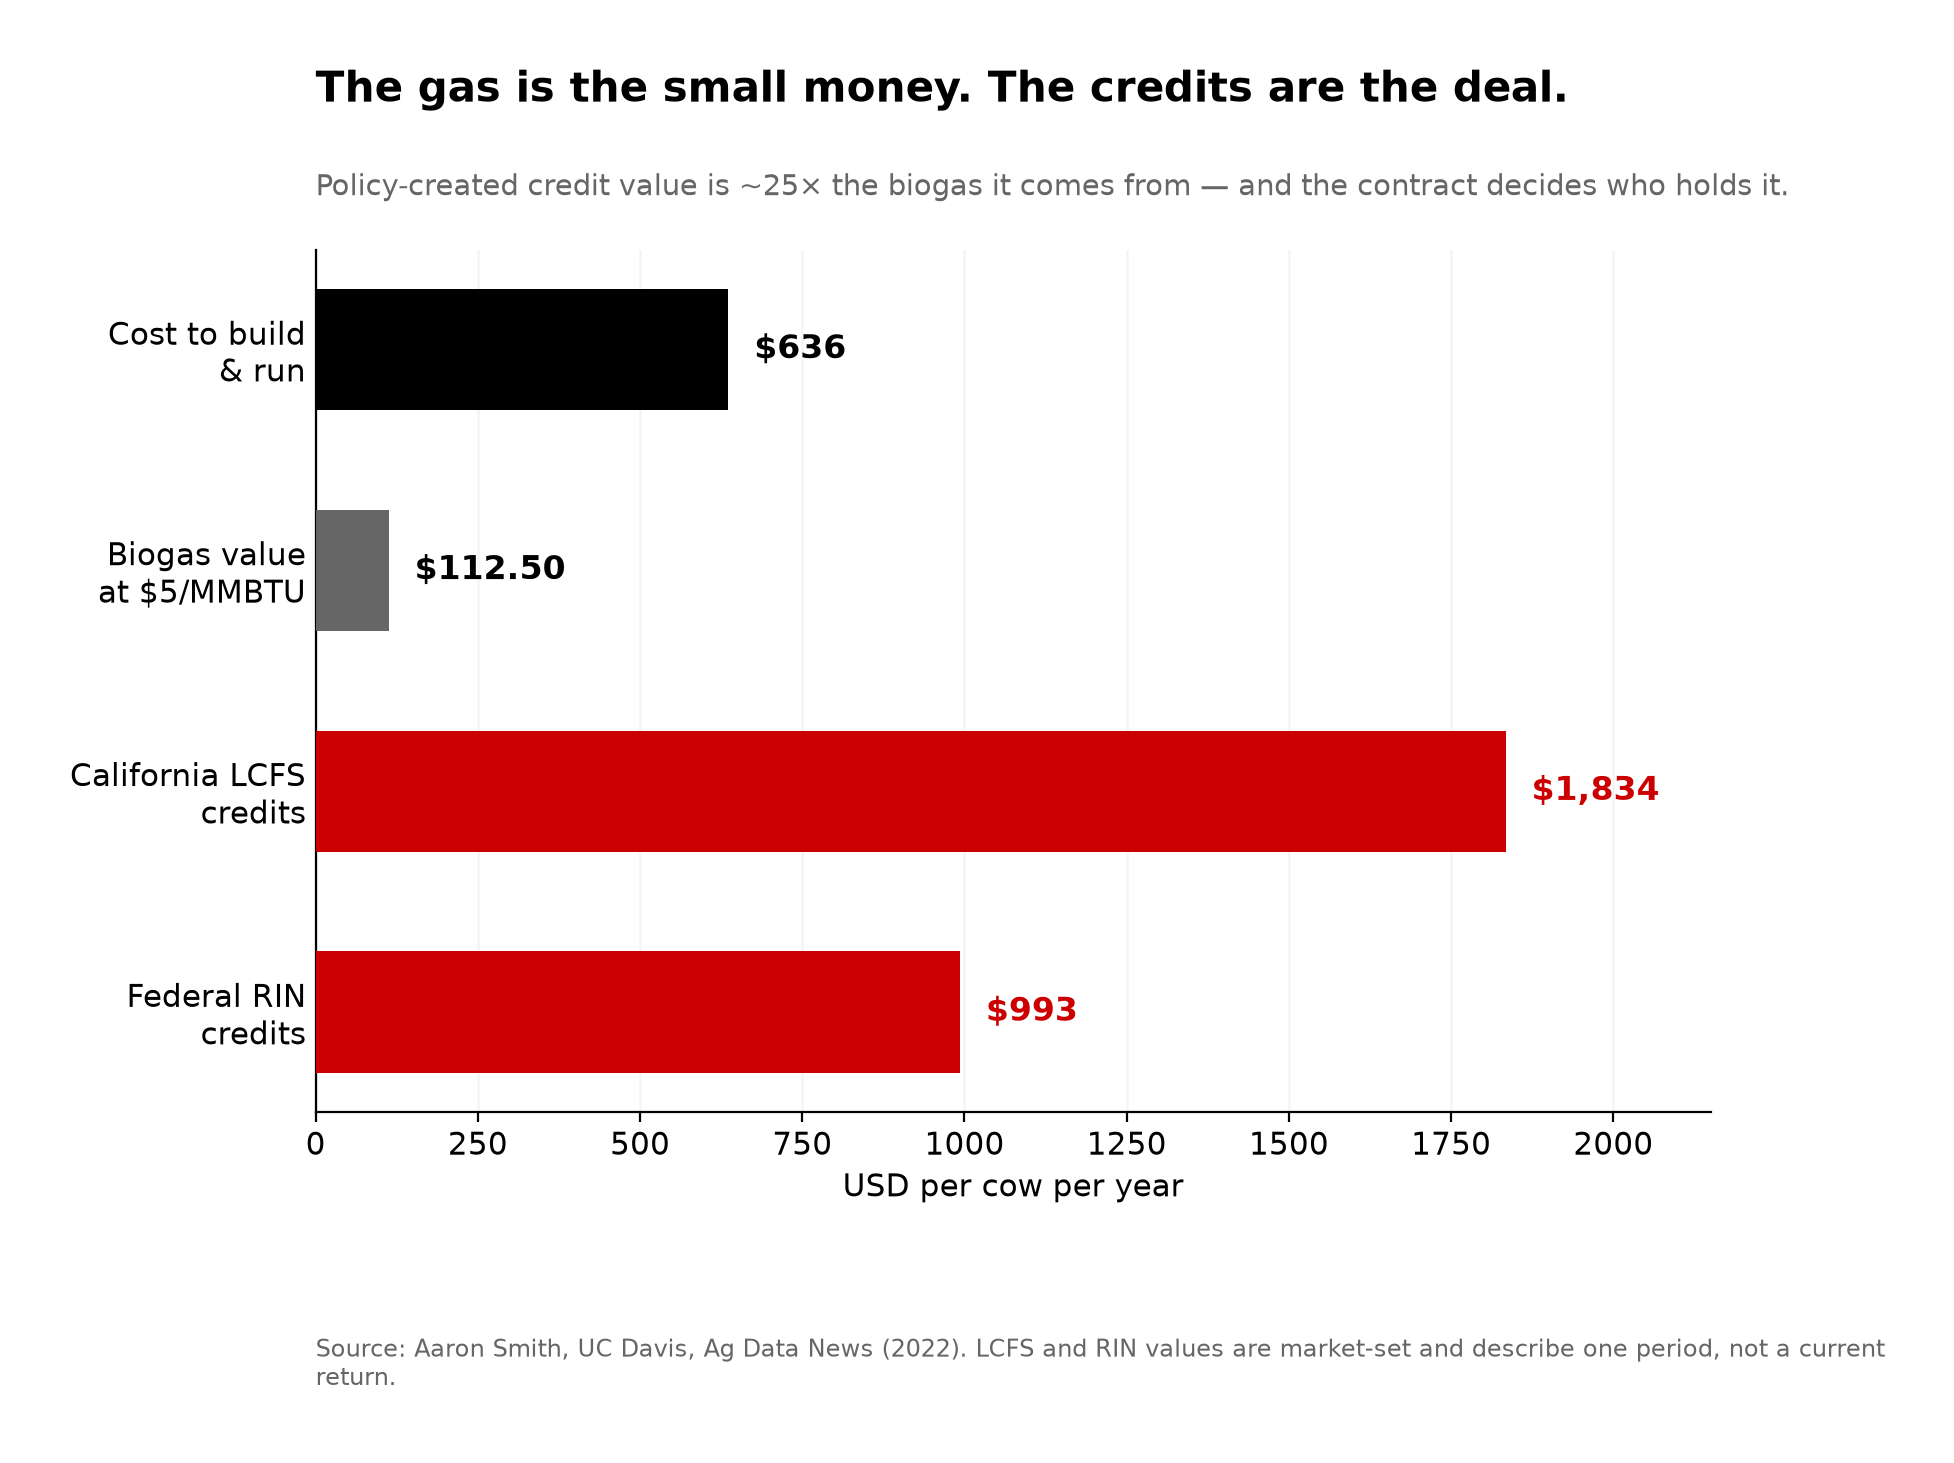
Now the per-cow view. UC Davis agricultural economist Aaron Smith, in a 2022 analysis, put a digester at roughly 22.5 MMBTU of biogas per cow per year at a cost of about $636 per cow, operating cost plus capital amortized over ten years, with the gas worth about $112.50 per cow at $5/MMBTU . On the gas alone, you’d never build it.
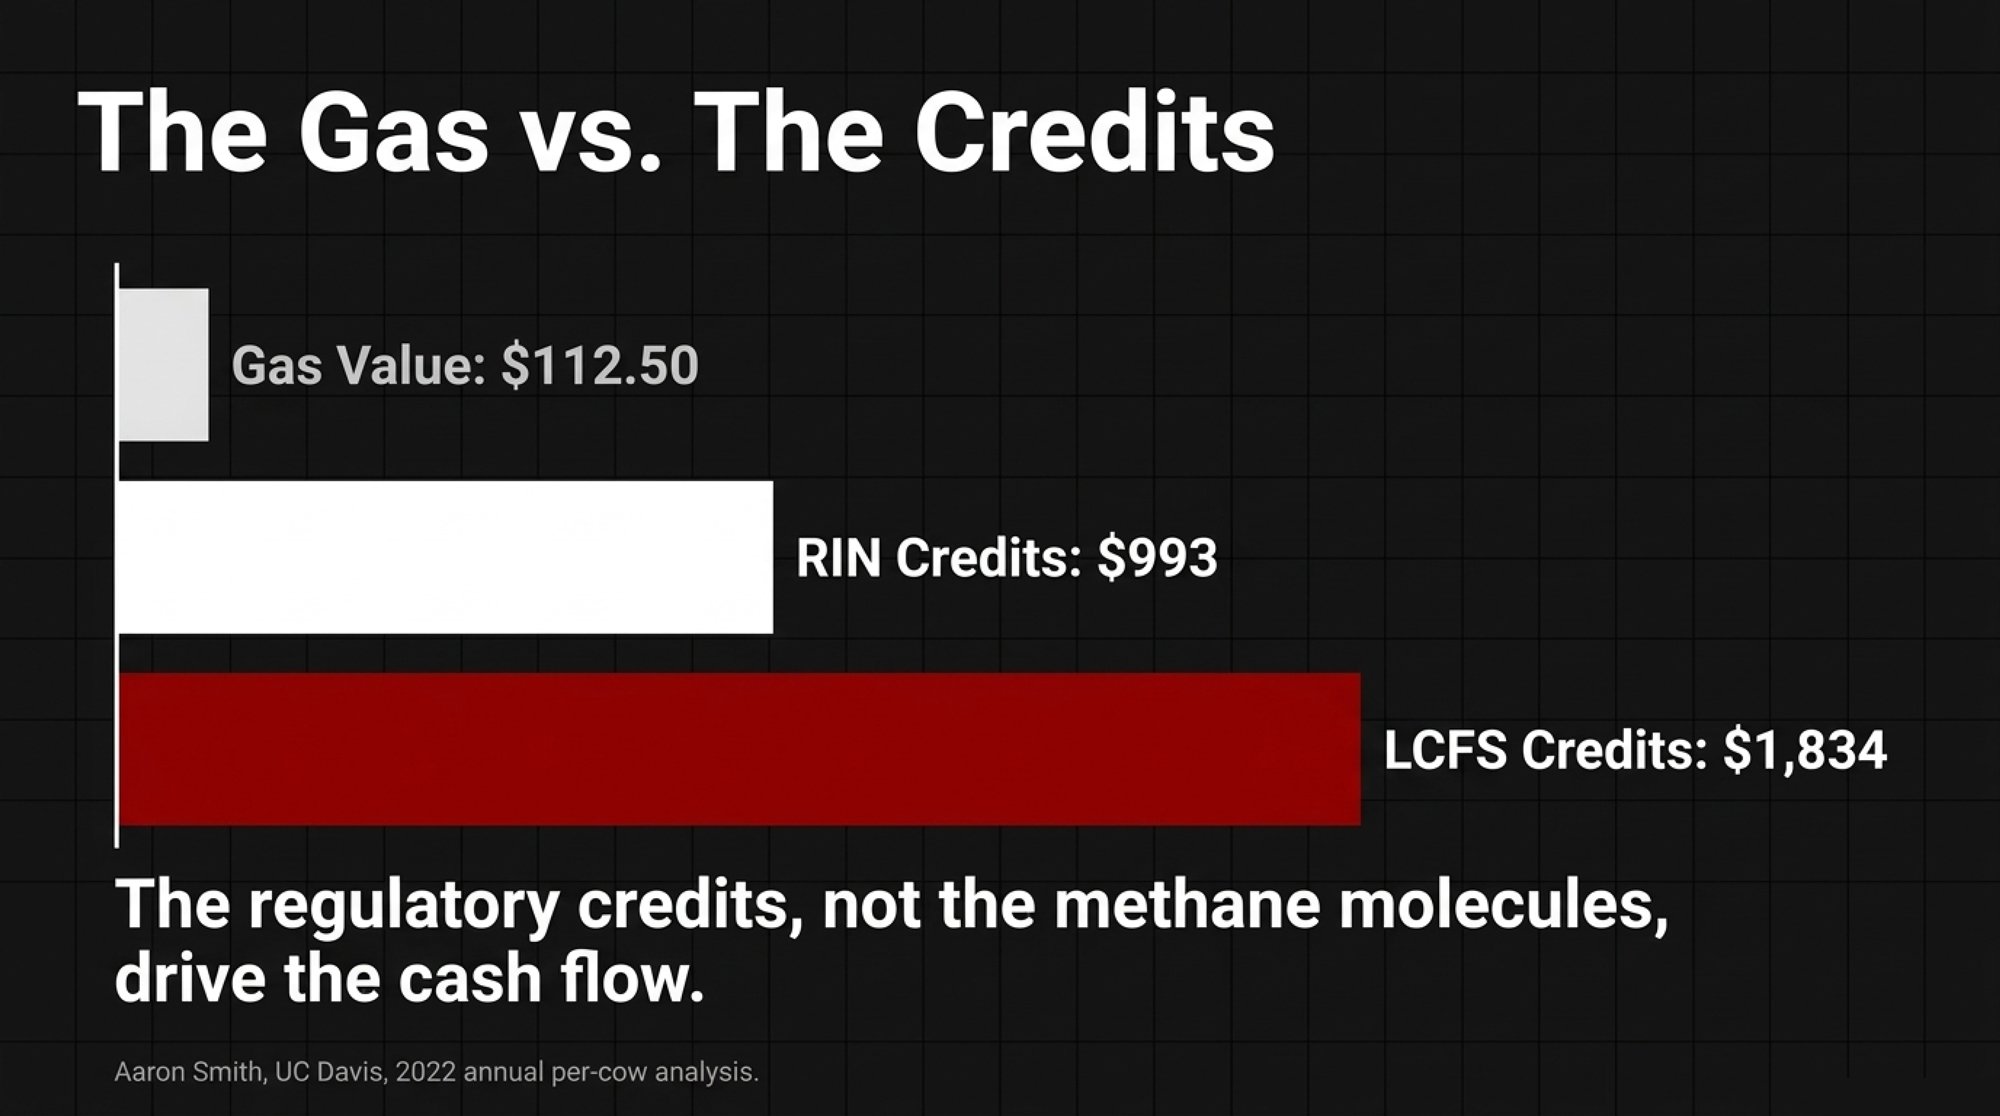
Then come the credits. Smith calculated that the same cow’s biogas earns approximately $1,834 per cow in California Low Carbon Fuel Standard credits and another $993 per cow in federal Renewable Identification Numbers, about $2,827 per cow in policy-created value . That’s more than four times the value of the gas. Don’t read it as a guaranteed margin on a deal you’re offered today: LCFS and RIN credits are market-set instruments, their value moves with program rules and market conditions, and Smith’s figure is a snapshot of one period rather than a fixed return . What doesn’t move is the underlying dynamic — the regulatory credits, not the methane molecules, drive the cash flow. A 2025 Terrain Ag analysis found the fuel is typically the smallest share of the revenue stream, which is the same finding from the lender’s side of the table .
Project scale tells the same story. Writing in October 2024, Smith reported that data provided to CARB put a typical 2023-built digester on a 2,500-cow dairy at $8.6 million to construct, about $1.2 million a year amortized over a decade, and roughly $1.1 million a year to operate, against gas sales of approximately $230,000 at 2023 city-gate prices. Net operating cost before credits: about $870,000 a year, plus another $500,000 if the gas has to be trucked. Over the first ten years he puts the net cost of building and running a digester at $2,730 to $3,380 per ton of methane abated, and notes that California grants can cover up to half of capital costs. agdatanews.substack

None of that credit stream is hypothetical. LCFS credit generation from manure digester projects has grown roughly 1,000% since 2020 and has produced more than a billion dollars’ worth of credits. California has put about $214 million of state money into 131 dairy digester projects in the San Joaquin Valley alone, and CARB’s own August 2024 dairy sector workshop draws its project data from CDFA’s grant records, EPA AgSTAR, and verified LCFS and cap-and-trade filings. sciencedirect

So the decisive question on any digester deal isn’t whether the project pencils. The question is who holds the credits, and the contracts are written on that point. Guidance published for developers in Biomass Magazine in 2022 advises that the agreement should state the developer owns all rights to the environmental credits, tax credits, and similar benefits arising from the project; lenders and offtakers want clean title in the project entity. Compeer Financial’s 2025 producer guidance puts it plainly: understanding the fine print is crucial . DeVos got a check because his tool earned on performance first, and the carbon was upside. Digester operators sit on top of substantial public subsidy value and mostly don’t hold title to it. The difference isn’t the science. It’s the contract. Our earlier breakdown of a larger covered-lagoon project runs in $1,130 per cow, $128 back.

When does a methane tool actually pencil?

The decision rule is simple even when the answer isn’t. A methane tool pencils only when the outside payment reliably clears the break-even gap and stays cleared after the marketplace or developer takes its share.

LeverRecurring cost to youWho keeps the created valueProven payout to a farmer?Time to effect
Rumensin / monensin (efficiency + credits)None — earns on feed efficiencyFarmer held the creditYes — 1,150 t sold, Jan 2024, DFA via AthianImmediate
3-NOP / Bovaer−$0.35/cow/day net IOFC($128,320 per 1,000 cows)Depends entirely on the premium clauseNo banked U.S. dairy credit to dateImmediate, ~31% methane cut
Manure digester$636/cow/year to build and runDeveloper-side templates assign LCFS, RINs and tax credits to the project entityGas only: ~$112.50/cow vs ~$2,827/cow in creditsMulti-year build, 10-year amortisation
Methane Efficiency genetics (Lactanet)$0 on DHI-enrolled femalesFarmer — it’s in the herdNo credit protocol yet; 23% heritability, >70% reliability5–7 years to herd-level expression
  • For 3-NOP: you need a locked premium above $0.35 per cow per day net, roughly $25,550 a year on 200 cows and $128,320 on 1,000. A $0.12/cwt premium returning $33 a cow doesn’t reach it. A handshake or a one-year pilot price is not a floor.
  • For a digester: ask who holds the LCFS credits and the RINs before you ask anything else, and ask it again about any state grant that covered construction. That clause decides whether the project is your asset or your neighbor’s.
  • For an efficiency tool that also earns credits: a different question entirely. If the product pays its own way on performance, the Rumensin case, carbon revenue is upside rather than justification.
  • For genetics: the one lever with no recurring bill. Lactanet’s Methane Efficiency trait runs 23% heritability with better than 70% reliability on genotyped young animals and costs nothing extra on DHI-enrolled females, though herd-level expression takes five to seven years.

What can you do before the contract hits your desk?

Plenty, and most of it is free. The highest-value move isn’t financial: get the story straight before a reporter, a neighbor, or your kid’s teacher gets it wrong for you. A 2025 Dairy MAX consumer survey found that consumers see farmers as the most trusted source of information on dairy sustainability . Use that standing before somebody else fills the silence.

The second move is to treat every carbon pitch as a contract problem, not a science problem. The science on 3-NOP is settled enough at roughly 31% methane reduction. The open question is who keeps the value when it works. For the genetics side of that answer, see why methane-efficiency breeding beats Bovaer’s $73 gap.
The Producer Playbook: What to Do Before Signing

  • Run 35 cents a cow a day against any additive offer before you sign — $25,550 a year on 200 cows, $128,320 on 1,000. If the premium doesn’t clear that with margin, the answer is no.
  • Check what the premium actually pays. A $0.12/cwt sustainability premium returns about $33 a cow a year, roughly a third of a $93–$105 additive bill. That’s why the gap keeps landing on the farm.
  • On a digester, find the credits clause before you read anything else. The regulatory credits, not the gas, carry the cash flow, and developer-side contract templates assign them to the project entity.
  • Ask what the grant paid for. California grants can cover up to half of digester capital cost, and who took that money shapes who owns the output.
  • Copy the model that actually worked. The only U.S. dairy methane credit ever banked came off Elanco’s Rumensin protocol, not Bovaer: a tool already paying for itself on feed efficiency, with carbon as upside.

DeVos got a check because his tool worked twice, once on efficiency and once on carbon. Most farms won’t get that deal. So where does your operation sit right now: positioned to get paid for the methane you’re being asked to cut, or about to absorb the cost alone?

That splits hard by herd size and region. We’re building the full cost-per-cow model — 3-NOP, digesters, and carbon programs by herd size and region — in next week’s Bullvine Weekly.
Methodology Note: Long-term greenhouse-gas, energy, water, and nutrient figures come from Rotz et al., Journal of Dairy Science (2024), a national U.S. life-cycle assessment comparing 1971 with 2020. These are national averages and will not match every region or operation. Northeast figures are from Cornell CALS reporting on the same body of work. The 3-NOP economics ($0.35/cow/day income-over-feed-cost decline; $128,320/year on a modeled 1,000-cow herd) are from a 2025 JDS economic analysis in which the decline reflected reduced feed intake and milk yield in the trials modeled; individual herd results will differ with feed cost, component values, and dose, and the published figure is a single modeled central value rather than a range. Bovaer’s reported price of $0.30–$0.40/cow/day and $93–$105/cow/year is a separate figure from that net IOFC decline and should not be read as the same number. The 200- and 500-cow rows are Bullvine’s barn math scaling the published per-cow figure across 365 days. Methane-reduction efficacy of 30.9–32.7% at 70.5 mg/kg dry matter is from a JDS meta-analysis; the full-lactation figures of 21%, 20%, and 27% are van Gastelen et al., JDS volume 107 (2024). Jasper DeVos’s January 2024 credit sale used Athian’s first accepted protocol, based on Elanco’s Rumensin (monensin); Bovaer/3-NOP is a DSM-Firmenich product and was not the tool used in that sale. Digester cost formulas are CARB’s own, published in Appendix F of its Short-Lived Climate Pollutant Reduction Strategy and applied in the ICCT’s May 2023 California renewable natural gas outlook. Digester per-cow figures — $636 cost, $112.50 gas value at $5/MMBTU, $1,834 LCFS, and $993 RIN credit value — are Aaron Smith’s 2022 calculations at UC Davis; LCFS and RIN credit values are market-set and move with program rules and market conditions, so those per-cow figures describe one period rather than a current return. Project-scale figures and the $2,730–$3,380 per ton abated range are Smith’s October 2024 analysis, published at the Energy Institute at Haas and Ag Data News, drawing on data provided to the California Air Resources Board; Bullvine has not obtained individual project submissions. LCFS credit growth and cumulative credit value for manure digester projects are from peer-reviewed analysis of CARB program data; the $214 million across 131 San Joaquin Valley projects is CDFA data as cited in peer-reviewed work. CARB’s August 2024 dairy sector workshop presentation identifies its project data sources as CDFA’s Dairy Digester Research and Development Program records, EPA AgSTAR, and verified LCFS and cap-and-trade filings. Contract-structure findings are from 2022 Biomass Magazine developer guidance, a 2025 Terrain Ag/American AgCredit analysis, and Compeer Financial’s 2025 producer guidance. Class III at $16.64/cwt is the USDA AMS announced August 2026 price. Bovine somatotropin figures are from USDA Economic Research Service, February 2026. Methane Efficiency heritability and reliability figures are from Lactanet. Nestlé’s targets are from its published Net Zero Roadmap. Currency pass completed September 14, 2026. Dollar figures are USD. We welcome producer numbers and corrections.

Learn More

The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
NewsSubscribe
First
Last
Consent

When Fear Takes the Wheel: How Consumer Backlash To Arla Foods Bovaer Trail Are Steering the Future of UK Dairy

Uncover the Bovaer debate in UK dairy. How do consumer worries influence dairy’s future? Get expert insights and opinions.

In a rapidly evolving world where sustainability is more crucial than ever, the dairy industry in the UK finds itself at a crossroads, caught between innovation’s potential and the formidable power of consumer perception as Arla Foods UK steps into the spotlight with its ambitious trial of the methane-reducing feed additive Bovaer, a wave of controversy has erupted, challenging the very fabric of modern dairy farming practices. This initiative—seen by some as a pioneering stride towards a greener future—sparks a heated debate fueled by public skepticism and widespread misinformation. What does this consumer backlash mean for the future of dairy farming, and how might it dictate the path of sustainable agriculture?

Harnessing Innovation: The Dairy Sector’s Battle Against Methane

Methane emissions, a significant contributor to agricultural greenhouse gases, present a pressing challenge within the dairy industry. As the global community grapples with the urgent issue of climate change, the dairy sector stands at a critical juncture. Balancing growth and sustainability, the industry strives to reduce its methane footprint significantly. The urgency of this task is underscored by methane’s heat-trapping capability, which is 80 times greater than carbon dioxide over a two-decade period. 

Introducing Bovaer, a revolutionary feed additive developed by DSM-Firmenich with the potential to curb methane emissions. With just a quarter teaspoon per cow per day, Bovaer could reduce enteric methane emissions from dairy cattle by a remarkable 30%. For beef cattle, the reduction could reach up to 45%. This innovation represents a significant step towards sustainability, offering a robust response to the pressing demands of the current climate crisis and instilling hope for a greener future in the dairy industry. 

The global push to address methane emissions extends beyond the dairy industry, encompassing international initiatives like the Global Methane Pledge. This pledge aims to slash methane emissions by 30% by 2030. Innovative technologies like Bovaer play a pivotal role in this collective effort, providing immediate emissions reductions and paving the way for future advancements. By participating in the Bovaer trial, the dairy industry contributes to a global movement towards a more sustainable future. 

As countries worldwide commit to ambitious climate targets, adaptable and scalable solutions such as Bovaer highlight the intersection of science and sustainability. These pioneering efforts demonstrate the potential for substantial environmental impact, driving the industry towards a greener future and setting a precedent for innovations that align economic and ecological objectives. 

A Pioneering Path: Arla’s Green Ambitions with Bovaer

Arla Foods UK has embarked on a groundbreaking trial to test the efficacy of Bovaer on 30 dairy farms. This strategic move aligns with Arla’s broader sustainability vision, which aims to mitigate the environmental impact of dairy production. By collaborating with several major grocery retailers, Arla seeks to assess the practical implications of implementing Bovaer on a larger scale and collect comprehensive methane reduction data from real-world settings. 

The rationale behind this trial is deeply rooted in Arla’s commitment to reducing Scope 3 greenhouse gas emissions and furthering its decarbonization efforts. Bovaer, a feed additive developed by DSM-Firmenich, promises to cut enteric methane emissions by significant margins — up to 30% for dairy cows. Such results support the dairy industry’s environmental targets and represent a tangible solution to one of the most pressing climate challenges. 

The regulatory nod for Bovaer in the UK came in January, following its approval by the United States Food and Drug Administration (FDA). This feed ingredient is commercially available in 68 countries, underscoring its global reach and the widespread recognition of its potential benefits in reducing livestock methane emissions. This trial signifies more than just an attempt to test a novel product; it is a step toward steering the dairy industry toward a more sustainable future.

When Innovation Meets Skepticism: The Bovaer Trial’s Unexpected Turmoil 

Arla Foods UK’s announcement of the Bovaer trial inadvertently triggered a whirlwind of unexpected consumer backlash. Public figures, such as UK MP Rupert Lowe, played pivotal roles in amplifying dissent. Lowe openly declared his refusal to consume products containing Bovaer and urged an expedited review by Defra. This vocal stance resonated with sections of the public, many of whom apprehended the introduction of a synthetic additive into a staple like milk. 

Social media perpetuates rampant misconceptions, adding fuel to the fire. A key driver of this was the unfounded association of dsm-Firmenich, the feed additive supplier, with high-profile tech billionaire Bill Gates. This erroneous linkage was shared widely, propagating suspicion and sowing doubt about the initiative’s intentions despite Arla and DSM-Firmenich’s clarifications. 

With its unparalleled reach and speed, social media became a fertile ground for spreading skepticism. Its echo chambers reverberated with misinformation, making it increasingly challenging for factual, nuanced details from the companies involved to gain traction. Arla and DSM-Firmenich faced significant hurdles in tackling these challenges, navigating a complex landscape of consumer mistrust that extended beyond mere additive concerns to broader corporate transparency and integrity themes. 

Addressing these deep-seated reservations involved both organizations engaging with stakeholders through various channels. They aimed to dispel myths and underline Bovaer’s rigorous scientific backing. Nevertheless, the rapid pace at which social media can distort narratives presented a formidable obstacle, underscoring the intrinsic challenge of managing corporate communications in an era where virality often outweighs veracity.

Navigating the Maze of Mistrust: Unraveling Consumer Attitudes Toward Chemical Additives

In the complex landscape of consumer behavior, skepticism towards food additives and chemicals often stems from a cocktail of psychological factors and societal influences. Dr. Jan Dijkstra, an associate professor in ruminant nutrition at Wageningen University, succinctly captures this sentiment by pointing to a growing distrust within Western society. He notes a prevalent ideology that aligns with ‘nature is better,’ suggesting that consumers increasingly gravitate towards what is perceived as natural or organic. This preference arises partly from a fear of the unknown—chemical names like 3-nitroxypropanol, for example, are dauntingly complex and conjure unease. 

Philip Graves, managing director at behavioral insights consultancy Shift, adds another layer by delving into the psychological underpinnings of these consumer reactions. He explains that the language used in communications about products like Bovaer can inadvertently trigger negative associations. For instance, ‘trial’ implies uncertainty, feeding into consumers’ inherent aversion to risk and loss. This mental association-building often skews perception, causing a new product to be viewed with suspicion. 

In addition to these psychological facets, the influence of social media and popular influencers significantly colors public perception. Influencers with vast followings can amplify skepticism, intentional or not, by perpetuating myths or expressing personal biases. This effect is magnified in a media landscape where sensationalism often outshouts reasoned debate, leaving many consumers wary and misinformed. 

The cumulative impact of these factors underscores a critical challenge for industry stakeholders: the need for transparent, science-backed communication strategies. By effectively addressing consumer concerns and enhancing education about the safety and benefits of food additives, companies can shift perceptions and build trust in innovations designed to meet urgent environmental goals.

Forging Trust: The Imperative of Transparent Communication in Navigating Consumer Crossroads 

Due to the recent consumer backlash against Bovaer, companies find themselves at a crossroads. Transparency and proactive engagement must become central to their strategies. The journey towards consumer acceptance begins with open, candid communication that demystifies the science behind feed additives. Organizations need to build a narrative around the safety, purpose, and ecological benefits of these innovations, presenting data in a format that is not only accessible but also relatable to the average consumer. 

Scientific backing plays a crucial role here; it is the foundation upon which trust can be built. Companies must be willing to fund comprehensive, high-quality research that stands up to scrutiny and critics alike. By publishing these results in peer-reviewed journals and making them available to the public, firms can reinforce the credibility of their claims. Furthermore, highlighting endorsements from independent regulatory bodies can help bridge the gap between skepticism and acceptance. 

Education is another critical pillar in mitigating backlash. Educational campaigns should illustrate the functionality and safety of additives like Bovaer and place them within the broader context of climate change mitigation efforts. Comparisons to everyday chemicals such as salt and vinegar—each beneficial yet widely accepted—could help consumers make cognitive connections that ease resistance. 

Engaging with trusted influencers can significantly enhance these efforts. These figures can act as ambassadors, dispelling myths and addressing concerns through relatable content that resonates with a broader audience. By leveraging their established platforms, influencers can help shift public perceptions and steer the conversation toward a more informed understanding of the benefits and necessities of such innovations. 

Ultimately, the industry must listen attentively to consumer feedback, conducting surveys and focus groups that uncover underlying fears and misconceptions. This dialogue can provide invaluable insights, enabling companies to tailor their communications and engagement strategies effectively. By fostering an environment of transparency and informed discourse, the dairy industry can chart a path forward that advances sustainability and garners consumer trust and acceptance. 

The Power of Perception: Navigating Consumer Psychology in Sustainability

Consumer psychology is a complex tapestry that significantly influences public reception of sustainability initiatives. Perception often triumphs over reality, profoundly shaping consumers’ attitudes. When sustainability efforts, like the Bovaer trial, encounter consumer skepticism, the problem is often rooted in the intricacies of psychological response. 

Experts such as Philip Graves underscore the pivotal role of framing and language in shaping these responses. In the psychological landscape consumers navigate, words are not mere conveyors of information but powerful triggers of emotion and belief. Phrases that suggest uncertainty or imply experimentation, such as “trial” or “considered safe,” can inadvertently cast shadows of doubt rather than enlightenment. 

Companies must delve into the art of positive priming to turn the tide. This involves crafting messages that resonate with authenticity and align with the public’s environmental aspirations. The clear, affirmative language contextualizing the environmental benefits can guide the narrative from skepticism to supportive engagement. 

Moreover, situating the initiative within a broader environmental context is essential. By connecting the dots between product usage and tangible environmental outcomes, companies can bridge the gap between consumer concerns and ecological advancements. Avoiding negative associations is about more than just avoiding them; it’s a call to inspire hope and confidence in the shared journey toward sustainability.

Charting a Sustainable Course: The Dual Challenge and Promise of Feed Additives in Dairy

As the dairy industry strives toward a future where sustainability is not just a preference but a necessity, the role of feed additives like Bovaer becomes increasingly pivotal. The spotlight on environmental responsibility has never been sharper. With livestock emissions under intense scrutiny, there is a pressing need for solutions to curb methane output. Feed additives’ potential to do just that places them at the forefront of this ecological endeavor. 

However, the journey is full of hurdles. Consumer concerns linger, casting long shadows over synthetic solutions despite their proven efficacy and cost efficiency. The industry is walking a tightrope between leveraging scientific advancements and addressing the alarm bells being rung by a skeptical public. The divide between synthetic and natural additives is stronger than ever, with calls for ‘natural’ solutions gaining traction despite the scientific complexities they may harbor. 

Yet, the allure of reducing greenhouse gases at a reduced cost cannot be ignored. Additives present a viable, economically sensible pathway to reduce the carbon footprint associated with dairy production. This dual advantage makes them an attractive prospect for stakeholders determined to align their operations with sustainability goals, even as they navigate the intricate dynamics of consumer acceptance. 

The choice between synthetic and natural additives may hinge on a critical balance of consumer perception and scientific advocacy. The industry’s commitment to greenhouse gas reduction seems unwavering, and feed additives, regardless of origin, will play a crucial role in this mission. The path forward will undoubtedly involve innovation in product development and communication of these advancements to an ever-discerning public.

The Bottom Line

In conclusion, Arla Foods UK’s trial of Bovaer has revealed the potent influence of consumer reactions on the dairy industry’s trajectory. This controversy underscores the intricate balance between embracing groundbreaking innovations and addressing consumer skepticism. As the industry advances, the imperative lies in fostering trust through transparent communication and engaging consumers positively to ensure that sustainability goals are effectively achieved. 

The conversation around Bovaer reveals more than just the challenges of implementing new technology; it highlights consumer perception’s critical role in the industry’s future. It prompts us to ponder: How can the dairy sector reconcile innovation with consumer acceptance to advance sustainability efforts while maintaining public trust? As stakeholders in this vital industry, the path forward hinges on informed decision-making and an understanding of consumer psychology in driving the sustainability agenda.

Key Takeaways:

  • The trial of the Bovaer feed additive has sparked significant controversy and consumer skepticism in the UK.
  • Misinformation and associations with known figures like Bill Gates exacerbated consumer backlash.
  • Growing public mistrust towards synthetic additives and chemicals in food influences perceptions.
  • Clear, transparent communication and scientific backing are crucial for businesses to build consumer trust.
  • Studying consumer psychology is vital to understanding and addressing their concerns.
  • The debate reflects broader consumer skepticism about sustainability claims and their perceived benefits.
  • Companies must navigate consumer attitudes by aligning with trusted influencers and providing relatable examples of additive use.

Summary:

The introduction of Bovaer, a feed additive designed to reduce methane emissions from cattle, has sparked controversy in the UK amidst growing consumer skepticism. Arla Foods UK’s trial, in collaboration with major grocery retailers, aimed to assess the potential for broad implementation but instead highlighted public distrust often fueled by misinformation. Despite Bovaer’s ability to cut methane emissions from dairy cattle by 30% and up to 45% for beef cattle—reflecting significant potential against the potent greenhouse gas—the trial provoked a backlash, emphasizing the importance of transparent communication. To navigate consumer perceptions, industry stakeholders must proactively engage and dispel myths, reinforcing the product’s scientific rigor and role in sustainable farming.

Learn more:

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

Denmark’s New Carbon Tax: What it Means for Dairy Farmers and Livestock Emissions

How will Denmark’s carbon tax on livestock affect your dairy farm? Read our expert analysis to determine what this means for your farm and emissions.

Summary:

Within the last month, the world has seen the first dairy farmers scheduled to be taxed for their cows’ methane emissions. Denmark has taken a pioneering step by introducing the world’s first carbon tax on agriculture, aiming to combat the environmental impact of livestock. In 2030, Danish dairy farmers will face an annual tax of $96 per cow, eventually increasing to $241 by 2035. This bold move has sparked a mix of reactions from the industry, ranging from cautious optimism to outright skepticism. As the global food system contributes nearly a third of greenhouse gas emissions, with livestock farming accounting for around 12%, Denmark’s initiative could serve as a model for other nations addressing climate change. Denmark’s dairy industry, a critical component of the economy, significantly impacts its carbon footprint. The government’s plan aligns with its broader climate ambitions to cut greenhouse gas emissions by 70% by 2030 compared to 1990, investing 40 billion kroner (about USD 5.9 billion) in forestry, wetland restoration, and other environmental activities to combat climate change.

Key Takeaways:

  • The first carbon tax on livestock globally will start in Denmark, targeting dairy farmers starting in 2030.
  • Farmers will initially pay a tax of $17 per cow annually, increasing to $43 by 2035.
  • Denmark’s measure aims to transform agriculture, focusing on sustainability and reducing methane emissions.
  • Profits from the tax will support the agricultural sector’s transition to greener practices in its first two years.
  • The Danish dairy industry shows mixed reactions, balancing acknowledgment of climate issues with concerns about bureaucratic impact.
  • Stakeholders emphasize the need for the tax to align with European Union legislation for fair competition.
  • This move might set a precedent, potentially influencing global agricultural policies on emission reductions.
  • Farmers may face new challenges but can explore innovative solutions to mitigate emissions effectively.
carbon levy Denmark, methane emissions reduction, dairy industry sustainability, carbon tax livestock, greenhouse gas emissions Denmark, climate change Denmark, livestock farming impact, feed additives methane, green technology agriculture, low-methane livestock breeding

Consider a yearly $100 charge for each cow in your herd. This is the reality for Danish dairy producers beginning in 2030, owing to the world’s first carbon levy on animals to reduce methane emissions. This pioneering law, which represents a massive change in global agriculture policy, has the potential to alter the dairy business’s financial structure drastically and set a global precedent. How equipped are we as a sector to bear this increased burden? The impact of Denmark’s decision extends beyond statistics. Not only is this the first such endeavor worldwide, but it also establishes a precedent that other nations may follow. The new tax, set to increase to $43 per animal per year by 2035, raises the issue of how dairy producers and the agriculture industry can reconcile sustainability and profitability. “With today’s deal, we are spending billions in the most significant reshaping of the Danish environment. “At the same time, we will be the first country in the world to impose a carbon tax on agriculture,” stated Foreign Minister Lars Lokke Rasmussen. This effort tries to push the agriculture industry toward more sustainable practices. But the essential issue remains: at what cost are we willing to adapt effectively? The potential for global influence of Denmark’s carbon tax is significant, and it’s a policy that the world will be watching closely.

Denmark’s Dual Identity: Quality Dairy Exports and Carbon Emissions 

Denmark is prominent in the global dairy and pork markets. The nation exports high-quality items to several locations throughout the globe. Denmark’s agriculture industry is a critical component of the economy and a significant contributor to greenhouse gas emissions.

The Danish government’s plan to impose a carbon price on cattle is consistent with its broader climate ambitions. Denmark has set aggressive goals, intending to cut greenhouse gas emissions by 70% by 2030 compared to 1990. This plan calls for a significant expenditure of 40 billion kroner (about USD 5.9 billion) on forestry, wetland restoration, and other environmental activities to combat climate change.

Why is there a concentration on livestock? Livestock farming, notably dairy and pork production, is essential to Denmark’s economy and significantly impacts its carbon footprint. According to the United Nations Food and Agriculture Organization (FAO), livestock emissions comprised around 12% of global greenhouse gas emissions in 2015. Methane, a potent greenhouse gas released by cows via enteric fermentation and dung, substantially influences climate change owing to its higher global warming potential than CO2.

A Timeline for Carbon Tax Implementation: What Dairy Farmers Need to Know

The Danish government has given a precise timeframe for putting the carbon price on livestock emissions, which will begin in 2030. Initially, the fee will be 300 kroner ($43) per tonne (1.1 tons) of CO2-equivalent emissions. This tariff will rise to 750 kroner ($107) per tonne by 2035.

However, these data only convey part of the picture. Farmers will get a 60% tax reduction, decreasing their effective costs. In practice, beginning in 2030, farmers will be taxed 120 kroner ($17) per tonne of animal emissions every year. Even if the baseline tax rate climbs by 2035, the 60% cut will remain in effect, resulting in farmers paying 300 kroner ($43) per tonne.

Let’s see what this implies for the ordinary Danish dairy farmer. Danish dairy cows emit around 5.6 tons of CO2 equivalent per year. Under the initial tax rate with the 60% break, this amounts to a charge of: 

  • 2030: 5.6 tonnes x 120 krone = 672 krone per cow ($96)

By 2035, with the increased tax rate and 60% break applied, the cost will be: 

  • 2035: 5.6 tonnes x 300 krone = 1,680 krone per cow ($241)

For a farmer with a herd of 100 cows, this translates to a financial burden of: 

  • 2030: 100 cows x 672 krone = 67,200 krone ($9,600)
  • 2035: 100 cows x 1,680 krone = 168,000 krone ($24,100)

While the goal is to incentivize carbon reduction via innovation, these statistics significantly burden farmers, possibly hurting their bottom line and company operations. It begs the issue of whether this will encourage the Danish dairy business toward more environmentally friendly methods or impose unsustainable expenses.

Industry Reactions: Support, Concern, and Skepticism

Denmark’s dairy business has responded positively and negatively to the new carbon tax measures. Peder Tuborgh, CEO of Arla Foods, called the deal “positive” but highlighted the need for fairness: “Farmers who genuinely do everything they can to reduce emissions should not be taxed.” Tuborgh contends that any tax base must be based entirely on emissions that may be practically controlled, implying that the tax requires practical implementation measures.

Kristian Hundebøll, CEO of DLG Group, highlighted worries about the competitiveness of Danish agriculture if the tax is not included in EU law. As Hundebøll puts it, “Neither the climate, agriculture nor the ancillary industries benefit from Denmark acting unilaterally.” This remark reflects concerns that Denmark’s pioneering position may harm its farmers compared to other EU members.

Despite these affirmations of the tax’s general environmental purpose, many in the dairy industry are wary. Farmers’ organizations, such as Baeredygtigt Landbrug, see the restrictions as burdensome and possibly obstructive to continued green expenditures. Chairman Peter Kiær expressed a widespread fear: “We recognize a climate problem…” However, we do not feel this deal will address the issues since it would interfere with agriculture’s green initiatives. These comments highlight a considerable divide among businesses regarding the best way to combine environmental responsibility and commercial success.

Innovative Adaptations: Strategies to Navigate Carbon Tax Challenges 

As dairy producers cope with the ramifications of this new carbon tax, it is critical to evaluate viable solutions and modifications to reduce the financial burden. One popular method is to alter livestock diets to limit methane emissions. For example, feed additives such as seaweed may prevent methane-producing microorganisms in cow digestive tracts. According to research by the University of California, Davis, this approach may reduce methane emissions by up to 82 percent.

In addition to feed adjustments, investing in green technology provides another path for reducing emissions. Anaerobic digesters convert manure into biogas, lowering methane emissions and providing a green energy source for the farm. According to EPA statistics, farms employing anaerobic digesters may cut greenhouse gas emissions by an average of 2,200 tons of CO2 equivalent yearly.

Another novel approach is genetic selection and breeding for low-methane-emitting livestock. According to CSIRO research, selective breeding has the potential to cut methane emissions over time drastically. Although still in its early phases, this strategy provides a long-term answer.

Industry experts underline the need for a multifaceted strategy. Torsten Hasforth, Concito’s chief economist, states that “the combination of feed changes, green technologies, and breeding programs is likely to yield the best results for farmers looking to reduce emissions” (source). However, he warns that the initial investment in these solutions might be significant, necessitating government or private sector financial assistance to make them viable for small-scale farmers.

Finally, the success of these solutions depends on their acceptance and execution. While large-scale dairy businesses may have the resources to invest in these technologies, smaller farms may need targeted subsidies or incentives to make these improvements possible. Coordination among farmers, academics, and politicians will be critical to achieving real carbon reductions as the business evolves.

Where Do Dairy Farmers Go From Here? 

So, where will dairy farmers go from here? The impending carbon price may seem like a hefty weight, but farmers can take tangible actions to cut their emissions and, as a result, limit the financial effect.

First, let’s discuss feed. Studies have shown that modifying cow diet may dramatically decrease methane emissions. For example, increasing fats or oils in the diet or including seaweed supplements may help cows create less methane. Dr. Frank Mitloehner, an air quality expert at UC Davis, says, “Dietary changes are one of the most accessible methods for reducing enteric methane emissions.”

Second, investing in green technology provides another option. Methane digesters transform manure into renewable energy, reducing emissions and producing valuable byproducts such as biofertilizers. Although these systems require early expenditures, they may result in significant long-term savings. According to Torsten Hasforth, Concito’s chief economist, “Installing methane digesters can be a win-win solution for both emissions and economic viability.”

Genetic selection is also a potential field. Breeding cows with naturally low methane emissions might provide a long-term answer. Although this may seem like something from a science fiction book, genetic selection has already shown promise for increasing other qualities, such as milk production. Dr. John Wallace, a University of Aberdeen researcher, believes that “selective breeding for lower methane emission traits could revolutionize the dairy industry.”

Finally, we should pay attention to pasture management measures. Efficient grazing management may increase soil carbon sequestration, indirectly offsetting some of the emissions from animals. Rotational grazing techniques promote pasture health and increase the soil’s carbon absorption capacities.

While each solution has its constraints, it also offers dairy farming innovation opportunities. Adopting these ideas might lead to more sustainable farming practices that help the environment and the financial line.

Global Comparisons: How Denmark’s Livestock Carbon Tax Stacks Up 

Denmark’s pioneering initiative to impose carbon prices on cattle differs sharply from methods in other nations. While New Zealand has suggested a methane reduction plan for its agricultural sector, its policy emphasizes incentives rather than outright taxes, concentrating on collaborative efforts with farmers to adopt sustainable techniques. Similarly, Ireland has implemented initiatives such as the Beef Data and Genomics Scheme, which encourages producers to breed low-emitting livestock without imposing a fee. 

Will Denmark’s brave move establish a worldwide precedent? Environmental economists think it may. “Denmark’s carbon tax on livestock could be a catalyst for similar policies across Europe,” says Dr. Lars Myhrvold, an environmental economist at Stockholm University. “Other EU countries are likely observing the impacts before considering similar measures.” Policy experts such as Klara Franzen of the European Environmental Bureau believe that similar projects will become more common, mainly if Denmark demonstrates that economic viability can combine with rigorous climate targets.

The ramifications are considerable. If Denmark succeeds, it will strengthen its commitment to the Paris Agreement while influencing global farming practices. This approach sends a clear message: address agricultural emissions front-on, even if it means making difficult economic choices.

Denmark’s Bold Move: A Catalyst for Global Dairy Industry Transformation? 

Denmark’s groundbreaking carbon tax on cattle is more than a national effort; it can potentially reverberate throughout the global dairy sector. This action raises important questions: Will other nations follow suit? Could this be the start of a new era in agriculture policy?

First, examine the precedent it establishes. Denmark’s decision illustrates how a nation may incorporate environmental responsibility into its agriculture industry. Other governments, particularly those in the European Union, may feel pressured to take similar steps to comply with regional climate targets. The EU has long been at the forefront of climate policy, and seeing one of its members take this move may spark more significant, coordinated action.

Furthermore, global dairy exporters from New Zealand, the United States, and South America may face growing pressure to adopt comparable techniques. These nations might use Denmark’s strategy as a foundation for reducing their agricultural emissions. Policymakers may claim that local firms must achieve more excellent environmental criteria to compete in a global market focused on sustainability.

However, it is critical to consider the possible economic implications. A carbon tax may raise farmers’ operating expenses, increasing consumer prices. This scenario may encourage governments to compromise environmental advantages and economic stability. Subsidies and transition money, for example, might help make such policies more appealing to the farm industry.

Denmark’s carbon price might establish a worldwide benchmark, causing a domino effect as countries struggle to fulfill international climate targets. The global dairy sector will need to prepare for change, not only in terms of compliance but also via new techniques that cut emissions while preserving production. The more enormous ramifications are clear: Denmark’s decision might signal the start of a revolutionary moment for global dairy production, propelling the sector toward a greener, more sustainable future.

Frequently Asked Questions (FAQ) on Denmark’s Livestock Carbon Tax 

  1. Why is Denmark implementing a carbon tax on livestock?
    Denmark intends to minimize greenhouse gas emissions from agriculture,  which is essential to climate change. The administration expects that imposing a carbon fee would promote more sustainable agricultural methods and help the nation fulfill its climate objectives [CNN].
  2. How much will the tax cost dairy farmers?
    The tax will begin at $17 per tonne of CO2-equivalent emissions in 2030 and rise to $43 per tonne in 2035. On average, this equates to $96 per cow per year at the start, increasing to $241 by 2035 owing to the 60% tax exemption.
  3. What will the government do with the tax revenue?
    The income will help the agriculture business adapt to more environmentally friendly methods in the first two years. The tax and its effect will then be evaluated [CNN].
  4. Are there any provisions for farmers already invested in reducing emissions?
    While the particular details have still to be determined, the tax must be based on emissions that may be controlled. Industry representatives believe farmers who endeavor to reduce emissions should not face undue burdens.
  5. How do Danish farmers view the new tax?
    Opinions vary. Some see it as a significant step toward sustainability. Still, others see it as unnecessary bureaucracy that stifles agricultural investment in green technology [CNN].
  6. What are some potential solutions to reduce livestock emissions?
    There are many ways to reduce methane emissions, including altering animal diets, improving manure management, and investing in methane collection and conversion devices.

The Bottom Line

Denmark’s implementation of the world’s first carbon tax on livestock is a dramatic change in agricultural policy aimed at reducing methane emissions from dairy cows. The fee will start at $17 per animal annually and increase to $43 by 2035. While the Danish dairy sector has shown some support, questions regarding economic feasibility and competitiveness remain. The tax’s more enormous ramifications include global sustainability initiatives, emphasizing the dual demands of environmental responsibility and agricultural production.

This proposal raises fundamental challenges about how to strike a balance between cutting emissions and keeping the dairy business sustainable. Adapting to these new restrictions requires creative solutions and a collaborative effort from farmers, industry stakeholders, and legislators. As we look forward, we must ask ourselves: Can the dairy business maintain its productivity while adhering to severe environmental regulations, or will these new rules irreversibly transform the agricultural landscape as we know it?

Learn more: 

Join the Revolution!

Bullvine Daily is your essential e-zine for staying ahead in the dairy industry. With over 30,000 subscribers, we bring you the week’s top news, helping you manage tasks efficiently. Stay informed about milk production, tech adoption, and more, so you can concentrate on your dairy operations. 

NewsSubscribe
First
Last
Consent

£4bn Investment Needed to Boost Climate Resilience in UK Dairy Farms, Report Finds

Learn why UK dairy farms need a £4bn investment for climate resilience. What does this mean for the future of dairy farming and protecting the environment?

Imagine a UK where dairy farms withstand the worst storms, endure droughts, and still produce the milk we love. This vision drives the urgent £4 billion investment in climate resilience for UK dairy farms. According to Kite Consulting’s report, this significant financial commitment is not just essential, but immediate. “The Cost of Climate Resilience: Future Proofing UK Dairy” estimates that necessary capital infrastructure and land improvements will average £472,539 per farm, or 2.4ppl annually over ten years. Why is this investment crucial? Given the increasing threat of severe droughts and unpredictable weather, robust, adaptable dairy farms are vital to securing the future of the dairy industry and our entire food supply chain.

Climate-Proofing UK Dairy Farms: A £3.9 Billion Necessity, But Also a Gateway to a Resilient FutureConsultants from Kite Consulting estimate that the investment needed to bolster climate resilience on UK dairy farms will total £3.9 billion over the next decade. The average cost per farm is projected at £472,539, primarily due to the need for capital infrastructure upgrades and additional land. This translates to an annual impact of 2.4 pence per liter of milk for the next ten years. These investments are crucial to prepare for increased drought risks and ensure compliance with environmental regulations, safeguarding the future of dairy farming amid evolving climate conditions.

The Rising Costs of Silage Storage: A Critical Challenge for UK Dairy Farmers

The costs of maintaining adequate silage storage are a growing concern for UK dairy farmers. As climate change increases drought conditions and delays grazing turnouts, more silage capacity becomes crucial. Farms now require about 1,350 additional tonnes of silage storage to be prepared. Financially, this means significant outlays. Enhancing silage storage to hold 1.5 years’ reserves is estimated at £204,450 per farm. This includes building extra silage clamps and associated infrastructure and maintenance costs. These investments are vital to protect forage stocks and ensure consistent milk production during adverse weather.

The Crucial Role of Forage Stocks in Sustaining Milk Production Amid Climatic Uncertainty: A Key Factor in Dairy Farming’s FutureUnderstanding the crucial role of forage stocks in maintaining milk production is essential as UK dairy farms adapt to climate change. Dairy cows need a steady forage supply to sustain their nutritional needs and milk output. Increased drought risks in summer or prolonged rainfall in winter can make grazing conditions unpredictable, reducing fresh pasture availability. To bridge this gap, farmers must have robust silage reserves. Without them, milk production can drop, leading to economic losses. Droughts affect immediate grazing and subsequent harvests, worsening forage shortages.

Similarly, extended wet periods require cows to be housed longer, increasing the need for stored forage. Hence, additional silage storage is vital, as Kite Consulting highlights. Adequate forage reserves ensure consistent milk supply, financial stability, and resilience for the UK dairy sector.

Slurry Storage Shortfalls: A Critical Barrier to Climate Resilience on UK Dairy Farms 

The current state of slurry storage on UK dairy farms is alarming, with about 85% of farms having less than eight months of storage. Given the rise in extreme weather events, this shortfall is critical, as it heightens pollution risks. The Silage, Slurry, and Agricultural Fuel Oil (SSAFO) regulations mandate a minimum of 4 months of slurry storage. However, this proves inadequate, especially after record-breaking rainfall in the last 18 months. 

Farms in Nitrate-Vulnerable Zones (NVZs) face even stricter rules. To prevent nitrate pollution, they need at least 22 weeks (5 months) of storage. Compliance in these areas also includes stringent nitrogen application limits to protect water bodies from agricultural runoff. 

Industry experts suggest that enhancing slurry storage to 8 months with covers is essential for tackling pollution and operational disruptions caused by unpredictable weather. This upgrade, necessary for environmental and operational sustainability, is estimated to cost dairy farmers £92,296 per farm. 

Boosting slurry storage capacity is vital in fortifying UK dairy farms against climate change. Although expensive, these investments are crucial for ensuring environmental stewardship and long-term viability in an increasingly volatile climate.

Navigating Nitrate Vulnerable Zones: A Balancing Act for Environmental Protection and Dairy Farm Viability

Nitrate-vulnerable zones (NVZs) cover 55% of land in England, aiming to protect waterways and soils from nitrate pollution. Dairy farmers in these zones face stringent rules to mitigate environmental harm. They must maintain a minimum of 22 weeks—roughly five months—of cattle slurry storage to prevent leaching into watercourses. NVZ regulations also impose strict limits on nitrogen application from both organic and inorganic sources, requiring precise nutrient management. 

The implications are significant. Increased slurry storage and meticulous nitrogen management demand substantial financial and administrative investment, which is incredibly challenging for smaller farms. Non-compliance carries the risk of legal penalties and fines. While essential for environmental sustainability, these regulations require the farming community to align with governmental standards, highlighting the need for robust support and resources.

Breaking Down the Financial Commitments for Climate Resilience: Key Investments on UK Dairy Farms 

The critical investments needed to strengthen climate resilience on UK dairy farms come with notable financial commitments: 

  • Silage Clamps: Farms must invest in extra silage clamps to store an additional 1,350 tonnes of silage. The estimated cost per farm is £204,450.
  • Slurry Stores: Increasing slurry storage to 8 months is crucial for regulatory compliance and pollution control, and it would cost £ 92,296 per farm.
  • Additional Land: More land is needed to build forage stocks and properly apply manure, adding significantly to the financial burden, although costs vary by location.

These investments, which form a key part of the £472,539 needed per farm over the next decade, contribute to the overall industry requirement of £3.9 billion. This highlights the urgent need for strategic funding and support to prepare for climate challenges. The recommendations in this report are not just suggestions but crucial steps that need to be taken to ensure the resilience and sustainability of the UK dairy industry in the face of climate change.

Leveraging Grants and Support Mechanisms: A Financial Lifeline for Climate Resilience on UK Dairy Farms

Farmers navigating the financial challenges of enhancing climate resilience on UK dairy farms can leverage various grants and support mechanisms to ease the economic burden. Among these, the Slurry Infrastructure Grant is pivotal, offering financial aid to upgrade slurry storage facilities. Two rounds of these grants have been disbursed, with a third expected later this year. These grants empower livestock farmers to achieve the requisite six months of slurry storage capacity, a critical component for maintaining environmental standards amidst changing climatic conditions. 

Despite the governmental support, the industry still faces a significant financial commitment. Each business can apply for a minimum grant of £25,000, covering up to 50% of eligible project costs. However, even with this support, the industry is still burdened with a substantial financial commitment. A minimum investment of £3.9 billion is needed to secure the necessary infrastructure and land for robust environmental protection. This underscores the need for external support to ensure the long-term sustainability of the UK dairy industry. 

Farmers can also seek other support tailored to dairy operations’ needs. These include subsidies for capital infrastructure investments and initiatives to promote sustainable practices, mitigate disease risks, and improve farm resilience. These efforts make climate adaptation and sustainable milk production more attainable for the UK’s dairy sector.

The Bottom Line

Securing the future of UK dairy farming amid rising climate challenges requires nearly £4 billion. This investment is crucial to protect the industry against adverse climate impacts and ensure operational resilience. Over a decade, with an average cost of £472,539 per farm, this financial burden is substantial but necessary for maintaining consistent milk production and environmental health. Critical investments include:

  • Enhanced slurry and silage storage.
  • Adequate land for manure management.
  • Improved forage reserves.

These improvements meet regulatory requirements and reduce risks from extreme weather, protecting both ecosystems and farmers’ livelihoods. Grants and support mechanisms offer some relief, but the industry must still cover a significant portion of the costs. Without this investment, UK dairy farms’ capacity to withstand environmental pressures and contribute to national food security will be compromised. All stakeholders need to understand the urgency of this investment. By committing to these changes, we can ensure the dairy industry’s viability and resilience for the future.

Key Takeaways:

  • The estimated cost to improve climate resilience across UK dairy farms over the next 10 years is approximately £3.9 billion.
  • The average cost per farm for capital infrastructure investments and additional land is projected to be £472,539, equating to 2.4ppl annually for a decade.
  • Extra silage storage per farm, necessary for drought and late grazing turnouts, will require an additional 1,350 tonnes at a cost of £204,450 per farm.
  • Currently, 85% of dairy farms have less than 8 months of slurry storage, falling short of the recommended 8 months capacity with covers.
  • Compliance with Nitrate Vulnerable Zones (NVZ) regulations is crucial, but costly, needing up to £92,296 per farm for adequate slurry storage.
  • Strategic investments in silage clamps, slurry stores, and expanded land area are key to achieving climate resilience and environmental protection.
  • A third round of the Slurry Infrastructure Grant is anticipated, with funds available to cover up to 50% of eligible project costs, but significant industry-wide financial commitment remains essential.
  • The dairy industry will need to invest a minimum of £3.9 billion despite potential government support, emphasizing the scale of the challenge ahead.

Summary:

The UK dairy industry is set to invest £4 billion in climate resilience over the next decade, with an average cost of £472,539 per farm. This investment is crucial due to the increasing threat of severe droughts and unpredictable weather, which threatens the dairy industry and the food supply chain. The total investment is expected to be £3.9 billion, with an annual impact of 2.4 pence per liter of milk for the next ten years. The rising costs of silage storage are a critical challenge for UK dairy farmers, with an estimated £204,450 per farm for silage storage to hold 1.5 years’ reserves. Additionally, slurry storage shortfalls on UK dairy farms are critical, with about 85% having less than eight months of storage.

Learn more:

Send this to a friend