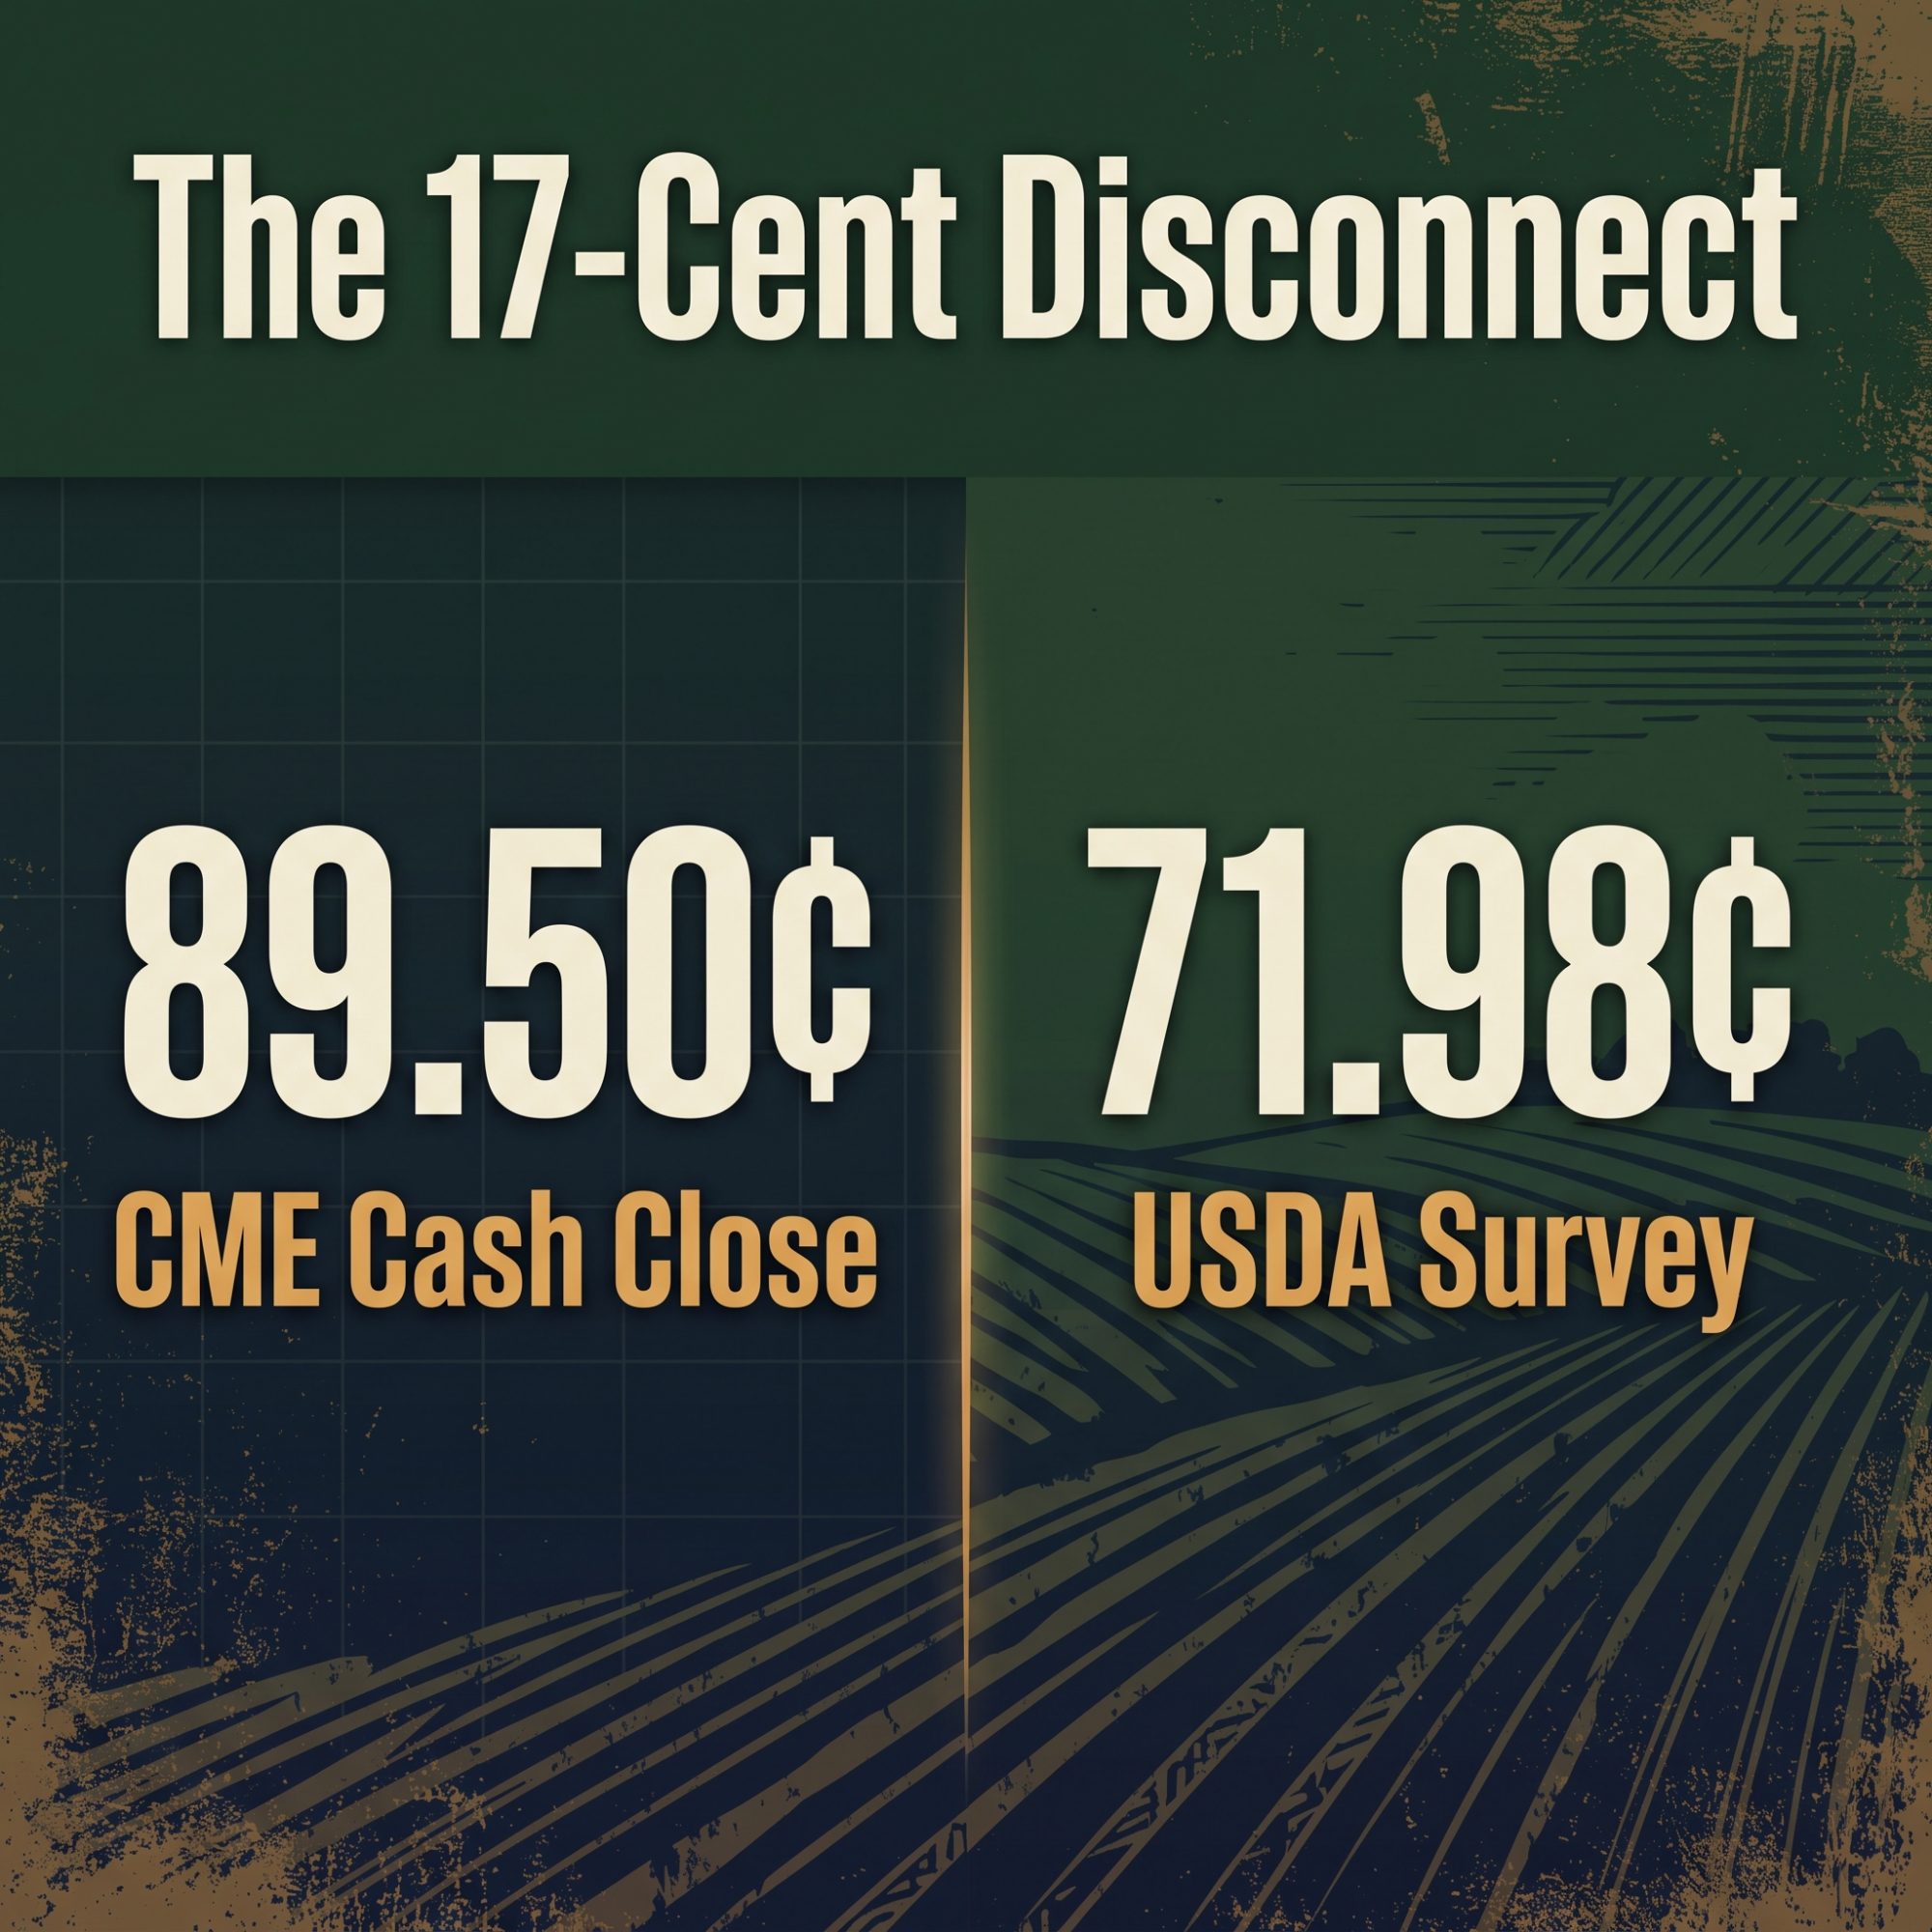
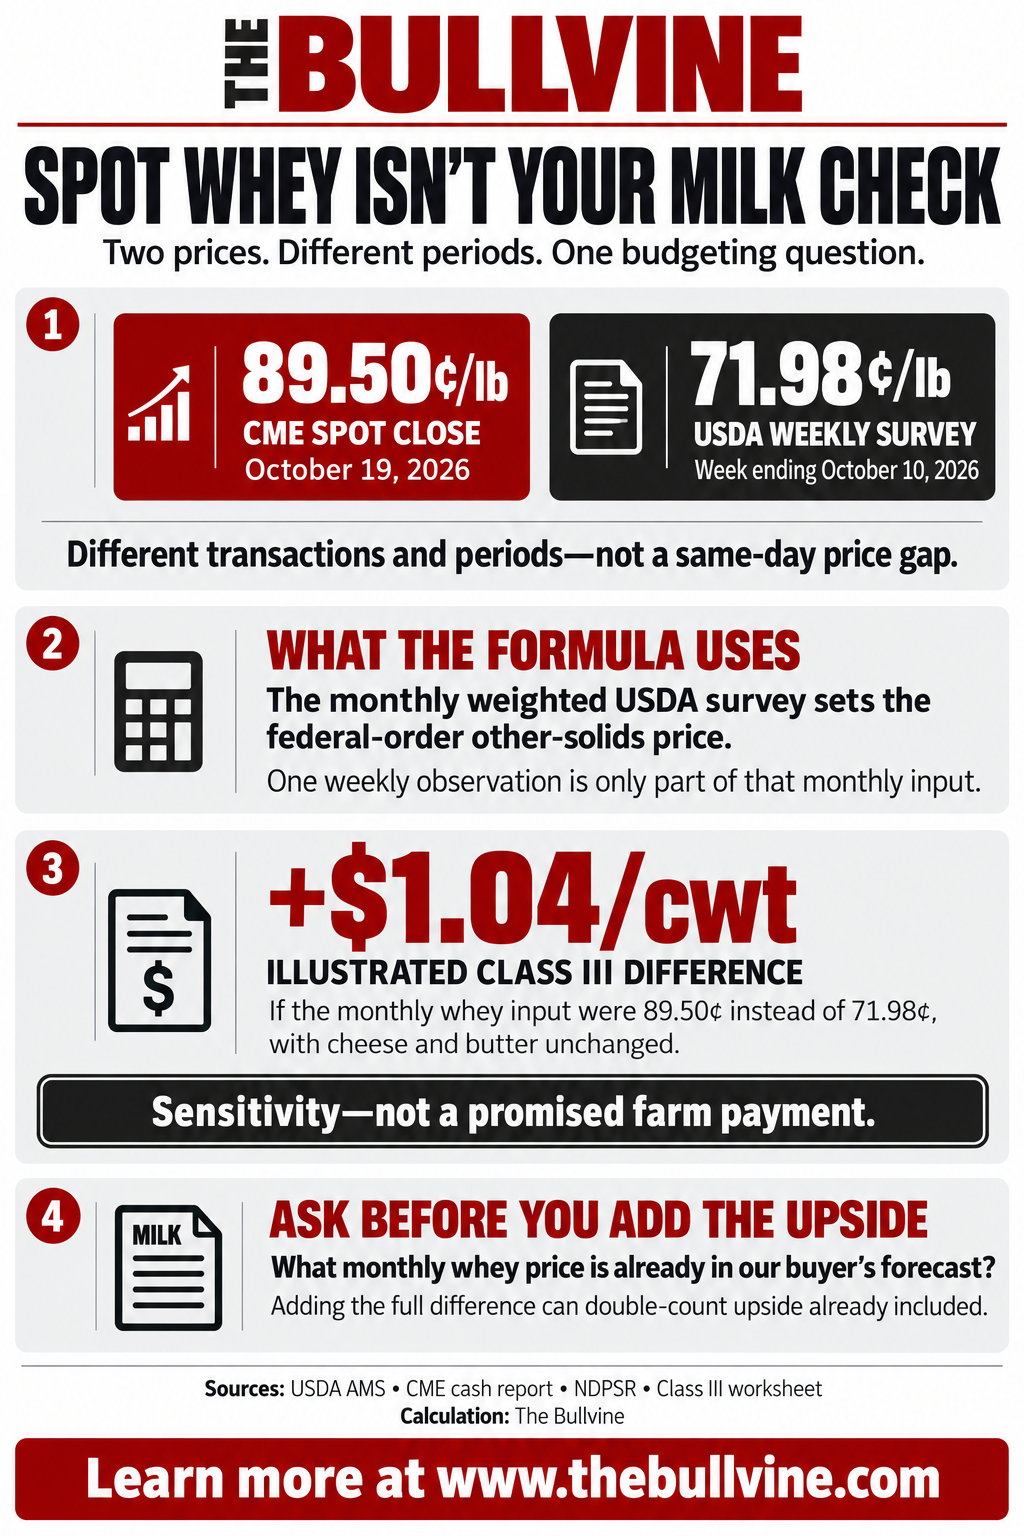
CME dry whey closed at 89.5¢ on October 19. USDA’s latest weekly survey reported 71.98¢. The monthly weighted survey—not the spot close—sets the federal-order other-solids price.
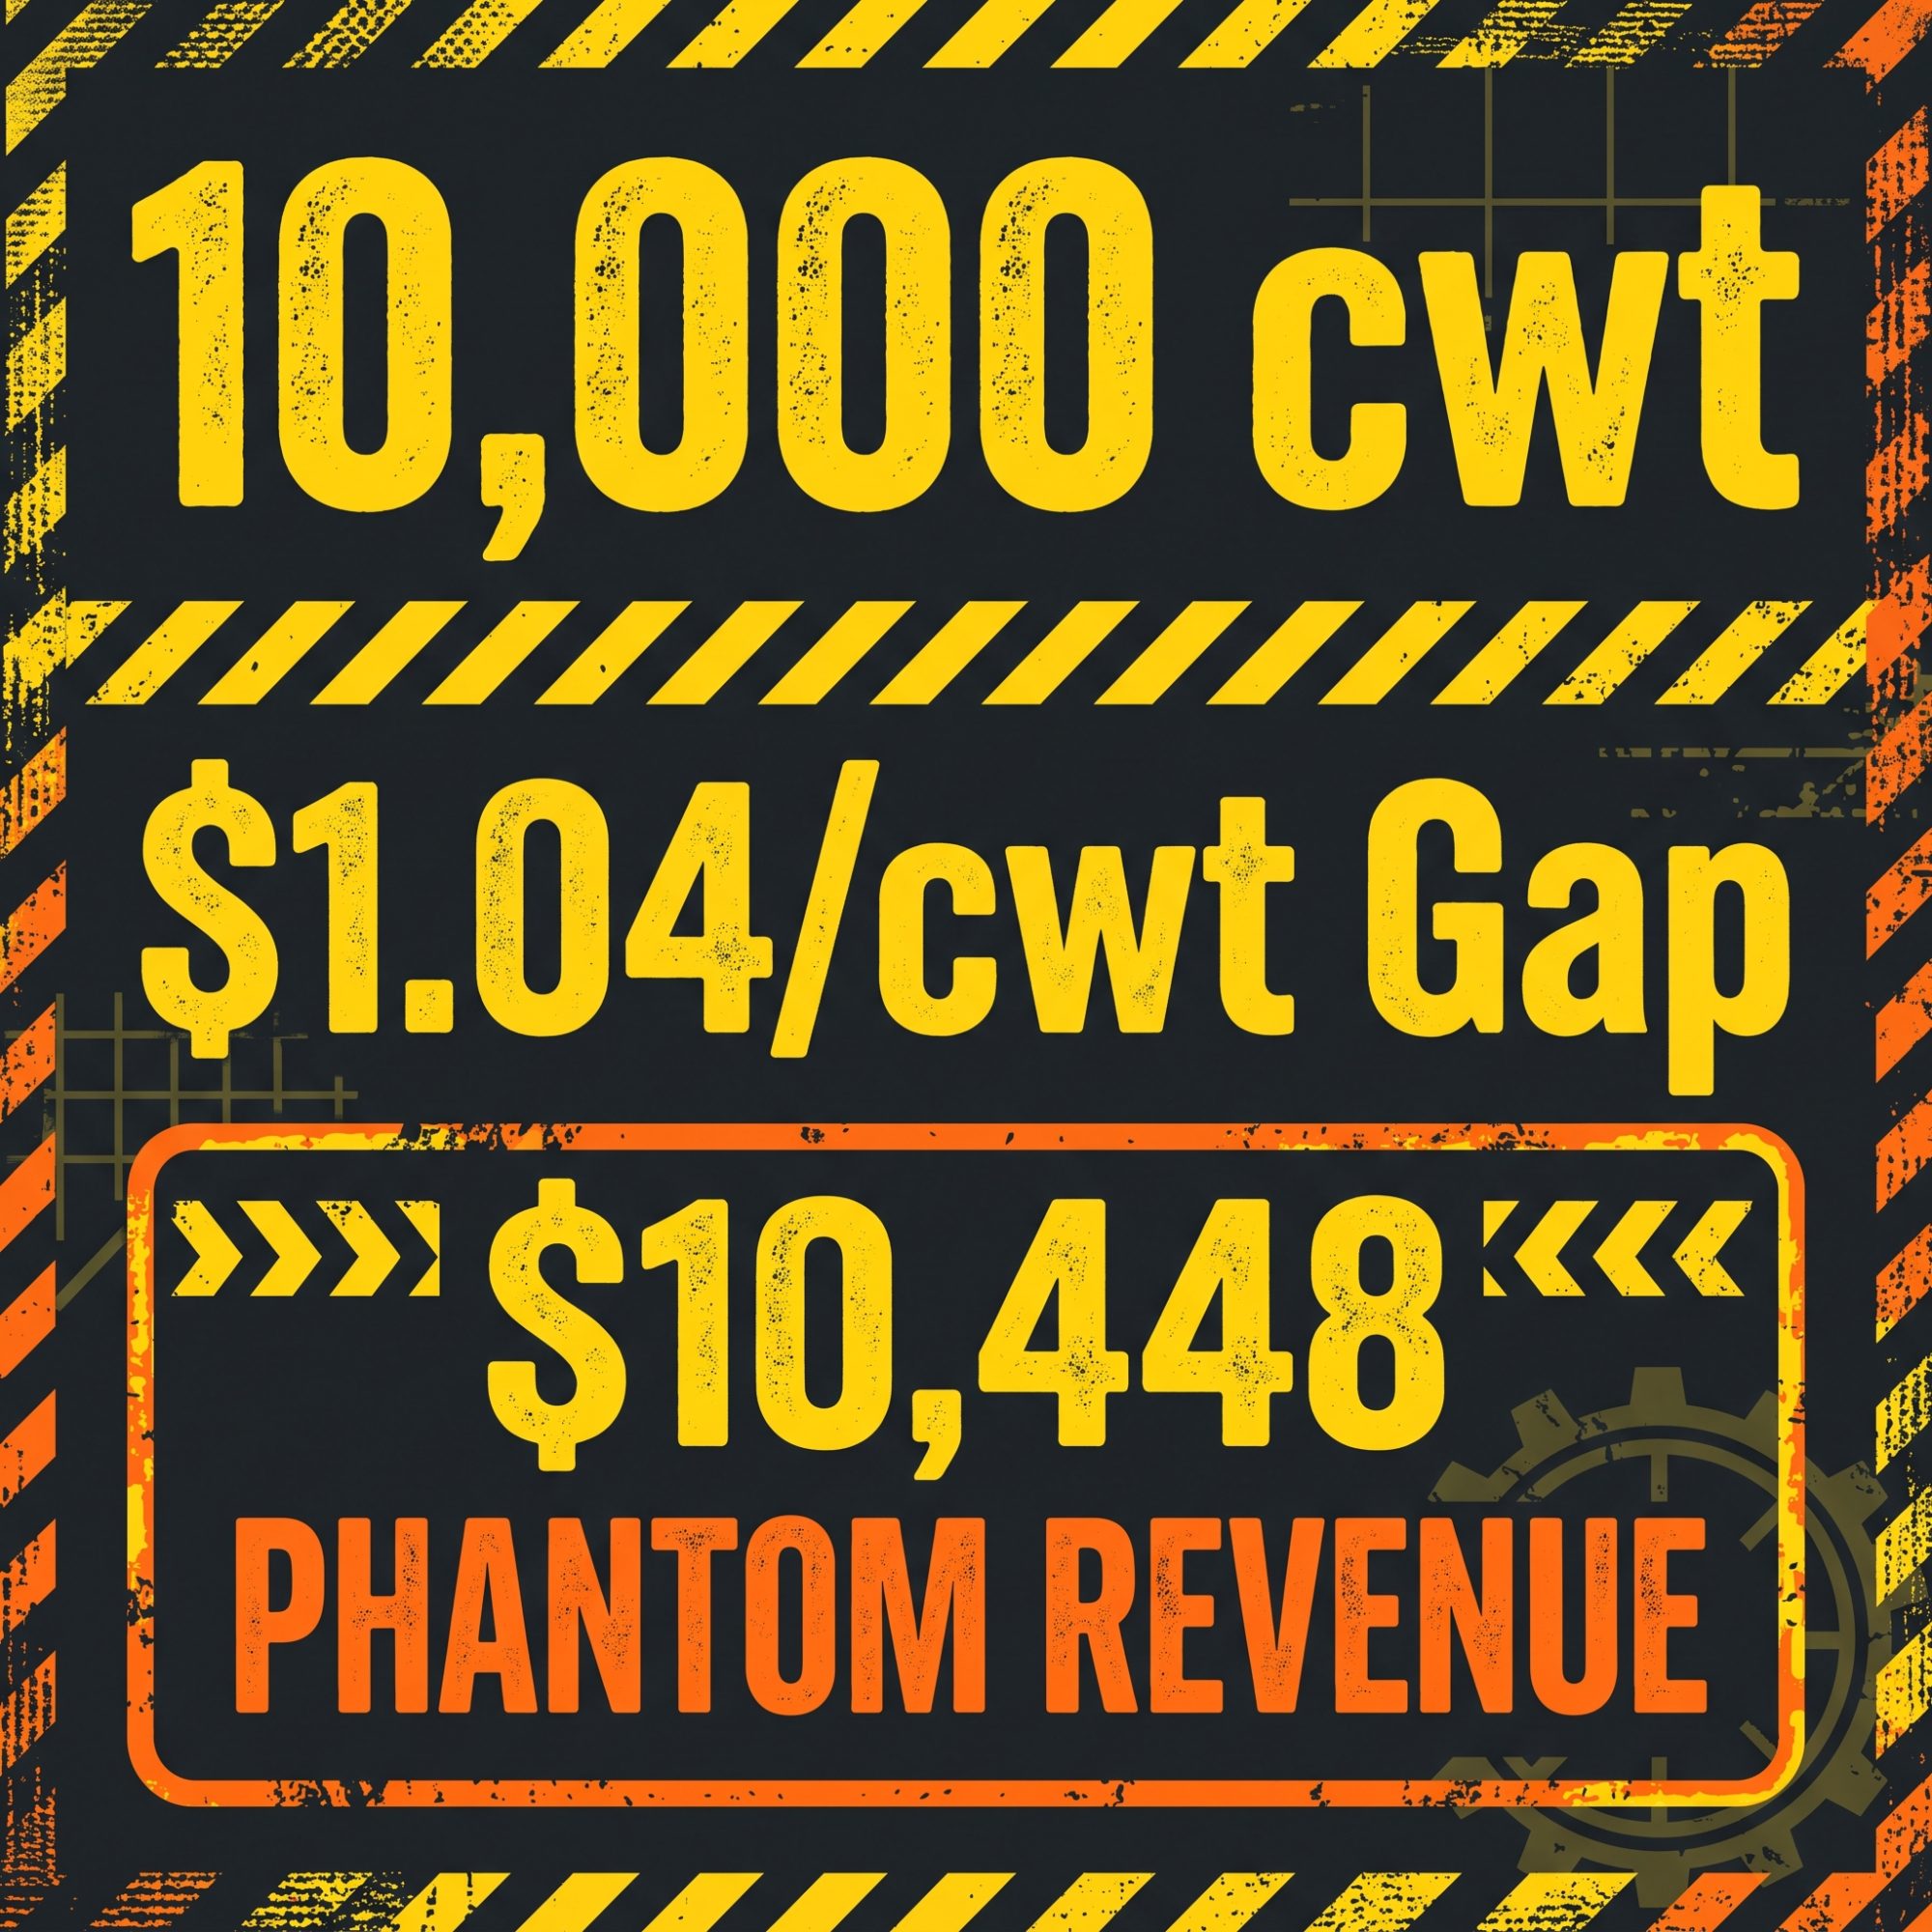
Both references cover Extra Grade dry whey, but they measure different transactions over different periods. Run both through USDA’s current Class III math and the distance is about $1.04 per hundredweight. That is Bullvine’s calculation, not a USDA price, and it is a sensitivity, not a payment. It belongs in the scenario column of the budget until the survey says otherwise.
Three markets, different pressures
The U.S. Dairy Export Council’s August trade analysis splits the protein story in two. Low-protein whey exports rose 25%. High-protein whey exports, the WPC80+ class, fell 21%, and USDEC attributed that fall to limited exportable supply.
The 25% was not dry whey alone. USDEC’s low-protein category bundles dry whey, low-protein whey protein concentrate and modified whey, and all three grew. Canada and Southeast Asia took most of the increase.
Milk protein concentrate exports rose 36% to 5,225 metric tons. USDEC’s read is that protein-fortified product makers turned to MPC because of the WPC80+ supply and price situation. That is USDEC’s interpretation, not a count of who reformulated.
Export category
Year-over-year volume change
What the category covers
USDEC’s reported context
Low-protein whey
+25%
Dry whey, low-protein whey concentrate, and modified whey
All three classifications grew; Canada and Southeast Asia drove most of the increase
High-protein whey, WPC80+
−21%
USDEC’s high-protein whey grouping
Limited exportable supply constrained shipments
Milk protein concentrate, MPC
+36%
Milk protein concentrate exports
USDEC suggested manufacturers were turning toward MPC given WPC80+ supply and pricing
Nonfat dry milk / skim milk powder
−19%
Combined NFDM and SMP exports
Elevated U.S. prices and limited exportable supply weighed on shipments
So August supports two things at once: stronger overseas demand for lower-protein whey, and tight export availability of high-protein ingredients. It does not support one shortage across everything with “protein” on the bag.
USDA counted 75.1 million pounds of dry whey production in August, up 8.2% on the year. Stocks sat at 61.3 million pounds, 21.6% above August 2025 and 10.4% below July. Heavier than last year, drawing down from last month, and neither figure measures what was uncommitted in October. A record spot close and a 21.6% stock build can both be true. What the stocks number kills is the story that the country ran short of whey.
USDA measure
August 2026 (million lb)
Change from August 2025
Change from July 2026
Total dry whey production
75.1
+8.2%
−7.4%
Total dry whey manufacturers’ stocks
61.3
+21.6%
−10.4%
Nonfat dry milk production, human use
132.2
+9.6%
−19.9%
Nonfat dry milk manufacturers’ stocks, human use
216.3
−3.6%
−7.1%
NFDM already shows resistance
Nonfat dry milk is a different tension. Production rose 9.6% to 132.2 million pounds in August while manufacturers’ stocks fell 7.1% from July and 3.6% from a year earlier, to 216.3 million pounds. Output up, inventory down: that is the tighter-market reading, and it holds.
Skim milk powder production, though, fell 33.1% on the year. USDA counts NFDM and SMP separately; USDEC’s export category combines them. Read either one without the other and you get the wrong number.
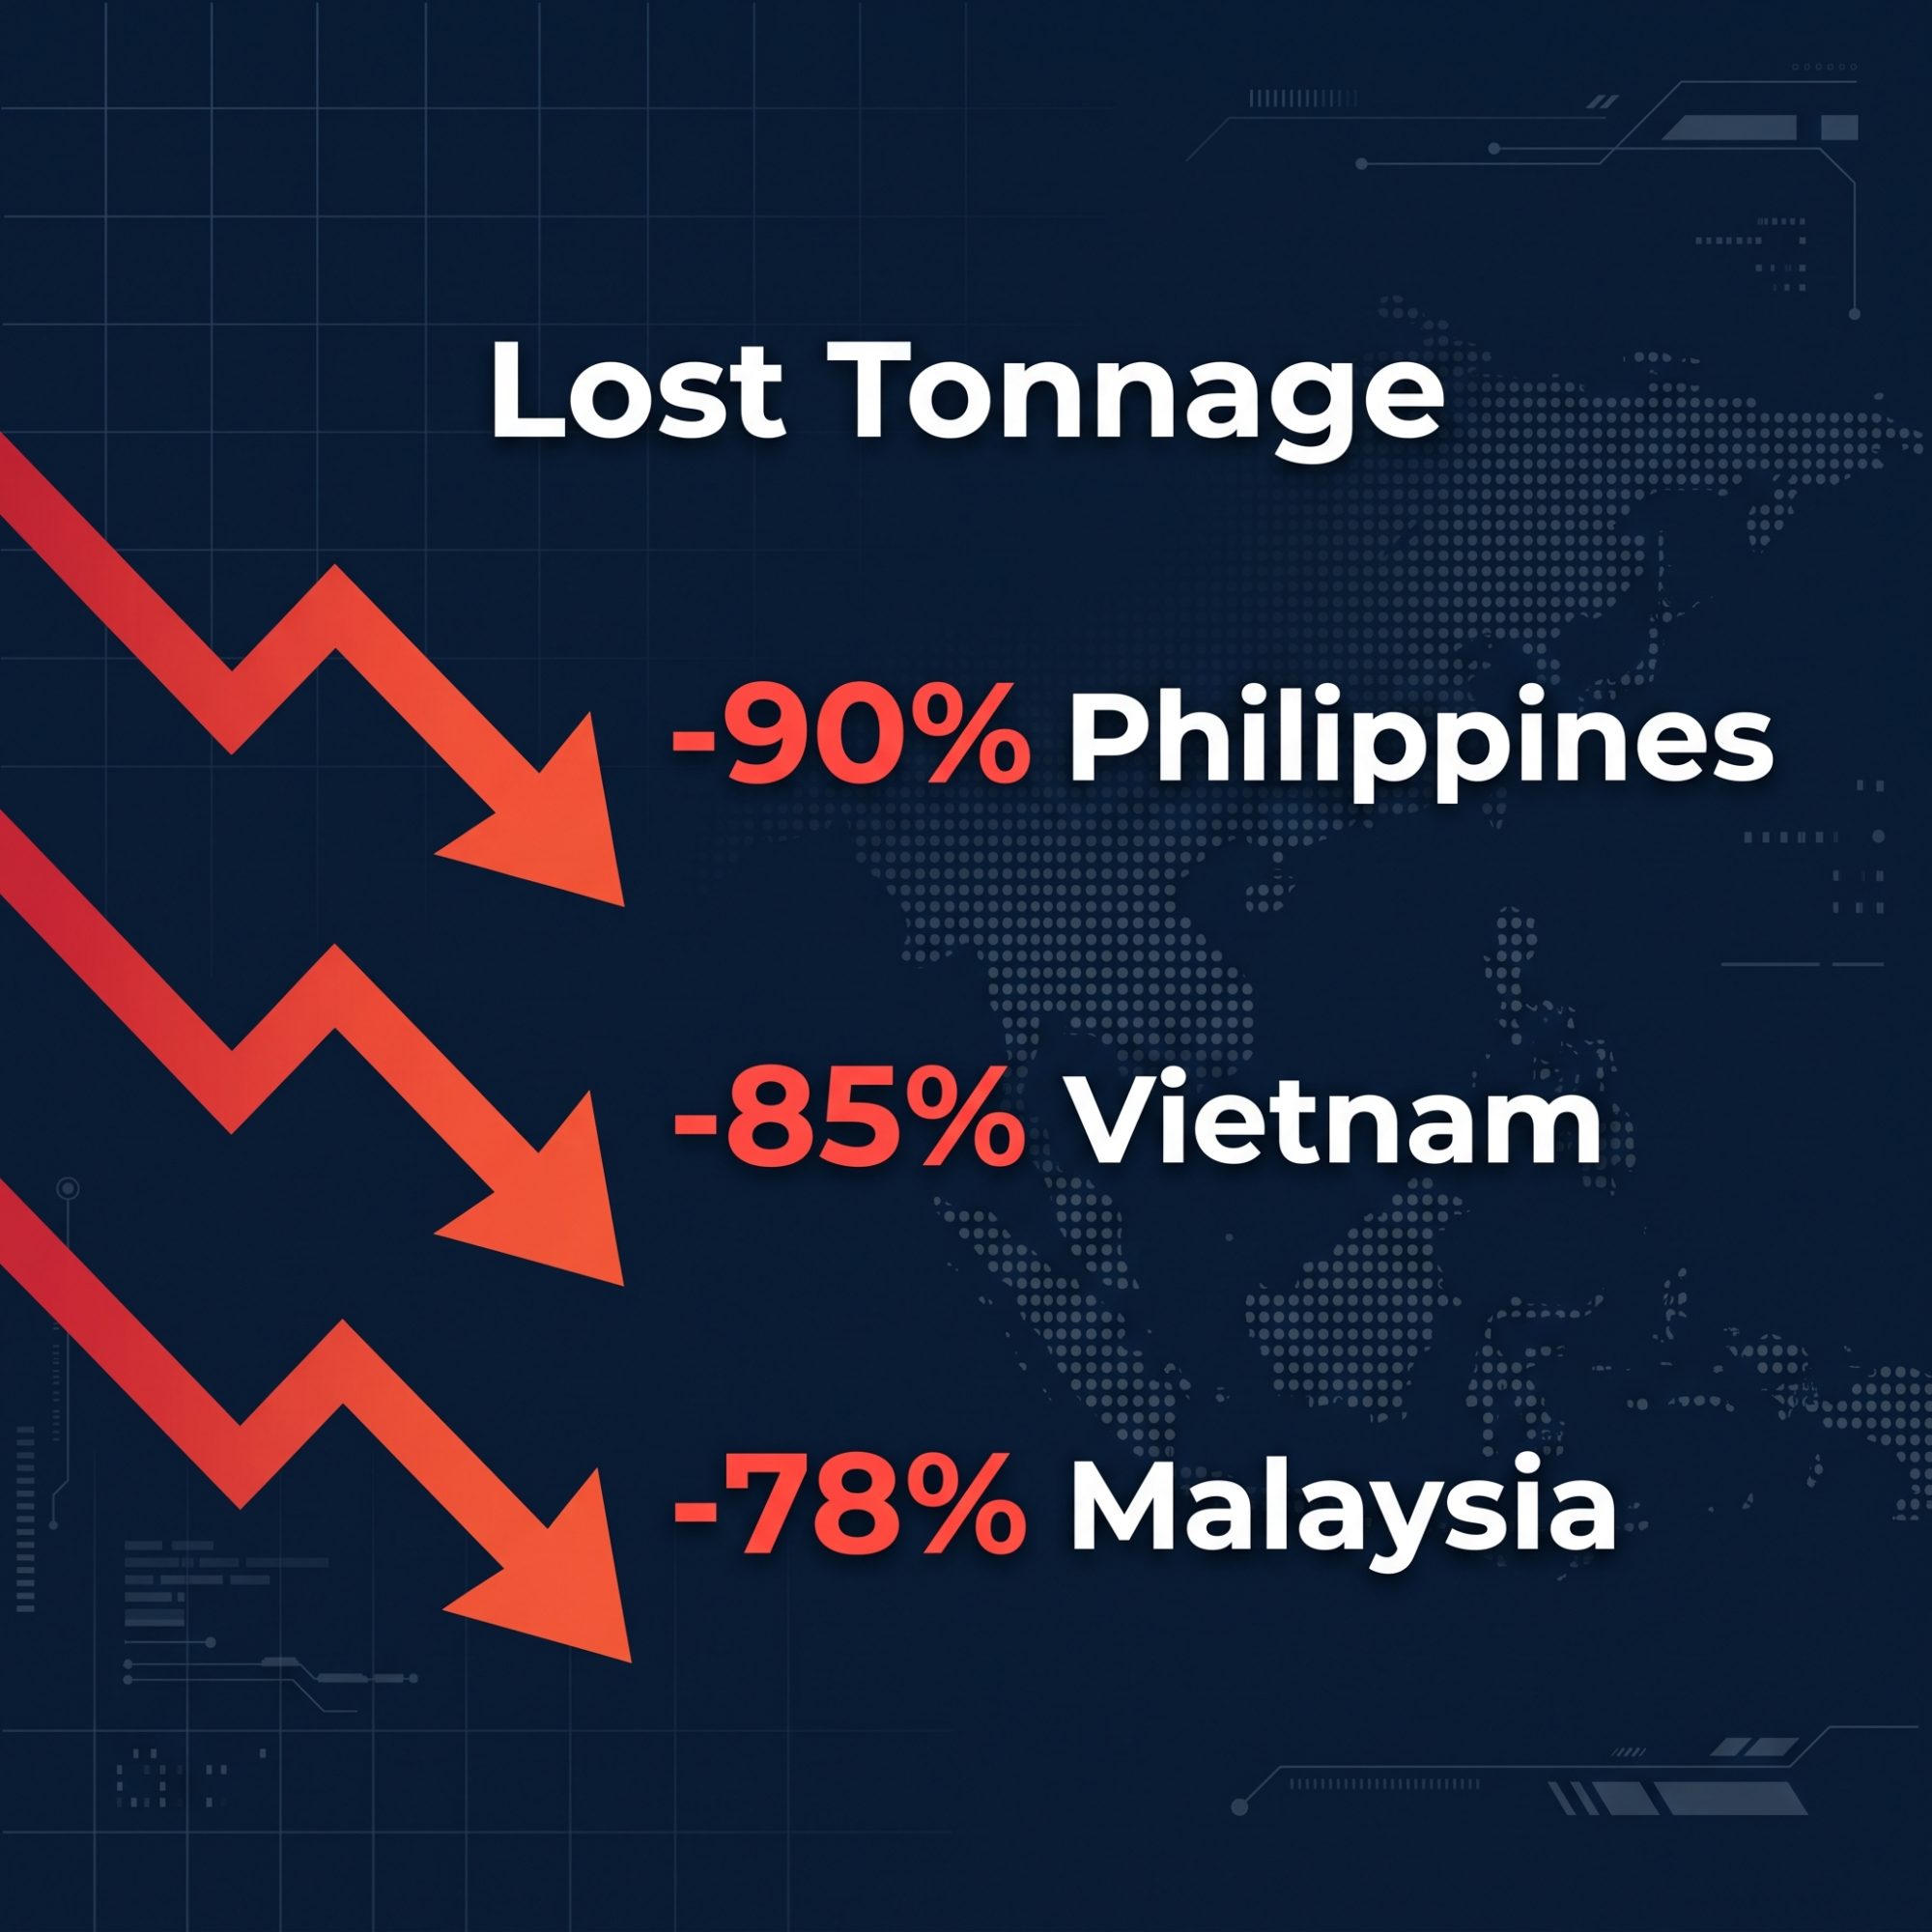
USDEC put August NFDM/SMP exports down 19%, blaming limited exportable supply and high U.S. prices. Southeast Asian buyers went to New Zealand and the EU instead. U.S. shipments to the Philippines fell 90%, Vietnam 85%, Malaysia 78%.
Tight inventory at home and lost tonnage abroad can run together for months. The 90% drop to the Philippines is the number to carry into the next export release, because it shows up in the price only after the business is already gone.
What reaches the milk check
The 71.98¢ is USDA’s October 15 National Dairy Products Sales Report, week ending October 10. The 89.50¢ is CME’s October 19 cash close. Different markets, different weeks. Neither a same-day discount nor a catch-up payment owed.
Federal-order component prices use weighted product prices from four or five weeks of USDA’s sales survey, not the latest CME close. Dry whey sets the other-solids price. The Class III protein formula uses cheddar cheese prices and a butterfat adjustment; it does not directly use whey-protein ingredient prices. A run in whey protein ingredient prices does not land on the protein line of a federal-order milk statement.
Bullvine’s whey-to-check test
USDA’s other-solids formula subtracts a 26.68-cent make allowance from the surveyed dry-whey price and applies a 1.03 yield factor. Standardized Class III carries 6.0 pounds of other solids per hundredweight of skim and a 0.965 skim-to-milk conversion.
The table below is Bullvine’s calculation on those USDA factors, with cheese and butter inputs held still. Low, central and high are reference cases, not probabilities, and none of them is an announced price.
Documented reference
Whey price (¢/lb)
Calculated other-solids price ($/lb)
Other-solids contribution to standardized Class III ($/cwt)
USDA survey: week ending Sept. 12, 2026
66.21
$0.4072
$2.36
USDA survey: week ending Oct. 3, 2026
68.14
$0.4270
$2.47
USDA survey: week ending Oct. 10, 2026
71.98
$0.4666
$2.70
CME spot illustration: Oct. 19, 2026
89.50
$0.6470
$3.75
Subtract $0.2668 from the whey reference, multiply by 1.03, then by 6.0 and 0.965.
Central to high is $1.04/cwt with everything else frozen. On an assumed 10,000 cwt a month, one-for-one exposure is about $10,448. The high case only enters the regulated calculation if prices like it show up in the monthly USDA survey. A CME close on its own does not get there.
Butter and cheese still matter
Butter output ran 6.3% above a year earlier in August; total cheese was up 1.4%. In the same October 15 sales report that moved whey and NFDM higher, surveyed butter and cheddar fell on the week.
Class III still prices protein off cheese and carries butterfat; Class IV carries nonfat solids and butterfat. With 6.3% more butter in the system, a whey rally lifts one line on the statement and leaves the others to their own markets. In the latest weekly survey, stronger whey coincided with weaker butter and cheddar prices. The overall Class III result depends on all those inputs.
What this means for your operation
Isolate spot prices in your budget. Any line built on 89.5¢ whey is a spot-reference scenario. The surveyed price is the one already in the monthly formula.
Stress-test your exposure. It is a stress test, not an expected gain. Ask the buyer how class utilization, component tests and payment terms change it at your farm, and whether their forecast already includes stronger whey. If it does, adding $1.04 counts it twice.
Check your break-even reality. If scheduled costs only clear under the high case, the operation is running on a price the survey has not recorded yet.
Date the reference points. August’s 61.3 million pounds of dry whey stocks, 216.3 million pounds of NFDM stocks and 25% low-protein whey export growth are the numbers to check against the next USDA and USDEC releases.
The full $1.04/cwt illustration requires a monthly weighted whey price of 89.5¢. Before budgeting that upside, establish how much is already in the buyer’s forecast and how any additional change would reach your check.
Whey Gap Stress-Test Calculator
Calculate your farm’s exact financial exposure to the spread between CME spot whey prices and USDA surveyed prices.
Financial Exposure Analysis
Class III CWT Impact
$0.00/cwt
Total Phantom Revenue Exposure
$0.00
Learn More
Understanding Your Milk Check: Class III vs. Class IV — Isolate the exact mechanics separating cheese from butterfat pricing on your monthly statement. Pinpoint where your revenue actually originates to adjust short-term feed rations, deliberately targeting the components paying the highest premiums on today’s grid.
FMMO Reform: What the Proposed Changes Mean for Your Bottom Line — Map your long-term margin projections against upcoming Federal Milk Marketing Order updates. Track how impending make-allowance shifts threaten to permanently restructure regional milk values, giving you time to manage debt or secure contracts before the new math takes effect.
Dairy Revenue Protection: Is It Right for Your Operation? — Secure record CME highs before the USDA survey even registers them. Deploy Dairy Revenue Protection and forward-contracting instruments to construct a concrete floor under your operation’s cash flow, completely detaching your survival from lagging federal formulas.
The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
Twelve companies reported 8.2 million pounds of dry whey last week. That survey — not the CME — sets your other-solids line. Eight Canadian lines close Sept. 29. Our floor case: 11.9¢/cwt.
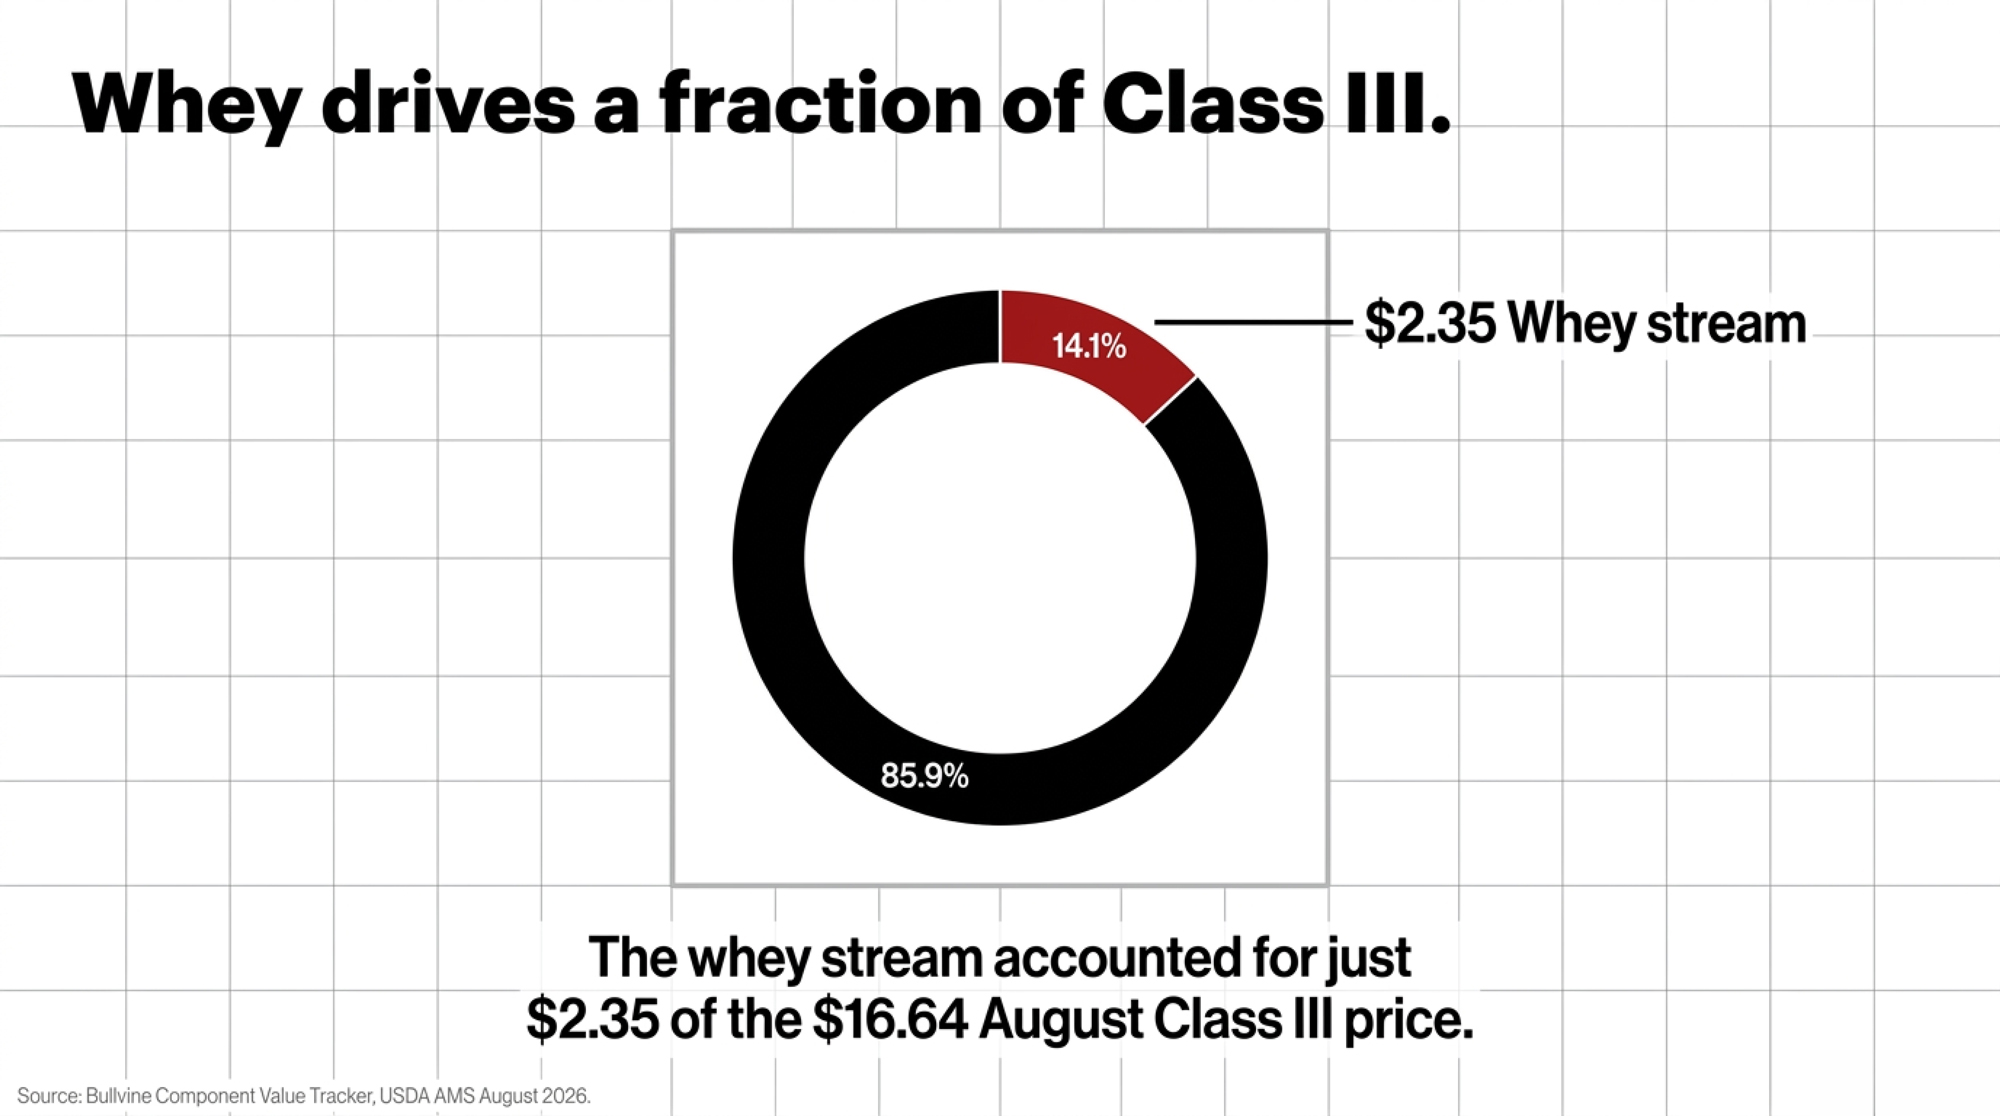
The Canada whey import ban 2026 excludes eight Canadian whey and modified-whey HTSUS lines under Proclamation 11062, effective 12:01 a.m. Eastern on September 29, closing a channel that carried $35.04 million in 2025. USDA’s formula moves Class III 5.96 cents for every penny of dry whey, and Bullvine’s Component Value Tracker isolates the whey stream at $2.35 of the $16.64 August Class III price — 14.1%. Across three substitution cases, the Q4 range runs 11.9 to 59.6 cents per hundredweight, $2,802 to $14,014 on a 400-cow model. Herds in the four skim-fat orders have no other-solids line to read. Substitution behavior remains unmodeled.
Eight tariff lines, $35.04 million of 2025 trade, one USDA survey covering 8.2 million pounds a week across twelve reporting companies. That’s the whole path from the Oval Office to your milk check.
President Trump signed Proclamation 11062 on September 8, 2026. The Office of the Federal Register published it on September 14 as FR Doc. 2026-18836, Volume 91, Number 176, pages 58319–58323. It excludes certain Canadian products from importation into the United States, effective for goods imported on or after 12:01 a.m. Eastern Time on September 29, 2026.
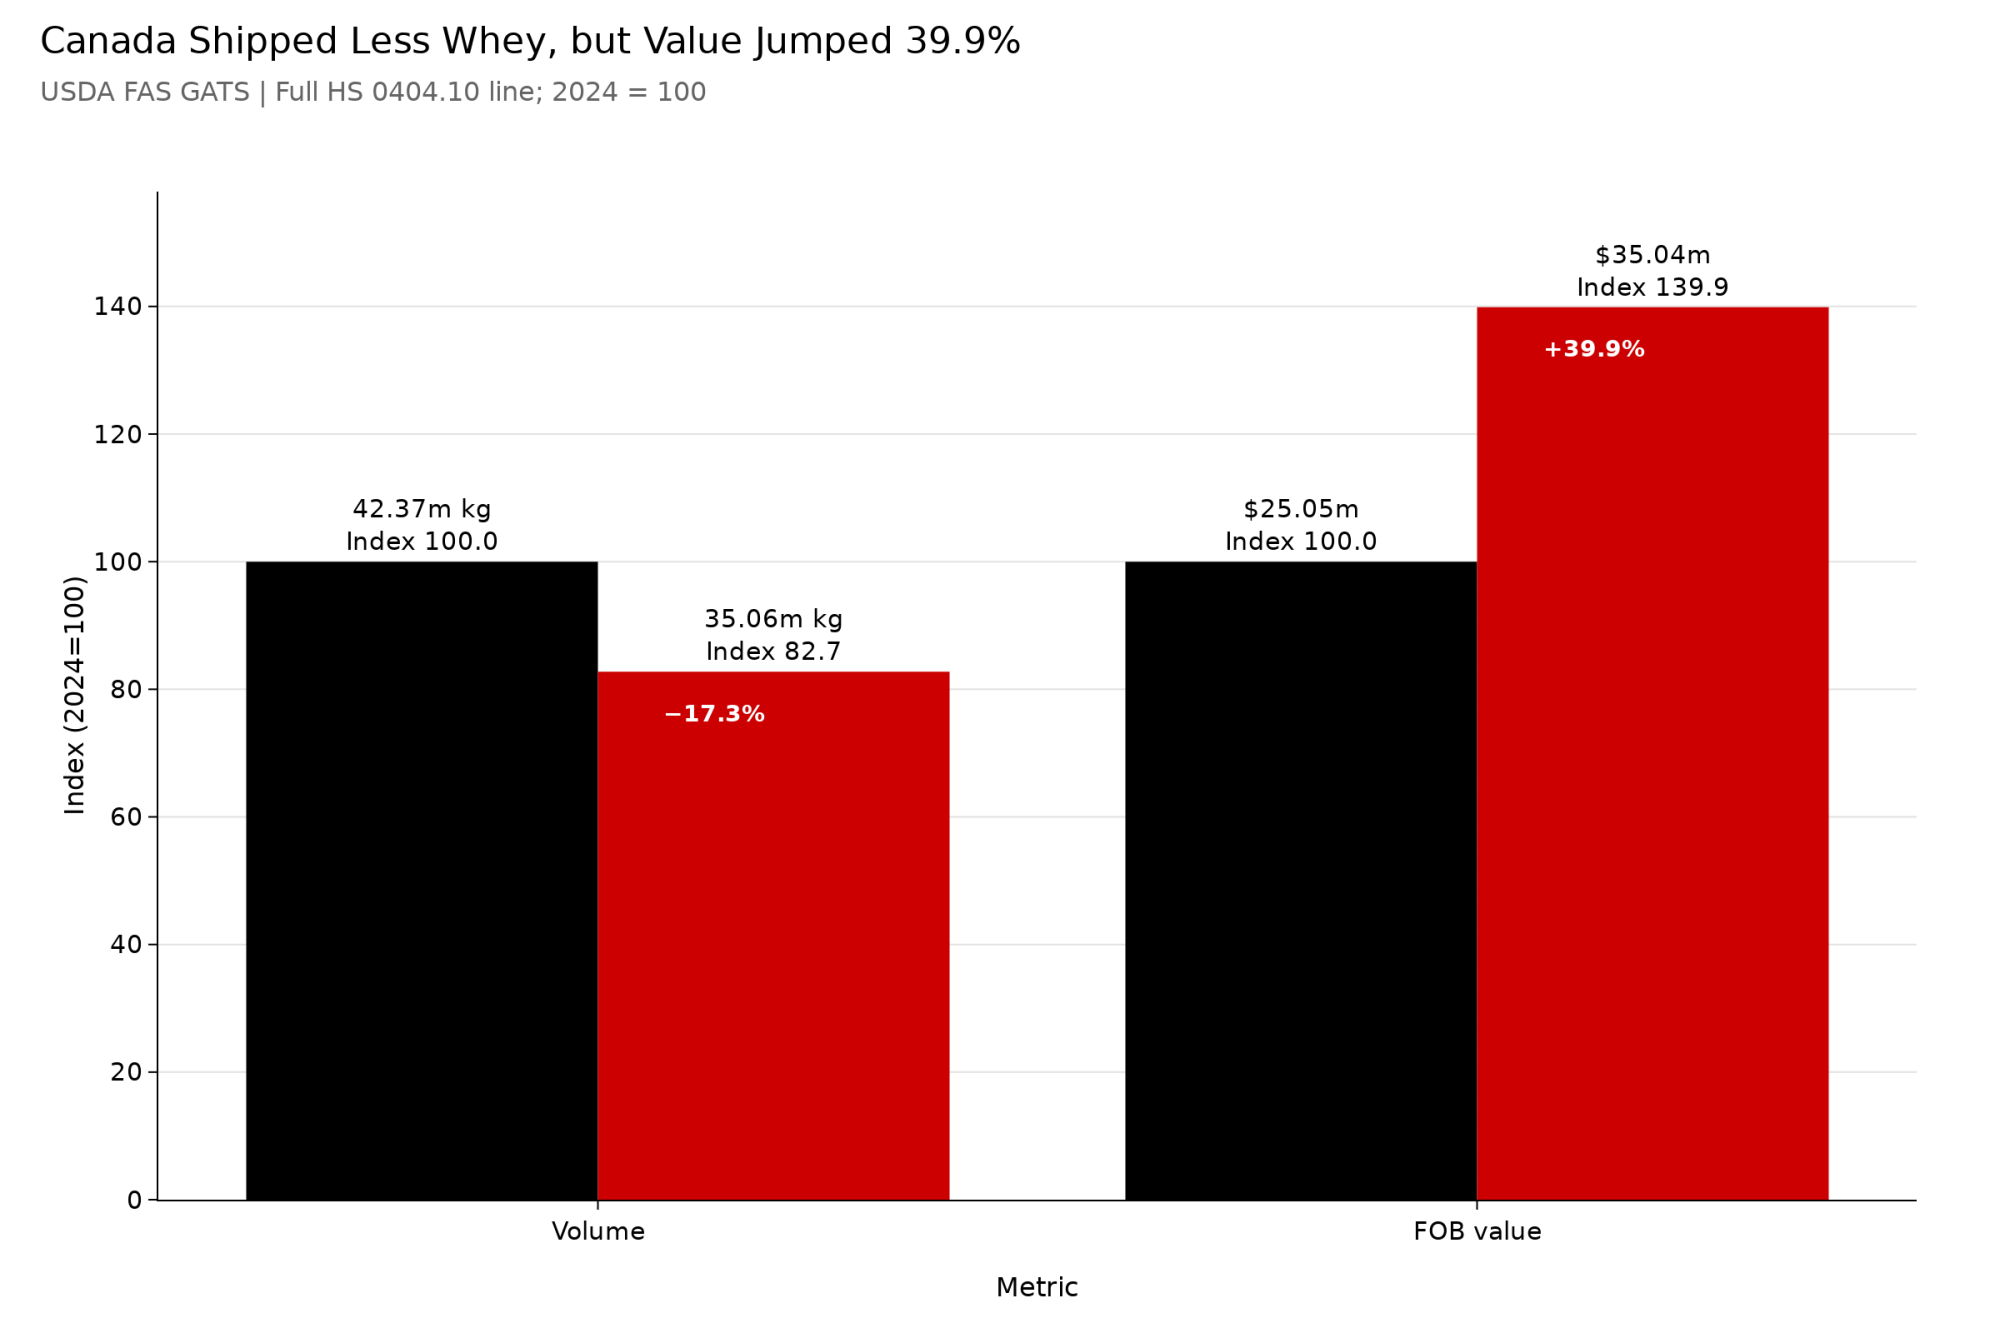
This is the first U.S. dairy action this cycle aimed at one component stream rather than a duty rate. Canada shipped $35.04 million FOB of HS 0404.10 whey and modified whey to the United States in calendar 2025, on 35.06 million kilograms, per USDA Foreign Agricultural Service GATS, which sources U.S. import records from the U.S. Census Bureau. The 2024 comparison was $25.05 million on 42.37 million kilograms, so value rose $9.99 million, or 39.9%, while volume fell 7.31 million kilograms, or 17.3%.
That $35.04 million covers the full HS 0404.10 line. The prohibition covers eight eight-digit classifications inside it, so the excluded subtotal is a portion of that figure rather than all of it.
The document sets no whey price, names no processor, and obliges nobody to pass a cent to a farm.
What does the Canada whey import ban 2026 actually cover?
Annex I lists HTSUS 0404.10.05 (whey protein concentrates), 0404.10.08, 0404.10.11 and 0404.10.15 (modified whey), 0404.10.20 (fluid whey), and 0404.10.48, 0404.10.50 and 0404.10.90 (dried whey). Certain invert and cane molasses ride in the same proclamation, along with non-alcoholic beer under HTSUS 2202.91.00, and neither is a dairy line.
Whey protein isolate normally entering under HTSUS heading 3502.20 is not listed. The U.S. Dairy Export Council, the export promotion body funded through Dairy Management Inc., told the U.S. International Trade Commission in Section 332 prehearing testimony dated July 15, 2025 that HS 0404.10 generally captures dry whey, permeates, and lower-protein concentrates, while high-protein products commonly classify under 3502.20. Check the annex against what your plant competes with before assuming coverage.
The chronology matters for anyone holding Canadian product. Proclamation 11047 of July 20, 2026 imposed additional 50% ad valorem duties on certain Canadian dairy products effective August 19. Proclamation 11056 of August 18 suspended the duties for three days after Canada expressed a commitment to remove the measures at issue. Proclamation 11062 recites that Canada reneged on that commitment on August 21. The suspension lapsed at 12:01 a.m. Eastern on August 22, and the duties took effect.
Proclamation 11062 builds on that duty rather than replacing it. Paragraph 2 provides that products subject to the ban which were imported but not yet entered for consumption, or withdrawn from warehouse for consumption, before September 29 remain subject to the 50% duty rate established by Proclamation 11047.
There is a companion document, and it’s the one to read if you buy Canadian inputs. Paragraph 3 of Proclamation 11062 points to a separate Proclamation of September 8, 2026 — Modifying the Scope of Products of Canada Subject to the Additional Duties Imposed to Offset Canadian Discrimination Against the Commerce of the United States With Respect to Dairy. Two scope-modification proclamations were published in the same Federal Register issue, FR Docs 2026-18838 and 2026-18839, covering alcoholic beverages and motor vehicles; the second took effect at 12:01 a.m. Eastern on September 15. Bullvine did not locate the dairy scope proclamation in that issue. Until it surfaces, the annex setting which Canadian dairy inputs carry the 50% duty is a document nobody outside the administration has read.
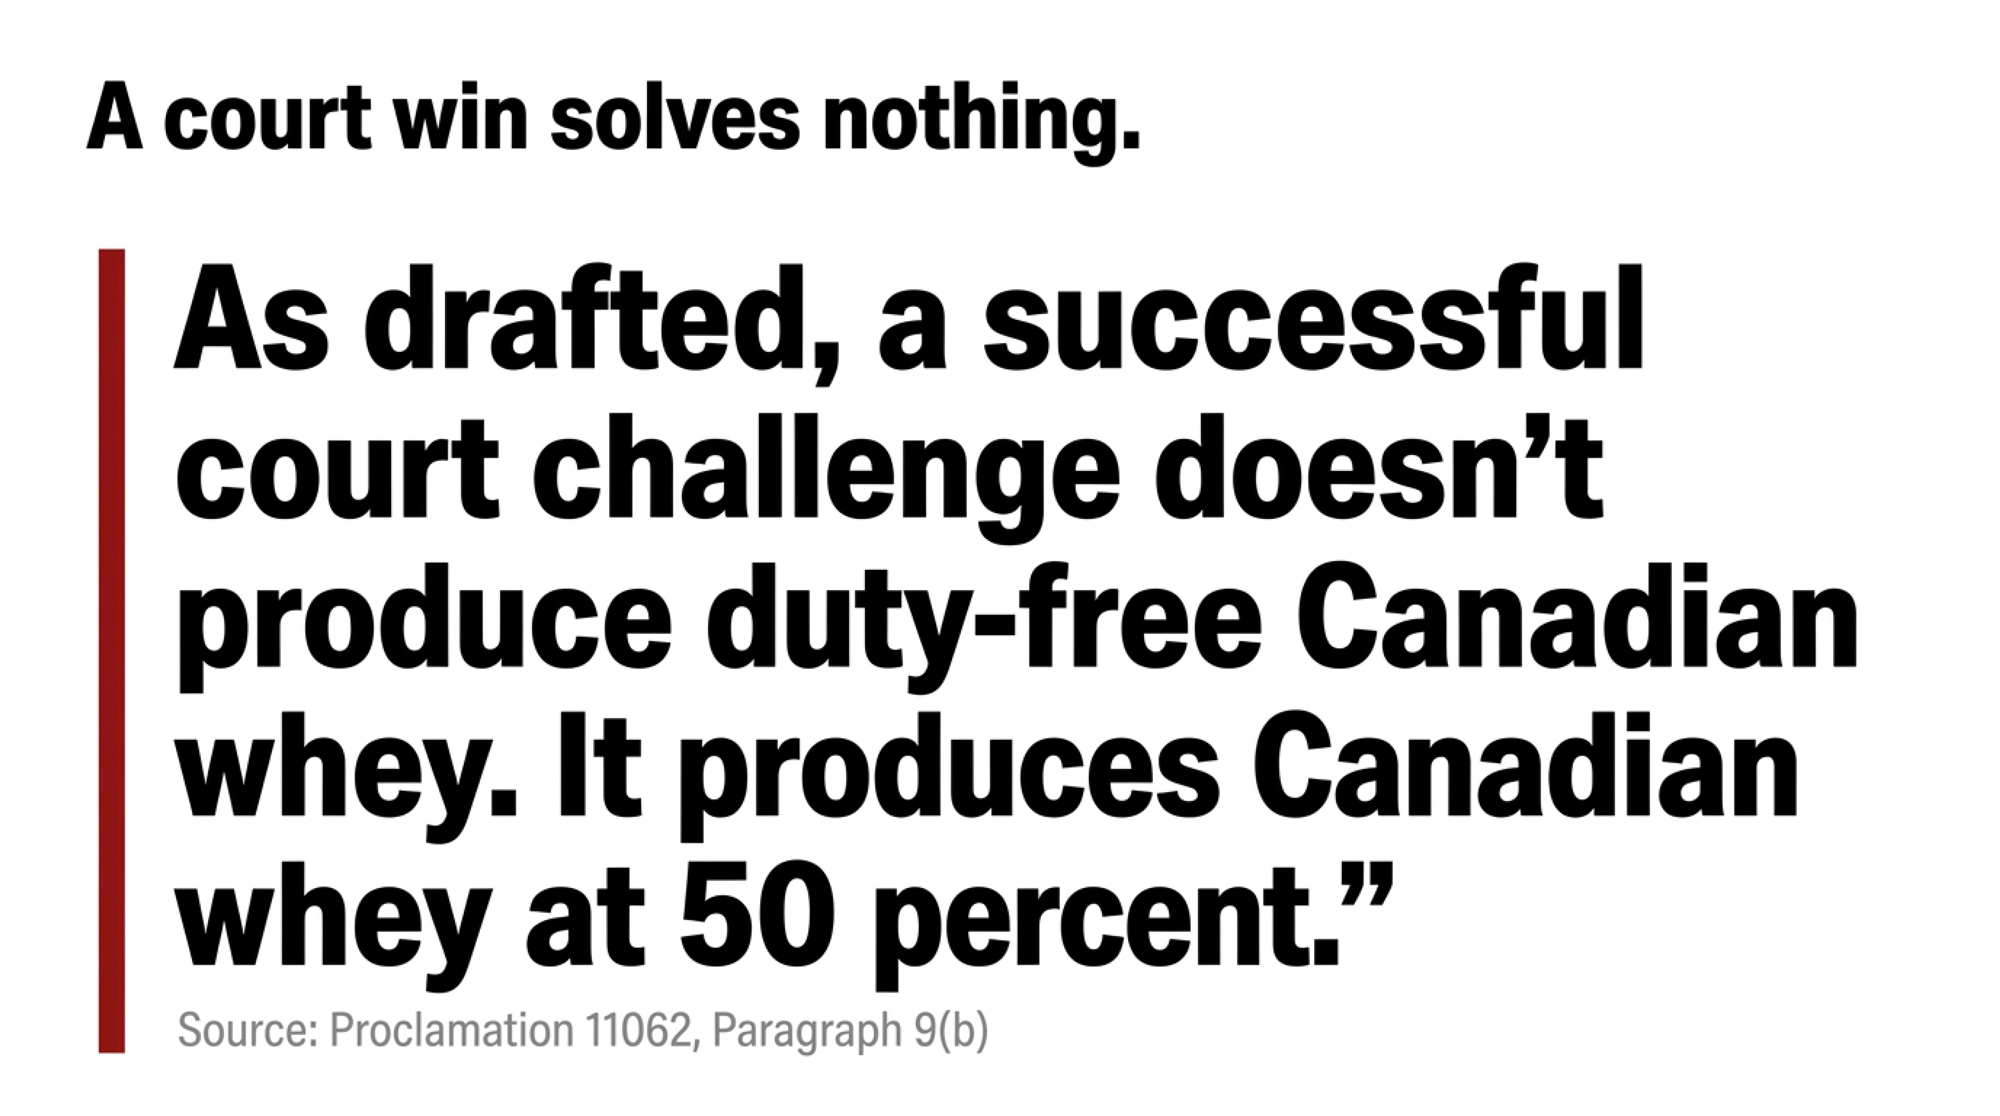
One clause deserves attention before anyone assumes litigation solves this. Paragraph 9(b) provides that if the import ban is invalidated in whole or in part as to any import, the 50% duty imposed in Proclamation 11047 applies to that import instead. As drafted, a successful court challenge doesn’t produce duty-free Canadian whey. It produces Canadian whey at 50%.
Paragraph 5 authorizes the CBP Commissioner, in consultation with Treasury, Commerce, and USTR, to issue rules and guidance. Paragraph 6 authorizes the Commissioner to make any technical or ministerial correction to the Annex through Federal Register notice so that the eight-line list can move. CBP issued CSMS #69851916 on September 11 covering the alcohol and motor vehicle scope changes. No CBP guidance specific to the dairy import ban had been located as of 1:30 p.m. Eastern Time on September 14, which leaves in-transit handling, foreign-trade-zone treatment, and entry mechanics open with 15 days to run. No legal challenge to the Section 338 dairy actions had been located as of the same check.
Which whey price actually lands in your milk check?
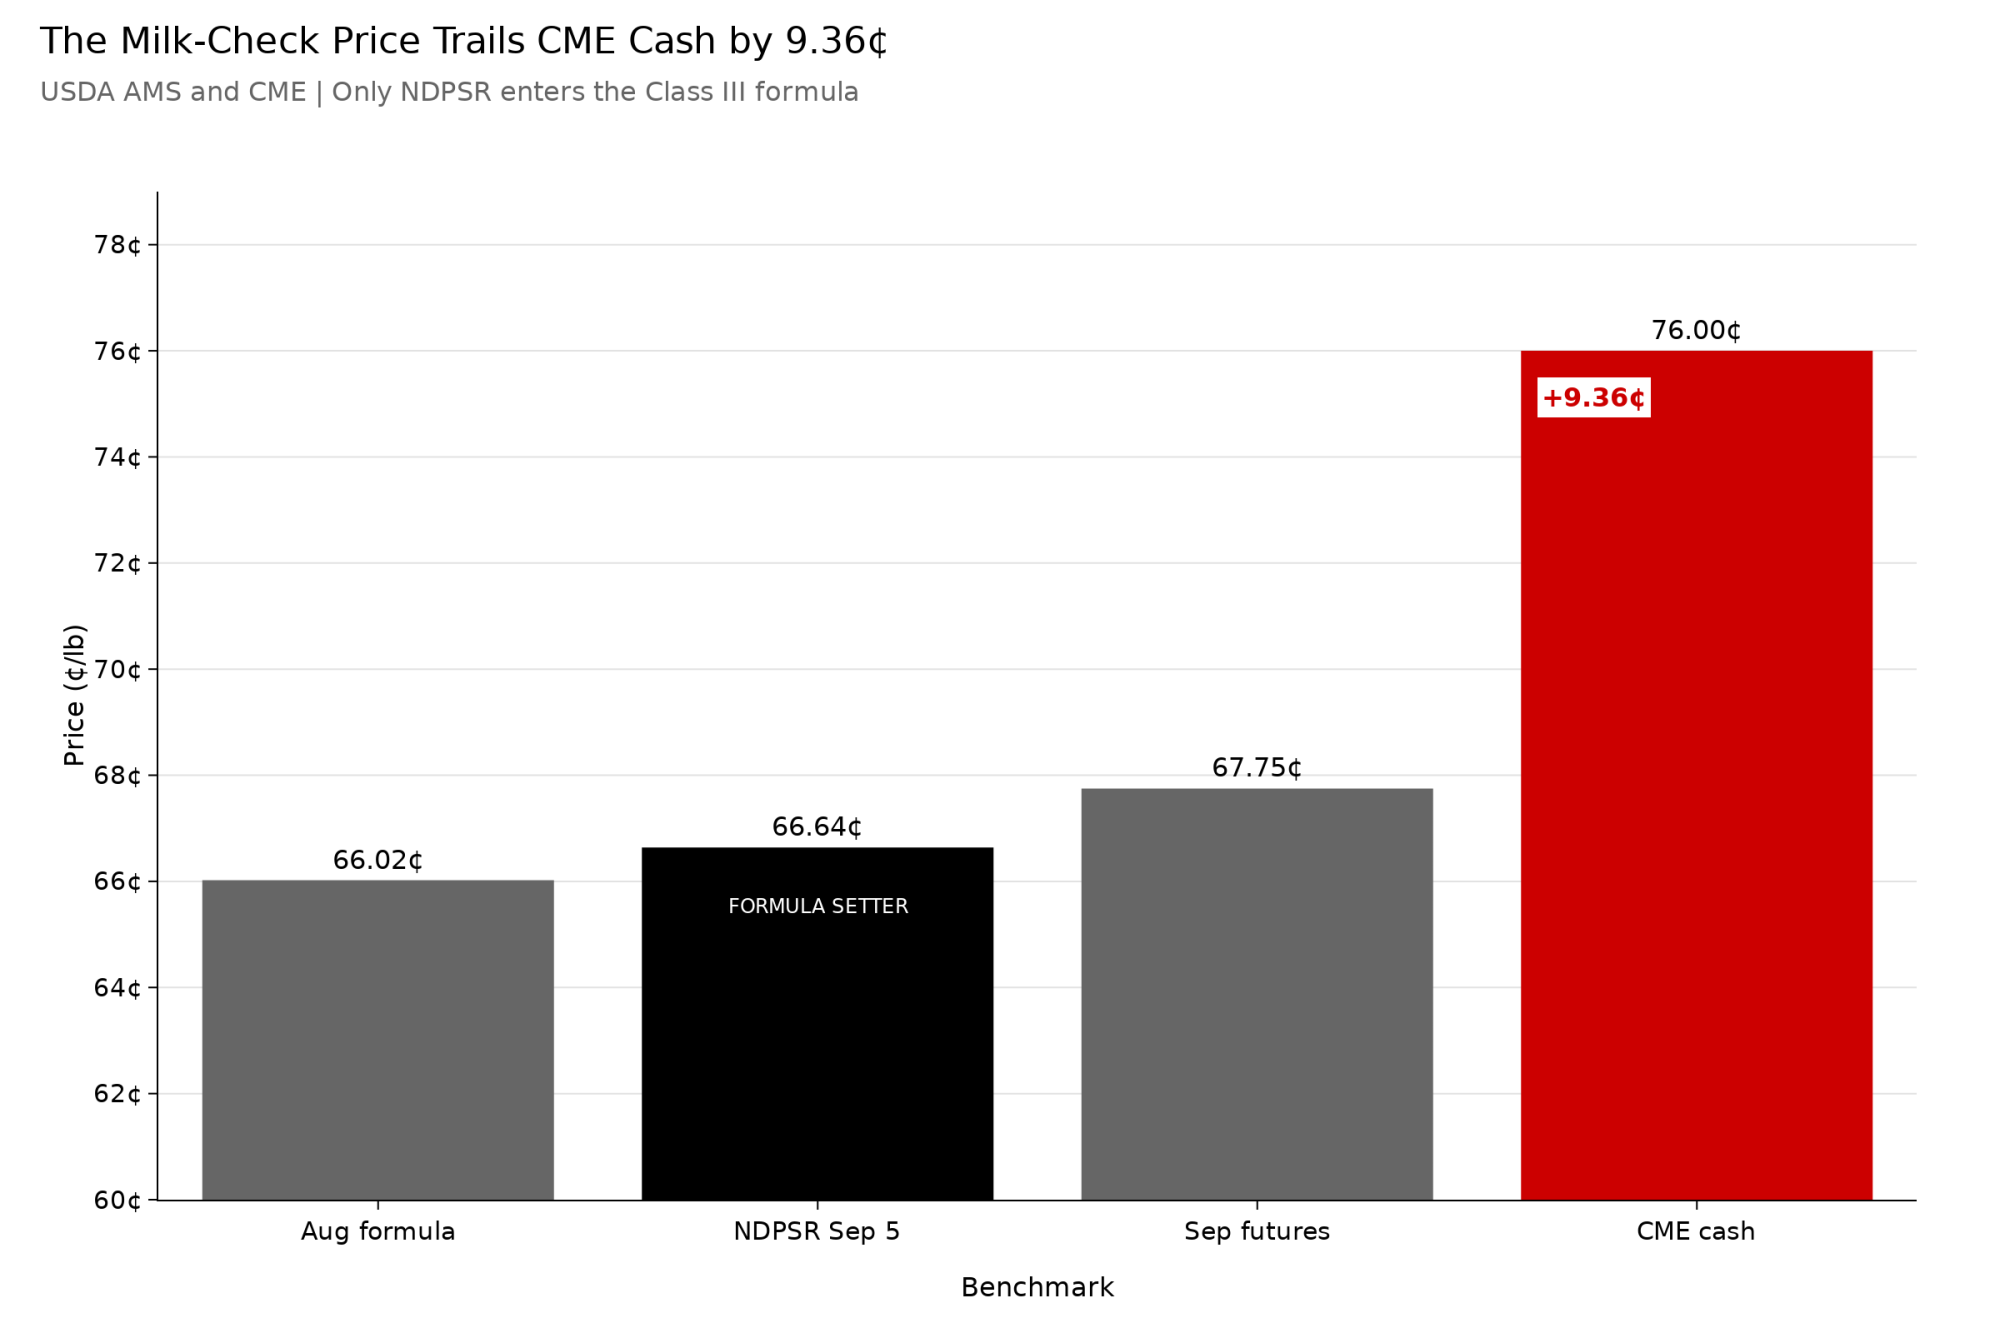
Three whey numbers printed in the same week, spread across more than nine cents. One of them touches the Class III formula.
Formula survey used directly in FMMO Class III pricing
CME dry whey futures, September contract, Sept 10, 2026 close
67.75¢/lb
Forward risk-transfer contract; not a settled class price
CME cash spot dry whey, Sept 11, 2026 close
76.00¢/lb
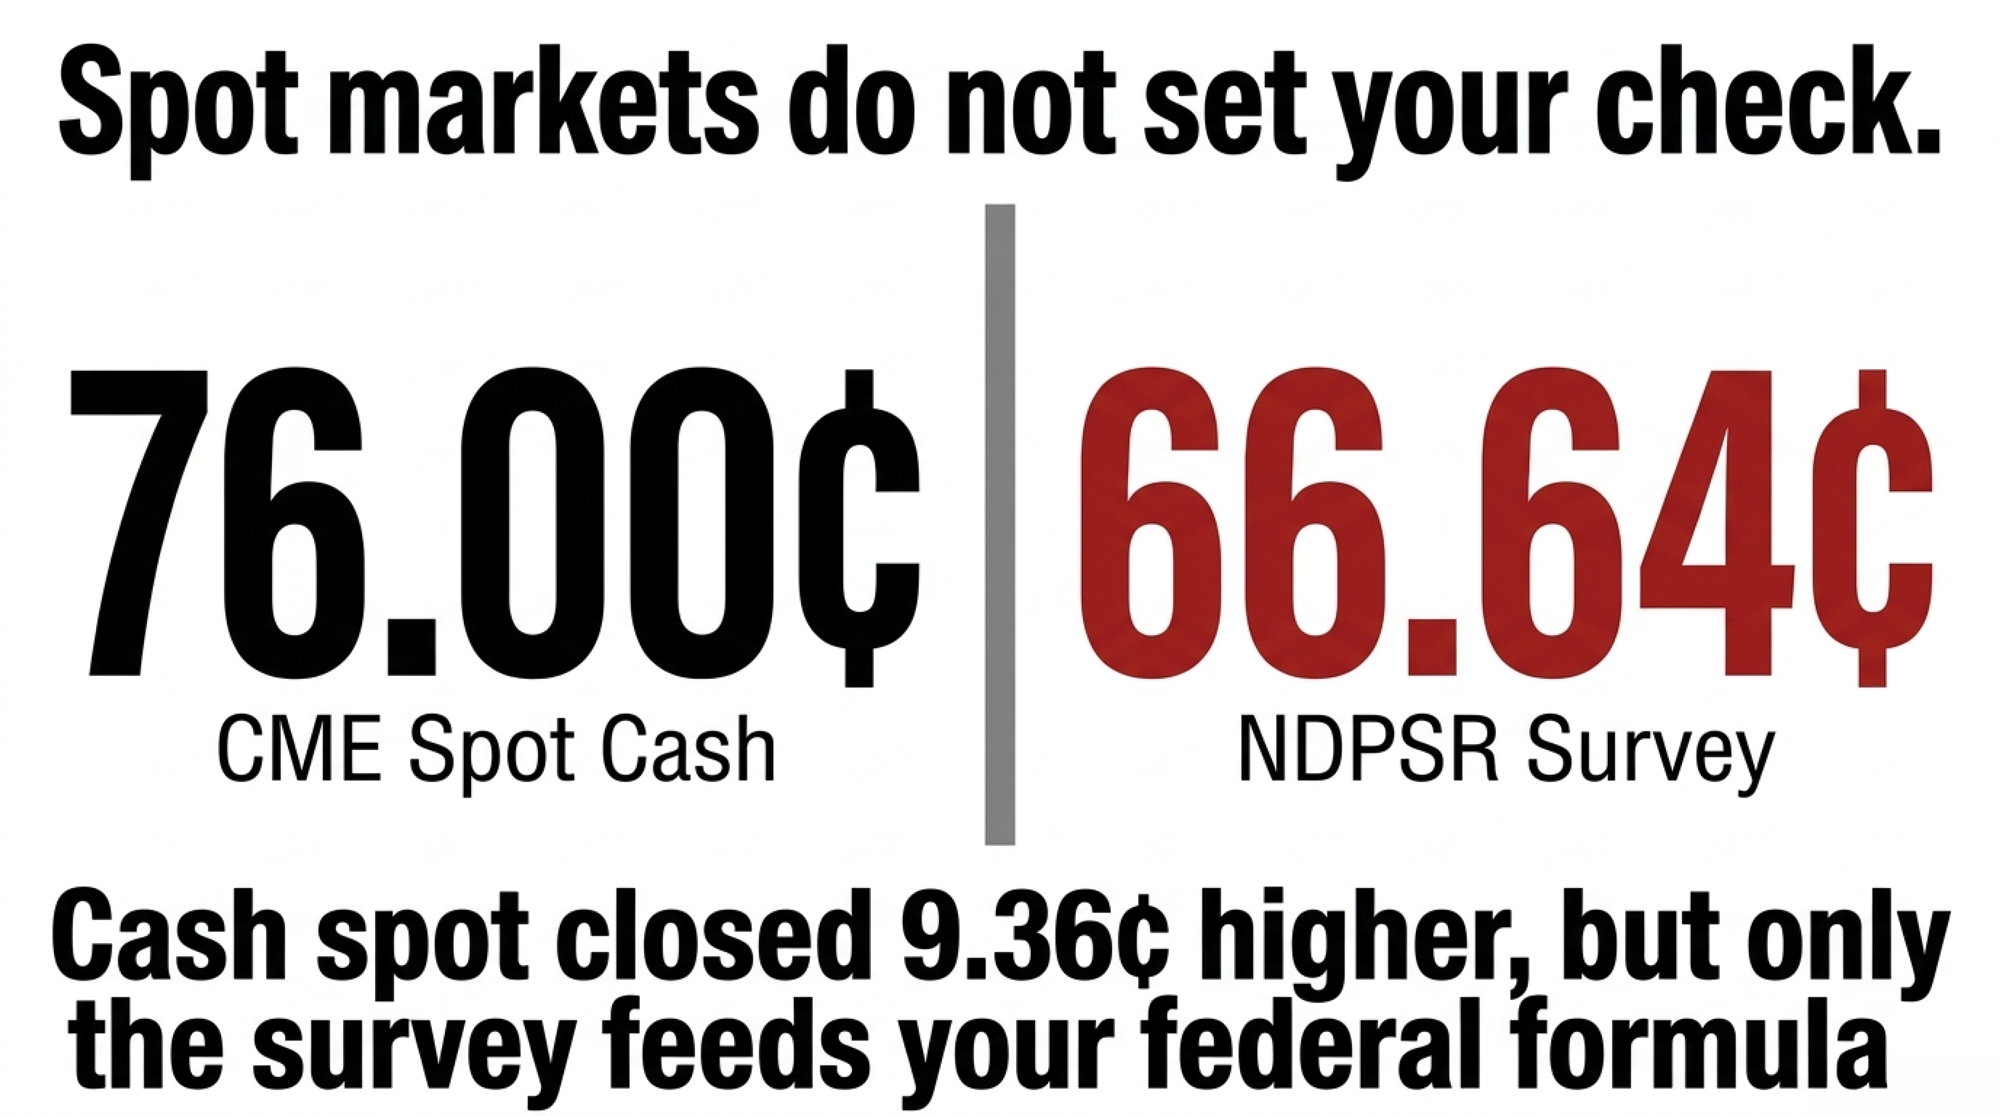
Spot cash exchange on light trading; 9.36¢ over NDPSR
Sources: USDA Agricultural Marketing Service, National Dairy Products Sales Report released September 10, 2026, U.S. national; USDA AMS Dairy Market News Weekly Report, Volume 93 Report 37, week of September 7–11, 2026.
USDA’s own market contacts flagged the gap. Central-region contacts told Dairy Market News that “while CME prices for dry whey have been trending higher, these movements are not reflective of broader market conditions.” Eastern contacts described CME spot trading as light. The cash market closed 9.36 cents above the survey that sets your other-solids price and 8.25 cents above the September futures contract.
The survey is narrow by design. USDA’s September 2 release recorded 12 entities reporting dry whey, and the September 10 release covered 8,220,923 pounds of qualifying Extra Grade sales for the week ending September 5. Manufacturers selling under 1 million pounds a year are exempt under 7 CFR Part 1170.
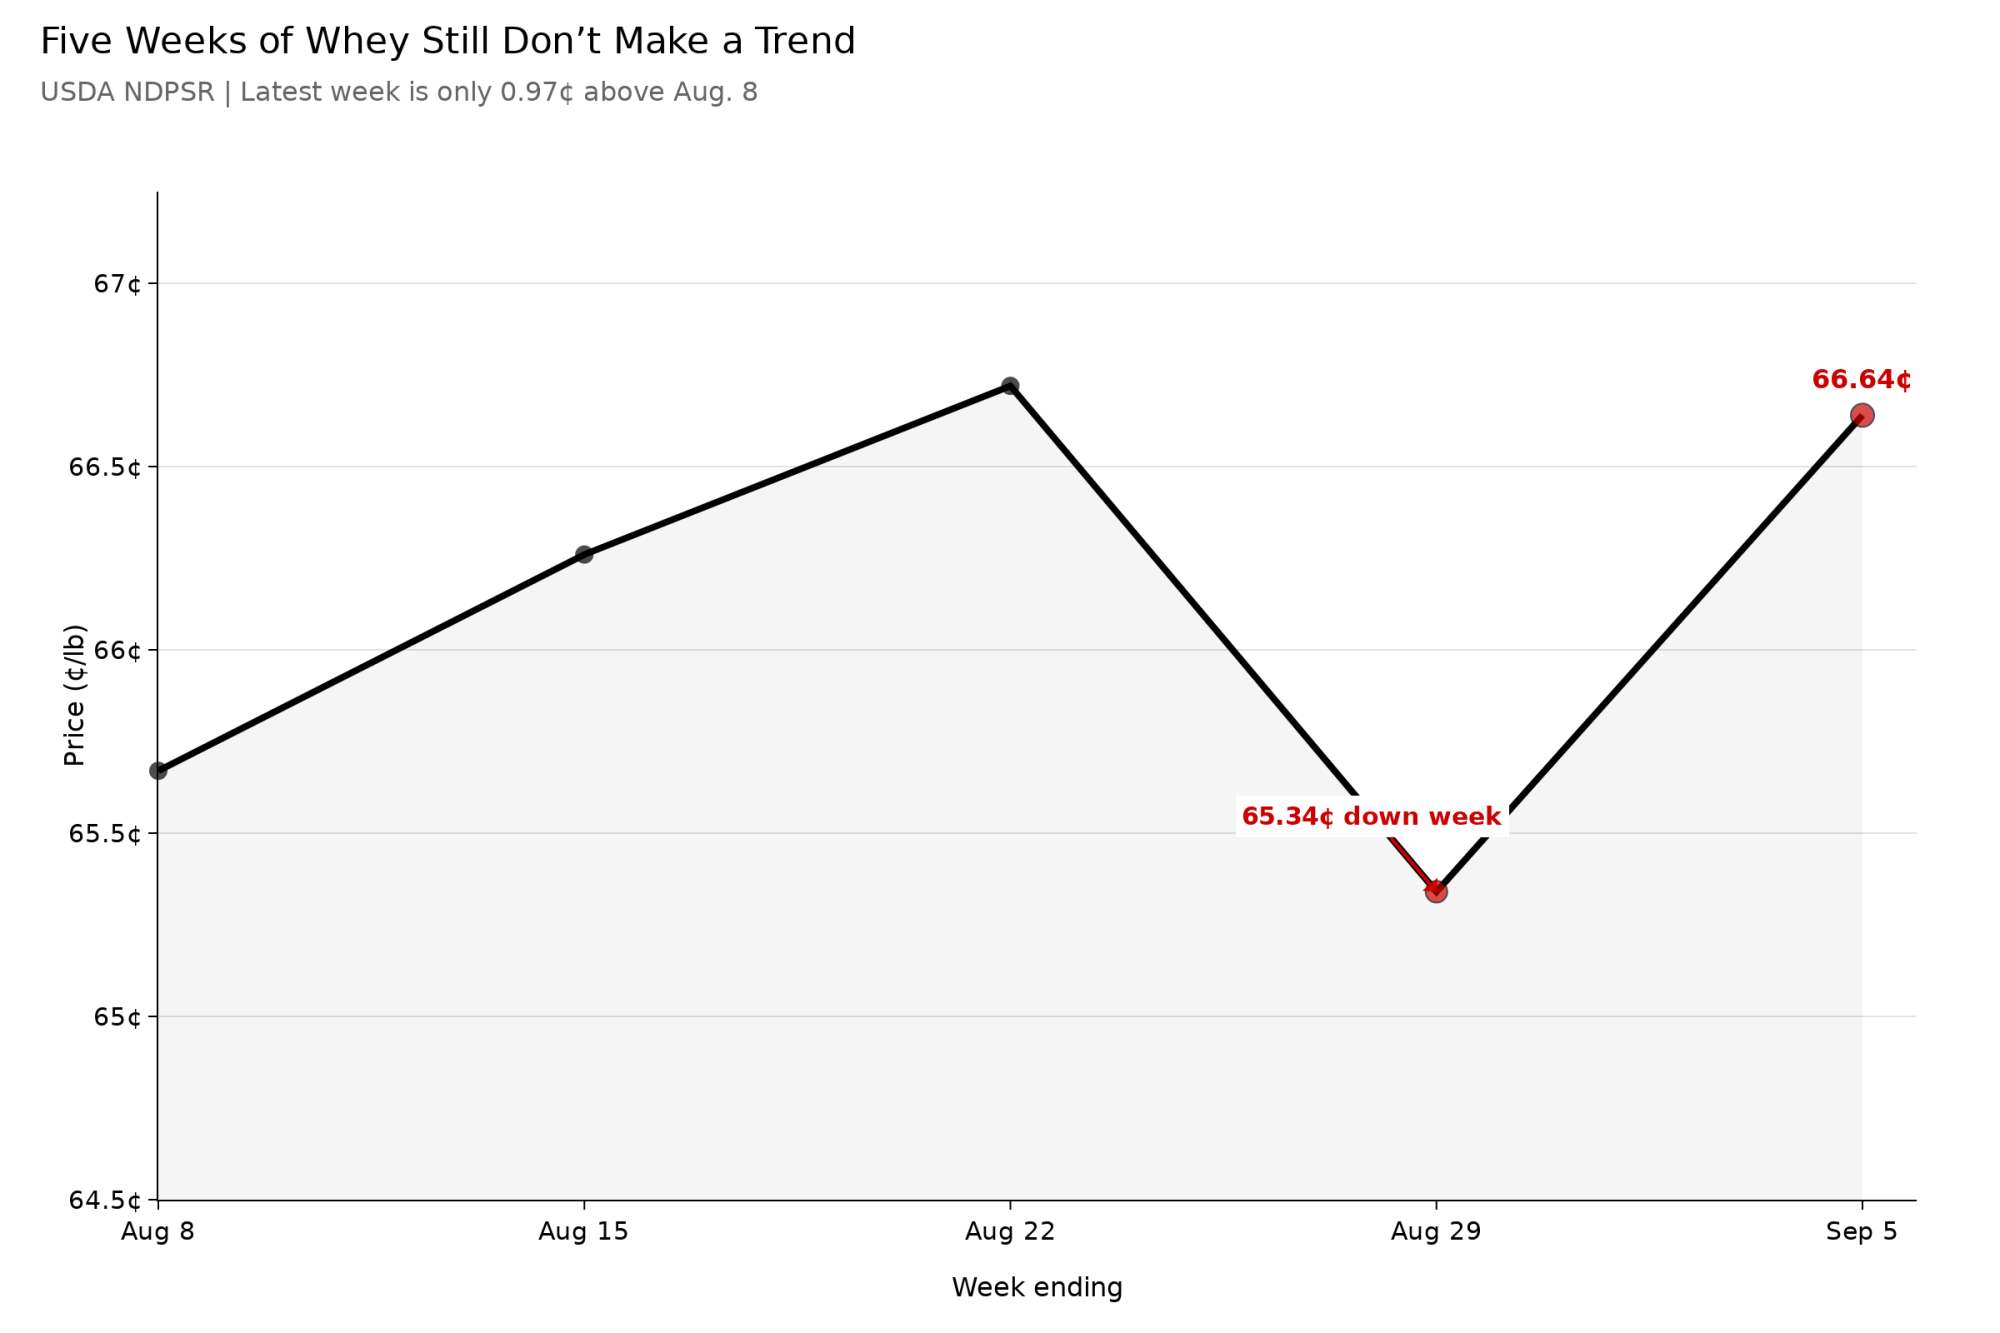
Five weeks of that survey read 65.67¢, 66.26¢, 66.72¢, 65.34¢ and 66.64¢. Up 0.97 cents, or 1.5%, with a down week inside it. Four consecutive moves in one direction make a trend, and this isn’t one.
Running the Numbers
Bullvine calculation — Component Value Tracker reading, whey stream inside Class III
Published evidence. USDA Agricultural Marketing Service announced August 2026 Class III at $16.64/cwt, dry whey at $0.6602/lb and other solids at $0.4052/lb for the U.S. Federal Milk Marketing Orders. The formula is Other Solids Price = (Dry Whey − 0.2668) × 1.03, with 6.0 pounds of other solids in the Class III skim value and a 0.965 conversion.
Bullvine math — the whey stream’s share of the August price:
(0.6602 − 0.2668) × 1.03 × 6.0 × 0.965 = $2.35/cwt, which is 14.1% of $16.64.
Bullvine math — the sensitivity:
1¢/lb on dry whey × 1.03 × 6.0 × 0.965 = 5.96¢/cwt on Class III, cheese and butterfat held constant.
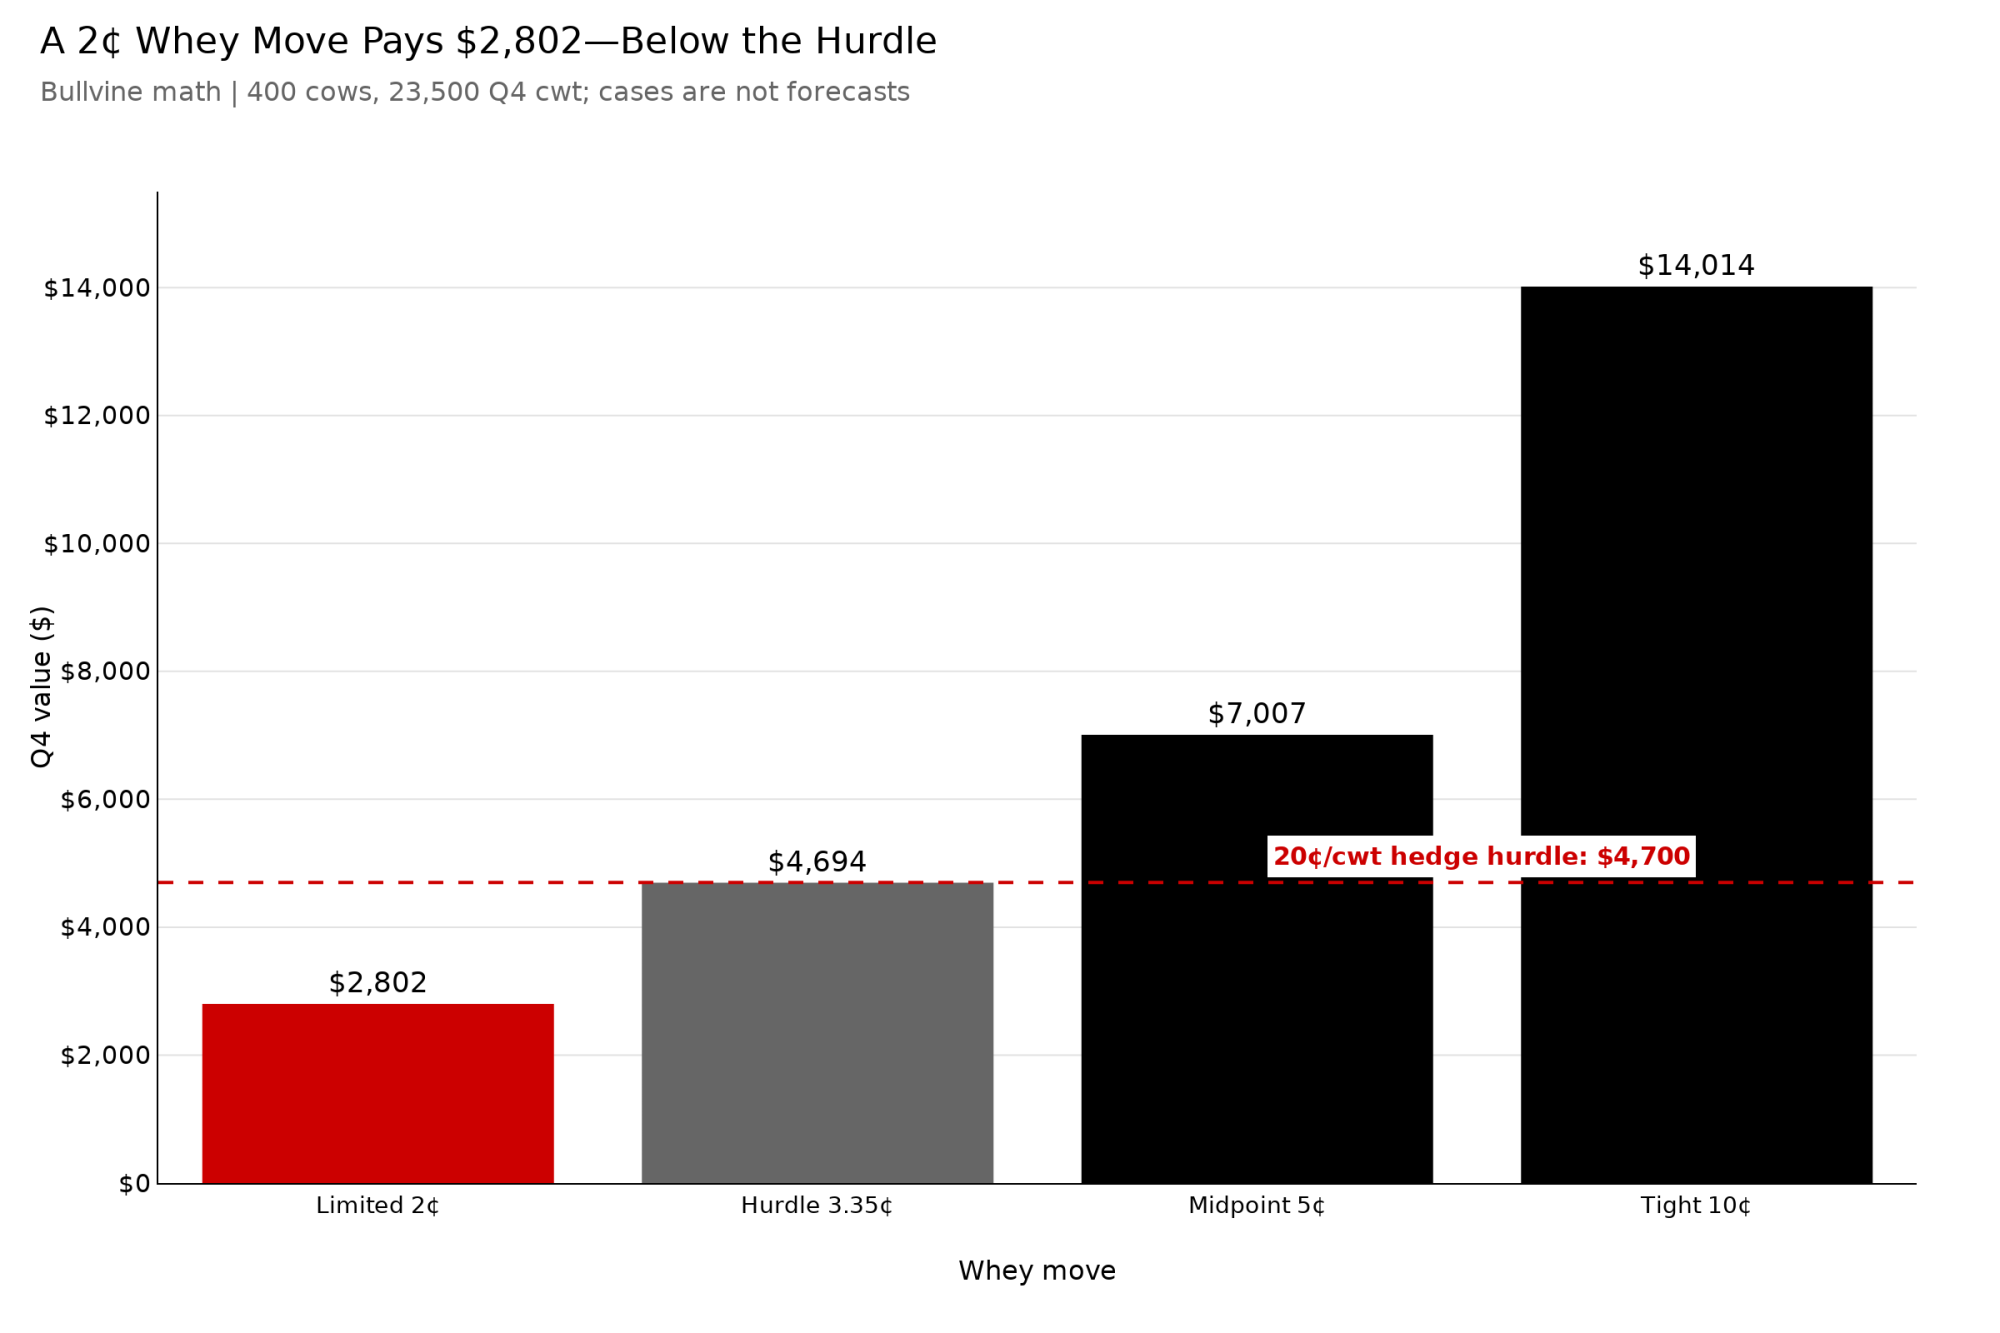
Stated assumptions. Three cases. The replacement shares and the price moves are Bullvine stress assumptions, not forecasts, and every dollar figure is rounded down.
Scenario
Canadian supply replaced
Dry whey move
Class III impact
Q4 gross value, 400-cow model
Limited transmission
75% from other origins or stocks
+2¢/lb
+$0.119/cwt
+$2,802
Midpoint sensitivity
50% replaced
+5¢/lb
+$0.298/cwt
+$7,007
Tight substitution
25% replaced, severe deficit
+10¢/lb
+$0.596/cwt
+$14,014
Scope. 400 cows, 235 cwt shipped per cow per year, Q4 volume 400 × 235 ÷ 4 = 23,500 cwt, USD, U.S. national formula basis. Gross Class III-equivalent value before PPD, basis, utilization, over-order premiums, hauling, and contract pass-through.
Who actually captures it? Seven federal orders use multiple-component pricing and four use skim-fat pricing. In a skim-fat order, there’s no other-solids line on your statement to read, because the whey value arrives inside the skim price, and you’ll need the plant to show you where it went. A herd already locked into a fixed-price Q4 contract captures none of this, whatever the whey market does. On a leveraged balance sheet, $7,007 of Q4 upside is a covenant conversation rather than a windfall.
Methodology note 1 — the utilization disconnect
USDA reported Class III at 58% of all-market utilization for July 2026, on 12.8 billion pounds of federally pooled producer milk, with a weighted average statistical uniform price of $19.18/cwt.
The other 42% was pooled under Class I, II, and IV formulas, none of which carries an other-solids line. For those producers, the dry whey mover reaches the check through the pool and the uniform price rather than as a component payment.
Class I is the exception, and it doesn’t apply this month. The base Class I skim price takes the higher of the advanced Class III or Class IV skim pricing factor, and the Class III factor is built partly on other solids. For September 2026, USDA put the advanced Class III skim factor at $11.76, and the Class IV factor at $12.16, so Class IV is the mover and whey isn’t feeding Class I at all. Flip those two, and it does.
Methodology note 2 — the high-protein creaming effect
U.S. whey protein concentrate production at 25.0 to 89.9% protein ran 40.128 million pounds in July 2026, with manufacturer stocks of 45.198 million pounds, per USDA National Agricultural Statistics Service, Dairy Products, released September 3, 2026.
The problem is where that stream goes. Dairy Market News contacts in the East reported processors “directing whey streams toward higher-protein derivatives, particularly WPC 80%, keeping traditional dry whey output secondary,” while Western contacts said availability is not improving because of competition from higher-value whey products. Some production has shifted from WPC 80% toward whey protein isolate, and contacts expect more of that in Q4.
Look at the gap driving it. In the week of September 7–11, national ranges ran WPC 34% at $2.05 to $2.90 per pound, WPC 80% in the low-to-mid $11s to mid-$12s, and WPI from $14 to the mid-to-upper $14s. Our read: a commodity dry whey price in the 60s isn’t pulling solids back from returns like that, which means a stronger survey price won’t automatically produce more of the product USDA surveys. It’s the same wedge we traced in April, when $11/lb whey showed up as 69¢ on the milk check.
Methodology note 3 — the weight-equivalence trap
Canada’s 2025 shipments equal roughly 77.3 million pounds across all of HS 0404.10, or about 6.4 million pounds a month.
That total mixes WPC, modified whey, fluid whey, and dried whey. It cannot be set one-for-one against Extra Grade dry whey powder, and it cannot enter a dry-whey formula pound for pound. Anyone dividing 77.3 million pounds into U.S. production to get a percentage is comparing two different products.
What breaks this
Substitution behavior is the largest uncertainty and it is not modeled. If buyers requalify European or Oceania suppliers, draw on the 45.198 million pounds of WPC stocks, or reformulate onto milk protein concentrate, residual demand on U.S. dry whey shrinks toward zero. No public dataset establishes an elasticity between a covered Canadian classification and the NDPSR survey price. Western manufacturers told Dairy Market News that evolving global trade conditions “are not expected to affect current fourth-quarter contracts.”
What does the three-stage ledger actually add up to?
It doesn’t add up, and that’s the finding. Three Bullvine numbers now sit on one page measuring three different things on two different bases, and summing them would be wrong.
In August, this publication priced the whole access fight at a nickel — roughly 5¢/cwt, about $1,175 on the 400-cow Q4 model. Unresolved opportunity, not a booked loss.
On September 8, we put the retaliation exposure at $51 to $90 a cow annually, based on 256 cwt shipped per cow per year. On the 235 cwt basis used throughout this piece, the same $0.20–$0.35/cwt range gives $47–$82 per cow, or $4,700–$8,225 across 23,500 Q4 cwt.
Leonard Polzin, dairy markets and policy outreach specialist at the University of Wisconsin–Madison Division of Extension, published that $0.20–$0.35/cwt anchor the same day for a sustained Canada-only action, inside a wider $0.10–$0.50 planning range, and flagged the anchor as possibly high. His framing carries: the two actions pull U.S. prices in opposite directions, and the net is not determined.
Canada’s United States Surtax Order (2026), P.C. 2026-0785 of September 4, applies 50% to listed U.S. whey, milk-protein, and powder classifications and 25% to listed cheese lines, in force since September 8. Canada’s Department of Finance announced the measures on August 25, framing them as covering $27.6 billion in U.S. imports to match the American tariffs on an equivalent value of Canadian goods. A co-op selling whey ingredients north pays the surtax on those classifications while its domestic ingredient desk may see the opposite effect.
The administration’s position is on the record. U.S. Trade Representative Jamieson Greer issued a statement on September 8 framing the action as a response to Canada’s continued retaliation. Section 338 of the Tariff Act of 1930 caps additional duties at 50% ad valorem and separately authorizes the President to exclude articles from importation where the discrimination is maintained or increased — the two-step this package follows.
IDFA, which represents dairy processors and ingredient manufacturers, took a different line the next day. “In response to the President’s Executive Order banning whey and modified whey imports from Canada effective Sept. 29th, IDFA reiterates its strong support for resolving long-standing U.S. dairy trade concerns through meaningful negotiations,” the association said. One technical note: the controlling instrument is a presidential proclamation, not an executive order, which matters to anyone tracking the legal authority or the litigation risk.
NMPF, which represents dairy cooperatives and their farmer members, supported the July 20 decision to impose the 50% dairy duties. No NMPF statement specific to Proclamation 11062 had been located as of midday September 14.
The asymmetry drives the decision. Canada’s surtax is in force and working on U.S. export returns now, while the September 29 offset is not in force, not measured, and conditional on substitution, survey transmission, and plant-level pass-through.
The 90-Day Playbook for Herds Shipping Class III Milk
This week
Ask your customs broker to locate the September 8 dairy scope-modification proclamation if your co-op buys any Canadian dairy input. It’s referenced in paragraph 3 of 11062 and was not published alongside the alcohol and motor-vehicle versions on September 14. Trigger: any Canadian dairy input on the purchase ledger. Backfire: it’s a duty document, not a ban document — don’t conflate the instruments or their dates.
Next 30 days
Identify your order type. Multiple-component pricing means an itemized “other solids” line on your statement. Skim-fat pricing means the whey value is submerged inside the skim price and only the plant can show you where it went. Trigger: if you can’t find the line, the co-op call moves to the top. Backfire: a plant premium can mask a weak pooled price — read the total.
Put the question straight to your director. Does our plant sell Extra Grade dry whey into the NDPSR survey, or does our whey stream go into WPC, isolate, or permeate that the survey never sees? Trigger: “stronger whey markets are good for members” is a non-answer — credit the ban at zero and escalate. Backfire: ask for the payment mechanism, not customer contracts.
Price your Q4 basis against the strip. CME Class III futures closed at $16.14 for October and $16.40 for November on September 10, 2026, with dry whey futures at 69.00¢ and 71.475¢ for the same months, per USDA AMS Dairy Market News. Trigger: break-even above the strip plus your basis means the decision is about the floor, not the ban. Backfire: futures are not the announced class price.
90 days
Run the hedge threshold on your own numbers. If an option-based floor costs 20¢/cwt more than a fixed-price sale, the required move is 0.20 ÷ (1.03 × 6.0 × 0.965) = 3.35¢/lb of dry whey. Trigger: the 2¢ case doesn’t clear it; the 5¢ case does. Backfire: basis and PPD can absorb the whole modeled gain.
Get the patronage and equity-redemption policy in writing. Written request to the board secretary. Trigger:if you hold allocated equity and can’t state the redemption schedule, that number is bigger than 30 cents per hundredweight. Backfire: balance-sheet value is a legitimate answer — make them say so explicitly.
Budget rule and 365-day watch
Pencil in $0.00. Do not raise Q4 forward margin projections until the NDPSR dry whey survey prints four consecutive weekly gains. One week is noise; the five weeks to September 5 included a down week.
Watch the volume line, not just the price.Opportunity signal: qualifying sales dropping below the 7.25–9.79 million pound band recorded in those five weeks while the price climbs is the substitution bridge showing up in the data — that’s when you price the next hedge, not when you add cows. Backfire: lighter dry whey output can come from thinner cheese runs or plants chasing WPC 80 and WPI margins, neither of which is Canada-related.
What this looks like on your own paper
Open your last settlement, find the other-solids pounds and the rate you were paid, and multiply the rate difference by your Q4 hundredweight. You now have your own version of the $2,802-to-$14,014 band on your components rather than a model’s.
Then go looking for the line where a co-op processing margin would show up. Monthly pay price, cash patronage, allocated equity, or nothing you can point to — make your district director name which one before September 29. Until somebody does, the right number for this in your Q4 budget is zero.
Key Takeaways
Eight HTSUS whey lines close at 12:01 a.m. Eastern September 29 under Proclamation 11062, but the whey stream is only $2.35 of the $16.64 August Class III price — 14.1% — so the ceiling on this is smaller than the $35.04 million trade figure suggests.
Three whey prices ran within nine cents of each other in the same week, and only the NDPSR survey at 66.64¢ feeds the Class III formula. CME cash closed 9.36¢ above it on light trading.
If an option floor costs 20¢/cwt more than a fixed-price sale, dry whey has to move 3.35¢/lb before that trade pays. The 2-cent case doesn’t clear it.
Paragraph 9(b) snaps invalidated imports back to the 50% duty under Proclamation 11047. As drafted, winning in court doesn’t get anyone duty-free Canadian whey.
Run Your Numbers
Component Value Tracker — This piece runs the whey stream on a 400-cow model. Put your own herd size, daily milk, and other-solids test in and see what the same 2¢-to-10¢ dry whey range is worth on your check, not ours. Print the summary before you price Q4.
Canada Dairy Tariffs 2026: Cost Per Cow — Arms you with balance-sheet exposure numbers across a multi-year trade war, quantifying the direct $51 to $90 per-cow hit from cross-border retaliation.
The Access Fight Is Worth 5¢: Class III Already Took 64¢ — Dismantles political rhetoric surrounding Canadian market access by comparing minor tariff concessions against massive federal order formula shifts that actually determine your mailbox price.
The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.
Tuesday brought some exciting changes in cash dairy prices on the Chicago Mercantile Exchange that might catch your attention. Dry whey saw a slight uptick, rising $0.01 to $0.57. This wasn’t just a blip; a recorded sale at that price supported it. Consistency in these minor gains can significantly boost your revenue over time.
But there’s more. Forty-pound cheese blocks edged up by a modest $0.0050, now sitting at $2.2150. Again, one sale was recorded at that new price point, showing that demand remains steady.
Dry whey: Up $0.01 to $0.57
Cheese blocks: Up $0.0050 to $2.2150
Cheese barrels: Unchanged at $2.26
Butter: Down $0.0175 to $3.1525
Nonfat dry milk: Up $0.0125 to $1.3425
It’s not all rosy, though. Butter prices slipped by $0.0175, settling at $3.1525 across thirteen recorded sales. This dip might be a downer, but informed decisions come from knowing all the details.
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
To provide the best experiences, we and our partners use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us and our partners to process personal data such as browsing behavior or unique IDs on this site and show (non-) personalized ads. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Click below to consent to the above or make granular choices. Your choices will be applied to this site only. You can change your settings at any time, including withdrawing your consent, by using the toggles on the Cookie Policy, or by clicking on the manage consent button at the bottom of the screen.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.