

One 2028 organic position is open in Ontario, closing September 30. Minimum buy-in: 20 kg of quota at C$480,000, plus roughly C$168,000 of your own equity at 65% LTV. The rest are on hold.
Dairy Farmers of Ontario publishes a 160-kilogram annual new-entrant pool and a 20 kg match per applicant, and never prints the quotient: a ceiling of eight assisted entrants a year. Set that against a net reduction of 34 farms in DFO’s own last two annual reports and the program’s theoretical capacity works out to one match per 4.25 farms off the reported count. Eight is our arithmetic, not a DFO statistic — it has surfaced publicly once, when Farmers Forum reported in August 2023 that DFO would loan 160 kilograms that year “divided between eight successful new-entrant applicants.” In a normal intake year, eight was the working allocation rather than a theoretical limit.
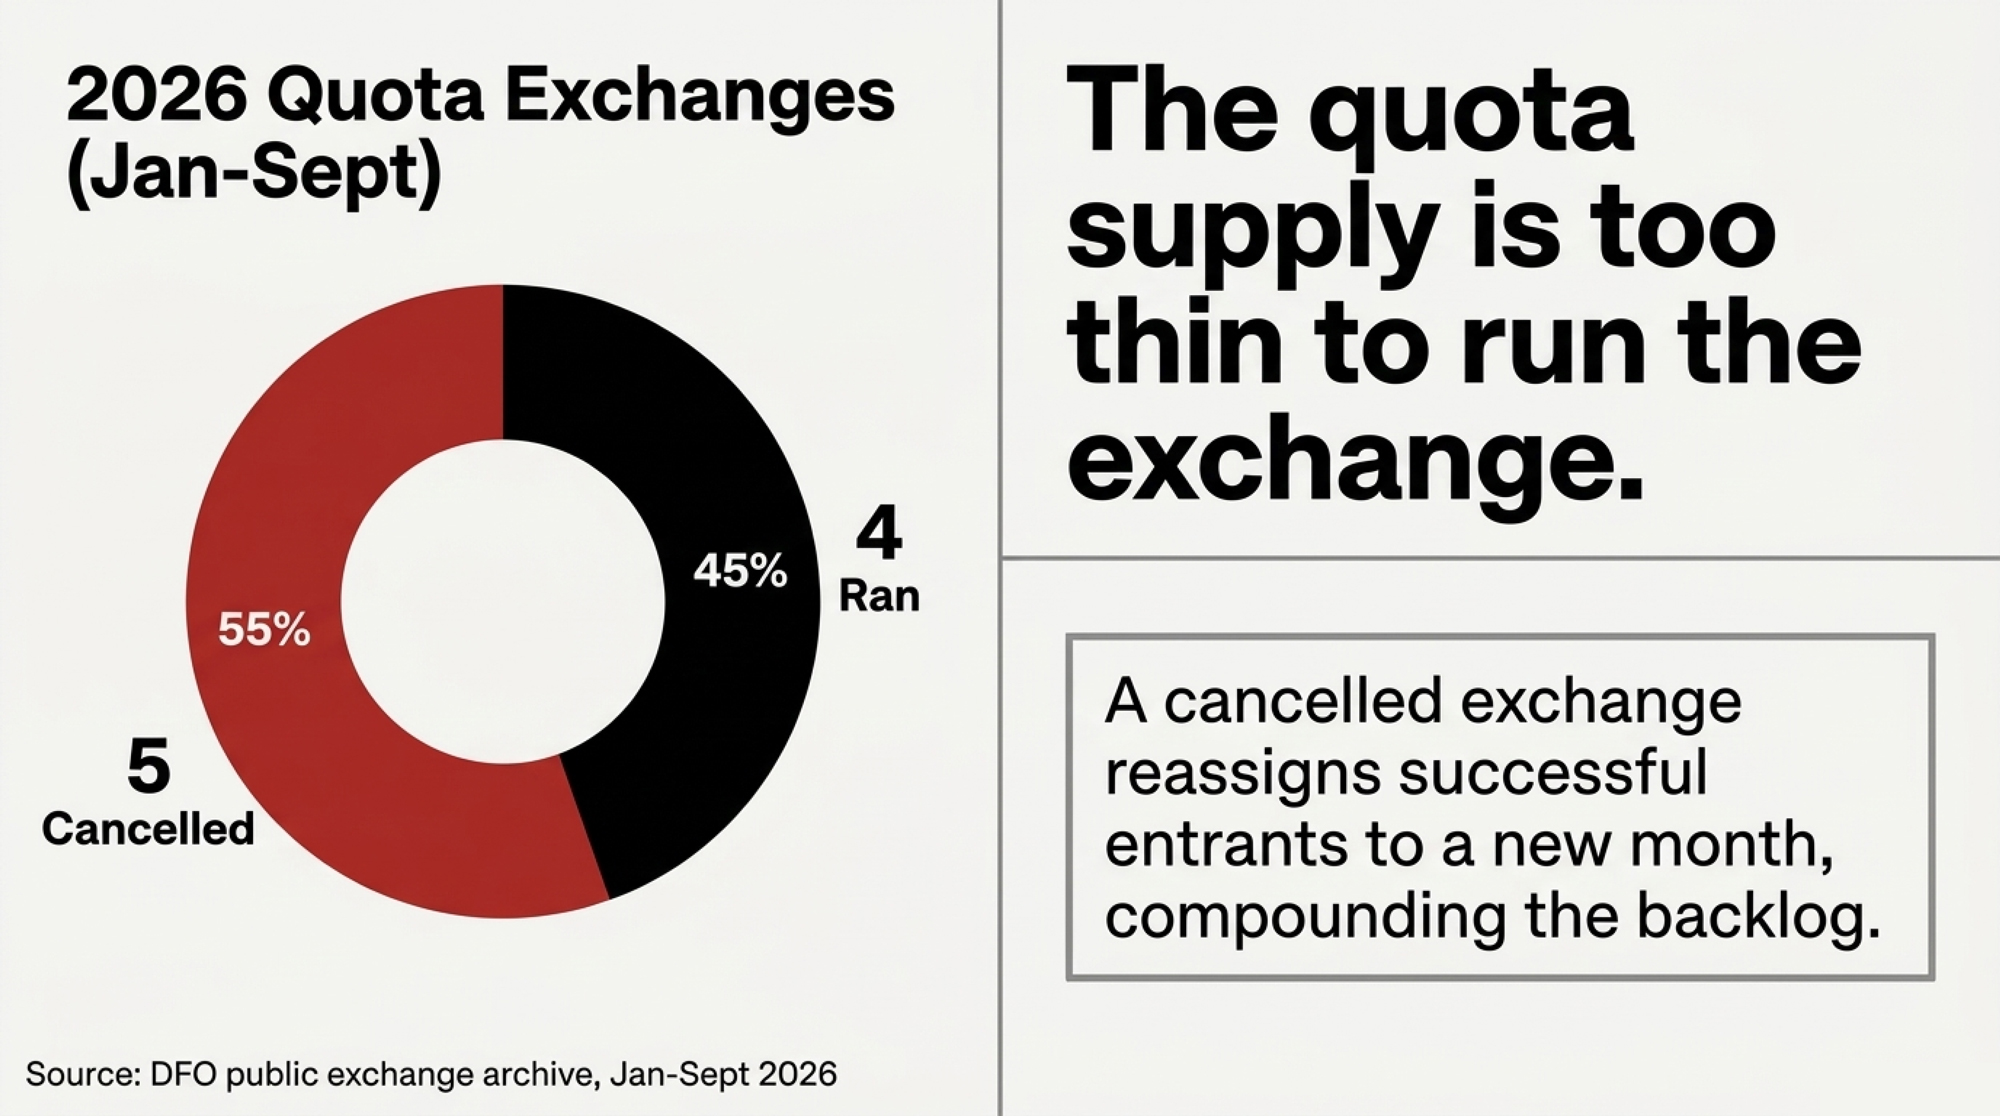
Now most of that capacity is unavailable. Citing cancelled quota exchanges and the number of New Producer Program and NEQAP applicants already carrying priority access into the 2026 and 2027 exchanges, DFO deferred the application period for the balance of the 2028 positions. One organic slot remains open until September 30; the rest are on hold with no published end date. The hold provides “an opportunity for the current backlog of successful applicants with priority access to the quota exchange to be cleared through the next several months,” according to DFO’s July 30 notice, which still carried it at 12:04 p.m. on September 15.
What DFO’s Policy Book Actually Commits To
The primary sources are DFO’s Quota and Milk Transportation Policies (revised June 1, 2026), the 2028 Organic NEQAP application (revised July 2026), and DFO’s own exchange summaries and twelve-month exchange archive. All were downloaded from new.milk.org.
Clause 1 reads: “The P5 makes available up to 160 kg of quota per year for the NEQAP in Ontario.” Clause 20 gives successful applicants priority access to buy 20 to 30 kilograms on an assigned exchange. Clause 25 commits DFO to allocate 20 kilograms to each successful applicant, subject to DFO issuing a licence and approving an order to issue quota.
One wording conflict is worth naming. DFO’s July 30 web notice states 160 kilograms flat and calls the 20 kilograms a match, while the policy book says “up to.” This article uses the policy book’s conservative reading. We put that question to DFO on September 15 with a September 22 deadline, along with the rest of what follows, and had no response as of publication.
On hold is not cancelled. The Board said it would revisit the decision in fall 2026, and it has published no end date.
DFO is Ontario’s delegated authority for marketing cow’s milk and a producer-funded board. Its policy documents are controlling primary records. Its characterization of its own program is an interested party’s characterization.
Why Can’t a Selected New Entrant Get Quota Off the Exchange?
Five of the nine Ontario quota exchanges scheduled from January through September 2026 were cancelled: February, April, May, July and August. Four ran in January, March, June and September. All nine outcomes are recorded in DFO’s public exchange archive.
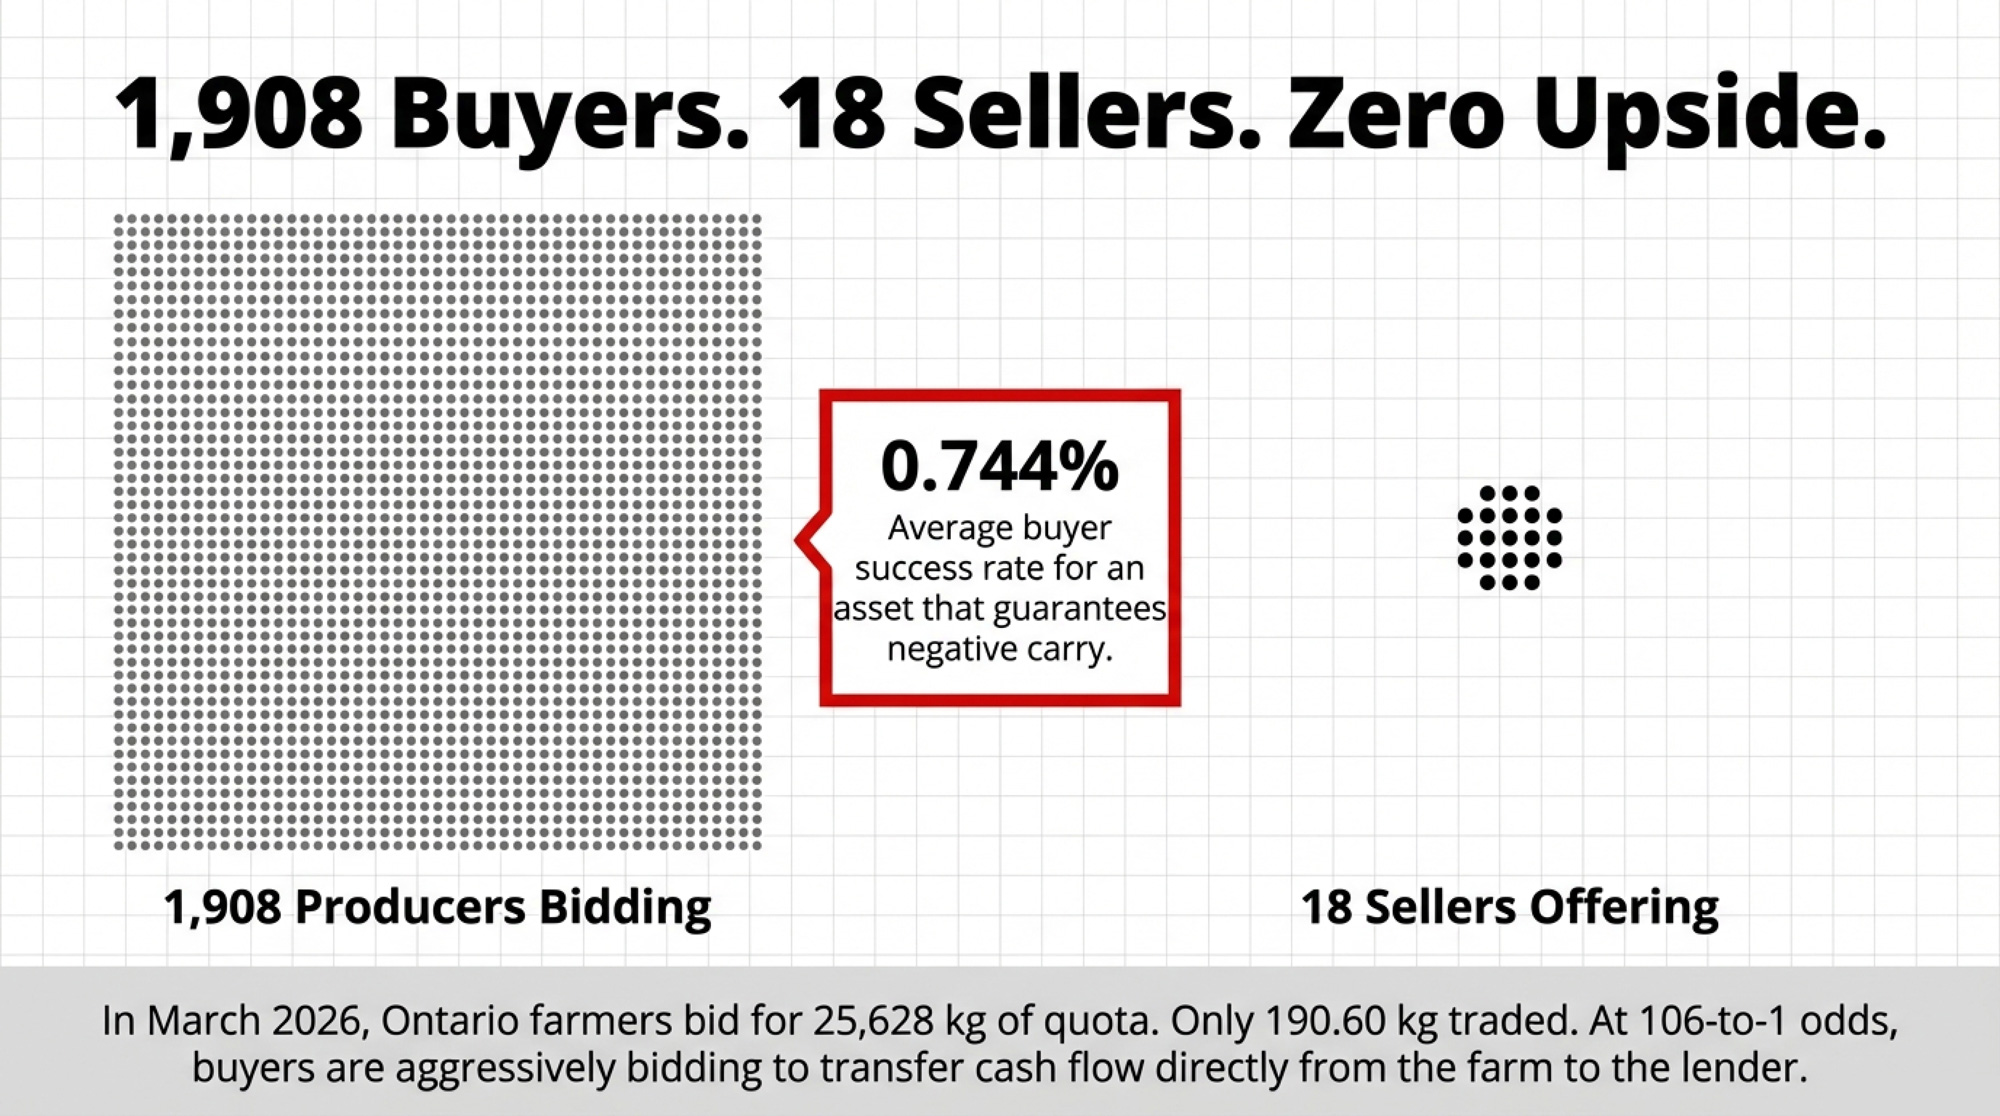
August shows the constraint in one document. DFO’s summary for that exchange, printed August 4, records two new entrants receiving assistance in the exchange and 0.00 kilograms acquired. It records 25,756.66 kilograms in accepted bids from 1,864 producers against 167.79 kilograms offered by 21 sellers, and DFO’s own note explains the cancellation: “There was 167.79 kg for sale, but 186.20 kg was required to run the first allotment round.” Clause 24 cancels a new entrant’s bid when volume can’t cover 0.1 kilogram to every other successful buyer, and a cancelled exchange reassigns that entrant to a new month.
September ran, and ran thin. DFO’s summary records 511.38 kilograms sold and transferred against 25,596.34 kilograms in accepted bids from 1,852 producers, at the C$24,000-per-kilogram cap. Two NEQAP participants used priority access to acquire a combined 55 kilograms. Two entrants got nothing in August, and two got 55 kilograms in September — the deferral and the clearance, one month apart, both in DFO’s own documents.
| DFO exchange month | Exchange outcome | Quota offered / transferred | Accepted bids and buyers | NEQAP outcome |
| August 2026 | Cancelled | 167.79 kg offered | 25,756.66 kg accepted bids from 1,864 producers | Two participants received assistance but acquired 0.00 kg |
| August cancellation threshold | First allotment could not open | 167.79 kg available | 186.20 kg required to run the first allotment round | Priority access could not overcome insufficient supply |
| September 2026 | Ran at C$24,000/kg cap | 511.38 kg sold and transferred | 25,596.34 kg accepted bids from 1,852 producers | Two NEQAP participants acquired 55 kg combined |
| January–September 2026 | Five of nine exchanges cancelled | Four exchanges ran | Exchange access was intermittent, not continuous | Backlog clearance depends on months that actually run |
Cancellations have run through three consecutive fiscal years: three in 2024, four in 2025, five through the first nine months of 2026. Three annual data points are not a trend, and this piece won’t call it one. It is enough to say quota supply has been thin enough to cancel exchanges in each of those years.
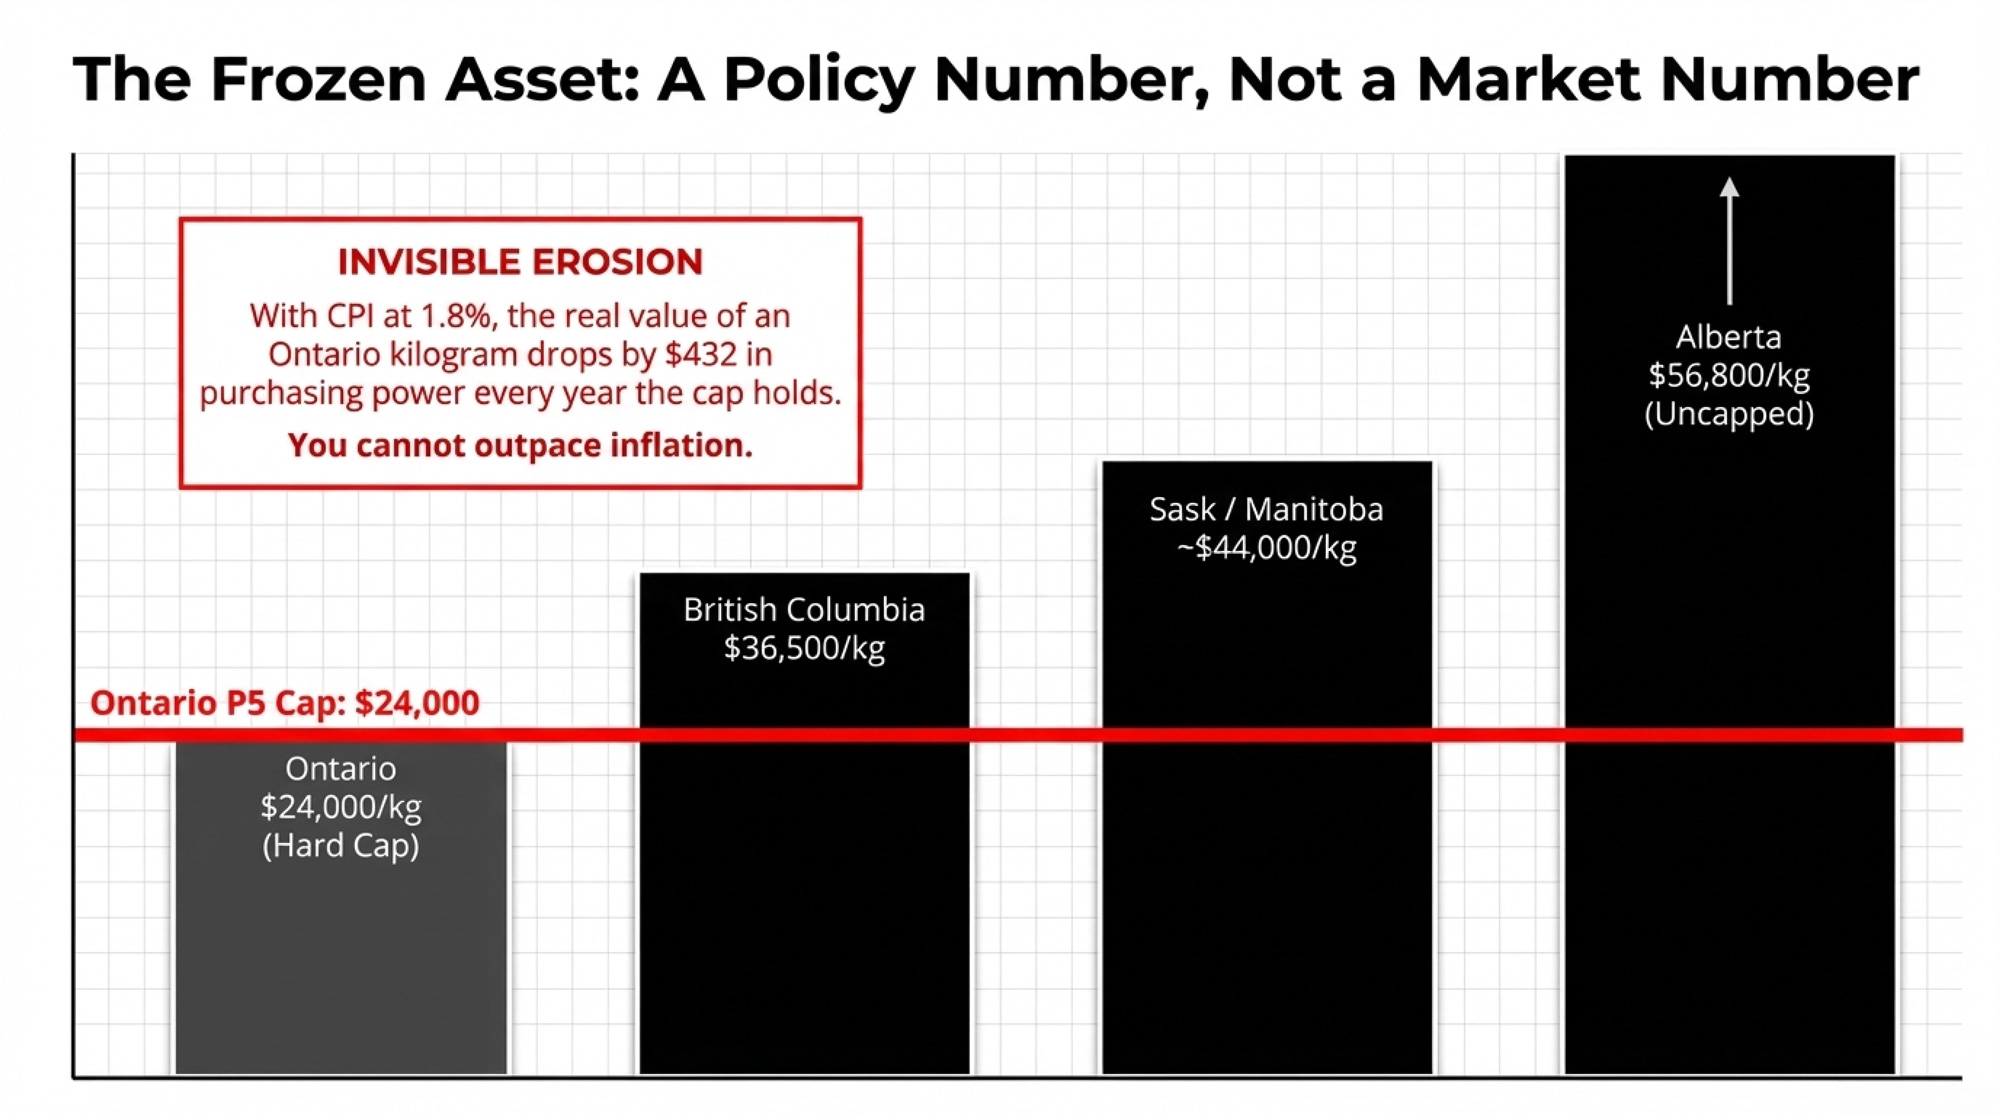
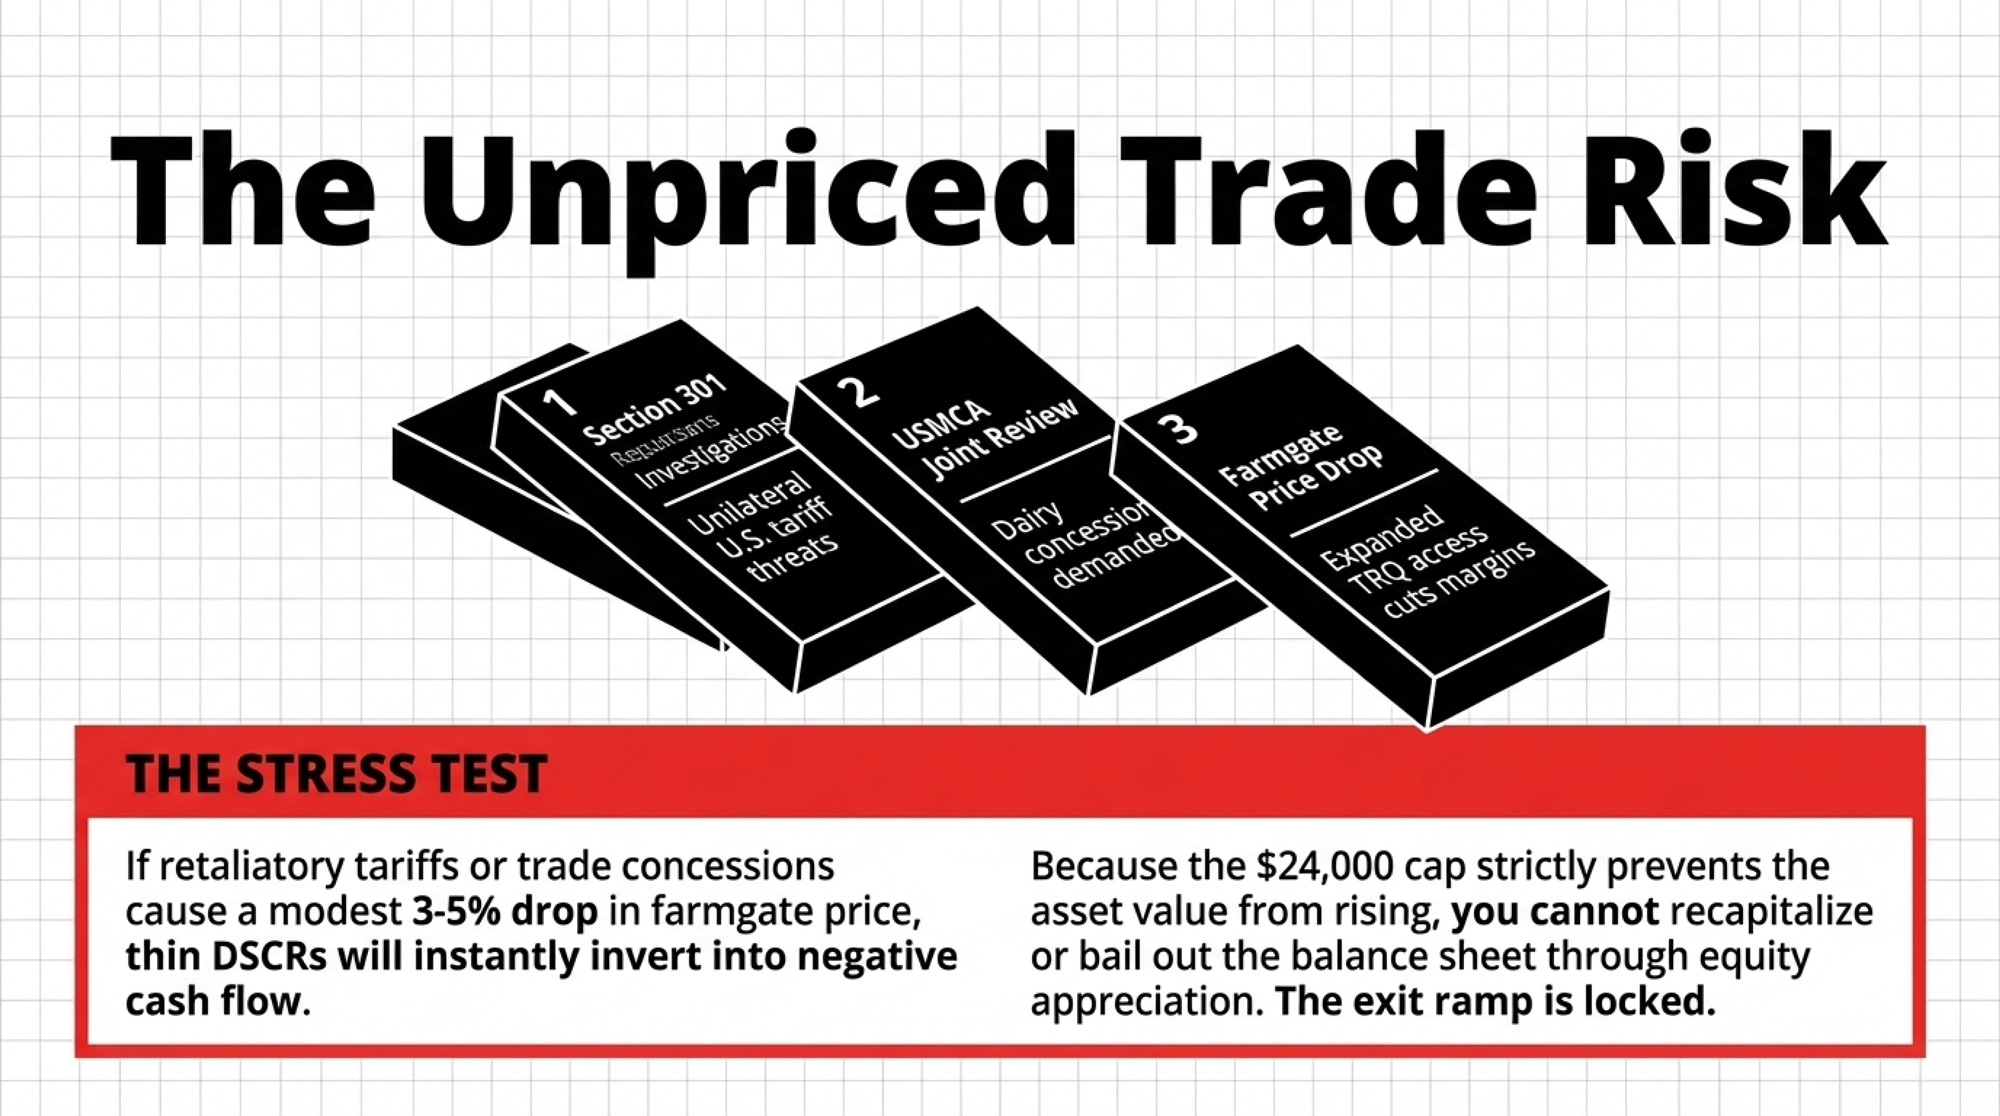
The C$24,000 figure is DFO’s administrative price cap on the Ontario exchange. It is not a class price, not a futures quotation, and not a spot commodity print.
Run the Capital Math Before You Call Your Lender
Running the Numbers — Bullvine calculation. Ontario, September 2026, Canadian dollars. Quota measured in kg butterfat per day.
Published sources
- Annual Ontario pool: up to 160 kg (DFO policy book, rev. June 1, 2026, clause 1)
- Match per successful applicant: 20 kg (same, clause 25)
- Own quota the 2028 entrant must acquire: 20 to 30 kg (clause 20; 2028 application, rev. July 2026)
- September 2026 exchange price: C$24,000/kg, the administrative cap (DFO exchange summary, printed September 2, 2026)
- Recovery from year 11: 0.1 kg per month, maximum 1.2 kg per 12-month period, term not exceeding 28 years for 2021-onward applicants (clauses 31 and 35)
- Ontario average composition, May 2026 single month: 4.3035 kg butterfat per hectolitre (Milk Producer, Dairynomics, July 2026 issue)
Stated assumptions, not DFO figures
- Butterfat per cow per day: low 1.20 kg · central 1.35 kg · high 1.50 kg, used only to scale quota into cows
- The June 2028 exchange clears at the same C$24,000 cap, which cannot be known today
The Bullvine model
The ceiling: 160 ÷ 20 = 8 equal matches per year.
| Case | Own quota purchased | Quota capital | Total quota after the 20 kg match | Daily shipment at 4.3035 kg BF/hL, May 2026 | Cows at 1.20 / 1.35 / 1.50 kg BF |
| Minimum | 20 kg | C$480,000 | 40 kg | 9.3 hL, about 929 L | 33 / 30 / 27 |
| Midpoint | 25 kg | C$600,000 | 45 kg | 10.5 hL, about 1,046 L | 38 / 33 / 30 |
| Maximum | 30 kg | C$720,000 | 50 kg | 11.6 hL, about 1,162 L | 42 / 37 / 33 |
The conservative number is C$480,000, and that is what belongs in a lender meeting. It buys quota and nothing else: no land, cows, replacements, buildings, parlour, organic certification, feed inventory, professional fees, or working capital. If you want the fuller picture of what a startup dairy enterprise absorbs, the real math on one operation’s buildsets the scale.
One precision point on what that money buys. Under Section A clause 5, DFO calculates the saleable and non-saleable split administratively, and the non-saleable percentage moves — 0.000% on the May 2026 summary, 2.000% on August’s. Kilograms purchased and kilograms you can later resell are not automatically the same number.
Then there is the equity behind the loan. Published commentary from Creek Road Financial, a mortgage brokerage rather than a lender, puts loan-to-value on Ontario quota at 60% to 75% against 10-to-15-year terms. Treat it as market commentary rather than underwriting policy, and note that DFO’s exchange cap has stood at C$24,000 per kilogram on every 2026 summary reviewed here. Your lender’s stated number governs. Applied to the minimum purchase:
- At 75% LTV: C$480,000 × 25% = C$120,000 equity on quota alone
- At 65% LTV: C$480,000 × 35% = C$168,000 equity
- At 60% LTV: C$480,000 × 40% = C$192,000 equity
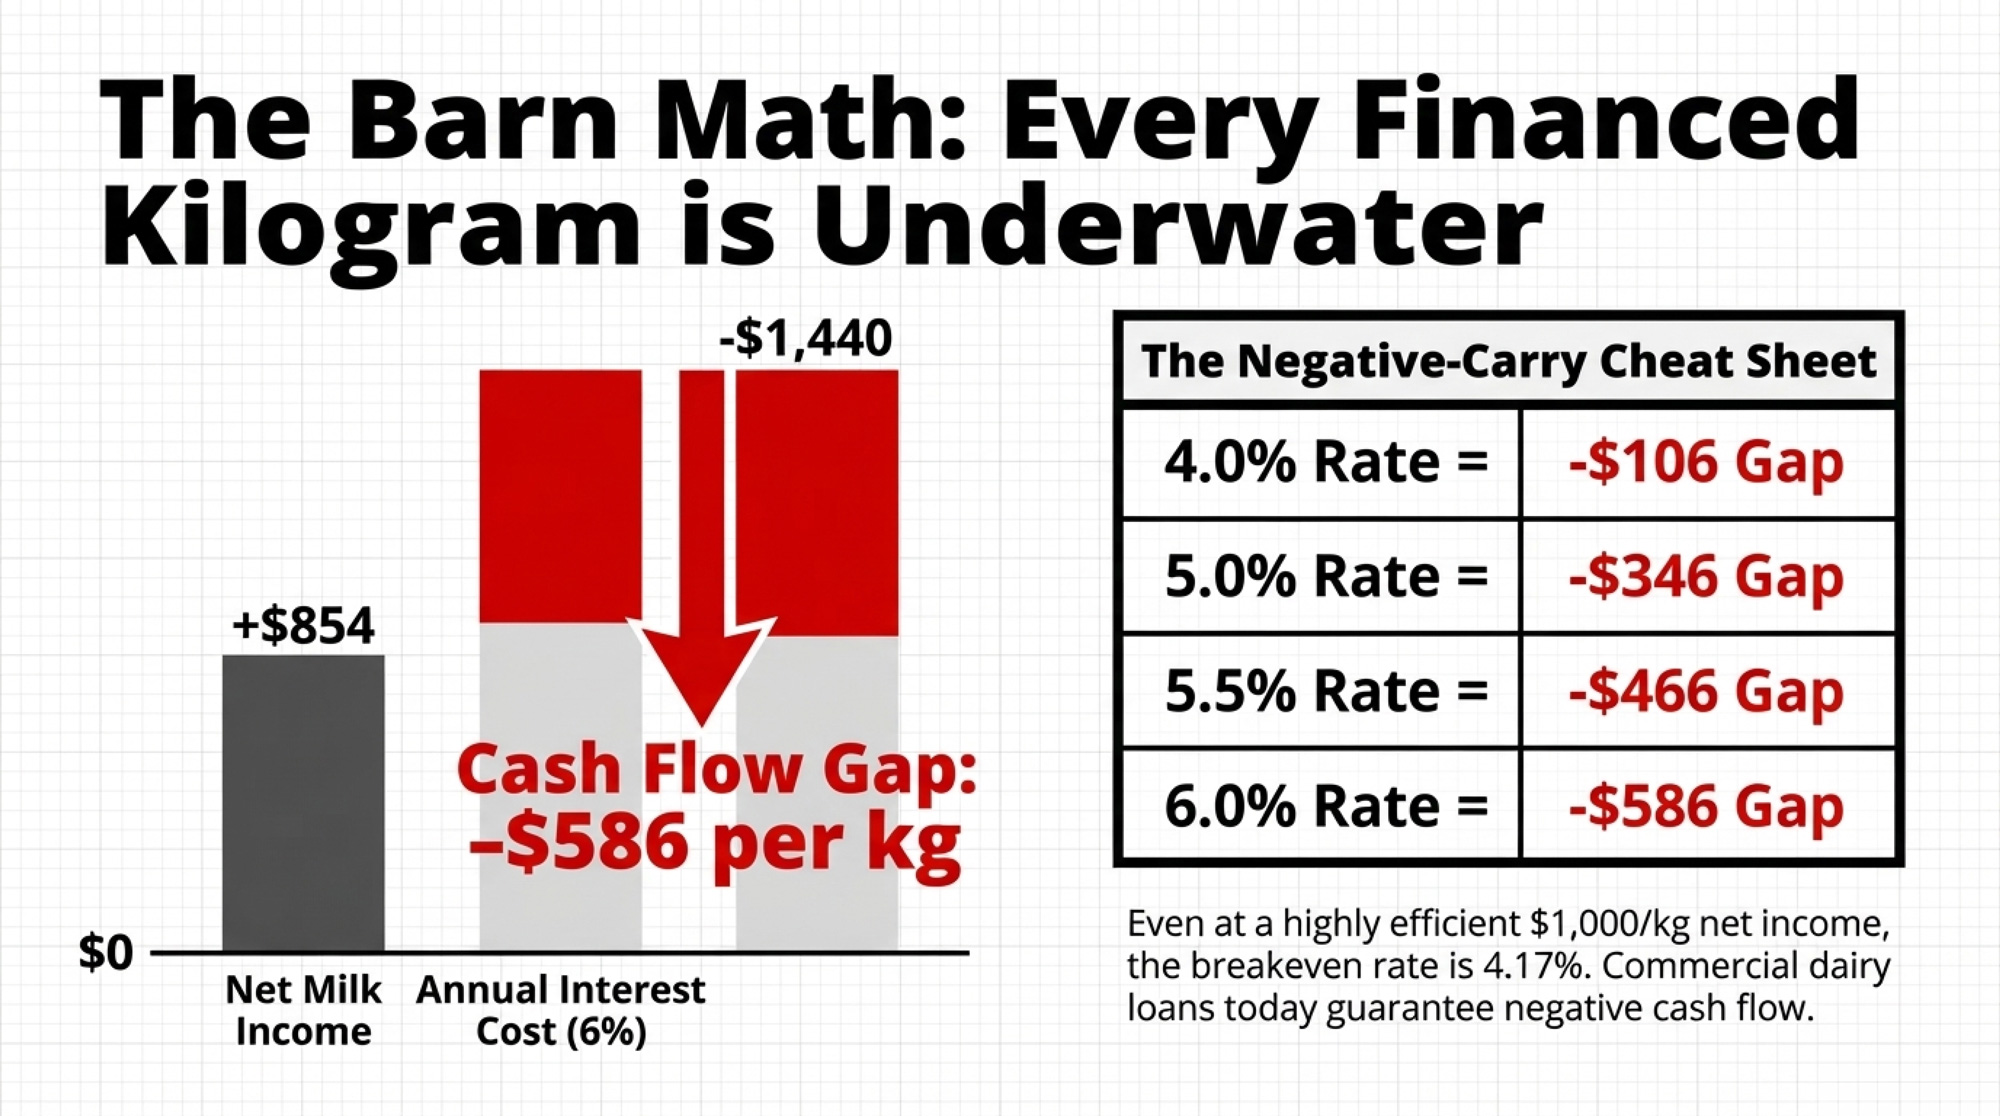
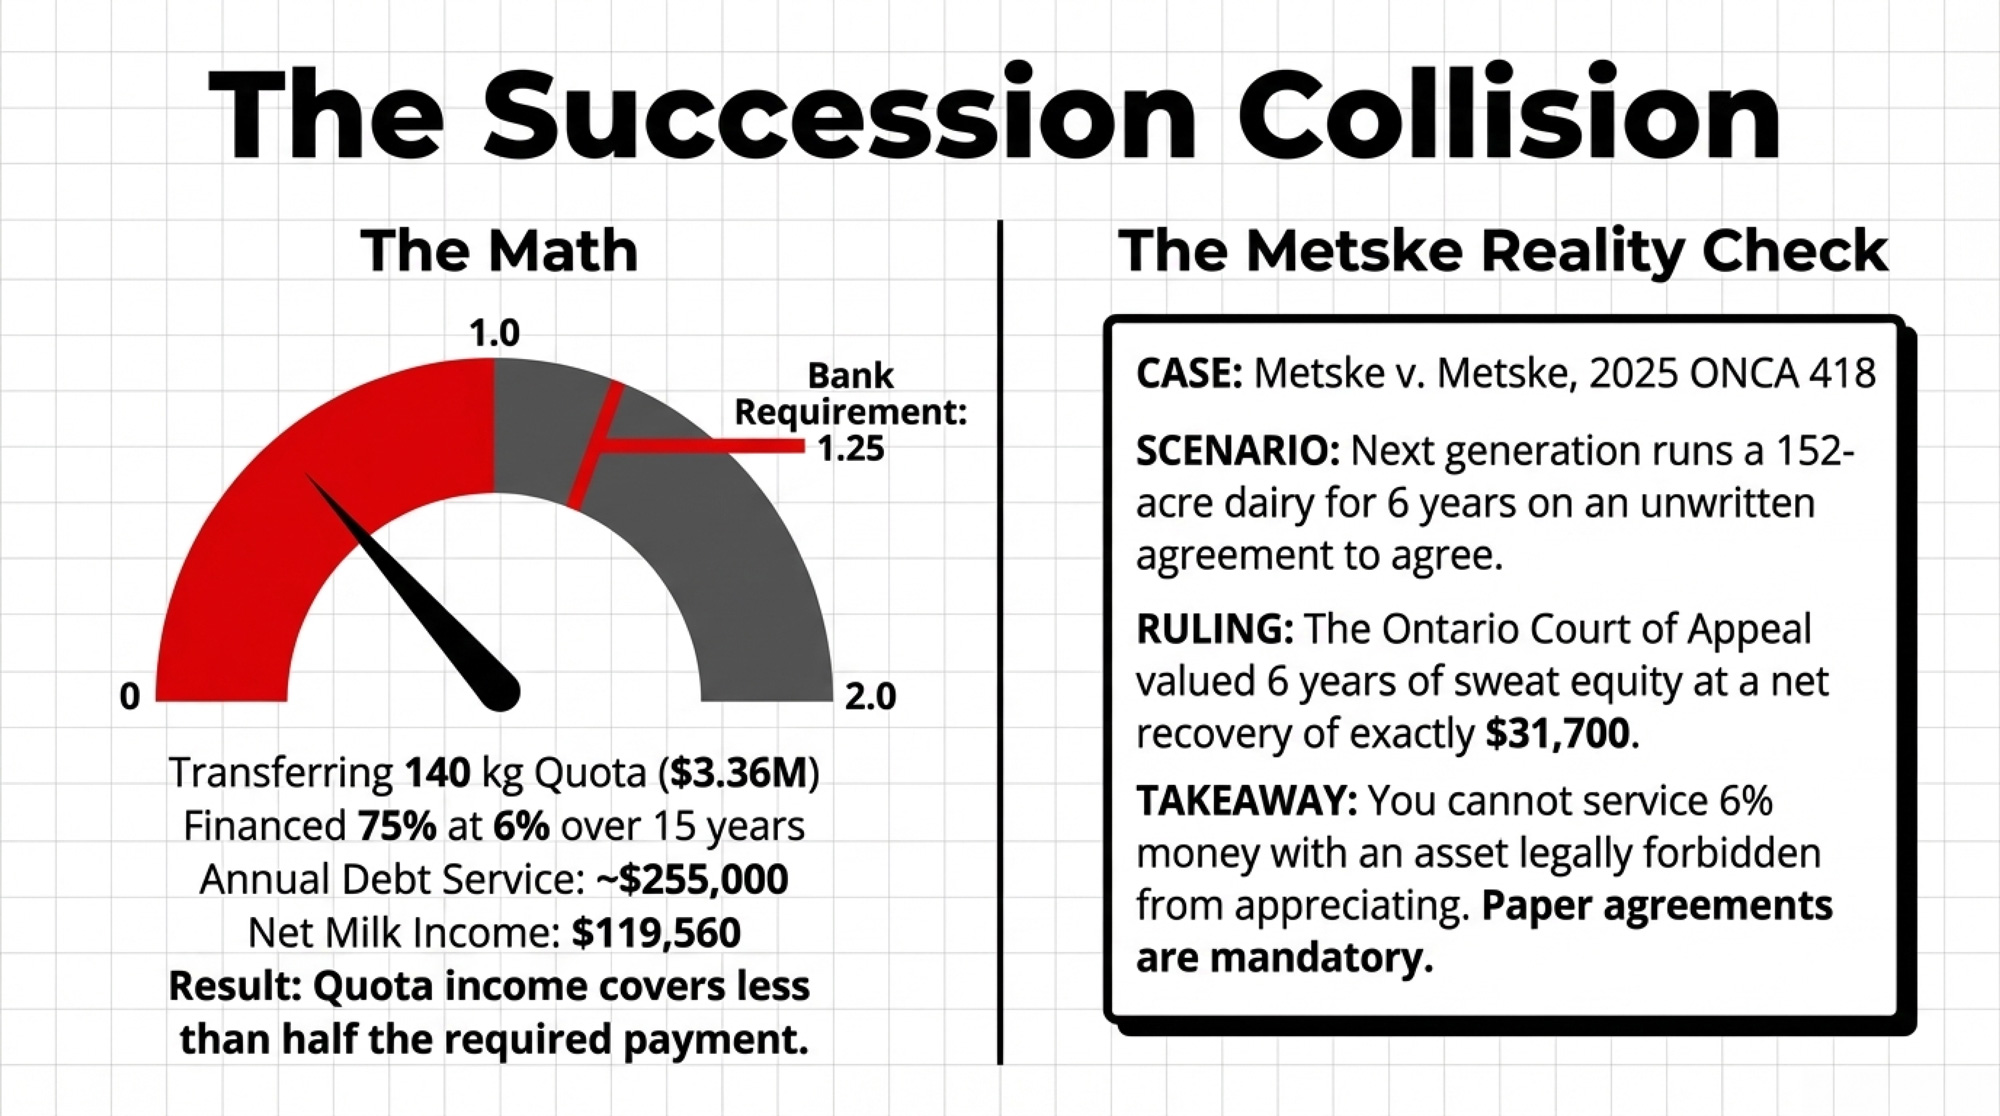
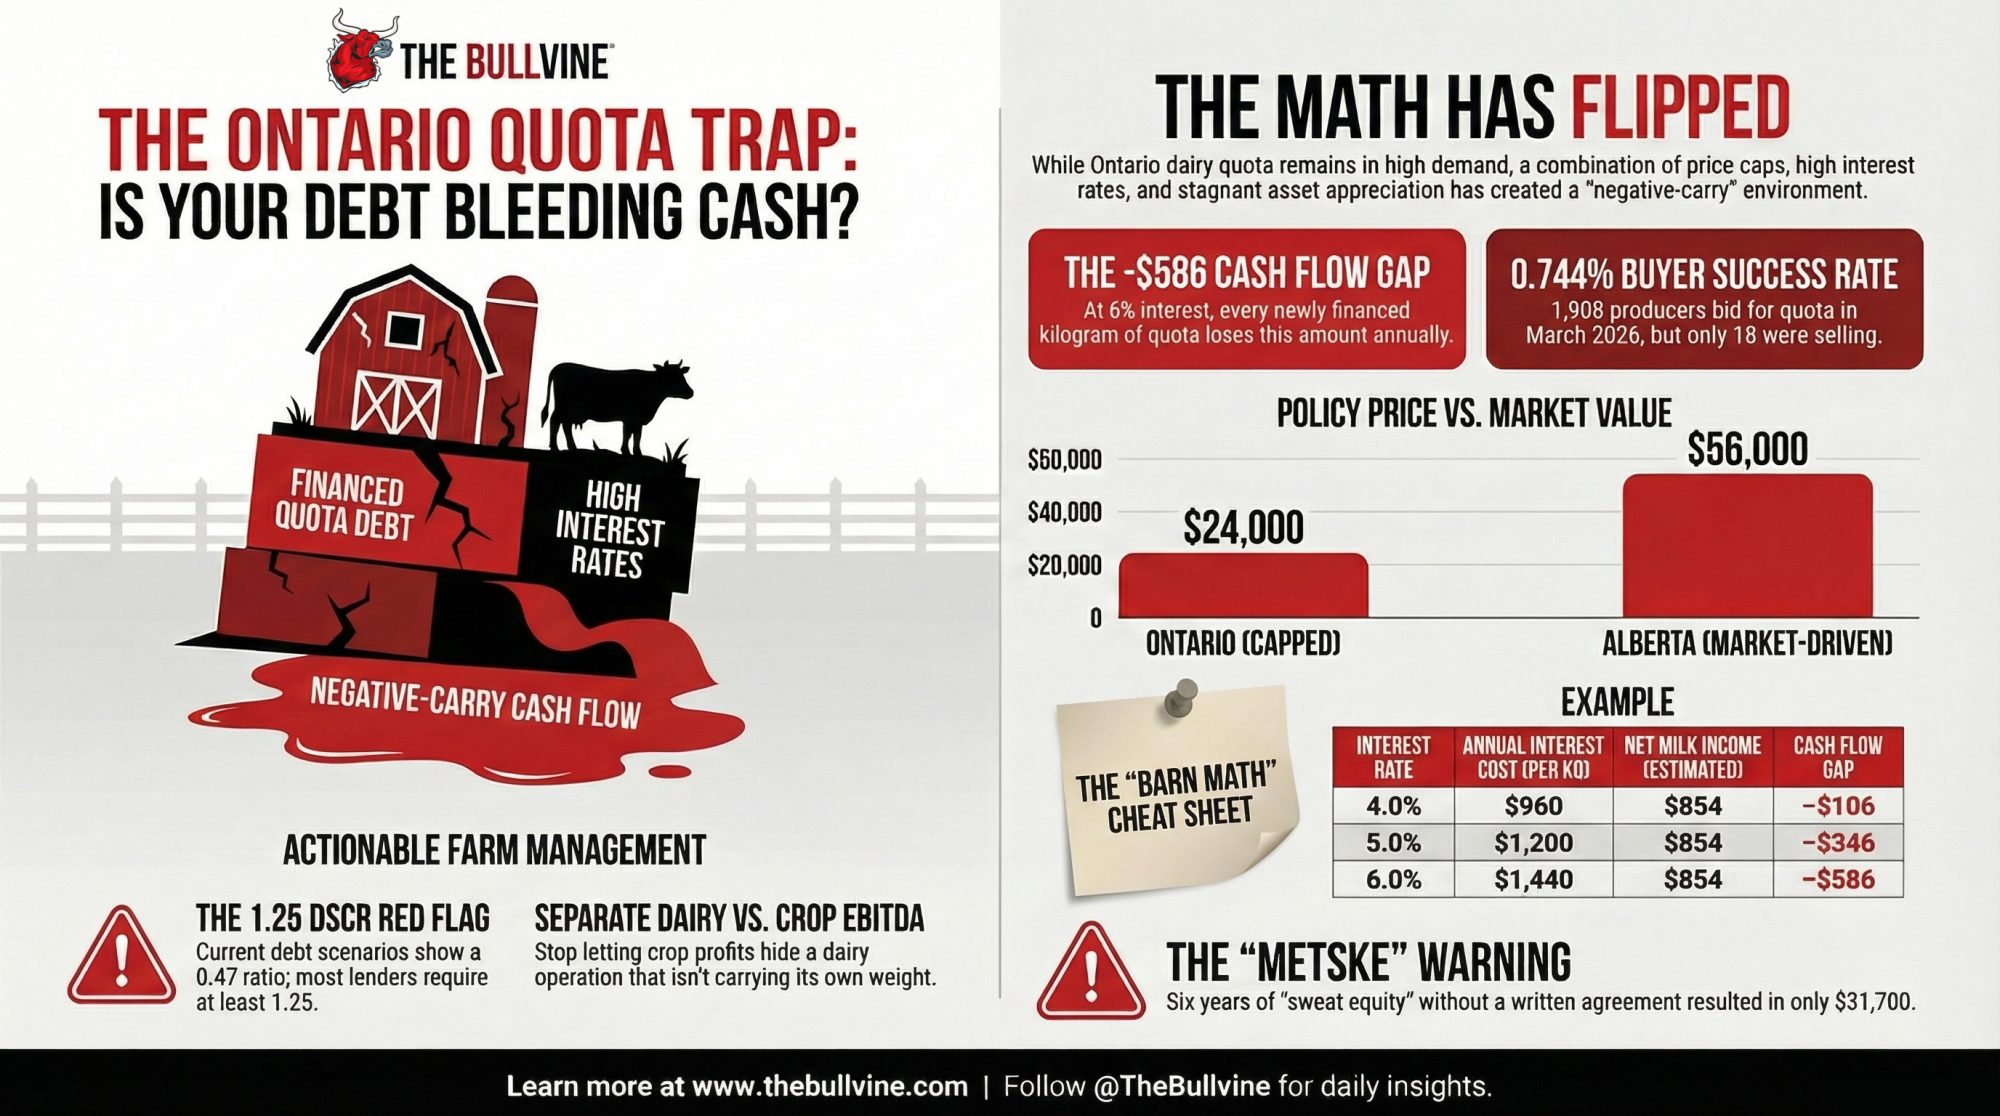
That is equity against quota before a single cow arrives, which is why the application demands signed lender letters with no appraisal contingency. Our own modelling on financed Ontario quota put each newly financed kilogram at roughly C$586 a year cash-flow negative at 6%, and that arithmetic applies to an entrant’s purchased kilograms the way it applies to anyone else’s.
Now price the match itself. From year 11, DFO recovers up to 1.2 kg per 12-month period. On our arithmetic, replacing 1.2 kg of shipping entitlement at the September cap costs C$28,800 a year, and 20 ÷ 1.2 puts full recovery 16.7 yearsout from the year-11 anniversary, landing inside the 28-year maximum term for post-2021 applicants. The match is interest-free quota rather than free quota, and the bill arrives as lost entitlement starting in year 11.
No double counting: the 20 kg match sits outside the capital and equity columns because the entrant never buys it.
Check the County List Before Paying an Accountant
Location disqualifies more applicants than financing does, and it costs nothing to check first. DFO’s application names the eligible area precisely: Glengarry, Prescott, Russell, Carleton, Dundas, Stormont, Frontenac, Grenville, Lanark, Leeds, Renfrew, Hastings, Lennox & Addington, Northumberland, Prince Edward, Peterborough, Kawartha Lakes, Durham, Wellington, Waterloo, Grey, Bruce, Huron, Perth, Oxford, Middlesex, Elgin, Lambton and Wentworth, plus the Dufferin townships of Amaranth, East Luther and East Garafraxa, and the part of Brant County north of Highway 403.
Miss the 16-month conversion window and DFO orders the acquired quota sold and recovers the match. That is the sharpest consequence in the document, and it sits behind three disclosed commitments: begin marketing within six months of the initial allotment, ship all milk as organic within 16 months, then keep shipping organic for at least five years.
Your lender gets no security from the 20 kilograms DFO supplies. Clause 38 states assistance quota “is not transferrable and cannot be encumbered,” which is why the application demands the two financing rules that decide who can file at all: a certified-accountant-prepared or reviewed 10-year plan, and signed lender letters stating principal and term with no appraisal contingency.
A lottery can end a qualified application, and DFO owes you no explanation when it does. An independent third party determines which applications meet the criteria; priority goes to applicants who have never held a licence in another Canadian supply-managed sector, and where qualified applications outnumber positions, the third party draws. Beginning with the 2027 intake, DFO’s posted policy moves application and selection two years ahead of production.
What the Farm Count Says About Eight Matches
DFO reported 3,187 Ontario dairy farms in its 2024 annual report and 3,153 in its 2024-25 report, published February 2026. The 34-farm difference is a net reduction in the reported count, not 34 documented exits, because DFO publishes no licence reconciliation setting cancellations against new licences issued. That distinction is why the ratio in the lead is a capacity comparison rather than a replacement rate, and why the direction of that count is the real backdrop to any new-entrant program.
For scale outside supply management, USDA’s National Agricultural Statistics Service put licensed U.S. herds at an annual average of 23,609 in 2025, down 1,036 from 2024 on initial estimates — a different country under a different regulator, and no part of the Ontario arithmetic.
Now the finding that survives every caveat. DFO’s 2024-25 annual report says 133 producers entered through NEQAP from March 2010 to October 2025, “with approximately 92 per cent remaining in the industry.” Two paragraphs later, the same report describes the New Producer Program differently: 156 producers used it, and 135 are currently shipping milk. One program gets a hard operational count, the other an approximate share. The 2022 report did the same thing, pairing 110 NEQAP entrants and approximately six per cent exiting against 146 NPP users and 132 currently shipping.
Run those cumulative totals, and NEQAP looks like it has been doing its job. 110 over 152 months annualizes to 8.68. The 23 added between October 2022 and October 2025 annualizes to 7.67. Both sit close to the eight-match ceiling, and Farmers Forum’s 2023 report of eight applicants points the same way. This is not an indictment of the program’s history.
What no public document supports is a claim about right now. No cohort table shows applicants qualified, applicants selected, entrants who acquired quota, licences issued, first shipments, still shipping, and the months between each step. Without that denominator, nobody outside DFO can tell whether the 2026 backlog is delay or attrition. We asked DFO for the cohort figures and for the definitions behind “entered the industry,” “remaining in the industry,” and “currently shipping milk” on September 15, with a September 22 deadline, and had no response as of publication. The absence of the cohort table is the finding.
Work the 30/90/365 Playbook
30 Days — Before September 30
Verify the farm location.
- Action: Check the parcel against the county and township list above, then download the application from DFO’s 2028 program page. Our companion checklist tracks all three sections, the eligibility screen and the post-selection commitments in one page.
- Requirement: The county, and in Dufferin or Brant, the township or the Highway 403 position.
- Threshold: Pull the property tax bill and read the municipality off it rather than working from memory. If the parcel sits in Dufferin, confirm it falls in Amaranth, East Luther, or East Garafraxa specifically. If it sits in Brant, confirm on the survey that it lies north of Highway 403. Outside the list, stop before spending on professional fees.
- Risk: An ineligible location burns an accountant’s fee and a lender letter for nothing.
Lock the financing letter.
- Action: Get the lender letter written with the principal and term stated and no appraisal contingency, and ask for the quota loan-to-value in writing.
- Requirement: The 10-year plan in the lender’s hands first.
- Threshold: Read the letter for two things: a principal amount in numbers and a term in years. On our arithmetic, a 65% LTV puts roughly C$168,000 of your own equity against the minimum purchase before you own a cow. If that equity isn’t identified and liquid, the file isn’t ready to send.
- Risk: A conditional letter reads as a rejected package.
Submit the complete package.
- Action: File by registered mail to 6780 Campobello Road, Mississauga, Ontario L5N 2L8, or by email to neqap@milk.org.
- Requirement: All three sections — application form, accountant-reviewed 10-year plan, signed lender letters — in one submission.
- Threshold: Lay the three sections out and confirm each carries a signature and a date. The accountant’s letter has to verify the plan is legitimate and that the business can generate a profit on the stated assumptions; if it only confirms the numbers were reviewed, it doesn’t meet the requirement. If all three aren’t finished 72 hours out, treat the intake as missed.
- Risk: DFO doesn’t accept late or incomplete packages.
90 Days — Structural
Test the organic conversion timeline.
- Action: Model the 16-month conversion against your certifier’s calendar, not the application’s.
- Requirement: Certifier confirmation, plus an organic feed plan covering projected mature inventory.
- Threshold: Two tests, both yours to run this month. If your certifier won’t put a projected certification date in writing, the 16-month clock is unbudgeted. If your certified or transitioning acreage can’t feed the projected mature inventory on paper, the application fails its own test before DFO reads it.
- Risk: Missing 16 months triggers a forced quota sale plus recovery of the match.
Price the recovery schedule into the plan.
- Action: Write DFO’s take-back into the back half of the 10-year plan. On our arithmetic, 1.2 kg a year at the September cap is C$28,800 of lost entitlement annually, running 16.7 years from the year-11 anniversary.
- Requirement: Your own butterfat per cow, not the 1.35 kg assumption used above.
- Threshold: Find the year-11 anniversary date. If you already hold assistance, it’s on your schedule. If you’re applying, count ten years forward from your projected June 2028 allotment date and mark the month — then check whether your plan says anything at all about that year.
- Risk: A plan that stops at year 10 understates what the match actually costs.
365 Days — Positioning
If you’re outside the eligible area or shipping conventional.
- Action: Track DFO’s 2028 program page for the Board’s decision rather than forcing an application through a screen it can’t pass.
- Requirement: Nothing but attention until the Board rules.
- Threshold: Check the “last updated” date on the program page monthly. If it moves, re-read the geography clause and the position count before assuming anything about your own eligibility — the July 30 revision changed both.
- Opportunity signal: The 2027 intake moves application and selection two years ahead of production under DFO’s posted policy, buying a longer runway to assemble financing. Build the accountant-reviewed plan now and file into a calmer queue.
- Risk: The hold has no published end date, so plan for the position not opening.
If you’re planning an exit rather than an entry.
- Action: Time your exchange sale against months that actually run.
- Requirement: Your current quota holding and saleable split from your last DFO confirmation.
- Threshold: Before you set an offer price, read the saleable and non-saleable split off that confirmation — the non-saleable percentage moved from 0.000% in May to 2.000% in August, and only the saleable portion sells. Five cancellations in nine months, and 25,756.66 kilograms of accepted bids against 167.79 offered in the August that never ran.
- Risk: A thin cap-priced market with a queue ahead of you means the timing is not yours to choose.
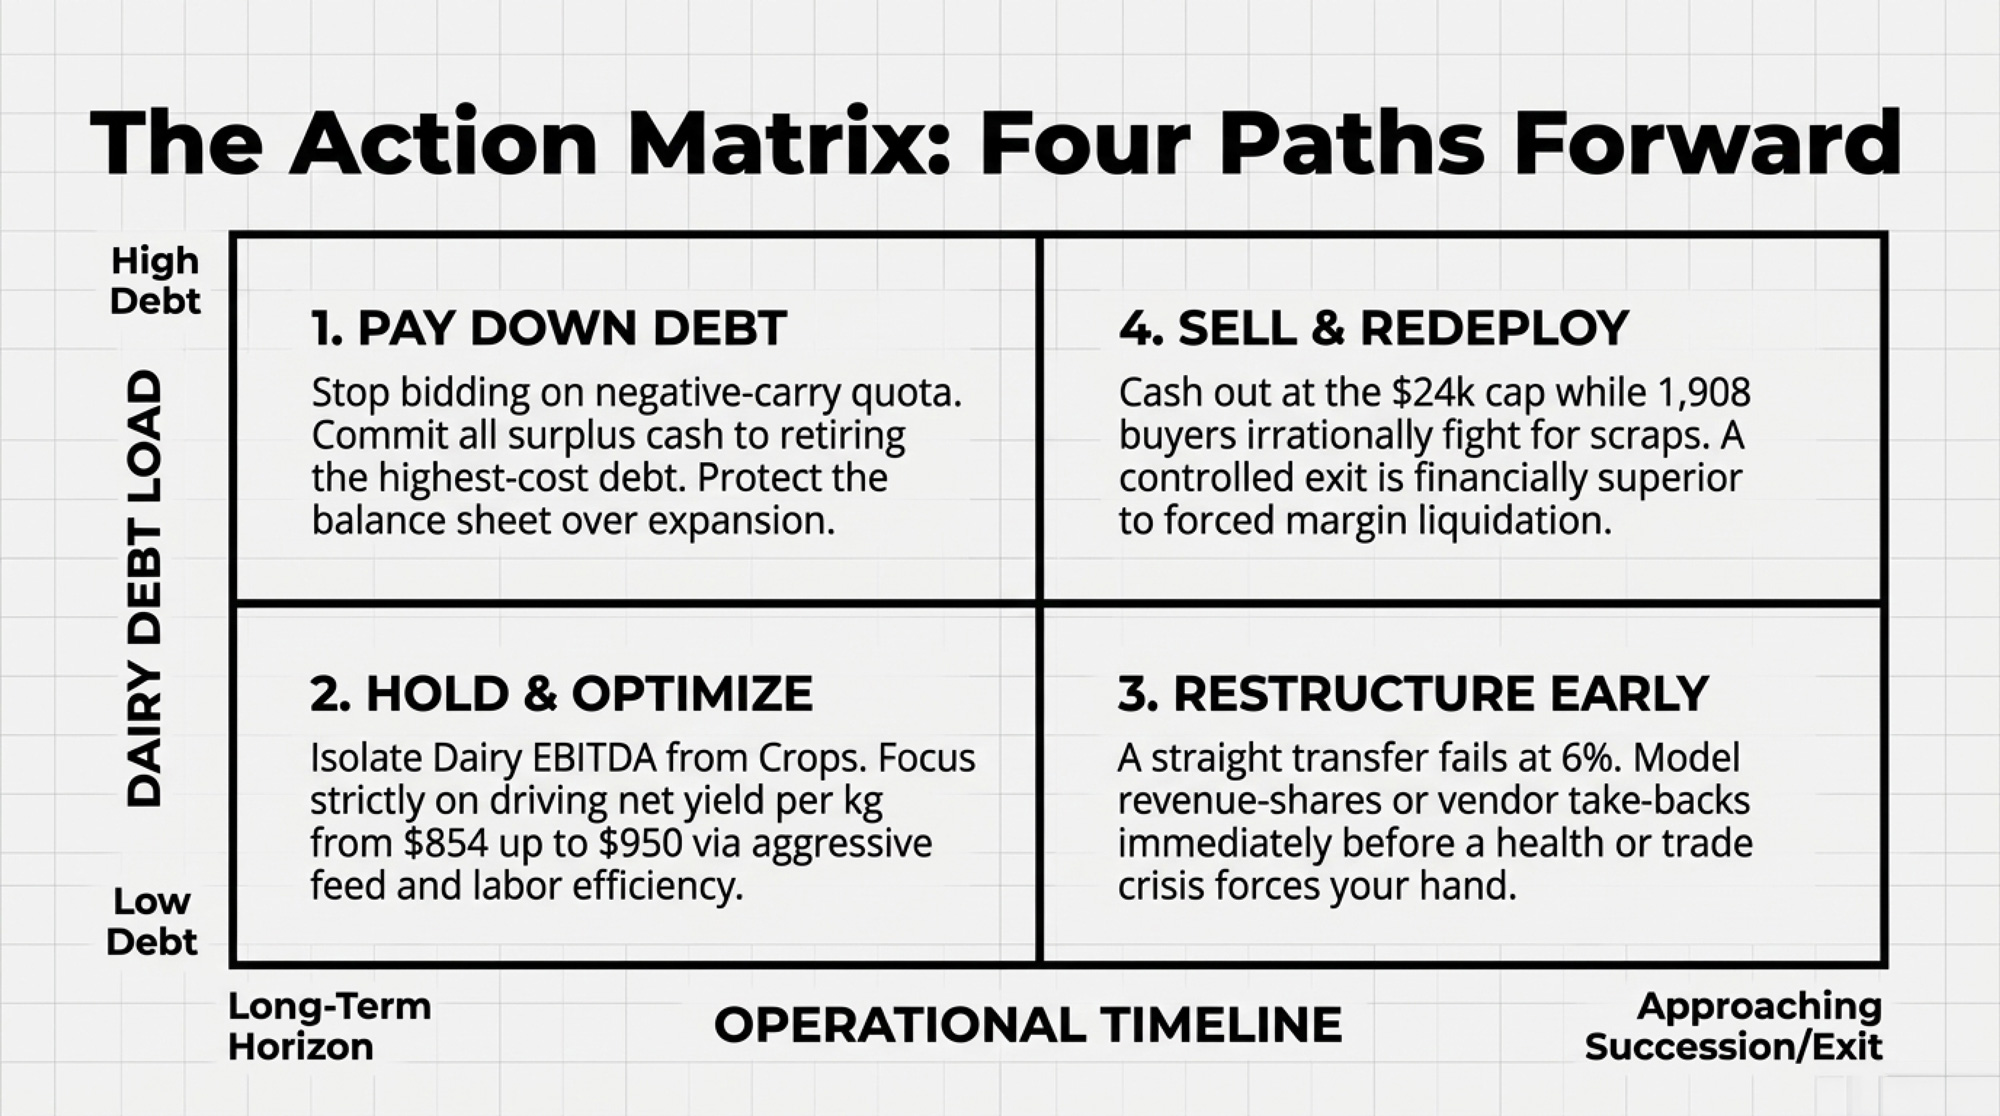
Eight matches a year against a reported farm count that fell by a net 34 is the trade-off this program lives inside, and priority access changes nothing in a month when the exchange has 167.79 kilograms to sell and needs 186.20 to open. Pull your last DFO exchange confirmation and your assistance schedule if you hold one, then check two lines: kilograms you own outright, and the anniversary date when recovery begins. Under clause 35, a transaction that drops a post-2021 entrant’s own quota below 20 kilograms costs the entire 20 kg of assistance.
Key Takeaways
- Eight assisted entrants a year is a Bullvine calculation from DFO’s published 160 kg pool and 20 kg match — DFO prints both inputs and never the quotient, and the ratio against a net 34-farm decline is the number to remember.
- Priority access only helps in a month when the exchange actually runs. Five of nine 2026 exchanges were cancelled, and August’s summary shows two selected entrants acquiring 0.00 kg.
- DFO’s annual report gives the New Producer Program a hard count — 135 of 156 currently shipping — while NEQAP gets “approximately 92 per cent remaining.” Without a cohort table, nobody outside DFO can tell whether the 2026 backlog is delay or attrition.
Ontario NEQAP Capital & Cash-Flow Stress Tester
Model quota debt, required cash equity, cow requirements, and DFO’s Year-11 recovery clawback under the C$24,000 cap.
Methodology Note. The eight-match ceiling divides DFO’s published annual pool of up to 160 kg by the 20 kg allocated per successful applicant under clause 25 of the Quota and Milk Transportation Policies revised June 1, 2026. Capital figures multiply the 20- to 30-kg purchase requirement by the C$24,000/kg cap recorded in DFO’s September 2026 exchange summary, printed September 2, 2026. The C$28,800 annual figure and the 16.7-year recovery period are Bullvine calculations from the 1.2 kg per 12-month take-back in clause 31. Cow counts apply stated butterfat assumptions of 1.20, 1.35, and 1.50 kg per cow per day, which are Bullvine assumptions and not DFO figures. Litre equivalents use Ontario’s May 2026 average composition of 4.3035 kg butterfat per hectolitre from Milk Producer, Dairynomics, July 2026 issue — a single month, not an annual average. Equity figures apply loan-to-value percentages published as market commentary by a mortgage brokerage, not underwriting policy from any lender. The farm-count comparison uses DFO’s own reported totals and measures net change, not gross licence exits, which DFO does not publish. Limits: these are Ontario figures under Ontario policy, the June 2028 exchange price cannot be known in September 2026, and provincial averages may not reflect your operation.
Learn More
- The 143-Hour Week at Clark Farms: The Real Math of On-Farm Creamery ROI and Your Time — Arms prospective producer-processors with the true capital outlays and labor balance sheets behind farm-level diversification before committing equity to on-farm infrastructure or processing facilities.
- The Bullvine Dairy Curve: 15,000 U.S. Farms by 2035 and Under 10,000 by 2050 – Who’s Still Milking? — Exposes long-term consolidation trajectories that drive producer exits across North America, charting herd-size survival thresholds and scale dynamics that determine who stays in business over the next three decades.
- The $586-Per-Kilo Dairy Quota Trap: Why New Ontario Quota at 6% Bleeds Cash Every Year — Breaks down the per-kilogram financial drag of borrowing at current interest rates, isolating the exact breakeven cash shortfall new entrants face when debt-financing Ontario exchange purchases.
The Sunday Read Dairy Professionals Don’t Skip.
Every week, thousands of producers, breeders, and industry insiders open Bullvine Weekly for genetics insights, market shifts, and profit strategies they won’t find anywhere else. One email. Five minutes. Smarter decisions all week.