










The T.C. Jacoby Weekly Market Report Week Ending March 26, 2021
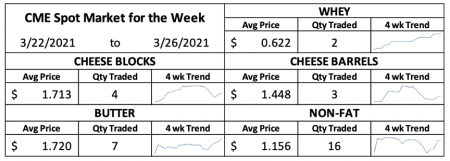
Cheese manufacturers report that demand has improved from both domestic and international sources. Even with improved demand, supply remains more than ample and inventories are growing.
 Spot cheese market observers are recovering from whiplash this week after watching the price dip then rally. Cheddar blocks lost 3¢ on Monday, 4.5¢ on Tuesday, and another 4.5¢ on Wednesday, before the winds changed course. Gains of 3¢ and 2¢ on Thursday and Friday helped to erase some of the loss, but at $1.72/lb. spot Cheddar blocks still finished the week 7¢ lower than last Friday. In the case of barrels, despite giving up 1.5¢ on Monday, modest gains on Tuesday, Thursday, and Friday pushed the price up to $1.4625/lb., a penny higher than last week. As a result, the block barrel spread narrowed to 25.75¢ on Friday.
 Cheese manufacturers report that demand has improved from both domestic and international sources. As Covid-19 dining restrictions are rolled back unevenly across the country, foodservice demand is firming, a trend that is likely to be particularly supportive for Italian style cheeses. Even with improved demand, however, supply remains more than ample, and inventories are growing. Total cheese stocks at the end of February reached 1.436 billion pounds, an increase of 27.8 million pounds compared to January. Though this increase exceeds the five-year average over the same period, it remains lower than the gains seen in 2017 and 2018. Other cheese stocks built somewhat faster than American cheese stocks, indicating that manufacturers have had more luck moving Cheddar and other American style cheeses into the market, likely through retail channels.
 On the other side of the Class III complex, whey prices showed no relenting this week, continuing their upward charge to hit yet a new record. Spot whey added 1.5¢ on Wednesday as two loads traded to move up to 62.75¢/lb., a new record for the three year old market. Demand is robust from both domestic and global users, even as logistical complications persist. Insatiable demand from China continues to underpin the global whey market. Chinese imports of whey hit a record high 277.1 million pounds during January and February, a 52.7% increase versus the same period last year after accounting for the leap day. Hefty Chinese dairy imports in January and February set records across many categories including milk powders and fluid milk.
 Moving over to Class IV products, the butter market was able to make up some ground this week. After seeing increases Tuesday through Friday, the spot butter price ended the week a full 11¢ higher than last Friday at $1.775/lb. Even as cream remains plentiful, foodservice activity has picked up and retail demand is robust as Easter and other spring holidays approach. Butter inventories totaled 352.7 million pounds at the end of February, an increase of 6.3% or 20.8 million pounds compared to January. This increase is less than half of the five-year average build of 43.5 million pounds between these two months, indicating that product is indeed moving into commercial channels. Nevertheless, butter stocks remain historically heavy, and the market will have to work through these inventories before returning to balance.
 After dropping 1.25¢ on Monday, the spot nonfat dry milk (NDM) market was also able to do an about-face. Moving upward on Tuesday and especially Thursday, when 12 loads traded hands, the market ended the week at $1.17/lb., up 1.75¢ compared to prior week. Plentiful condensed skim continues to stifle more dramatic price increases but demand has at least remained sufficient to keep some tension in the market. International demand from both Mexico and overseas markets has remained substantial though manufacturers report that higher prices are causing some global buyers to balk. At 192.6 million pounds Chinese imports of skim milk powder during January and February set a new record, though the vast majority of this product was supplied by New Zealand.
Even though the overarching demand picture appears to be brightening, there is still a risk that the gains will be outpaced by supply. Milk is plentiful, particularly in the West where the spring flush has arrived convincingly. Dairy Market News reports that milk production is heavy in California, with output rising in nearby states. Spot loads of milk are generally
available across the country and can be procured for processing needs at several dollars under the Class III price in the Midwest. Class I demand has slipped modestly over the last week as educational institutions have been on spring break but pull from the bottlers is expected to improve following the holiday.
The milk futures markets followed the trends set by the spot market. Most nearby Class III contracts lost value on Monday, Tuesday, and Wednesday before staging a bit of a recovery on Thursday and Friday, ultimately gaining some value over the course of the week. In the Class IV market, after bobbling earlier in the week, gains on Wednesday, Thursday, and especially Friday, pulled contract values up. Every Class IV contract between APR21 and SEP21 settled at least a quarter higher on Friday than on Monday.
The markets generally moved sideways as the trade waits for USDA’s Prospective Plantings report scheduled for release next week. High prices are expected to drive additional plantings of both corn and soybeans though the scale of the increase remains to be determined. Most nearby corn futures contracts settled no more than a couple cents different on Friday than on Monday. Soybean futures were a bit more active, moving up on Tuesday and Wednesday before descending again on Thursday and Friday. Though the moves weren’t enormous, most nearby contracts settled lower on Friday than on Monday.
Source: Jacoby




