









The T.C. Jacoby Weekly Market Report Week Ending April 16, 2021
USDA ends the Farmers to Families Food Box program after May, squelching hope surrounding the kind of government spending that propelled the cheese and Class III markets to unsustainable heights in 2020.
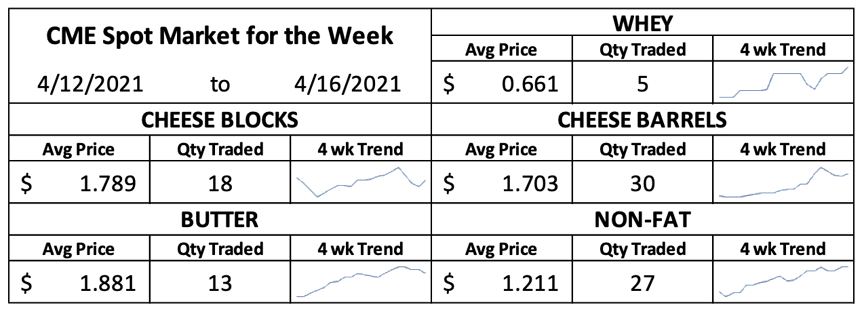
The government let a little air out of the milk markets this week. Most Class III and Class IV futures contracts lost between 10 and 30ȼ. For the past six weeks, cheese prices have climbed ever higher thanks to accelerating demand from restaurants and speculation that USDA would continue to buy and donate dairy at a heady clip. But on Tuesday USDA announced that it would end the Farmers to Families Food Box program after May, squelching hopes – and fears – surrounding the kind of government spending that propelled the cheese and Class III markets to unsustainable heights in 2020. Although the cheese markets staged a comeback today, they finished lower than where they began the week. CME spot Cheddar blocks dropped a nickel to $1.78 per pound. Barrels ultimately fell just a quarter-cent and closed at $1.69. Butter also weakened. Spot butter slipped 3ȼ to $1.85.
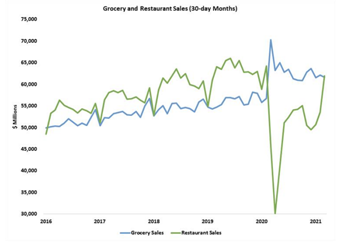 Demand for both cheese and butter remains strong, as restaurants restock and retailers have yet to pull back. Americans spent $127.7 billion at restaurants and grocery stores in March, the highest total on record. Grocers continue to ring up stellar sales, and spending at restaurants is almost back to pre-pandemic levels. At some point, consumers will pare back on grocery purchases as restaurant visits become more routine and their pantry shelves grow heavy. But for now, both food sectors are pushing product at a good clip.
 The protein powders continued to climb. CME spot nonfat dry milk (NDM) added a penny and reached a fresh 14-month high at $1.215. Spot whey jumped 4.5ȼ to 67.5ȼ, its highest price on record. Although the spring flush is in full swing, driers are running below capacity in the Great Lakes states as the new cheese plant laps up a greater share of the regional milk supply. Both domestic and export demand are strong, but logistics issues have slowed some sales. The container shortage and port backlogs add to the cost of freight and delay deliveries. Although U.S. milk powder is priced to move, the freight issues are likely trimming sales – and prices – at the margin. But tightening milk powder stocks in Oceania and low output in Europe suggest the U.S. will continue to fare well in foreign markets.
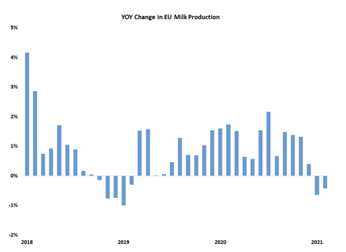
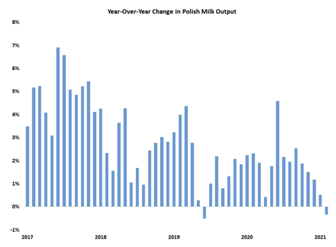 European milk collections were just shy of 27 billion pounds in February, assuming steady milk production trends in Sweden. Adjusted for leap day, that is 0.4% lower than in February 2020, following a 0.7% shortfall in January. Output fell below year ago levels in all the major dairy nations except the United Kingdom, Italy, and Ireland. Polish milk collections were 0.3% lower than in February 2020, a rare decline for one of Europe’s most consistent sources of growth. Lower European milk output helped to offset about 40% of the growth in U.S. milk production in the first two months of the year.
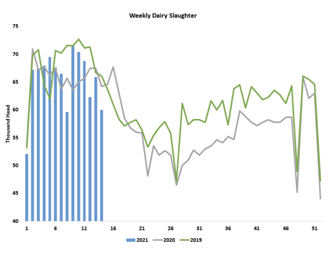
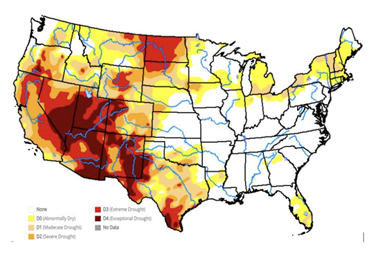 U.S. milk output remains strong, but expenses are on the rise. Feed costs are starting to bite, especially in the West, where dairy producers must pay unusually steep freight rates on top of already high grain and protein prices. Regional drought and scarce inventories compound the Western feed shortage and raise the cost of milk production noticeably. Pricey inputs will weigh on milk output eventually. However, given the massive milk-cow herd and relatively low slaughter rates, milk production is likely to remain formidable in the near term. Fortunately for dairy producers, strong demand has supported dairy product values.
 May corn futures topped $6 per bushel this week for the first time since 2013, when the industry struggled to rebuild inventories after the devastating 2012 drought. Aside from concerns that it’s a bit too dry in Brazil, there are no serious crop issues to fuel this year’s rally. But demand is formidable. Livestock numbers are up, and drought in the West will push cattle out of grasslands and into feedlots. Exports are booming. May corn settled at $5.855, up another 8.25ȼ from last week. December corn finished at $5.1225, 14ȼ higher than last Friday. May soybeans jumped more than 30ȼ to $14.3325. May soybean meal finished a dollar higher, at $402.20 per ton.
Original Report at: https://www.jacoby.com/market-report/government-lets-air-out-of-the-milk-markets-this-week/




