Archive for Dairy Markets – Page 58

CME Markets show gains on Wednesday

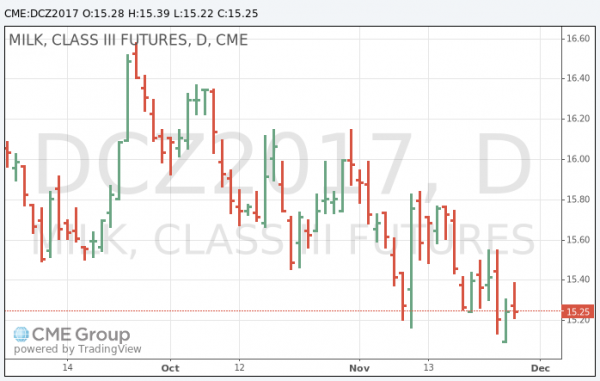
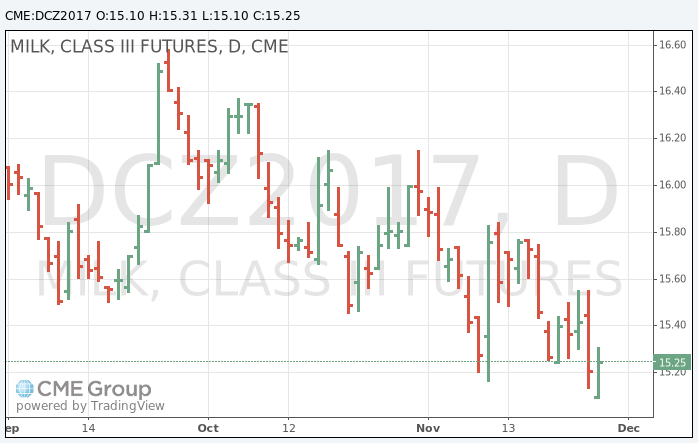
At the Chicago Mercantile Exchange, the Dairy markets made some gains on Wednesday. December Class III milk futures were up $.01 at  $15.42. January milk was up $.06 at $14.00.  February was up $.06 at $13.61.  March was up $.02 closing at $13.62.  April was up $.02 at $13.92.  The rest of the 2018 milk futures were all up a little or unchanged.

Grade AA Butter was up $.0325 closing at $2.2025.  One carload was sold at that price. Barrels were up $.02 to $1.44.  Three carloads were traded ranging from $1.42 to $1.44. 40-pound blocks were also up  $.02 to $1.5075.  Two carloads of blocks were traded at $1.4975 and $1.5075. Nonfat dry milk was up $.01 closing at $.66.  Two carloads were sold for $.6525 and $.66 cents per pound.

Dairy prices wobble through holidays

Cash dairy prices weakened the week before Christmas though cheese and powder regained a little ground at week’s end.

A somewhat bullish Milk Production report may have been partly responsible but traders were also anticipating the November Cold Storage report.

CME block Cheddar fell to $1.4350 per pound last Wednesday, lowest price since March 21, 2017, but jumped a nickel Friday to close at $1.4925, down 3 3/4-cents on the week, down 22 1/4-cents since Nov. 3, and 19 3/4-cents below a year ago when they dropped 11 cents.

The barrels dipped to $1.40 last Wednesday, the lowest price since July 10, 2017, but closed Friday at $1.41, down 25 cents on the week, 14 1/2-cents below a year ago when they dropped 14 1/2-cents, and they reversed the inverted spread to 8 1/2-cents below the blocks. Nine cars of block traded hands last week at the CME and 42 of barrel.

The markets were closed Christmas Day but Tuesday’s trading took the blocks down a penny, to $1.4875, while the barrels were up a penny, to $1.42.

Cheese producers accepted spot milk at marked discounts last week, according to Dairy Market News, ranging $4 to $8 under Class III. Cheese sales remained steady to slow. DMN said there would be some allotted days off during the holidays but plants plan to ramp up cheese production to meet the abundant milk intakes.

Western cheese makers report solid domestic retail and food service demand has generally helped support the cheese market this fall. However, as holiday shipment obligations are fulfilled, there is concern that there may be a lull following the winter holidays, before the football playoffs.

Cash butter finished Friday at $2.18 per pound, down 6 1/2-cents on the week and 6 3/4-cents below a year ago, the first time in almost a year that it fell below a year ago. Seventeen cars found new homes last week.

The butter lost a penny Tuesday, slipping to $2.17, lowest price since $2.13 on May 10, 2017.

DMN says butter sales are on par with previous years. Holiday retail orders are completed, thus food service is now one of the priorities on the production side. Cream has been abundant but the market tone remains somewhat resilient.

The western butter market was steady to weak last week. Contacts report that prices are higher than expected as holiday orders have mostly been fulfilled and butter supplies are plentiful. Some buyers are expecting and waiting for further price decreases so they are limiting purchases to their immediate needs.

Cash Grade A nonfat dry milk set a record low of 64 3/4-cents per pound last Tuesday; however, it closed Friday at 66 1/2-cents, up three quarter-cents on the week but 35 1/2-cents below a year ago, with 17 cars exchanging hands on the week.

The powder gave up a penny and a half Tuesday, falling to 65 cents per pound.


Plentiful supply


The Agriculture Department’s last Cold Storage report of 2017 shows Nov. 30 butter stocks stood at 158.8 million pounds, down 59.1 million pounds or 27 percent from October and 2.4 million or 1 percent below November 2016.

American type cheese, at 733.2 million pounds, was down 7.2 million pounds or 1 percent from October but 20 million or 3 percent above a year ago. The other cheese category totaled 500.3 million pounds, down 1 percent from October but 13 percent higher than a year ago. The total cheese inventory was down 9.3 million pounds or 1 percent from October but 76 million pounds or 6 percent above a year ago.

FC Stone says the large jump in the “other cheese” category may indicate that we are producing quite a bit more mozzarella and that may have had something to do with the wide barrel/block inversion.


Culling nose-dives


U.S. dairy cow culling nose-dived in November but was up slightly from November 2016. The Agriculture Department’s latest Livestock Slaughter report shows an estimated 243,700 head were slaughtered under federal inspection, down 17,300 head from October but 500 head above a year ago. Culling in the first 11 months of 2017 totaled 2.74 million head, up 108,000 from a year ago.


Class I down


The first Federal order Class I base milk price of 2018 was announced by the USDA at $15.44 per hundredweight, down $1.44 from December 2017, $2.01 below January 2017, and equates to about $1.33 per gallon, down from $1.45 in December. It is the lowest Class I price since June 2017

Source: Capital Press

Dairy markets down after Christmas Break

Dairy markets were down Tuesday on the Chicago Mercantile Exchange, with the exception of blocks,

December Class III milk futures were down $.02 at  $15.41. January milk was down $.08 at $13.94.  February was down $.09 at $13.55.  March was down $.07 closing at $13.60.  April was down $.05 at $13.90.  The rest of the 2018 milk futures were all down except for a $.06 gain in September.

Grade AA Butter was down $.01 closing at $2.17.  One carload was sold Tuesday at that price. Barrels were up $.01 closing at $1.42.  Three carloads were traded at that price. 40-pound blocks were down  $.005 to $1.4875.  Eight carloads of blocks were traded, ranging from $1.48 up to $1.4925. Nonfat dry milk was down $.015 closing at $.65.  Four carloads were sold ranging from $.6450 to $.6525.

Cash dairy markets break records

Records were broke in last week’s cash dairy markets. CME block Cheddar fell to $1.4450 per pound on Dec. 12 but then rallied and closed Friday at $1.53, up 5 1/2-cents on the week and reversed six weeks of decline, but was 27 cents below a year ago.

The barrels closed at $1.66, down a penny, 4 cents below a year ago, and 13 cents above the blocks after setting a record inverted spread of 22 1/2-cents last Tuesday. They also set a record single day volume Monday, selling 36 cars, highest since daily trading started Sept. 1, 1998 and surpassed the previous high of 35 loads set June 18, 2010, according to FC Stone. A total of 97 cars were sold last week at the CME and just 7 of block.

The blocks lost 4 cents Monday, as traders anticipated Tuesday morning’s Global Dairy Trade auction and the afternoon’s November Milk Production report. They gave up another 4 cents Tuesday, dipping to $1.45, the lowest block price since March 29, 2017.

The barrels lost 8 cents Monday and plunged a dime Tuesday, to $1.48, lowest barrel since July 27, 2017, but narrowed the spread to 3 cents above the blocks, a spread that typically runs 3-5 cents below the blocks.

Dairy Market News reports that milk remains readily available to Midwestern cheese plants and some cheese producers warned that only heavily discounted milk offers will be considered for the remainder of 2017.

Western cheese output is ongoing as milk is also plentiful. Processors are hesitant to take on additional milk due to the weakness of cheese prices and ample supplies.

Cash butter slipped to $2.19 per pound last Monday, then reversed gears and slowly climbed to $2.26 Thursday, but saw a Friday close at $2.2450, up 2 1/2-cents on the week and 5 1/2-cents above a year ago when it jumped 12 1/2-cents. 40 cars traded hands last week at the CME.

The butter was down 4 1/2-cents Monday but gained a penny Tuesday, inching back to $2.21 per pound.

Central region butter producers report that orders are back in line with expectations following a slow start to the month. Cream remains abundant but the market tone remains resilient.

Western butter makers report that demand is following typical seasonal patterns. Inventories have been drawn down, but cream is becoming less expensive and readily available.

Cash Grade A nonfat dry milk also set a record last week, unfortunately a record low of 65 3/4-cents per pound, down 2 1/2-cents on the week and 36 1/4-cents below a year ago.

The powder inched three-quarter cents lower Monday and a quarter-cent Tuesday, sliding to another record low of 64 3/4-cents per pound.

November milk up

November milk output was up for the 47th consecutive month in the U.S., totaling 16.2 billion pounds in the top 23 states, according to preliminary USDA data, up just 1.1 percent from November 2016. The 50-state total at 17.3 billion pounds, was up 1.0 percent. Revisions lowered the original October 23-state estimate by 27 million pounds, now put at 16.7 billion pounds, up 1.3 percent from a year ago.

Milk cow numbers totaled 8.73 million head in the 23 states, unchanged from October but 57,000 more than a year ago. The 50-state total, at 9.4 million head, was unchanged from October but 53,000 above a year ago. Output per cow averaged 1,861 pounds in the 23 states, up 9 pounds.

California output trailed its year ago data for the 11th consecutive month, down 34 million pounds or 1.1 percent, due to 14,000 fewer cows milked and a 5 pound loss per cow. Wisconsin was up just 0.9 percent, on a 20-pound gain per cow but cow numbers were down 1,000 head from a year ago.

New York edged out Idaho for the No. 3 slot, though output was off 0.3 percent, due to a 20-pound loss per cow. Cow numbers were up 5,000. Idaho was down 0.6 percent on a 15-pound drop per cow and cow numbers were up 100. Pennsylvania was up 2.1 percent, thanks to a 35-pound gain per cow. Cow numbers were unchanged. Minnesota was up 1.5 percent, on a nice 40-pound gain per cow offsetting a 4,000 cow loss.

Michigan was up 2.2 percent on a 20-pound gain per cow and 5,000 more cows. New Mexico was up 2.0 percent on 6,000 more cows and a 5-pound gain per cow. Texas was up 5.9 percent, thanks to 25,000 more cows and a 15-pound gain per cow. Washington state was off 0.8 percent on a 5-pound loss per cow and 1,000 fewer cows. Analysts see the report feeding the bulls.

GDT drops

Hemorrhaging in the Global Dairy Trade auction was back Tuesday, the last GDT of 2017. All products offered suffered losses, with the weighted average plunging 3.9 percent, after inching up 0.4 percent on Dec. 5, reversing a 3.4 percent drop Nov. 21 and 3.5 percent on Nov. 7.

Cheddar led the declines, down 7.9 percent after dropping 3.9 percent Dec. 5. Anhydrous milkfat was down 6.7 percent, after inching 0.6 percent lower last time. Skim milk power was down 4.8 percent, after leading the gains last time with a 4.7 percent uptick. Whole milk powder was down 2.5 percent, following a 1.7 percent gain, and butter fell 2.3 percent after an 11.1 percent meltdown last time.

HighGround Dairy equated the GDT butter price to $2.03 per pound U.S. CME butter closed Tuesday at $2.21. GDT Cheddar cheese equated to $1.54 per pound U.S. and compares to Tuesday’s CME block Cheddar at $1.45. GDT skim milk powder averaged 76 cents per pound and whole milk powder averaged $1.25 per pound U.S. CME Grade A nonfat dry milk price closed Tuesday at 64 3/4-cents per pound.


Source: Capital Press

Dairy markets were mostly up Thursday

In Chicago, Thursday dairy markets were mostly up at the CME. December Class III milk futures were unchanged at  $15.44. January milk was up $.17 at $13.97.  February was up $.14 at $13.70.  March was up $.12 closing at $13.75.  The rest of the 2018 milk futures were all slightly up or unchanged.

Grade AA Butter fell down $.015 closing at $2.18.  Two carloads of butter were sold ranging from $2:1775 to $2.18. Barrels were up $.0025 closing at $1.4025.  No barrels were traded Thursday. 40-pound blocks were up $.0075 to $1.4425.   Nonfat dry milk was up fractionally, ending a slide of record low prices.  Prices were up  $.0125 closing at $.66.  Two carloads were sold with one going for $.6550 and the other at $.66.

Dairy markets were ­­­­mostly lower Wednesday

At the Chicago Mercantile Exchange on Wednesday the dairy markets were mostly lower, following decreases in federal order prices for Class I milk as well follow through selling and increased milk production forecasts set by the EU. Class III milk futures for December were unchanged at $15.44 Wednesday. January milk closed $0.13 lower at $13.80. February closed down $0.08 to $13.56. March was down $0.15 at $13.63.

Grade AA Butter closed down $0.0150 at $2.1950. Twenty-one carloads of butter were sold on a range of $2.1925 to $2.22. Barrels were down $0.08 to $1.40. Eleven carloads were sold ranging from $1.42 to $1.4450. 40-pound blocks closed $0.0150 lower at $1.4350. One trade was at $1.42.

For January, the USDA has set the base Class I milk price at $15.44 per hundredweight, down $1.44 from December, with the base Class I skim price at $6.98, down $1.32.

The USDA reports cash butter for the week ending December 16th averaged $2.22 per pounds, $0.01 lower than the previous week. 40 pound blocks of cheddar were pegged at $1.79, $0.0650 lower. 500 pound barrels averaged $1.63, a decrease of $0.03. Dry whey came out at $0.315, up $0.023. Nonfat dry milk averaged $0.727, up $0.003.

Dairy prices tumble to 14-month low, amid signs of buoyant milk output

Dairy prices fell to a 14-month low at GlobalDairyTrade auction, defying strength in whole milk powder futures, as prices felt pressure from raised sales volumes, and buoyant milk output signs.

The GlobalDairyTrade index dropped 3.9% at Tuesday’s auction, the last of 2017, to 935 points, its lowest since October last year.

The decline, which meant the index finished down 13.1% for the year, defied indications from New Zealand’s NZX market of higher prices.

Best-traded whole milk powder futures for March closing earlier on Tuesday at $2,990 a tonne, up 2.7% since the previous GlobalDairyTrade auction, two weeks ago, after a rally spurred by worries over dryness in major producing regions in New Zealand, the top milk-exporting country.

Skim milk, milk fat price tumbles

However, data this week from Dcanz, the New Zealand dairy industry group, revealed domestic milk output up 3.3% last month at 242.6m kilogrammes of milk solids.

Fonterra, the Auckland-based dairy giant which runs GlobalDairyTrade, ahead of Tuesday raised by more than 10,000 tonnes, to 643,000 tonnes, its forecast for product volumes it intended to sell through the event over the next 12 months.

“This change reflects an increase of 6,000 tonnes for skim milk powder and 4,180 tonnes for anhydrous milk fat,” Fonterra said, flagging “strong market demand” for both products.

Nonetheless, skim milk powder prices fell by 4.8% at the auction to a 19-month low, while anhydrous milk fat values by 6.7%.

Prices of whole milk powder, which accounts for the bulk of volumes sold through GDT dipped by 2.5%.

‘Bursting with powder’

Values of anhydrous milk fat remain up 19.1% for 2017 despite Tuesday’s setback – contrasting with a 36% slump in GlobalDairyTrade prices of skim milk powder.

Skim milk powder prices have felt particular pressure from larger-than-expected output in the European Union, the top producer and exporter of the commodity, where production has been supported by a European Commission intervention scheme buying which has created a stocks mountain of some 400,000 tonnes.

The EU’s “substantial” skim milk powder inventories “will continue to weigh on global skim milk powder markets”, the US Department of Agriculture said in a briefing on Friday.

In the US itself, prices of Chicago-traded non-fat dry milk futures have continued to underperform, with December futures last week touching spot 72.63 cents per pound, a record low for a spot contract.

“Warehouses in the US and Europe are bursting with powder, and driers are running hard for the holidays,” the US-based Milk Producers Council said.

‘Continued sharp correction’

Butter values fared a little better at GlobalDairyTrade, in falling by 2.3% to $4,474 a tonne, to leave the commodity with gains of 4.3% for 2017 as a whole.

The relative resilience defied a caution from the USDA that “for 2018, the price outlook points to a continued sharp correction in butter prices,” although the department did add that “strong consumer demand should keep prices from dropping far below $4,000 a tonne”.

Indeed, the USDA said that “given the dismal outlook” for the market for skim milk powder, manufactured as a co-product of butter output, “it appears that processors are unwilling to churn more butter at the risk of carrying burdensome supplies of co-products”.

Source: Agrimoney

Dairy markets were mostly down Tuesday

At the Chicago Mercantile Exchange on Tuesday dairy markets were mostly down. December Class III milk futures finished down $.06 at  $15.44. January milk was down $.12 at $13.93.  February was down $.20 at $13.64.  March was down $.20 closing at $13.78.  The rest of the 2018 milk futures were all down.

Grade AA Butter was up $.01 closing at $2.21.  Nine carloads of butter were sold ranging from $2:19 to $2.21. Barrels were down $.10 closing at $1.48.  Seventeen carloads of barrels traded between $1.48 and $1.5550. 40-pound blocks fell $.04 to $1.45.  One carload of blocks sold at $1.45. Nonfat dry milk fell again, closing down $.0025 at $.6475.  Two carloads were sold with one going for $.65 and the other at $.6450.

Dairy markets down Monday in Chicago

At the Chicago Mercantile Exchange dairy markets continued to fall as the new week of trade began. December Class III milk futures finished unchanged at  $15.50. January milk was down $.35 closing at $14.05.  February was down $.38 at $13.84. March was down $.34 closing at $13.98.  The rest of the 2018 milk futures were all down or unchanged.

Grade AA Butter was down $.045 Monday closing at $2.20.  Six carloads of butter were sold ranging from $2.1925 to $2.2275. The spread between barrels and blocks remains wide, but both went down Monday. Barrels were down $.08 closing at $1.58.  Eleven carloads of barrels traded between $1.5875 and $1.63.


New Zealand Stock Exchange to extend dairy derivatives trading session

The New Zealand Stock Exchange (NZX) said on Tuesday it would extend trading by six hours in its dairy derivatives market from July 2018, citing higher global demand.

NZX said it would keep the market open until 10 p.m. (1000 GMT) instead of closing at 4 p.m. (0400 GMT), adding that opening times would remain unchanged.

“The extended market hours will facilitate easier trading between Europe and Asia, two key dairy trading regions,” NZX said in a statement.

NZX’s dairy derivatives volumes have grown 57 percent in the year to date and it has added 208 unique users over the same period, which is up 58 percent from the previous year.

“This extension will also enable key dairy buying regions, such as the Middle East and Africa, greater access to NZX’s dairy derivatives market,” NZX derivatives head Nick Morris said.

NZX said it would collaborate with participants and clearers, as well as software and data vendors in early 2018 on the changes.

Source: KITCO

Low milk prices affect struggling dairy farms in the Valley

Many local dairy farms have been forced out of business in recent years.

A low milk price at the grocery store might seem like a good thing for your wallet, but it can actually hurt local dairy farmers.

Most dairy farmers need $19 per hundred-weight of milk to be profitable.

According to The University of Wisconsin-Madison’s Brian Gould, in 2015, the price was $17.13.

In 2016, it had dropped to $15.97, and in 2017, the price was back up to $17.54.

In 2018, prices are set to be around $14 and lower.

“It was very much a joy to grow up on a family farm,” said Teresa Callender. “I’m the sixth generation on the dairy farm.”

Walkup Holsteins has been in operation for a century.

Due to competitive milk prices in Europe, Canada, and here at home, they’re forced to look at other options.

“We are basically looking at diversifying,” said Callender. “We have tried to control our expenses, and we’ve got them pulled down to the point that we just, we can’t pull them down a whole lot further.”

“We are being more efficient, and more efficient,” said Randy Inman.

Mar-Bil Farm has three generations.

“Our grandkids want to farm,” said Inman.

His daughter Karen, her husband Jason, and their three children also live and work on the farm.

“It’s going to be hard for us to sustain that until they grow up,” said Hewitt.

“We haven’t been replacing equipment,” said Inman. “We need to! You know?”

Simply adding more cows to an operation is not always an option.

“We just don’t have the facilities and, obviously, we can’t expand right here,” said Callender.

“I feel like it’s going to take the government kind of intervening,” said Hewitt.

Some expenses, such as caring for the cows, won’t go away.

“We can’t jeopardize their health and just not do those type of things, so those expenses will always be there,” said Callender.

You can help by trying to purchase locally-produced milk when you shop.

The Rockingham Cooperative is also partnering with the Harrisonburg Baptist Church to purchase cheese made from local milk and donate it to those in need in the area.


Source: WHSV 3

Dairy prices were mostly higher Wednesday

At the Chicago Mercantile Exchange, Dairy prices were mostly higher on Wednesday. Class III milk futures for December were up $.01 closing at  $15.61.   January milk was up $.23 closing at $14.50.  February was up $.17 at $14.36.  March was up $.12 closing at $14.45. The rest of the 2018 milk futures were mixed.

Grade AA Butter closed up $.005 at $2.2125.  Three carloads of butter were sold with one selling at $2.2125. Barrels were unchanged at $1.67.  Sales were up again, with 16 carloads of barrels trading at that price. 40-pound blocks closed up $.01 at $1.4550.  One carload of blocks was sold.   Nonfat dry milk has dropped to a new all-time low for the second day in a row, down another $.01 at $.67.  Nine carloads were sold Wednesday, with three of them topping at $.67 a pound.

USDA Drops Milk Production Forcast

USDA’s World Agricultural Supply and Demand Estimates dropped the forecast for milk production in 2017. Trend could continue into 2018.

The milk production forecast is lowered for 2017 on slower growth in milk per cow. The slower growth in milk per cow is expected to carry into 2018 and combined with an expected slower rate of growth in cow numbers, the 2018 milk production forecast is lowered. The 2017 and 2018 fat basis import and export forecasts are unchanged from the previous month. On a skim-solids basis, the 2017 and 2018 export forecasts are raised on higher expected whey exports. No changes are made to 2017 and 2018 skim -solids basis import forecasts.
 
Price forecasts for cheese, butter, and nonfat dry milk are lowered for 2017 on current price weakness and slower demand. The 2017 whey price forecast is unchanged at the midpoint. All dairy product price forecasts are reduced for 2018 on pressure from large stocks and slower expected demand. Class III and Class IV price forecasts are lowered for 2017 and 2018, reflecting the lower product prices. All milk prices are forecast lower at $17.60 to $17.70 per cwt for 2017and $16.65 to $17.45 per cwt for 2018.

USDA’s negative price forecasts pushes markets lower

At the CME on Tuesday the Dairy markets were ­­­­lower in reaction to USDA’s negative price forecasts for 2017 and 2018. Class III milk futures for December were down $.01 closing at $15.60. January milk was down $.07 at $14.27. February closed down $.07 to $14.33. March was down $.07 at $14.33.

Grade AA Butter closed up $.0175 at $2.2075. Twenty-one carloads of butter were sold on a range of $2.1925 to $2.22.

The cash cheese spread ended Tuesday with a fresh all-time high. Barrels were unchanged at $1.67. Nineteen carloads were sold ranging from $1.66 to $1.67.


Dairy prices were mostly lower again

At the Chicago Mercantile Exchange on Monday, Dairy prices were mostly lower again. Class III milk futures for December were the exception, up $.01 closing at  $15.61.  All other milk futures through 2018 went down. January milk was down $.04 closing at $14.34.  February was down $.06 at $14.26.  March was down $.10 closing at $14.41.  

Grade AA Butter closed down $.03 at $2.19.  Three carloads of butter were sold with two selling at $2.20. Barrels were unchanged at $1.67.  Sales were up, with 36 carloads of barrels trading between $1.6675 and  $1.6725. 40-pound blocks closed down $.0175 at $1.4575.  Three carloads of blocks were sold ranging from $1.4575 to $1.48.  


Dairy prices were mostly down

At the Chicago Mercantile Exchange dairy prices were mostly down on Wednesday trading.   Class III milk futures for December were unchanged at  $15.42. January milk was down $.05 closing at $14.24.  February was down $.06 at $14.25.  March was down $.05 closing at $14.42.  Most of the 2018 milk futures market saw similar losses except for a penny gain in September.

Grade AA Butter closed up $.0250 closing at  $2.225.  Twenty carloads of butter were sold with two topping at $2.225. Barrels were up $.0075 closing at $1.57.  Eight carloads of barrels were sold ranging from $1.5625 to $1.57. 40-pound blocks dropped $.0425 to $1.47.  Nine carloads of blocks were sold ranging from $1.47 to $1.505.   Nonfat dry milk ended the day unchanged at $.7125.  No sales were recorded.

Dairy prices were mostly up Tuesday

At the Chicago Mercantile Exchange dairy prices were mostly up Tuesday with Class III milk futures for December were up $.05 to $15.42. January milk was up $.01 closing at $14.29.  February was down $.03 at $14.31.  March was unchanged at $14.47.  The milk futures market also saw some small gains in April, May, and June. Grade AA Butter closed up $.01 closing at  $2.20.  

November NMPF Dairy Market Report

U.S. Cheddar cheese prices hit a 10-month high in October, while butter prices softened but remained well above $2 a pound. Nonfat dry milk and dry whey prices are showing extended weakness due to deteriorating prices in world markets, which are overhung by excessive stocks of skim milk powder in the European Union (EU).

Against this backdrop of prices, there are some recent signs that overall supply has been gradually heading back toward balance with demand in U.S. domestic dairy markets. These include: (1) year-over-year growth in milk production well below 2 percent, (2) slower growth in cheese production, (3) further reduction in cheese stocks and (4) continued growth in cheese exports.

The Dairy Market Report is produced by the National Milk Producers Federation with support from Dairy Management, Inc.

The report is available on the NMPF web site: http://www.nmpf.org/dairy-market-report

Milk futures were mixed, mostly lower, on long term demand uncertainties

At the Chicago Mercantile Exchange Class III milk futures were mixed, mostly lower, on long term demand uncertainties. Class III milk futures for December were up $.05 to $15.37. January milk was down $.21 closing at $14.28. February was $.22 lower at $14.34. March closed $.16 lower to $14.47. The milk futures markets saw losses for the every since June.

Cash cheese blocks were $.0425 lower at $1.52. Five loads were sold, including two at $1.53 and three at $1.52. Barrels were up $.0150 to $1.55. Eleven loads were sold, ranging from $1.5375 to $1.55. Butter was $.0250 lower at $2.19. Eight loads were sold, ranging from $2.1850 to $2.20. Nonfat dry milk was $.01 lower at $0.71.

Cooperatives Working Together recently announced the acceptance of 20 requests for export assistance from member co-ops, covering 3.351 million pounds of Cheddar, Gouda, and Monterey Jack cheeses, along with 55,116 pounds of butter. The products are headed to Asia, with delivery slated for December 2017 through February 2018.

Exports key to higher U.S. milk prices in 2018

USDA’s milk production report shows October production increased to 1.4% higher than a year ago; September production was 1% higher than a year ago.

“This is a lot of milk considering that last year, milk production was running 2.5% higher than a year ago,” says Bob Cropp, University of Wisconsin Extension dairy economist.

The October increase was the result of 0.7% more cows and just 0.6% more milk per cow.

“Overall the increase in milk production will put some downward pressure on milk prices,” Cropp says.

The September Class III price was $16.36. The normal seasonal increase in dairy product sales helped boost the October Class III price to $16.69.

USDA’s milk production report shows October production increased to 1.4% higher than a year ago; September production was 1% higher than a year ago.

“This is a lot of milk considering that last year, milk production was running 2.5% higher than a year ago,” says Bob Cropp, University of Wisconsin Extension dairy economist.

The October increase was the result of 0.7% more cows and just 0.6% more milk per cow.

“Overall the increase in milk production will put some downward pressure on milk prices,” Cropp says.

The September Class III price was $16.36. The normal seasonal increase in dairy product sales helped boost the October Class III price to $16.69.

“The November Class III is expected to be up slightly to around $16.80,” Cropp says. “But dairy product prices have declined, meaning the December Class III price could fall below $16, to around $15.45.”

Milk prices higher in 2017
That puts the average for 2017 at about $16.15, compared to $14.48 last year – an increase of more than a $1.65.

According to Cropp, the Class III price is driven by the price of butter, cheddar cheese and dry whey. The price of butter on the Chicago Mercantile Exchange averaged $2.65 per pound in August, but declined steadily since then, hitting $2.21 at the end of November. The amount the price declined is a little surprising in that September butter production was 0.3% lower than a year ago and Sept. 30 stocks were 4.5% lower than a year ago. But butterfat exports, which had been running higher than a year ago, fell 16% in September, resulting in year-to-date exports up just 9%. Butterfat exports had been aided by Europe butter being priced higher than U.S. butter on the world market. The price of butter could still fall further, but should stay above $2 per pound.

Cheddar cheese prices were above $1.70 per pound in October and the first two weeks in November. But both cheddar blocks and barrels are now below that mark — barrels are $1.64 and blocks, $1.60. Cheese stocks remain ample, with Sept. 30 American cheese stocks 4.7% higher than a year ago and total cheese stocks 5.7% higher.

Cheese production has been relatively strong, with September production of cheddar cheese 4.5% higher than a year ago and total cheese production 2.7% higher. Domestic cheese sales have been fair. But cheese prices have benefited from higher exports. September cheese exports were 23% higher than a year ago and 24% higher year to date.

According to the U.S. Dairy Export Council, the European Union exported 43% more skim milk powder from January through August compared to the previous year. Canada, with aggressive pricing below both the EU and the U.S., has increased exports of skim milk powder. Canada previously was exporting about 1,000 tons of skim milk powder per month but is now exporting 8,000 to 10,000 tons.

“In addition, Mexico having concerns about the outcome of current NAFTA negotiations has reduced its source of nonfat dry milk imports from the U.S.,” Cropp says. “Mexico last year sourced 94% of its nonfat dry milk from the U.S. This has dropped to 77%, as Mexico is now sourcing from both the EU and Canada. As a result, the price of nonfat dry milk has fallen to $0.715 per pound, a level not seen since early last year.”

USDA and other forecasters have lowered their price forecast for 2018. Both Class III and Class IV futures for 2018 have fallen. Class III futures are in the $14s from January through May and in the $15s for the remainder of the year. Class IV futures start the year below $14, and reach the $14s by March and the $15s by August. If these prices hold true, milk prices in 2018 will average lower than 2017 prices. USDA reports the Class III price in 2018 could average as low as $15.50 and the Class IV price as low as $14.15. But according to Cropp, final milk prices will depend on the level of milk production, domestic sales and exports.

USDA is forecasting an increase in 2018 milk production of 1.8%, from a 0.5% increase in the average number of milk cows and 1.3% more milk per cow. This is a lot of milk, Cropp says, “but if milk prices start the year near current futures market prices, we could see heavier culling of milk cows and a lower increase in milk per cow.”

All eyes on exports
Domestic sales of butter and cheese should continue to be favorable in 2018, Cropp says. But he believes a crucial factor in where milk prices end up will be dairy exports.

“For most of this year, milk production for four major exporters — EU, New Zealand, Argentina and Australia — was lower than the year before. The U.S. was the exception with increased production,” Cropp says. “But milk production has now started to increase in all five exporters, meaning the U.S. will face strong competition for markets in 2018. Unless there is good growth in world demand to absorb this increase in milk production, world dairy product prices will decline.”

China and others are expected to increase their imports, but world prices have already started to decline, which will put pressure on U.S. prices.

“But still, I feel milk prices will end up higher than current futures market prices, particularly for the last half of the year, from a little lower increase in milk production and prices supported by domestic sales and exports,” Cropp concludes.


Source: Wallaces Farmer

Too much to digest at dairy markets

Dairy traders had a lot to digest last week and it wasn’t just turkey. The menu also included the October Milk Production, Cold Storage and Slaughter reports, plus the Global Dairy Trade auction.

They closed the Thanksgiving-holiday shortened week with CME block Cheddar at $1.61 per pound, down a penny on the week and 25 cents below a year ago.

The barrels finished at $1.6750, up 4 3/4-cents, 1 1/2-cents below a year ago, and an inverted 6 1/2-cents above the blocks.

The blocks fell 6 cents Monday only to get it back Tuesday, returning to $1.61.

The barrels rolled 8 1/2-cents lower Monday and lost a nickel Tuesday, plunging to $1.54, the lowest price since Sept. 21, with 13 cars selling Monday and 14 more on Tuesday.

Cheesemakers in the Midwest were receiving spot milk offers early last week and expected them to continue through Wednesday, according to Dairy Market News, and spot milk prices range from flat market to $5 under class. Cheese inventories vary but are generally “fairly long.” Cheese orders have been steady to slow, with some contacts suggesting that buyers are waiting for steadying market prices.

Western cheesemakers report steady production and plenty of milk available, says DMN. “Demand is stable, but not as robust as previous years. Interest from foreign buyers has picked up as prices have eased on market exchanges” and “exports may play a critical role in maintaining comfortable cheese stocks entering into 2018.”

Cash butter closed last Wednesday at $2.2225 per pound, up three-quarter cents on the week and 17 1/2-cents above a year ago, with 22 cars exchanging hands.

The October Cold Storage report butter data didn’t seem to matter Monday as the butter lost a penny and a half and melted down another 2 1/4-cents Tuesday, to $2.1850.

Central region butter makers reported active production schedules Thanksgiving Week, as cream was readily accessible and “finding its way into Midwestern butter plants from regions across the country,” according to DMN. “Butter sales remain strong late into the busy season, and the butter market tone is holding somewhat steady.”

Western processors also have enough cream for churning. Holiday demand is “solid and drawing down butter inventories,” but supplies remain plentiful. Retail stores have increased butter promotions. International market competition between the EU and the USA for market share is increasing, says DMN.

Cash Grade A nonfat dry milk dipped to 70 1/2-cents per pound Tuesday, lowest price since April 2016, but finished Wednesday at 71 1/4-cents, down 1 1/4-cents on the week and 19 1/4-cents below a year ago. Only two cars sold on the week.

Monday took the powder up three-quarters and added a penny Tuesday, creeping back to 73 cents per pound.

Class I up

The Agriculture Department announced the final Class I base milk price of 2017 at $16.88 per hundredweight, up 47 cents from November and even with December 2016.

It is the highest Class I since March 2017 and equates to $1.45 per gallon. The year’s average is $16.45, up from $14.80 in 2016 and $16.34 in 2015.

Cold storage

Americans continue to chow down butter and cheese supplies. The USDA’s latest Cold Storage report put Nov. 30 butter stocks at 219.75 million pounds, down 36 million or 14 percent from September and 8.4 million pounds or 4 percent below 2016. The September estimate was revised 1.1 million pounds lower.

American type cheese, at 739.3 million pounds, was down 41.2 million pounds or 5.0 percent from September and only 3.3 million pounds above, virtually unchanged, from a year ago. The “other” cheese category showed stocks of 504.2 million pounds, up 2 million pounds from September and 42.3 million or 9 percent above a year ago.

The total cheese inventory stood at 1.27 billion pounds, down 40.2 million pounds or 3 percent from September but 45.5 million or 4.0 percent above a year ago. Revisions added 2.7 million pounds of American cheese to September’s total, 1.8 million pounds to the other cheese total, and 2.5 million pounds to the total cheese estimate. Pundits viewed the report as bullish on cheese and neutral on butter.

Culling jumps

Rising milk output and falling prices are pushing more dairy cows into retirement. U.S. dairy cow culling reversed gears in October and was up from September and October 2016. The Agriculture Department’s latest Livestock Slaughter report shows an estimated 261,000 head were slaughtered under federal inspection, up 11,400 head from September and 23,800 head above a year ago.

Culling in the first 10 months of 2017 totaled 2.497 million head, up 108,000 from the same period a year ago.


Source: Capital Press

Milk and butter prices up, cheese steady

On Thursday at the Chicago Mercantile Exchange, milk and butter prices closed up again, and cheese held steady. Class III milk futures for December were up $.12 to $15.37. January milk went up $.21 closing at $14.68.  February was up $.19 at $14.71.  March was up $.17 to $14.74.  Thursday was the third straight day where milk prices for later in 2018 were either up or unchanged. Grade AA Butter closed up $.0075 at $2.2125.  Six carloads of butter were sold with one topping at $2.2125. Barrels were unchanged at $1.51.  

Milk and butter prices closed up, Class III milk futures for December were unchanged

In trading on Wednesday at the Chicago Mercantile Exchange, Milk and butter prices closed up but cheese fell. Class III milk futures for December were unchanged at $15.25. January milk went up $.08 closing at $14.47.  February was up $.08 at $14.52.  March was up $.05 to $14.57.  For the second day in a row, prices for later in 2018 were either up or unchanged Wednesday. Grade AA Butter closed up $.02 at $2.205.  Six carloads of butter were sold with one topping at $2.205. On the cheese market, barrels were down $.03 at $1.51.  Nine carloads of barrels were sold ranging from $1.51 to $1.5275. Forty-pound blocks were down $.01 at $1.60.  Seven carloads of blocks were sold ranging from $1.5975 to $1.6075.

Dairy Outlook: November 2017

Markets continue to move sideways with little prospect for forecast price improvement. None of the factors that are well known give much optimism for price improvement

Market Commentary

Markets continue to move sideways with little prospect for forecast price improvement. None of the factors that are well known– cow numbers, expected domestic and global milk production, high dairy product inventories and current trade patterns, give much optimism for price improvement. However, a number of very tense areas of the world could cause a future disruption in a way that would change price forecasts.

If price forecasts for 2018 are realized, the majority of Pennsylvania dairy producers will need to have a cost of production below $17.50/cwt in order to cash flow for the year. This fact poses a significant challenge to a number of our state’s dairies, especially as some have delayed equipment reinvestment and repairs hoping for better years.

Components the Only Game in Town

Dairy producers continue to focus on shipping more components as the main way to improve income. The Northeast Market Administrator’s Bulletin for September contained some interesting statistics on butterfat and protein tests on milk shipped in Order 1. Over the last 17 years, butterfat tests have increased an average of 0.14% and protein tests have increased an average of 0.11. However, those average increases do not reflect the increases observed on many well managed dairy farms in the state. During many dairy advisory team meetings, the conversation focuses on the forage quality and management needed to achieve the goal of an average of 6 lbs of components produced daily from each cow in the herd.

The Cyber Economy’s Indirect Impact on PA Dairy

While there are dairy producers in most of Pennsylvania’s counties, the majority of dairy farms are located in the southcentral / southeast portion of our state. A recent study of Pennsylvania’s dairy industry, commissioned by the Center for Dairy Excellence, indicated that the industry is continuing to grow and concentrate in the areas where it is already located. This same area of PA has a tremendous transportation network, which the dairy industry has always seen as a benefit in moving milk to market.

However, over the past 10 years, this extensive transportation network has also attracted a large number of warehouses, or “logistics centers” to the area. Proponents of logistics centers forecast that there is no end to the amount of these structures needed, as an increasing share of consumers purchase an increasing amount of product on-line. These logistic centers are located along this transportation grid in Southeast Pennsylvania for the same reason that our extensive food processing industry in located there—because half of the population of the United States can be reached within a 12 hour drive.

Some in our state’s dairy industry would say the biggest impact of these logistics centers to dairy is the amount of farmland that has been taken out of production to build these centers. However, these logistic centers are affecting the dairy industry in a much less obvious way. Anecdotal information indicates that average laborers may earn a wage of $14.50/hour. As a result, dairy farms within a reasonable commute of any of these centers find that they are faced with a minimum wage floor, not set by state government, but by local competition for laborers. If dairies are not willing to match the wage rate offered by the logistics center, it becomes increasingly difficult to recruit and retain employees.

Yet, many Pennsylvania dairies have a cost structure that is too high to compete successfully with dairies in other parts of our nation, mainly due to feed costs. Higher labor costs are not helpful to the need for competitive cost of production on our state’s dairy farms.

Table 1: 12 month Pennsylvania & U.S. All Milk Income, Feed Cost, Income over Feed Cost ($/milk cow/day)

¹ Based on corn, alfalfa hay, and soybean meal equivalents to produce 75 lbs. of milk (Bailey & Ishler, 2007)

² The 3 year average actual IOFC breakeven in Pennsylvania from 2014-2016 was $8.97 ± $1.76 ($/milk cow/day) (Beck, Ishler, Goodling, 2017).

Table 2: 12 month Pennsylvania & U.S. All Milk Price, Feed Cost, Milk Margin ($/cwt for lactating cows)

¹ Based on corn, alfalfa hay, and soybean meal equivalents to produce 75 lbs. of milk (Bailey & Ishler, 2007)

² The 3 year average actual Milk Margin breakeven in Pennsylvania from 2014-2016 was $12.41 ± $2.38 ($/cwt) (Beck, Ishler, Goodling, 2017).

Figure 1: 12 month PA Milk Income and Income over Feed Cost

² The 3 year average actual IOFC breakeven in Pennsylvania from 2014-2016 was $8.97 ± $1.76 ($/milk cow/day) (Beck, Ishler, Goodling, 2017).

Figure 2: 24 month Actual and Predicted* Class III, Class IV, and Pennsylvania Average Mailbox Price ($/cwt)

* Predicted values based on Class III and Class IV futures regression (Gould, 2017).

Table 3: 24 month Actual and Predicted* Class III, Class IV, and Pennsylvania Average Mailbox Price ($/cwt)

Month Class III Price Class IV Price Average PA Mailbox Price
Sep-16 $16.39 $14.25 $16.95
Oct-16 $14.82 $13.66 $16.48
Nov-16 $16.76 $13.76 $17.04
Dec-16 $17.40 $14.97 $18.53
Jan-17 $16.77 $16.19 $18.86
Feb-17 $16.88 $15.59 $18.24
Mar-17 $15.81 $14.32 $17.91
Apr-17 $15.22 $14.01 $16.43
May-17 $15.57 $14.49 $16.32
Jun-17 $16.44 $15.89 $17.17
Jul-17 $15.45 $16.60 $17.40
Aug-17 $16.57 $16.61 $18.21
Sep-17 $16.36 $15.86 $17.74
Oct-17 $16.72 $14.89 $18.32
Nov-17 $16.58 $13.98 $17.81
Dec-17 $15.98 $14.04 $17.52
Jan-18 $15.65 $14.11 $17.34
Feb-18 $15.55 $14.27 $17.37
Mar-18 $15.40 $14.54 $17.41
Apr-18 $15.35 $14.69 $16.63
May-18 $15.50 $14.84 $16.79
Jun-18 $15.74 $15.01 $17.00
Jul-18 $16.01 $15.21 $17.25
Aug-18 $16.14 $15.40 $17.40

* Italicized predicted values based on Class III and Class IV futures regression (Gould, 2017).

To look at feed costs and estimated income over feed costs at varying production levels by zip code, check out the Penn State Extension Dairy Teams DairyCents or DairyCents Pro apps today.


Class III milk futures Up, January Milk Down – November 29th 2017 Daily Dairy Market Report

Mixed results from the dairy markets on Tuesday.  With the Chicago Mercantile Exchange seeing Class III milk futures for December going up $.04 to $15.25. But, January milk were down $.07 at $14.39, as well as February was down $.10 at $14.44, and March was down $.04 to $14.52. Prices for later in 2018 were either up or unchanged Tuesday. Grade AA Butter closed down $.0225 at $2.185. Five carloads of butter were sold with one topping at $2.19. Barrels were down $.05 at $1.54. Fourteen carloads of barrels were sold ranging from $1.585 down to $1.54. 40-pound blocks were up $.06 at $1.61. Two carloads of blocks were sold.

Dairy markets down Monday

After some pre-holiday gains, dairy prices fell Monday on the Chicago Mercantile Exchange.

Class III milk futures for December were down Monday $.21 to $15.21.

Read more: Brownfield Ag News

World dairy markets still volatile but expected to rebound

World dairy markets are not likely to ever change their volatile nature, but signs of recovery and growth are starting to appear.

That’s the message Veronique Pilet, head of economics at the French dairy inter-branch organization CNIEL, told those attending the World Dairy Summit in Belfast, Northern Ireland.

“Historical lows are giving way to a period of recovery,” said Pilet. “And we are now seeing a stronger demand for dairy in 2017.

“The global dairy market remains uncertain and the only thing that we can say for sure is the volatility, which is a result of supply and demand issues, is here to stay.

“Dynamism in the European and U.S. markets is leading recovery, and production prospects over the next few months remain good. Butter prices are at an all-time high. However skimmed milk powder prices are still eroding.”

Pilet said recovery this year followed a year when both global production of dairy and consumption were stagnant and in some areas showed a slight decrease.

She said contributing factors to current market conditions could be the Russian ban on importing dairy products from the European Union, decreased buying power in oil-producing countries and the poor economic situation in South America.

New Zealand remains the world’s largest exporter of dairy with a 29 percent share of the market, closely followed by the EU at 28 percent and the U.S. at 24 percent.

Overall production of milk rose by 0.9 percent in 2016 compared with growth rates of two percent and more in recent years.


Source: The Western Producer

Pressure building on Fonterra’s milk price

Pressure is building on Fonterra’s farmgate milk price as increased production led to the fourth drop in a row at the latest Global Dairy Trade auction.

Fonterra’s forecast, which under law has to be reviewed every three months, stands at $6.75/kg of milksolids.

Most banks have lowered their forecasts to around $6.25 to $6.50/kg.

A milk price around that level would not spell doom for dairy farmers, as it would still be comfortably above DairyNZ’s most recent estimate of break-even of $5.20 to $5.25/kg.

ASB rural economist Nathan Penny said most farmers would be making money at above $6.00/kg, and a 6.50/kg milk price would still be high historically.

Penny said a more moderate milk price would add some balance to the market — particularly as high prices tend to encourage farmers to increase production.

At today’s auction, the GDT price index fell by 3.4 per cent and the average winning price came to US$2970 a tonne.

The weakness was broad-based, with the largest falls in casein, down 12.6 per cent, skim milk powder, down 6.5 per cent and butter, down 5.9 per cent.

Whole milk powder prices — which have the greatest bearing on Fonterra’s farmgate milk price — fell 2.7 per cent to US$2778 a tonne, and the declines were across most of the contract periods through to April next year.

Since August 2, whole milk powder prices have fallen by 12 per cent.

“It is clear the market is nervous about rising global supply,” said ANZ senior economist Phil Borkin.

“European supply is increasing on the back of higher farmgate prices and favourable seasonal conditions, and local supply is improving too.”

Borkin said whole milk powder prices should now find support at around current levels.
“Ultimately, it sets the scene for Fonterra to downgrade its milk price forecast for 2017/18 early next month to close to our current forecast of $6.25-$6.50/kg.”

Analysts said worries about increased production — both in New Zealand and in Europe — have started to weigh on prices.

Dairy Companies Association of NZ data out last week showed local dairy production kicked up by 2.9 per cent in October — the peak of the season.

Fonterra’s season peaked on October 26 at 82 million litres, up 1 per cent on the previous season’s peak of 80 million litres.

In October Fonterra lowered its forecast annual collection from 1.575 billion kg of milksolids to 1.54 billion kgs, which would be a 1 per cent increase on the previous season.

Rabobank dairy analyst Michael Harvey said the general sentiment in global markets remains bearish.

“With farmgate milk prices across the export region above breakeven, milk production is gaining momentum,” he said.

European data this week showed EU milk deliveries were up 3.7 per cent in September — the strongest growth in 18 months.

ASB’s Penny said New Zealand production had rebounded sooner than the bank had expected.

“With NZ production much-improved and EU production already firm, we factor in this better global production outlook into our milk price forecast.

“All up and along with the weak run of recent auction results, we trim our 2017/18 milk price forecast by 25 cents to $6.50/kg,” he said.

The co-operative’s current $6.75/kg forecast for this season compares with $6.12/kg of milksolids in the 2016/17 season.

Farmgate milk prices slumped to $3.90/kg and $4.40/kg respectively in the two preceding seasons, requiring Fonterra to offer soft loans to help farmers through the downturn.


Source: NZ Herald

Analysts expect Fonterra to lower its forecast payout before Christmas

Santa may not bring what dairy farmers want this festive season, with most analysts expecting a drop in the Fonterra farmgate forecast payout before Christmas.

Under the terms of the Dairy Industry Restructuring Act, Fonterra is legally obliged to provide an update on the forecast payout in December.

Federated Farmers, though, remain optimistic the dairy giant will maintain its current forecast price of $6.75 per kilogram of milksolids, set in July.

Dairy group chairman Chris Lewis said the milk market was competitive in the heavy producing regions of Waikato, Manawatu, Canterbury and Southland and other processors were paying good prices.

For example, in a letter to shareholders this week Westland Milk Products have pledged to hold its earlier range of $6.40 to $6.80 for this season.

He also pointed out the New Zealand dollar had depreciated from 74c against the US last year to 68c now, which would help support prices.

But analysts say the latest global dairy auction results and other market signals are pointing towards a revised figure around the $6.50 mark.

If that was the case it would mean a reduction of almost $500 million for the economy. For the average farmer, it would mean a $39,000 drop in income, based on a 419 average herd size that milks 373kgMS per cow.

AgriHQ’s Amy Castleton said the outlook was generally weaker. She agreed a lower dollar helped, and while Fonterra hedged much of its foreign exchange requirements, there was still a portion of its sales that was subject to exchange rate movements.

OM Financial said if prices remain unchanged to the end of the season in May, it estimated a payout of $6.62, but by incorporating NZX dairy futures, it projected a weaker milk price of $6.50

ASB rural economist Nathan Penny trimmed his forecast to $6.50, pointing out prices had now fallen for four consecutive auctions.

Over this period, overall and whole milk powder prices have dipped by around 10 per cent, while butter prices have eased nearly 15 per cent. Anhydrous milk fat has been the lone holdout, rising around 2 per cent over the same period.

New Zealand production for October lifted 2.9 per cent compared to October 2016, after August and September had been behind 2016 levels.

“New Zealand production has rebounded sooner than we expected from the very wet weather – we had expected the rebound to come over the summer and autumn. It seems that New Zealand weather and thus production can turn on a dime,” he wrote in the ASB’s latest Rural Economic Note.

Rabobank analyst Michael Harvey would not be drawn on a number, except to say there was a likelihood of a downward revision to Fonterra’s forecast payout.

Westpac economist Shyamal Maharaj supported a revision.

“It’s almost impractical for Fonterra to keep their forecast at $6.75 considering the recent GDT data as well as other market indicators.”

“The main thing we’re looking at it is the outlook for the Chinese economy next year, we’ve forecast whole milk powder prices will reflect a softening of Chinese demand,” Maharaj said.

After the GDT  two weeks ago, the ANZ lowered its milk price forecast to a range of $6.25-6.50.

Meanwhile in Europe the European Commission has started to sell skim milk powder below its purchase price, in an attempt to clear its two-year stockpile before the product begins to spoil.

The intervention purchase price is set at €1693 per tonne and a recent sale of 44 tonnes was at about €1450/tonne, indicating a change in attitude by the Commission. 


Source: Stuff

Dairy Outlook: Sideways Milk Market

Markets continue to move sideways with little prospect for forecast price improvement. None of the factors that are well known give much optimism for price improvement

Markets continue to move sideways with little prospect for forecast price improvement. None of the factors that are well known– cow numbers, expected domestic and global milk production, high dairy product inventories and current trade patterns, give much optimism for price improvement. However, a number of very tense areas of the world could cause a future disruption in a way that would change price forecasts.

If price forecasts for 2018 are realized, the majority of Pennsylvania dairy producers will need to have a cost of production below $17.50/cwt in order to cash flow for the year. This fact poses a significant challenge to a number of our state’s dairies, especially as some have delayed equipment reinvestment and repairs hoping for better years.

Components the Only Game in Town

Dairy producers continue to focus on shipping more components as the main way to improve income. The Northeast Market Administrator’s Bulletin for September contained some interesting statistics on butterfat and protein tests on milk shipped in Order 1. Over the last 17 years, butterfat tests have increased an average of 0.14% and protein tests have increased an average of 0.11. However, those average increases do not reflect the increases observed on many well managed dairy farms in the state. During many dairy advisory team meetings, the conversation focuses on the forage quality and management needed to achieve the goal of an average of 6 lbs of components produced daily from each cow in the herd.

The Cyber Economy’s Indirect Impact on PA Dairy

While there are dairy producers in most of Pennsylvania’s counties, the majority of dairy farms are located in the southcentral / southeast portion of our state. A recent study of Pennsylvania’s dairy industry, commissioned by the Center for Dairy Excellence, indicated that the industry is continuing to grow and concentrate in the areas where it is already located. This same area of PA has a tremendous transportation network, which the dairy industry has always seen as a benefit in moving milk to market.

However, over the past 10 years, this extensive transportation network has also attracted a large number of warehouses, or “logistics centers” to the area. Proponents of logistics centers forecast that there is no end to the amount of these structures needed, as an increasing share of consumers purchase an increasing amount of product on-line. These logistic centers are located along this transportation grid in Southeast Pennsylvania for the same reason that our extensive food processing industry in located there—because half of the population of the United States can be reached within a 12 hour drive.

Some in our state’s dairy industry would say the biggest impact of these logistics centers to dairy is the amount of farmland that has been taken out of production to build these centers. However, these logistic centers are affecting the dairy industry in a much less obvious way. Anecdotal information indicates that average laborers may earn a wage of $14.50/hour. As a result, dairy farms within a reasonable commute of any of these centers find that they are faced with a minimum wage floor, not set by state government, but by local competition for laborers. If dairies are not willing to match the wage rate offered by the logistics center, it becomes increasingly difficult to recruit and retain employees.

Yet, many Pennsylvania dairies have a cost structure that is too high to compete successfully with dairies in other parts of our nation, mainly due to feed costs. Higher labor costs are not helpful to the need for competitive cost of production on our state’s dairy farms.

Table 1: 12 month Pennsylvania & U.S. All Milk Income, Feed Cost, Income over Feed Cost ($/milk cow/day)

¹ Based on corn, alfalfa hay, and soybean meal equivalents to produce 75 lbs. of milk (Bailey & Ishler, 2007)

² The 3 year average actual IOFC breakeven in Pennsylvania from 2014-2016 was $8.97 ± $1.76 ($/milk cow/day) (Beck, Ishler, Goodling, 2017).

Table 2: 12 month Pennsylvania & U.S. All Milk Price, Feed Cost, Milk Margin ($/cwt for lactating cows)

¹ Based on corn, alfalfa hay, and soybean meal equivalents to produce 75 lbs. of milk (Bailey & Ishler, 2007)

² The 3 year average actual Milk Margin breakeven in Pennsylvania from 2014-2016 was $12.41 ± $2.38 ($/cwt) (Beck, Ishler, Goodling, 2017).

Figure 1: 12 month PA Milk Income and Income over Feed Cost

² The 3 year average actual IOFC breakeven in Pennsylvania from 2014-2016 was $8.97 ± $1.76 ($/milk cow/day) (Beck, Ishler, Goodling, 2017).

Figure 2: 24 month Actual and Predicted* Class III, Class IV, and Pennsylvania Average Mailbox Price ($/cwt)

* Predicted values based on Class III and Class IV futures regression (Gould, 2017).

Table 3: 24 month Actual and Predicted* Class III, Class IV, and Pennsylvania Average Mailbox Price ($/cwt)

Month Class III Price Class IV Price Average PA Mailbox Price
Sep-16 $16.39 $14.25 $16.95
Oct-16 $14.82 $13.66 $16.48
Nov-16 $16.76 $13.76 $17.04
Dec-16 $17.40 $14.97 $18.53
Jan-17 $16.77 $16.19 $18.86
Feb-17 $16.88 $15.59 $18.24
Mar-17 $15.81 $14.32 $17.91
Apr-17 $15.22 $14.01 $16.43
May-17 $15.57 $14.49 $16.32
Jun-17 $16.44 $15.89 $17.17
Jul-17 $15.45 $16.60 $17.40
Aug-17 $16.57 $16.61 $18.21
Sep-17 $16.36 $15.86 $17.74
Oct-17 $16.72 $14.89 $18.32
Nov-17 $16.58 $13.98 $17.81
Dec-17 $15.98 $14.04 $17.52
Jan-18 $15.65 $14.11 $17.34
Feb-18 $15.55 $14.27 $17.37
Mar-18 $15.40 $14.54 $17.41
Apr-18 $15.35 $14.69 $16.63
May-18 $15.50 $14.84 $16.79
Jun-18 $15.74 $15.01 $17.00
Jul-18 $16.01 $15.21 $17.25
Aug-18 $16.14 $15.40 $17.40

* Italicized predicted values based on Class III and Class IV futures regression (Gould, 2017).

Source: Penn State Extension

Dairy markets mostly up before Thanksgiving break

With one exception, the dairy markets gained ground before the Thanksgiving break.

The last day of dairy trading this week at the Chicago Mercantile Exchange saw the Class III milk futures for November down $.02 to $16.80. Everything else closed up.

Read more: Brownfield Ag News

Global Dairy Prices Fall to Eight-month Low as Supply Ramps Up

Global dairy prices fell for the fourth auction in a row and hit an eight-month low on Wednesday, which could hit farmgate milk prices.

The GDT Price Index dipped 3.4 percent, with an average selling price of $2,970 per ton, in the fortnightly auction held in the early hours of the morning.

Prices had risen in the second quarter on strong global demand and as production eased, but have since had a bumpy ride as supply has picked up.

“Buyers are unlikely to feel much urgency to buy product right now with the prospect of more milk being available from NZ,” said Amy Castleton, Feilding-based analyst at AgriHQ.

New Zealand dairy giant Fonterra , had said on Tuesday that its domestic milk output rose 3 percent in October from the year before as wet weather subsided towards the end of the month.

Prices for whole milk powder, the most widely traded product, dropped 2.7 percent in the auction, in contrast with derivative market expectations of a rise. Skim milk powder fell 6.5 percent.

The sustained drop in prices could lead to Fonterra slashing its milk payout to farmers by the end of the year, according to analysts.

The world’s largest dairy exporter currently pays NZ$6.75 per kilogram of milk solids to New Zealand farmers.

“With the weak run of auction results and an improved production outlook, we revise down our milk price forecast,” said Nathan Penny, rural economist at ASB Bank, predicting a payout of NZ$6.50.

The auction results can affect the New Zealand dollar as the dairy sector generates more than 7 percent of the nation’s gross domestic product.

However, investors were unfazed by the result as the Kiwi rallied alongside its Australian counterpart on comments by the Australian central bank governor on Thursday.

A total of 35,042 tons was sold at the auction, falling 0.1 percent from the previous one, the auction platform said on its website.

GDT Events is owned by New Zealand’s Fonterra Co-operative Group Ltd , but operates independently from the dairy giant.

U.S.-listed CRA International Inc is the trading manager for the Global Dairy Trade auction.

The auctions are held twice a month, with the next one scheduled for Dec. 5.

Source: Reuters

Australia and New Zealand dairy producers shrug off lower auction prices

Shares in dairy producers listed in Australia and New Zealand rose on Wednesday despite global the price of milk products dipping to an eight-month low overnight.

Shrugging off the fall in prices, A2 Milk was the best performer on S&P/ASX 200 in Sydney in early trade, lifting 5 per cent, while on the NZX, Synlait Milk added 2.2 per cent and on Fonterra, was up 0.2 per cent.

The moves came after the Global Dairy Trade index – the industry benchmark reflecting the latest fortnightly auction prices – fell 3.4 per cent on Tuesday, including a 2.7 per cent drop in the price of whole milk powder. That marked the fourth straight decline for the index and the lowest price since March.

Fonterra, the world’s biggest dairy producer, said on Tuesday that total milk production in New Zealand in October – the typical supply peak – was up 3 per cent compared to the year prior.

The share price lift continues a banner year for dairy producers. A2 Milk, which on Tuesday reported a 68.9 per cent jump in unaudited revenue for the fourth months to October, is now up 306 per cent so far this year. Synlait is 143.7 per cent higher and Fonterra is up 5.5 per cent.

Source: Financial Times

Milk futures down, butter and cheese up Tuesday

Near-term dairy markets were down Tuesday on the Chicago Mercantile Exchange.

The Class III milk futures for November were down $.01 to $16.82. December was down $.03 at $15.37. January was down $.04 at $14.60. February was down $.03 to $14.56 There were some minor increases for the April, May, and June futures.

Read more: Brownfield Ag News

Dairy markets mixed Monday

Dairy markets began the holiday-shortened week with mixed trade on the Chicago Mercantile Exchange.

The Class III milk futures regained a few cents Monday, with November up $.04 to $16.83. December was up $.13 at $15.40. January was up $.10 at $14.64. February was up $.11 to $14.59

Read more: Brownfield Ag News

Dairy markets closed mixed Wednesday

Dairy markets were mixed on the Chicago Mercantile Exchange Wednesday.

The Class III milk futures for November were up $.02 to $16.84. December was down $.03 at $15.73. January was down $.07 to $14.96. February was down $.05 to $14.96

Read more: Brownfield Ag News

Dairy prices mostly up Tuesday

Class III milk rose again on the Chicago Mercantile Exchange Tuesday.

The Class III milk futures for November were up $.02 to $16.82. December was up $.07 at $15.76. January was up $.07 to $15.03. February was up $.08 to $15.01

Read more: Brownfield Ag News

Dairy markets mixed Monday

Butter and cheese prices were mixed while Class III milk prices rose on the Chicago Mercantile Exchange Monday.

The Class III milk futures for November were up $.03 to $16.80. December was up $.10 at $15.69. January was up $.09 to $14.96. February was up $.06 to $14.93

Read more: Brownfield Ag News

Dairy prices continue to be mixed

CME block Cheddar climbed to $1.76 per pound on Halloween but closed Friday at $1.7150 per pound, as traders absorbed the mostly bearish September Dairy Products report, down 3 cents on the week, 18 1/2-cents below a year ago, and compares to $1.7275 on the first trading day of October.

The barrels also finished at $1.7150, up a penny on the week, 14 1/2-cents below a year ago, but 2 1/2-cents above their Oct. 2 perch.

The blocks dropped 2 1/4-cents Monday and plunged 6 cents Tuesday, to $1.6325, as traders studied the GDT.

The barrels were unchanged Monday but rolled a penny and a half lower Tuesday, to $1.70, 6 3/4-cents atop the blocks.

Dairy Market News reports that cheese demand has ebbed slightly for some Midwest cheesemakers. Western cheese production is steady, supplies are substantial, but not causing major concern. International sales are good and manufacturers hope that will help reduce inventories.

Cash butter fell to $2.2225 last Thursday but closed Friday at $2.2325, down 7 cents on the week and 34 cents above a year ago.

The butter slipped three-quarters Monday and lost a penny and a half Tuesday, slipping to $2.21, lowest price since May 10, 2017.

Cream continues to be available for Central butter producers and is finding its way to upper Midwestern churns from across the nation. Contacts suggest weakening European butter markets are bringing U.S. prices down.

Cash Grade A nonfat dry milk closed Friday at 72 cents per pound, down 3 cents on the week and 12 3/4-cents below a year ago.

The powder inched up three-quarters Monday but fell a penny and a half Tuesday, to 71 1/4-cents per pound, lowest spot price since April 12, 2016.

GDT drops 3.5 percent

Tuesday’s Global Dairy Trade auction saw its weighted average for products offered drop 3.5 percent, following a 1.0 percent decline Oct. 17 and a 2.4 percent descent Oct. 3.

Whole milk powder led the declines, down 5.5 percent, following a 0.5 percent loss Oct. 17. Butter was down 3.6 percent following a 2.5 percent dip in the last event. Cheddar was off 2.8 percent, after inching 0.1 percent lower last time.

Skim milk powder was up 1.2 percent, after plunging 5.6 percent, and anhydrous milkfat was up 0.5 percent, after it jumped 5.2 percent last time.

FC Stone equated the GDT 80 percent butterfat butter price to $2.4412 per pound U.S. CME butter closed Tuesday at $2.21. GDT Cheddar cheese equated to $1.8146 per pound U.S. and compares to Tuesday’s CME block Cheddar at $1.6325. GDT skim milk powder averaged 82.48 cents per pound and whole milk powder averaged $1.2937. CME Grade A nonfat dry milk price closed Tuesday at 71 1/4-cents per pound.

Benchmark up 33 cents

The nation’s October benchmark Class III milk price climbed to $16.69 per hundredweight, up 33 cents from September and $1.87 above October 2016. It is the highest Class III since February 2017 and equates to $1.44 per gallon, up from $1.27 a year ago. The 10 month Class III average is at $16.19, up from $14.42 a year ago and compares to $15.98 in 2015.

The November Class III futures contract was trading late Tuesday morning at $16.45 and December was at $15.45, with nothing above $16 until September 2018.

The October Class IV price is $14.85, down $1.01 from September but $1.19 above a year ago, and the lowest Class IV since May 2017. Its average stands at $15.44, up from $13.65 a year ago and $13.97 in 2015.

California benchmark up

California’s October Class 4b cheese-milk price is $16.17 per cwt., up $1.29 from September, $1.74 above a year ago and 52 cents below the comparable FO Class III price. Its 10-month average stands at $15.33, up from $13.72 a year ago and $14.63 in 2015.

The Class 4a butter-powder price is $14.51, down 18 cents from September, $1.40 above a year ago, but the lowest 4a price since May 2017. The 4a average now stands at $15.24, up from $13.25 in 2016 and $13.81 in 2015.

Dairy products report

USDA’s latest Dairy Products report was more bearish than expected and showed total cheese output at 1.01 billion pounds, down 1.4 percent from August but 2.7 percent above September 2016. Year to date output stands at 9.25 billion pounds, up 2.6 percent from a year ago.

Mozzarella, at 334 million pounds, was up 0.2 percent, with YTD at 3.1 billion pounds, up 0.9 percent.

Total American cheese fell to 393.8 million pounds, down 1.3 percent from August but 4.2 percent above a year ago. YTD, at 3.7 billion was up 3.4 percent.

Cheddar, the kind traded at the CME, totaled 282.8 million pounds, down 0.4 percent from August, but 4.5 percent above a year ago, with YTD at 2.7 billion pounds, up 4.6 percent.

U.S. churns produced 134.8 million pounds of butter, up 2.8 percent from August but 0.3 percent below a year ago. YTD totaled 1.38 billion pounds, up 0.7 percent

Dry whey totaled 91.3 million pounds, up 20.8 percent, with YTD hitting 788.6 million pounds, up 9.6 percent. Stocks were up and HighGround Dairy’s Eric Meyer called it “the most bearish statistic of all,” as dry whey inventories stand at a record 105 million pounds, up 107.5 percent (more than double) last year.

Nonfat dry milk output totaled 133.4 million pounds, down 1.5 percent from August but 6.2 percent above a year ago, with YTD at 1.38 billion pounds, up 3.4 percent.

Skim milk powder totaled 30.4 million pounds, down 33.6 percent from August and 21 percent below a year ago. YTD output is at 417.2 million, up 0.4 percent.

September nonfat dry milk stocks hit 321.1 million pounds, up 8.2 million pounds or 2.6 percent from August and 10.5 million pounds or 48.6 percent above a year ago.


Source: Capital Press

Dairy markets continue downward trend Tuesday

Dairy prices continued their downward trend on the Chicago Mercantile Exchange Tuesday.

The Class III milk futures for November were down $.09 to $16.47. December was down $.20 at $15.42. January was down $.17 to $15.04. February closed down $.21 to $15.02.

Read more: Brownfield Ag News

Send this to a friend